
 Display Driver Market | 2026-2036
Display Driver Market Size, Share, and Industry Trends Forecast 2026-2036
Display Driver Market Analysis
Copper interconnect metallization is restructuring cost structures across advanced node display driver ICs. Samsung Electronics Co., Ltd. leverages captive foundry capacity to secure wafer supply for high-resolution smartphone panels. MediaTek Inc. anchors its position through co-development programs with leading OLED panel manufacturers in Taiwan and South Korea. Himax Technologies, Inc. specializes in automotive-grade driver solutions that meet extended temperature reliability requirements.
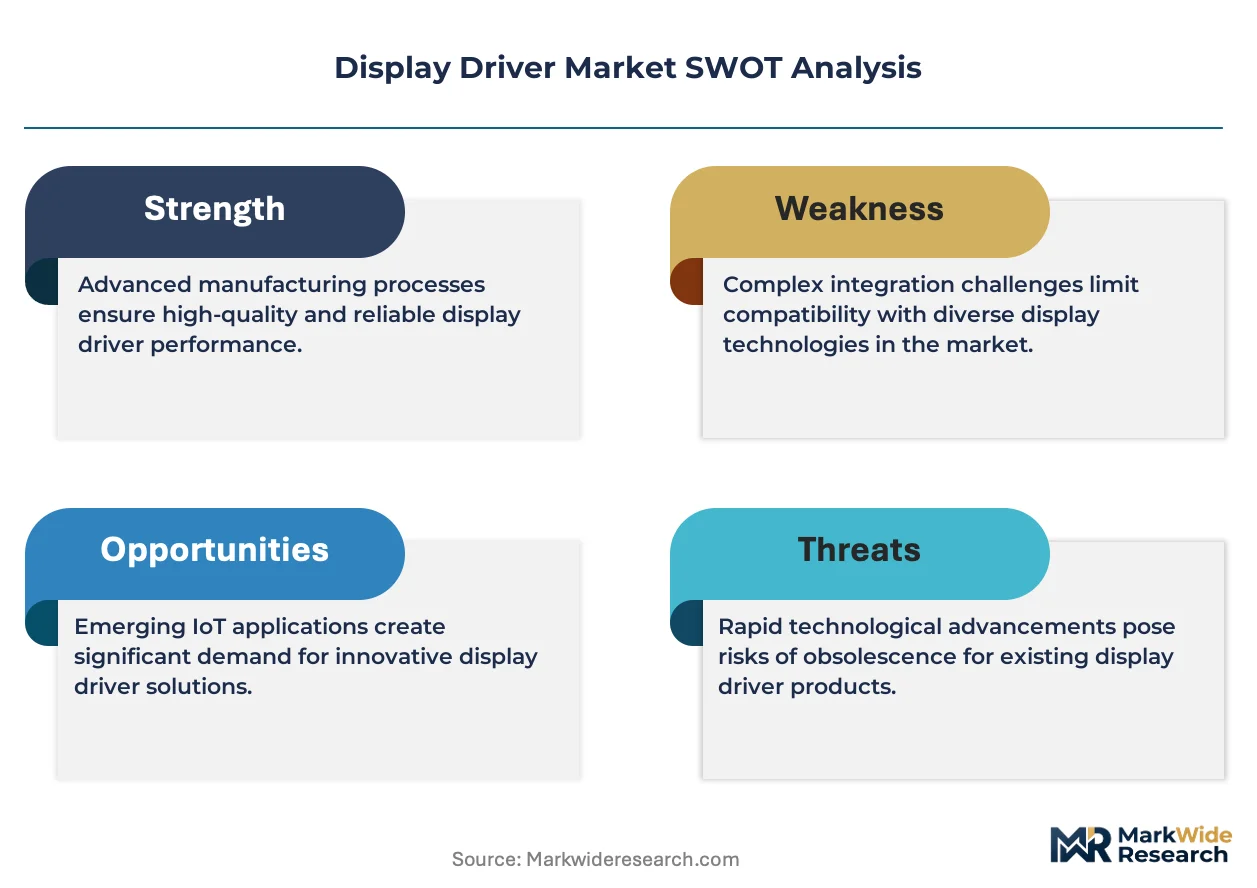
A display driver IC is a semiconductor device that converts digital video signals into analog voltages to control pixel illumination across TFT-LCD, OLED, and micro-LED panels, typically fabricated at 28nm to 40nm process nodes with integrated gamma correction and timing controller functions. Its primary purpose is to deliver precise current modulation and uniform brightness distribution across millions of individual pixels in high-refresh-rate displays. OLED driver ICs command premium margin pools due to complex compensation algorithms for pixel degradation and variable refresh rate synchronization. Automotive display applications represent the fastest-expanding end-user category as cabin digitization accelerates demand for multi-panel driver consolidation.
REACH restrictions on hazardous substances in electronics manufacturing constrain material choices for display driver packaging and substrate compositions in European supply chains. South Korea's Ministry of Trade, Industry and Energy enforces domestic content requirements that shape procurement patterns for driver ICs bound for national display champions. China's SAMR implements national standard GB specifications that govern electromagnetic compatibility testing for display modules integrated into consumer devices. Stakeholders must monitor how divergent energy-efficiency certification schemes across major manufacturing jurisdictions fragment qualification timelines and inventory planning.
Market Dynamics
Copper interconnect migration at advanced nodes is compressing manufacturing cost structures while tightening foundry allocation windows for display driver ICs. This metallization shift, combined with China's GB energy-efficiency mandates, is forcing rapid qualification cycles across panel supply chains.
Growth Catalysts
- OLED penetration in automotive:Cabin digitization across premium vehicle platforms is expanding addressable silicon content per vehicle. Multi-panel consolidation requires higher-channel-count driver architectures.
- REACH substance restrictions:ECHA enforcement on hazardous materials in electronics packaging is accelerating substrate material transitions toward halogen-free alternatives.
- 28nm process maturation:Foundry yield improvements at this node are enabling cost-effective integration of timing controllers with source drivers.
Market Restraints
- Wafer supply concentration:Advanced node capacity concentrates among Taiwan and South Korea foundries, creating allocation vulnerability during demand spikes.
- Copper metal cost volatility:Interconnect material pricing fluctuations directly impact gross margins at 28nm and below.
- Pixel compensation algorithm complexity:OLED degradation modeling requires larger die area and embedded memory, constraining cost-down trajectories.
Strategic Opportunities
- Micro-LED driver architectures:Mass transfer yield improvements are opening modular driver IC designs for large-format commercial displays.
- India PLI scheme:Domestic display manufacturing incentives are creating captive demand for localized driver assembly and test capacity.
- Variable refresh rate standardization:Adaptive sync protocols across gaming and mobile segments are enabling premium SKU differentiation.
Industry Challenges
- Mixed-signal design talent scarcity:Analog pixel circuit expertise concentrates among senior engineers at legacy IDMs, constraining new entrant scaling.
- Multi-jurisdiction qualification overlap:Divergent electromagnetic compatibility testing between China's SAMR and South Korea's RRA extends time-to-revenue for new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Driver Market |
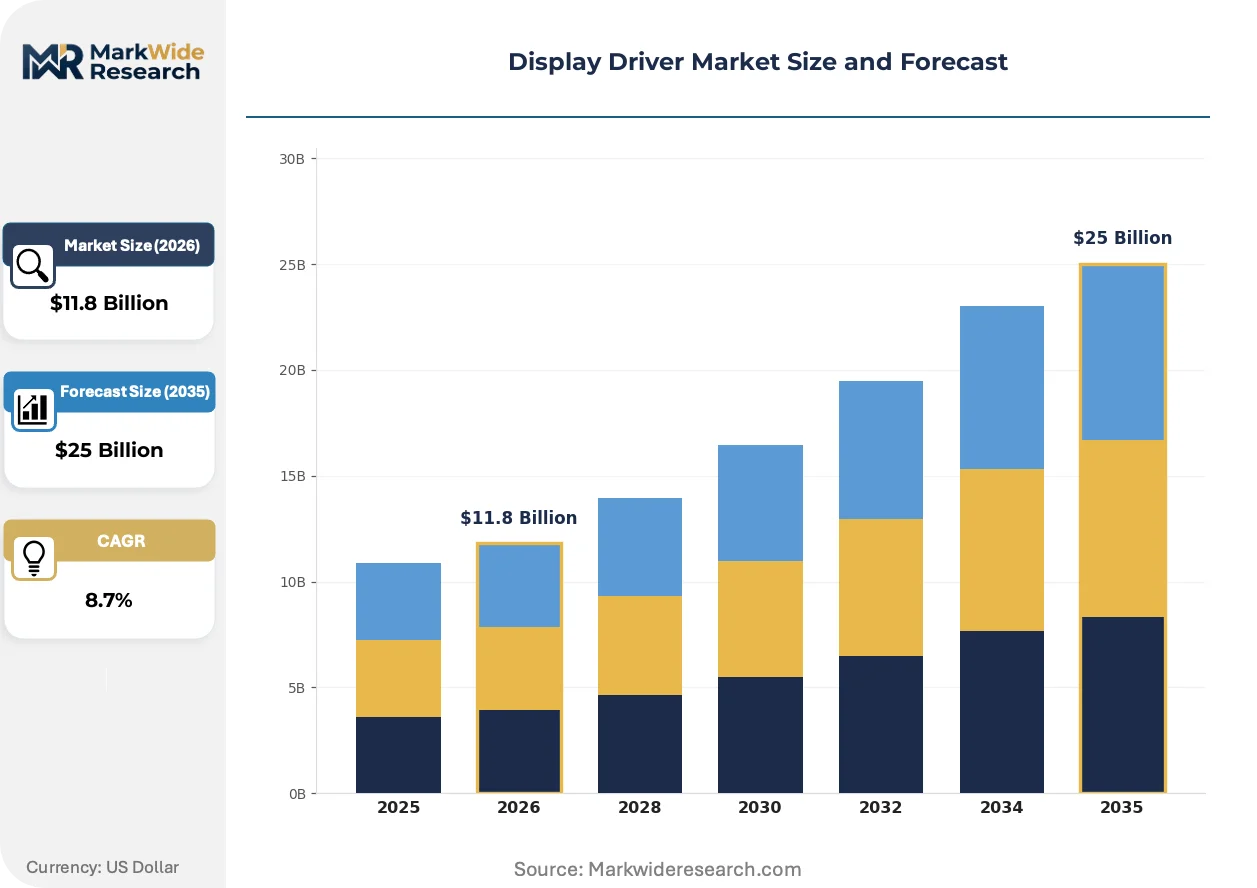
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Driver, OLED Driver, TFT Driver, LCD Driver Application: Smartphones, Tablets, Laptops, Televisions Technology: Analog, Digital, Hybrid, VESA End User: Consumer Electronics, Automotive Displays, Industrial Equipment, Medical Devices |
| Companies Covered | Himax Technologies, Inc., Raydium Semiconductor Corporation, Samsung Electronics Co., Ltd., MediaTek Inc., Sitronix Technology Corporation, Novatek Microelectronics Corp., Silicon Works Co., Ltd., LX Semicon Co., Ltd., Synaptics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Driver Market Emerging Trajectories
System-in-package integration is collapsing board-level component counts while elevating thermal management requirements. These packaging advances are compressing form factors and shifting competitive advantage toward assembly-test capabilities.
Copper pillar bumping with fine-pitch redistribution layers is consolidating interconnection density for high-pin-count source drivers. Smartphone panel manufacturers in South Korea and China are adopting this technology at volume production scale. The shift is consolidating supplier tiers as only captive or merchant OSATs with plating expertise qualify for flagship programs.
China's GB 4943.1 electromagnetic compatibility standards are mandating stricter emission controls for display modules in consumer devices. Domestic panel makers must redesign driver PCB layouts and shielding architectures to achieve certification. Automotive display applications face the steepest compliance redesign cycles due to叠加 vehicle-level EMC requirements.
Automotive OEMs are compressing supplier qualification timelines as cabin display counts multiply per vehicle platform. Tier-1 electronics suppliers are consolidating vendor lists and demanding two-year cost-down commitments at contract signature. This behavior is most pronounced in Germany and Japan, where premium marques lead multi-panel instrument cluster adoption.
Display Driver Market Segmentation
Display driver ICs fragment across four distinct axes that determine silicon architecture, margin structure, and qualification timelines. Product type and application splits dominate revenue allocation, while technology and end-user dimensions shape foundry node selection and packaging requirements.
Product Type:
OLED drivers command premium pricing pools while LED drivers anchor volume shipments across mainstream consumer panels.
- OLED Driver:Complex compensation circuitry corrects pixel degradation over operational lifetime. South Korean panel manufacturers concentrate procurement for flagship smartphone lines, where variable refresh rate synchronization mandates larger die area and embedded frame buffers.
- LCD Driver:Mature timing controller integration at 40nm nodes enables cost-optimized sourcing for high-volume television and monitor applications. China's domestic panel capacity expansion sustains foundry allocation for this segment through captive supply agreements.
- LED Driver:Current-mode architectures serve backlight unit control in edge-lit and mini-LED configurations. Automotive instrument cluster adoption is climbing fastest as cabin digitization multiplies LED zone counts per vehicle.
- TFT Driver:Amorphous silicon and LTPS panel compatibility requires gamma correction precision across extended temperature ranges. Industrial display applications specify these drivers for outdoor signage and kiosk terminals.
Mature deployment sits with LCD Driver. Newer deployment is concentrated in OLED Driver.
Application:
Smartphone procurement drives leading-edge node adoption while television volumes sustain trailing-edge foundry utilization.
- Smartphones:High-refresh-rate panels at 120Hz and above demand source drivers with integrated touch-sensing noise suppression. South Korean and Chinese OEMs specify 28nm silicon for flagship tier differentiation.
- Televisions:8K resolution timing controllers consolidate multiple source drivers per panel, elevating channel count requirements. Cost pressure from Chinese set manufacturers compresses driver ASPs toward commodity levels.
- Tablets:Stylus latency specifications below 10 milliseconds require dedicated touch-reporting synchronization circuits. Education sector procurement in India and Southeast Asia sustains mid-range driver demand.
- Laptops:Low-power panel self-refresh modes extend battery endurance for mobile productivity use cases. Enterprise fleet refresh cycles in North America and Western Europe determine seasonal demand patterns.
Volume concentration centers on Television. Premium margin capture concentrates in Smartphone.
Technology:
Digital architectures displace analog dominance as panel resolution and refresh rate specifications escalate.
- Digital:Programmable gamma tables and dynamic voltage scaling enable factory calibration flexibility. Smartphone and automotive applications mandate digital architectures for software-updatable compensation algorithms.
- Hybrid:Analog pixel driving with digital timing control balances power efficiency against calibration precision. Tablet and laptop panel manufacturers specify hybrid solutions for mid-tier product positioning.
- Analog:Fixed gamma curves and discrete voltage references serve cost-sensitive television and monitor segments. Legacy production lines in Taiwan and China maintain analog driver output for regional brands.
- VESA:DisplayPort and embedded DisplayPort protocol compliance enables adaptive sync and panel self-refresh standardization. Gaming monitor manufacturers in Germany and the United States specify VESA-certified drivers for premium SKU differentiation.
Analog architectures retain share in cost-optimized Television. Digital deployment is expanding most quickly across Smartphone and Automotive.
End User:
Consumer electronics absorb process node maturation while automotive and medical segments impose reliability premiums.
- Consumer Electronics:Smartphone, tablet, and television manufacturers drive annual foundry capacity planning through concentrated procurement windows. Chinese OEMs specify domestic driver IC sourcing under national semiconductor self-sufficiency directives.
- Automotive Displays:AEC-Q100 Grade 1 qualification mandates extended temperature operation from minus 40 to 125 degrees Celsius. German and Japanese Tier-1 suppliers consolidate vendor lists as instrument cluster panel counts multiply per vehicle platform.
- Industrial Equipment:Extended availability commitments and harsh environment sealing specifications elevate driver packaging costs. Factory automation HMI deployments in Germany and Japan specify industrial-grade drivers for 24/7 operational duty cycles.
- Medical Devices:Diagnostic imaging panels require 10-bit and 12-bit grayscale precision for DICOM calibration compliance. FDA and EU MDR documentation requirements extend qualification timelines for new driver introductions.
Volume scale sits with Consumer Electronics. Steepest expansion trajectory is concentrated in Automotive Displays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in South Korea and China, where panel makers anchor foundry allocation decisions. Foundry partnerships tighten supply coordination around Seoul's semiconductor cluster and Shenzhen's display ecosystem. Divergent energy-efficiency mandates across jurisdictions fragment qualification timelines.
South Korea
Flagship smartphone panel production drives leading-edge node demand for OLED driver ICs. The Ministry of Trade, Industry and Energy enforces domestic content requirements shaping procurement for national display champions. Samsung Electronics anchors captive foundry capacity in Suwon and Pyeongtaek, securing wafer supply for high-resolution mobile panels.
China
Domestic panel capacity expansion sustains foundry allocation for LCD and emerging OLED lines. SAMR implements GB 4943.1 electromagnetic compatibility standards mandating stricter emission controls for display modules. BOE Technology and TCL CSOT concentrate driver IC demand in Beijing and Shenzhen, where local procurement directives favor domestic sourcing.
Taiwan
Co-development programs with panel manufacturers anchor MediaTek's position in timing controller integration. The National Communications Commission enforces EMC certification aligning with international standards while maintaining regional testing protocols. Hsinchu Science Park hosts foundry and fabless design concentration, where TSMC and UMC allocate 28nm capacity for display driver production.
United States
Automotive OEM qualification timelines compress as cabin display counts multiply per vehicle platform. FCC Part 15 regulations govern unintentional radiators in display modules, extending certification cycles for multi-panel instrument clusters. Synaptics maintains design operations in California, where proximity to automotive Tier-1 suppliers supports driver development for infotainment systems.
Japan
Premium marques lead multi-panel instrument cluster adoption, consolidating vendor lists with two-year cost-down commitments. METI oversees industrial standards coordination through JIS specifications for automotive electronics reliability. Sharp and Japan Display concentrate procurement in Osaka and Tokyo prefectures, where AEC-Q100 Grade 1 qualification mandates extended temperature operation.
Display Driver Market Vendor Landscape
Capacity expansion dominates the current landscape as foundries race to secure 28nm allocation for display driver ICs. The vendor base concentrates among fabless specialists and integrated device manufacturers with captive foundry access. Three archetypes define positioning: semiconductor conglomerates with vertical fabrication control, fabless design houses with panel-maker partnerships, and automotive-grade specialists with extended temperature certification. Strategic partnerships and geographic expansion constitute the dominant competitive vectors as firms secure qualification across China's GB standards and South Korea's domestic content regimes.
Among South Korea-based integrated manufacturers, Samsung Electronics Co., Ltd. and LX Semicon Co., Ltd. exemplify the captive-foundry archetype, securing wafer supply through in-house fabrication. Himax Technologies, Inc. occupies a specialist position in automotive-grade driver solutions, representing the extended-reliability tier where AEC-Q100 certification creates qualification barriers. MediaTek Inc. anchors the fabless partnership model, leveraging co-development programs with leading OLED panel manufacturers in Taiwan and South Korea to secure design wins.
| Leading Market Players |
|---|
| Himax Technologies, Inc. |
| Raydium Semiconductor Corporation |
| Samsung Electronics Co., Ltd. |
| MediaTek Inc. |
| Sitronix Technology Corporation |
| Novatek Microelectronics Corp. |
| Silicon Works Co., Ltd. |
| LX Semicon Co., Ltd. |
| Synaptics Incorporated |
| Others |
Supply Flow & Price Mechanics
South Korean and Chinese smartphone OEM procurement concentration anchors a contract-based long-term offtake model where foundry allocation windows determine effective pricing power. Panel manufacturers leverage multi-year supply agreements to lock in 28nm wafer supply, compressing spot-market exposure for advanced node driver ICs.
Pricing Analysis
Volume shipments of LCD drivers at 40nm nodes sustain commodity-level ASPs while OLED driver premiums capture margin pools through embedded compensation algorithms and variable refresh rate certification. Price differentiation rests on AEC-Q100 automotive grade versus consumer-tier qualification, with German and Japanese Tier-1 suppliers absorbing reliability premiums for instrument cluster applications. Pricing pressure stems from Chinese set manufacturers driving television driver costs toward monitor-panel levels. Education sector tablet procurement in India exhibits highest price sensitivity, whereas medical imaging panel buyers prioritize 12-bit grayscale precision over unit economics.
Supply Chain Analysis
Photoresist and copper interconnect materials rest on Japanese specialty chemical producers and Taiwan foundry ecosystems, tethering cost structures to Asia-Pacific feedstock availability. Wafer fabrication concentrates in Taiwan, South Korea, and China, with TSMC and Samsung Electronics anchoring advanced node capacity. Single-source vulnerability runs through 28nm foundry allocation during smartphone demand spikes. Distribution runs through captive OSATs with copper pillar bumping expertise and merchant assembly houses serving regional panel makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around foundry-backed scale players as copper interconnect migration and 28nm capacity scarcity force fabless design houses toward acquisition or exit.
For Market Incumbents: Deploy captive foundry capacity expansion in South Korea and Taiwan to secure wafer allocation against emerging China domestic sourcing mandates. Deepen timing controller integration at 28nm nodes to differentiate from merchant driver suppliers. Samsung Electronics and LX Semicon leverage in-house fabrication to withstand margin compression from Chinese panel maker vertical integration pushes. For New Entrants and Emerging Players: The premium-to-economy tier gap in automotive LED drivers opens white-space for AEC-Q100 Grade 1 qualification specialists. Target industrial HMI deployments in Germany and Japan where extended availability commitments elevate packaging costs and deter commodity entrants. Pursue co-development partnerships with emerging India PLI beneficiaries to localize assembly and test capacity ahead of domestic panel ramp. For Investors and Strategic Acquirers: The window for entry favors automotive-grade specialists with AEC-Q100 certification and extended temperature reliability IP. Mixed-signal design talent scarcity at legacy IDMs creates acquisition targets among Taiwan-based fabless houses with panel-maker relationships. Watch for China SAMR domestic content enforcement tightening as inflection signal for regional supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Consolidation | Samsung Electronics secures wafer supply for OLED drivers through captive Pyeongtaek capacity. |
| Automotive Certification Investment | Himax Technologies meets AEC-Q100 Grade 1 standards for German Tier-1 instrument cluster adoption. |
| India PLI Localization | Domestic display manufacturing incentives create captive driver assembly demand in Gujarat and Tamil Nadu. |
| Copper Interconnect Migration | 28nm node maturation enables cost-effective timing controller integration at MediaTek. |
| Micro-LED Architecture Development | Modular driver designs target commercial display mass transfer yield improvements. |
Methodological Framework
SEC 10-K filings, ECHA REACH substance restriction updates, and China SAMR GB standard publications formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with foundry planning officers, panel maker procurement directors, and automotive Tier-1 electronics suppliers validated capacity allocation assumptions and qualification timeline estimates. Bottom-up wafer demand modeling and top-down display panel production forecasts were triangulated against customs trade data for driver IC shipments.
Historical trendline analysis across smartphone, television, and automotive display shipments informed the projection framework. Segmentation dimensions modeled include product type, application, technology architecture, and end-user vertical with regional regulatory cluster overlays. CAGRs were derived from foundry capacity expansion schedules and panel maker procurement commitment disclosures. Copper interconnect yield curves and OLED compensation algorithm die area requirements served as industry-specific forecast inputs.
Inputs from foundry utilization reports and panel maker earnings disclosures were available through the study window; gaps in merchant OSAT capacity utilization introduce uncertainty bands around assembly cost trajectories. Forecasts reflect documented assumptions regarding China domestic content enforcement timing and South Korea Ministry of Trade energy-efficiency mandate implementation. A small set of triggers—Taiwan foundry allocation shocks, REACH substance restriction expansion, and India PLI scheme disbursement pacing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Micro Server IC Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
5G Processor Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Global Multimedia Chipsets Market