
 Latin America Gas Sensors Market | 2026-2036
Latin America Gas Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Gas Sensors Market Foresight
Buyer concentration across Latin American oil and gas operators is broadening as national energy companies decentralize procurement to private midstream contractors. Honeywell International Inc. leverages its channel partnerships with Pemex affiliates to sustain instrumentation contracts across Mexican refining clusters. Robert Bosch GmbH anchors automotive exhaust sensor supply for Brazilian OEM assembly lines. Siemens AG competes through integrated safety system offerings that bundle gas detection with process control platforms.
Gas sensors are transducer devices that detect and quantify target gas concentrations through electrochemical reactions, infrared absorption, or semiconductor resistance changes, typically operating across temperature ranges from minus forty to plus fifty degrees Celsius with detection thresholds in parts-per-million. Their primary purpose is to prevent toxic exposure, combustion hazards, and environmental violations in enclosed or industrial atmospheres. Electrochemical cell technology leads Latin American industrial procurement due to proven reliability in humid tropical conditions, while non-dispersive infrared platforms capture expanding share in emission monitoring applications requiring carbon dioxide and methane specificity. Photoionization detectors occupy niche positions in petrochemical leak detection where volatile organic compound sensitivity justifies premium positioning.
Brazil's national petroleum regulator ANP enforces mandatory gas detection at offshore platforms and downstream facilities, while Mexico's ASEA mandates continuous atmospheric monitoring at hydrocarbon storage terminals under refined products regulations. Argentina's Secretariat of Energy enforces similar standards through provincial environmental licenses for Vaca Muerta shale operations. Stakeholders must monitor evolving Mercosur technical standards alignment and decide whether to certify products under unified regional protocols or maintain separate national approval tracks.
Market Dynamics
Latin American gas sensor deployment pivots on regulatory enforcement divergence between national oil company procurement centralization and provincial environmental licensing fragmentation, creating tiered compliance markets that favor regionally certified suppliers over global standard portfolios.
Growth Catalysts
- ANP Offshore Mandates:Brazil's national petroleum regulator requires continuous atmospheric monitoring at all floating production units, expanding electrochemical sensor retrofit programs across pre-salt basin platforms.
- Vaca Muerta Shale Licensing:Argentina's provincial environmental authorities embed gas detection requirements into hydrocarbon extraction permits, driving fixed-point detector installations at wellhead compression stations.
- Non-Dispersive Infrared Advancement:Improved optical path stability in tropical humidity conditions positions NDIR platforms for methane-specific monitoring in Colombian pipeline corridors.
Market Restraints
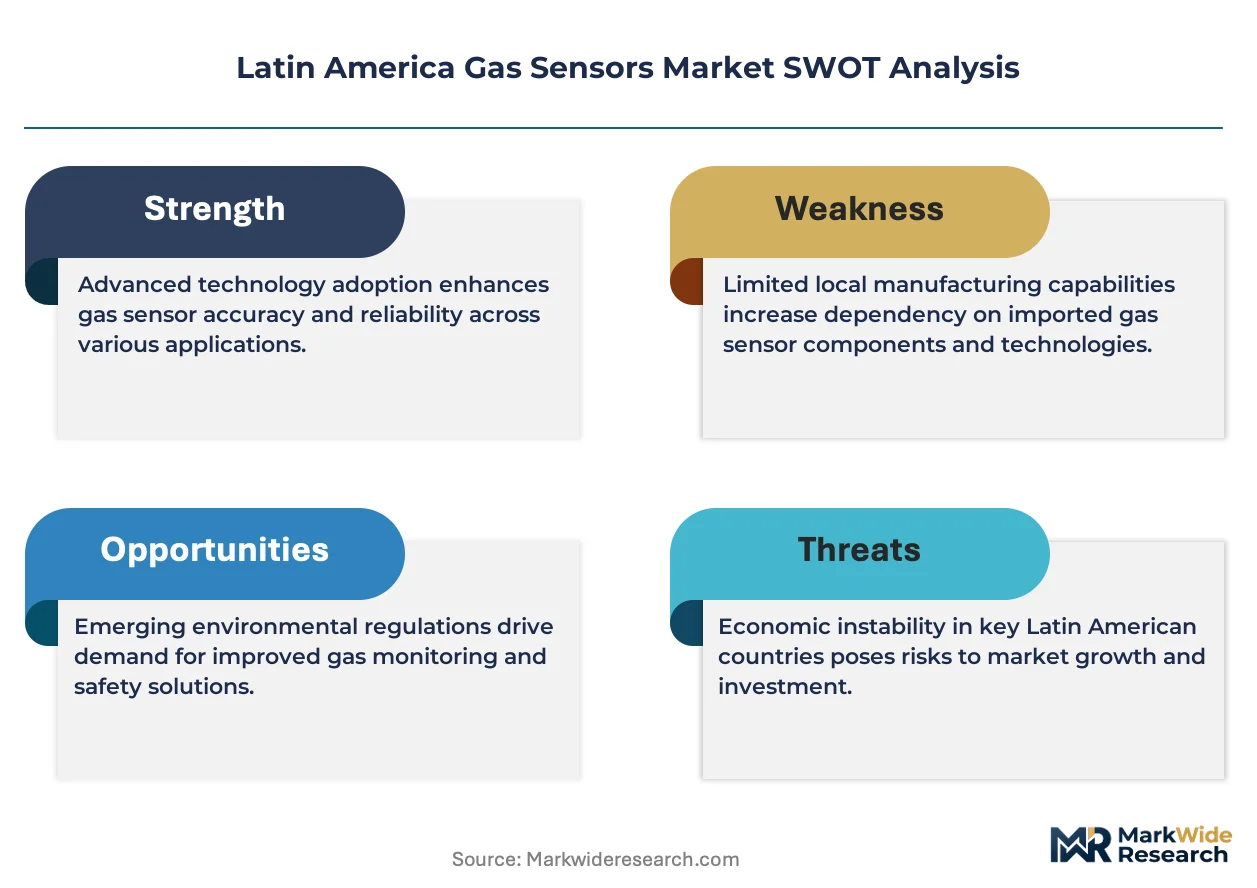
- Precious Metal Input Volatility:Electrochemical cell production depends on platinum and palladium catalysts sourced through concentrated South African and Russian supply channels, exposing Brazilian manufacturers to exchange rate-compounded cost spikes.
- Calibration Infrastructure Gaps:Certified reference gas availability remains restricted to São Paulo, Mexico City, and Buenos Aires metropolitan zones, forcing remote Andean mining operations to absorb elevated service logistics costs.
- Semiconductor Sensor Substitution:Metal oxide platforms achieve sufficient accuracy for residential carbon monoxide applications at one-third the unit cost of electrochemical alternatives, compressing addressable market scope in consumer segments.
Strategic Opportunities
- Chilean Mining Electrification:Copper and lithium extraction operations transitioning to battery-electric underground fleets create demand for multi-gas detectors monitoring hydrogen evolution alongside traditional combustible and toxic species.
- ASEA Terminal Regulations:Mexico's energy safety agency mandates leak detection and repair protocols at refined products storage facilities, opening service contracts for integrated sensor-telemetry systems.
- IoT Convergence:Wireless mesh networking protocols paired with edge-computing analytics enable predictive maintenance models that unbundle hardware sales from recurring software subscriptions.
Industry Challenges
- Metrology Certification Timelines:INMETRO approval processes for new sensor chemistries extend eighteen to twenty-four months in Brazil, delaying product launches behind competitor introductions in adjacent Mercosur markets.
- Legacy System Integration:Pemex and Ecopetrol refineries operate distributed control platforms from 1990s vintages with proprietary communication buses, requiring custom protocol gateways that inflate project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Gas Sensors Market |
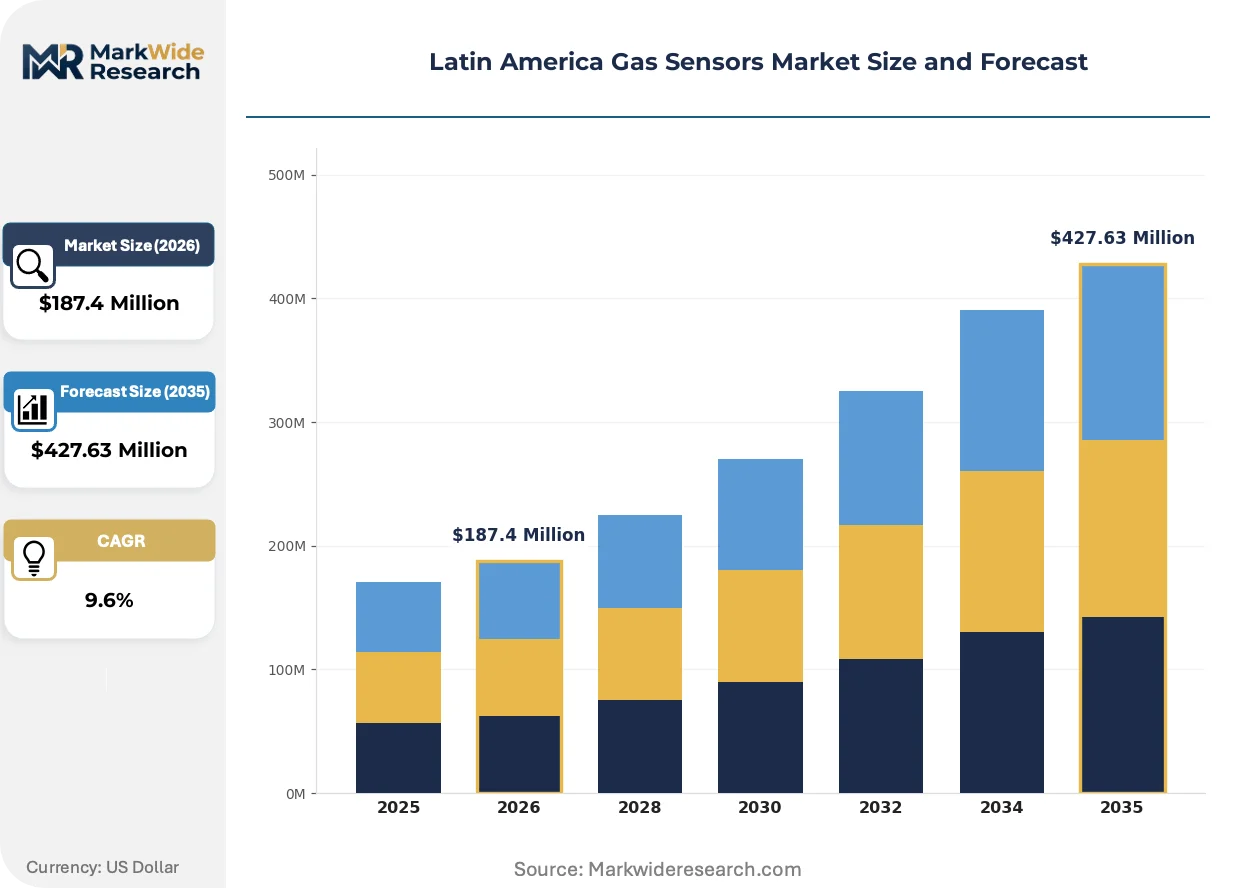
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-Oxide Semiconductor, Electrochemical, Infrared, Ultrasonic Technology: Electrochemical Cell, Non-Dispersive Infrared, Photoionization Detectors, Catalytic Bead End User: Industrial, Residential, Automotive, Environmental Monitoring Application: Leak Detection, Air Quality Monitoring, Emission Monitoring, Safety Systems |
| Companies Covered | ABB Ltd., Honeywell International Inc., Robert Bosch GmbH, Amphenol Advanced Sensors, Figaro Engineering Inc., Nemoto Sensor Engineering Co., Ltd., Dragerwerk AG & Co. KGaA, Siemens AG, NGK Insulators Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Gas Sensors Market Shifts & Advancements
Technology trajectories in Latin American gas sensing center on miniaturization enabling wearable form factors, regulatory harmonization pressures accelerating certification consolidation, and procurement decentralization shifting specification authority from national oil companies to specialized midstream contractors.
Photoionization detector miniaturization is rewriting field deployment economics for volatile organic compound monitoring. Brazilian petrochemical maintenance contractors adopt handheld units weighing under 400 grams for perimeter screening during turnaround outages. The technology compresses response times from minutes to seconds, enabling real-time go/no-go decisions that eliminate stationary detector relocation labor.
Mercosur technical standards alignment discussions are advancing toward unified electromagnetic compatibility and environmental testing protocols. Argentina's Secretariat of Industry and Brazil's INMETRO coordinate mutual recognition agreements that would eliminate redundant certification costs for sensors crossing member borders. Colombian and Chilean regulators observe the process but maintain independent approval tracks pending outcome clarity.
Midstream logistics operators now specify sensor-telemetry bundles through engineering procurement construction contractors rather than direct national oil company tenders. Mexican pipeline construction consortia embed continuous monitoring into lump-sum contracts, transferring operational technology selection authority from Pemex technical committees to contractor engineering departments. The pattern concentrates procurement volume with firms demonstrating integrated safety system execution capability across multiple Latin American jurisdictions.
Latin America Gas Sensors Market Segmentation
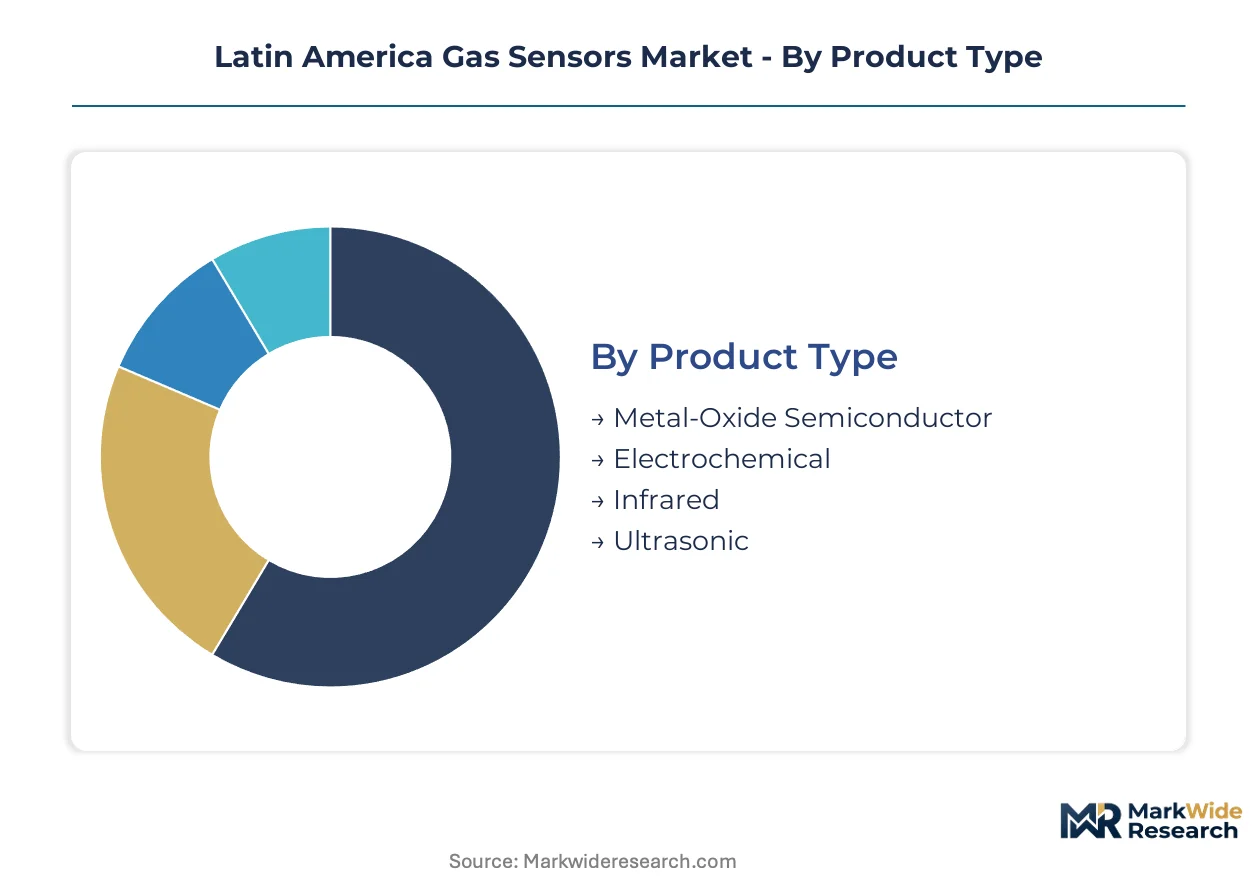
Gas sensor procurement across Latin America fragments across detection chemistry, deployment environment, and regulatory compliance tier. Buyers prioritize electrochemical reliability in humid tropical conditions while infrared platforms capture methane-specific monitoring contracts.
Product Type:
Industrial buyers select detection platforms based on target gas specificity, cross-sensitivity tolerance, and total cost of ownership across calibration cycles.
- Electrochemical:Three-electrode cells with sulfuric acid electrolyte achieve sub-ppm resolution for hydrogen sulfide and carbon monoxide. Brazilian petrochemical operators specify these for offshore platform retrofits under ANP atmospheric monitoring mandates.
- Infrared:Non-dispersive absorption benches with dual-wavelength referencing eliminate humidity interference. Colombian pipeline operators deploy these for methane leak detection across Andean corridor compression stations.
- Metal-Oxide Semiconductor:Tin dioxide sensing layers with integrated heaters detect combustible vapors at reduced unit cost. Residential carbon monoxide alarms in Mexican urban markets favor these for price-sensitive consumer segments.
- Ultrasonic:Acoustic emission detection identifies gas leaks through pressure-wave analysis without direct chemical contact. Argentine Vaca Muerta shale wellheads trial these for non-intrusive perimeter monitoring.
Electrochemical sensors lead on scale; infrared platforms lead on momentum.
Technology:
Technology selection hinges on detection threshold requirements, response speed demands, and integration complexity with existing distributed control architectures.
- Non-Dispersive Infrared:Optical benches with gold-plated reflector assemblies achieve methane specificity below 50 ppm without cross-sensitivity to humidity. Mexican energy reform leak detection mandates at refined products terminals accelerate procurement.
- Electrochemical Cell:Amperometric cells with porous membrane diffusion barriers operate across minus forty to plus fifty degrees Celsius. Brazilian mining safety regulators specify these for underground hydrogen sulfide compliance.
- Photoionization Detectors:Ultraviolet lamp ionization chambers with ten point six electron volt photon energy detect volatile organic compounds at parts-per-billion thresholds. Brazilian petrochemical maintenance contractors adopt handheld miniaturized units for turnaround perimeter screening.
- Catalytic Bead:Platinum-coated wire coils detect combustible gas through catalytic oxidation heat release. Legacy installations at Pemex refining clusters retain these for methane monitoring despite higher drift rates than optical alternatives.
Electrochemical cell technology dominates installed base; non-dispersive infrared gains share fastest in new project specifications.
End User:
End-user segmentation reflects divergent procurement authority structures, from centralized national oil company tenders to decentralized residential retail channels.
- Industrial:Oil and gas, mining, and petrochemical operations with mandatory atmospheric monitoring under national regulator enforcement. Brazilian ANP offshore platform mandates and Mexican ASEA terminal regulations concentrate demand.
- Automotive:Exhaust gas oxygen and nitrogen oxide sensors for OEM assembly line integration. Brazilian vehicle production clusters specify these for emission control module compliance.
- Environmental Monitoring:Stationary ambient air quality stations and mobile monitoring vehicles. Colombian urban air quality networks deploy these for particulate and ozone co-location studies.
- Residential:Standalone carbon monoxide and natural gas alarms for consumer retail distribution. Mexican building code amendments drive replacement cycles in metropolitan zones.
Industrial end users command procurement volume; automotive segments follow platform standardization trends.
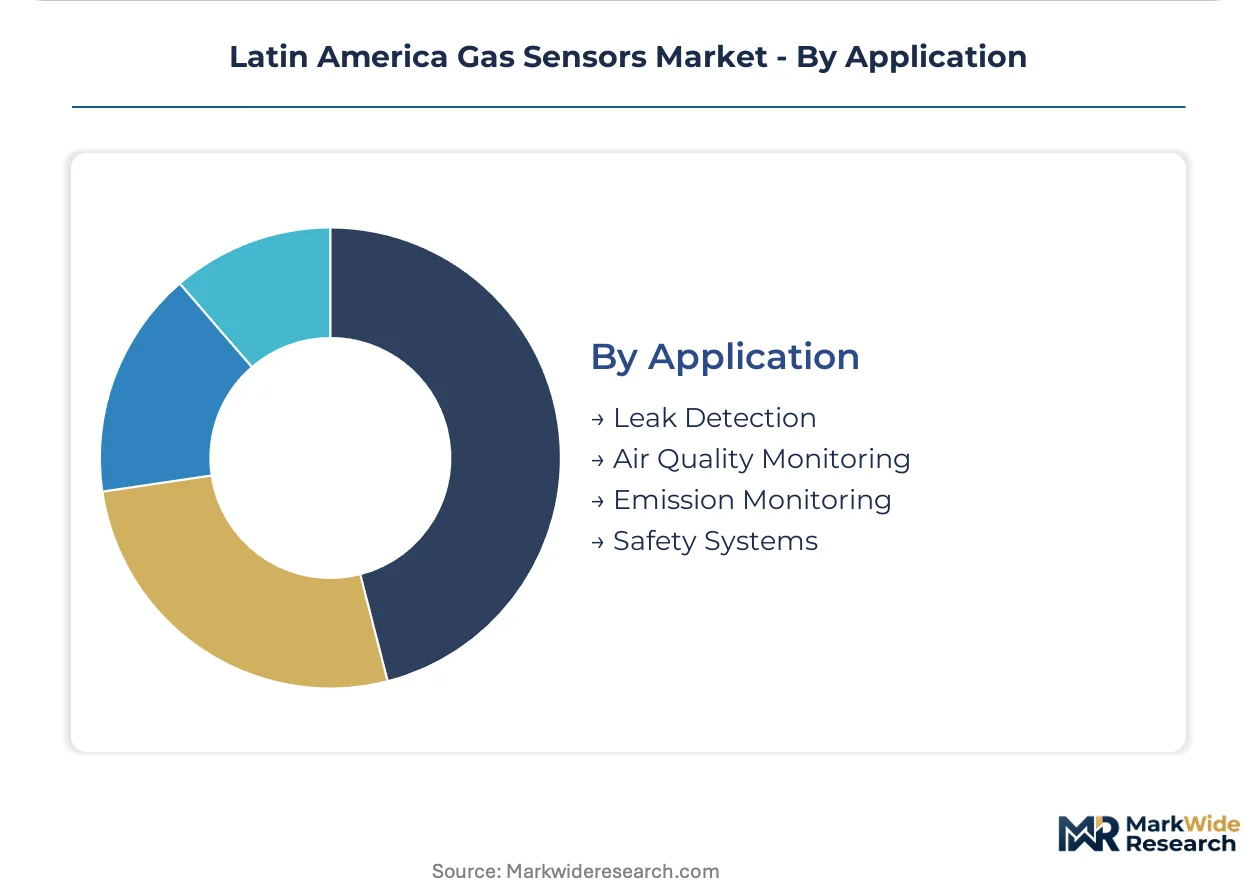
Application:
Application segmentation tracks regulatory mandate evolution, with leak detection and emission monitoring gaining specification authority as environmental enforcement tightens.
- Leak Detection:Continuous perimeter monitoring and portable survey instruments for pipeline and storage facility integrity. Mexican pipeline construction consortia embed these specifications into lump-sum engineering contracts.
- Safety Systems:Fixed-point detectors with control panel integration for toxic and combustible gas alarms. Argentine provincial environmental licenses for Vaca Muerta operations mandate wellhead installations.
- Emission Monitoring:Stack and flare gas analyzers for regulatory reporting and carbon accounting. Colombian oilfield operators deploy these for methane intensity reduction commitments.
- Air Quality Monitoring:Urban ambient networks and indoor environmental quality sensors. Chilean copper mining electrification projects create demand for hydrogen evolution monitoring alongside traditional species.
Safety systems applications anchor revenue stability; leak detection specifications expand fastest through midstream contractor procurement decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands larger procurement volumes than Mexico, yet Mexican regulatory velocity under ASEA mandates is accelerating faster project pipelines for leak detection infrastructure.
Brazil
Offshore platform retrofits dominate demand as ANP mandates expand across pre-salt basin floating production units. INMETRO certification timelines stretching eighteen to twenty-four months delay new electrochemical chemistry launches behind Mercosur neighbors. São Paulo metropolitan clusters concentrate calibration infrastructure and sensor distribution logistics for nationwide supply.
Mexico
Energy reform leak detection mandates at refined products terminals create specification authority shifts from Pemex committees to EPC contractors. ASEA protocols require continuous atmospheric monitoring at hydrocarbon storage facilities. Northern border states and the Bajío Region concentrate pipeline construction consortia embedding sensor-telemetry bundles into lump-sum contracts.
Argentina
Vaca Muerta shale licensing embeds gas detection requirements into provincial environmental permits for wellhead compression stations. The Secretariat of Energy enforces atmospheric monitoring standards through extraction licensing frameworks. Neuquén Province concentrates fixed-point detector installations at extraction clusters.
Colombia
Pipeline corridor methane monitoring drives non-dispersive infrared platform procurement across Andean compression stations. Urban air quality networks deploy stationary ambient monitoring for particulate co-location studies. Bogotá metropolitan infrastructure anchors calibration service availability for remote field operations.
Chile
Mining electrification creates demand for multi-gas detectors monitoring hydrogen evolution alongside traditional combustible and toxic species. Copper and lithium extraction operations transitioning to battery-electric underground fleets require expanded safety system specifications. Antofagasta and Atacama regions concentrate deployment for extraction safety compliance.
Latin America Gas Sensors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale-driven instrumentation groups hold offshore platform contracts while regional distributors capture provincial mining licenses. The vendor base organizes around three strategic archetypes: integrated safety system bundlers, component specialists with electrochemical cell expertise, and automotive exhaust sensor suppliers. Capacity expansion in Brazilian electrochemical manufacturing and technology licensing partnerships for infrared platform localization represent dominant competitive moves.
Among diversified industrial technology groups, Honeywell International Inc., Siemens AG, and ABB Ltd. exemplify the integrated safety system archetype, occupying positions that bundle gas detection with process control platforms across Latin American refining and petrochemical clusters. These entities leverage channel partnerships and direct national oil company relationships to sustain instrumentation contract flows.
| Leading Market Players |
|---|
| ABB Ltd. |
| Honeywell International Inc. |
| Robert Bosch GmbH |
| Amphenol Advanced Sensors |
| Figaro Engineering Inc. |
| Nemoto Sensor Engineering Co., Ltd. |
| Dragerwerk AG & Co. KGaA |
| Siemens AG |
| NGK Insulators Ltd. |
| Others |
Supply & Pricing Matrix
Mexican EPC contractor consolidation around lump-sum sensor-telemetry bundles is compressing procurement margins and forcing electrochemical cell manufacturers toward São Paulo capacity additions to defend price competitiveness.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for electrochemical sensors serving ANP-mandated offshore retrofits. Three-tier pricing structure across premium certified, standard industrial, and economy residential levels stratifies by INMETRO certification tier and calibration service bundling. Cost compression in consumer metal-oxide segments is intensifying because semiconductor platforms achieve carbon monoxide detection at one-third electrochemical unit cost. Residential retail channels exhibit highest price sensitivity; offshore platform operators under regulatory mandate show lowest.
Supply Chain Analysis
Electrochemical cell assembly workforce availability concentrates in São Paulo industrial corridors and Mexico City metropolitan zones. Platinum and palladium catalyst sourcing draws from South African and Russian supply channels. Single-source vulnerability in precious metal inputs exposes Brazilian manufacturers to exchange rate-compounded cost spikes. Distribution runs through regional distributors capturing provincial mining licenses alongside direct national oil company tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America gas sensor procurement rewards geographic arbitrage between Brazilian manufacturing scale and Mexican regulatory velocity, with ASEA-mandated terminal retrofits offering faster payback than INMETRO-delayed product launches.
For Market Incumbents: Deepen backward integration into platinum catalyst supply through South African offtake agreements to offset precious metal volatility. Expand electrochemical manufacturing capacity in São Paulo to reduce unit costs for ANP-mandated offshore platform retrofits. Secure INMETRO pre-approval for new chemistries to compress eighteen-to-twenty-four-month certification timelines behind Mercosur competitors.
For New Entrants and Emerging Players: The price-point gap between handheld photoionization detectors and fixed-point electrochemical installations opens white-space at mid-tier portable monitoring for Brazilian petrochemical maintenance contractors. Target Colombian pipeline corridor methane monitoring where NDIR platform procurement accelerates under emission reduction commitments. Pursue wireless mesh IoT convergence to unbundle hardware sales from recurring software subscriptions.
For Investors and Strategic Acquirers: Asymmetric upside sits with electrochemical cell specialists possessing INMETRO certification infrastructure and Pemex channel relationships. Long-term viability hinges on regulatory enforcement durability across Latin American hydrocarbon extraction licensing. Monitor Mercosur technical standards alignment progress for mutual recognition agreement implementation as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | São Paulo electrochemical manufacturing scale reduces unit costs for ANP-mandated offshore retrofits. |
| Backward Integration | Platinum catalyst supply control mitigates South African and Russian channel volatility exposure. |
| Technology Licensing | NDIR platform localization partnerships capture Colombian pipeline methane monitoring procurement. |
| Joint Venture | Mexican EPC contractor alliances transfer specification authority from Pemex committees to integrated safety system bundlers. |
| Certification Investment | INMETRO pre-approval infrastructure compresses product launch timelines behind Mercosur neighbors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sensor procurement managers at national oil companies, EPC contractor engineering directors, and electrochemical cell manufacturing plant managers with secondary validation against ANP regulatory filings, ASEA protocol documentation, and INMETRO certification databases. Bottom-up project pipeline enumeration and top-down industrial safety spend estimates were triangulated to anchor market sizing.
Comparable-period anchoring linked historical electrochemical sensor deployment rates to forward ANP offshore mandate expansion schedules and ASEA terminal retrofit timelines across the projection horizon. Segmentation dimensions modeled include detection chemistry, deployment environment, end-user procurement authority structure, and regulatory compliance tier. CAGRs were derived from unit shipment trajectories and average selling price evolution, with precious metal input cost curves and certification timeline assumptions as industry-specific forecast inputs.
Caveats apply where Mercosur technical standards alignment delays or precious metal supply channel disruptions could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement durability and EPC contractor procurement decentralization momentum. Practitioners should monitor INMETRO-Mercosur mutual recognition agreement progress and South African platinum export policy for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Wireless Flow Sensors Market