
 Edge AI Processor Market | 2026-2036
Edge AI Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Edge AI Processor Market Analysis
Asset-light fabless licensing is narrowing the capital barrier for new entrants in edge silicon. NVIDIA Corporation leverages its CUDA software ecosystem to sustain design wins across robotics and smart surveillance deployments. Qualcomm Technologies, Inc. anchors its position by integrating AI accelerators directly into mobile and automotive SoC roadmaps. Intel Corporation competes through foundry partnerships that extend x86-compatible edge offerings into manufacturing predictive maintenance systems.
An edge AI processor is a dedicated compute engine that executes machine learning inference locally on device, typically operating within sub-15W thermal envelopes using INT8 or lower precision arithmetic to minimize latency and power draw. Its primary purpose is to eliminate round-trip data transmission to cloud datacenters for time-sensitive decisions in industrial and consumer environments. ASICs now capture the deepest margin pools where volume commitments from automotive and smartphone OEMs justify custom silicon tape-outs. FPGAs serve the fastest-growing niche in smart surveillance, where reconfigurable logic adapts to evolving computer vision algorithms without hardware respins. Embedded processors remain the volume backbone across retail facial recognition terminals, though per-unit silicon content stays comparatively thin.
FDA scrutiny of AI-enabled medical devices and NHTSA autonomous vehicle validation protocols are tightening functional-safety documentation requirements for healthcare and automotive edge deployments. The EU AI Act adds conformity assessment layers for high-risk applications, directly shaping product development roadmaps and market access timelines for European-bound hardware. Stakeholders must monitor whether emerging export controls on advanced process nodes force architectural shifts toward domestically manufacturable geometries.
Market Dynamics
Taiwan's foundry cluster concentrates 90 percent of leading-edge AI silicon capacity, creating chokepoint vulnerability for automotive and smartphone OEMs racing to secure wafer allocations. This geographic lock-in is reshaping procurement timelines and forcing architectural trade-offs.
Growth Catalysts
- Automotive inference demand:Level 2+ autonomous driving systems require dedicated neural processing units. OEMs in Germany, Japan, and the United States are qualifying multi-die chiplet packages for 2026 vehicle platforms.
- EU AI Act conformity infrastructure:High-risk embedded AI applications now face mandatory third-party assessment. Hardware vendors are pre-certifying inference engines to accelerate European market access for medical imaging and industrial safety systems.
- INT4 quantization maturation:Sub-8-bit arithmetic slashes memory bandwidth and power draw. Smart surveillance camera manufacturers in Shenzhen and Seoul are deploying INT4-capable accelerators to extend battery-operated deployment windows.
Market Restraints
- Advanced node access constraints:Export controls on EUV lithography equipment limit 7nm and below production to Taiwan and South Korea. Chinese fabless designers face forced migration to 12nm and larger geometries.
- Functional-safety certification costs:ISO 26262 ASIL-D qualification for automotive inference chips demands 18-24 month validation cycles. Tier-1 suppliers absorb these costs, squeezing margin for second-tier silicon vendors.
- GPU substitution in training:Cloud-based model development still concentrates in NVIDIA datacenter GPUs. Edge inference vendors struggle to capture upstream design-in influence as model architects optimize for CUDA ecosystems first.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor assembly and testing attract edge AI module packaging. Foxconn and Tata are qualifying Bengaluru and Chennai facilities for automotive-grade SiP production.
- Neuromorphic sensing fusion:Event-based vision sensors paired with spiking neural network accelerators enable sub-milliwatt always-on perception. Swiss and Dutch research consortia are commercializing silicon for drone navigation and predictive maintenance.
- Digital therapeutics hardware mandates:FDA breakthrough device designation pathways accelerate reimbursement for AI-enabled diagnostic peripherals. Home-based cardiac monitoring and diabetic retinopathy screening create new endpoint categories for low-power inference engines.
Industry Challenges
- Compiler toolchain fragmentation:Each silicon vendor maintains proprietary graph optimization stacks. ML engineers waste engineering months porting models between Qualcomm, MediaTek, and Ambarella SDKs.
- Spare wafer allocation volatility:Foundry customers without multi-year volume commitments face 40-week lead time swings. Fabless edge AI startups lose design wins when they cannot guarantee 52-week supply continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge AI Processor Market |
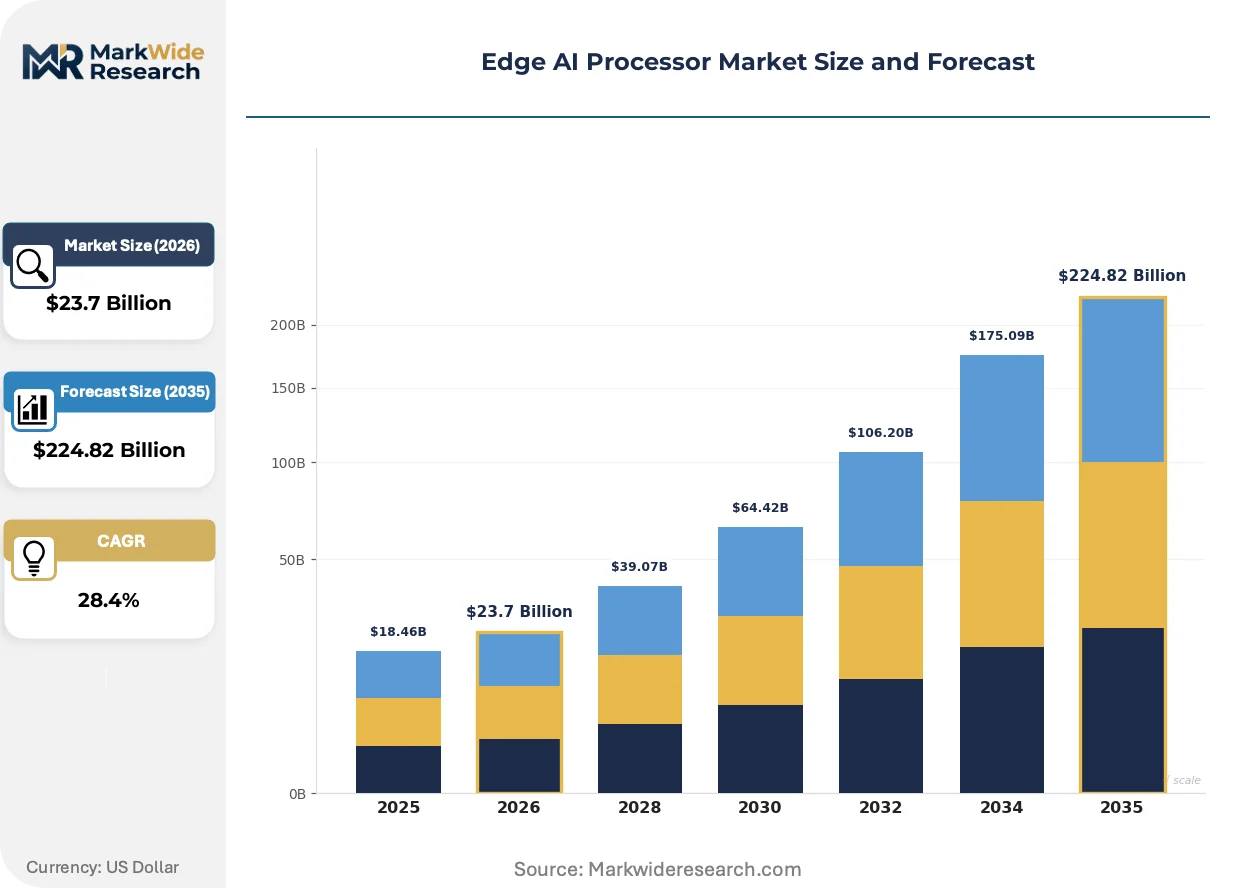
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $224.82 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Processors, Network Processors, ASICs, FPGAs End User: Manufacturing, Automotive, Retail, Healthcare Application: Real-Time Analytics, Facial Recognition, Predictive Maintenance, Smart Surveillance Technology: Machine Learning, Computer Vision, Natural Language Processing, Robotics |
| Companies Covered | NVIDIA Corporation, Qualcomm Technologies, Inc., Intel Corporation, Apple Inc., Samsung Electronics Co., Ltd., Advanced Micro Devices, Inc., Huawei Technologies Co., Ltd., MediaTek Inc., Mythic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge AI Processor Market Emerging Trajectories
Compute architectures are fragmenting across precision, memory hierarchy, and packaging approaches as application-specific optimization overrides general-purpose performance chasing. This specialization is compressing design cycles and fragmenting the vendor landscape.
Chiplet-based heterogeneous integration is migrating from high-performance computing into sub-10W edge devices. Automotive SoC designers are disaggregating neural accelerators, safety islands, and I/O hubs into separate dies connected by UCIe interconnects. This modularity lets OEMs swap accelerator tiles for vision versus lidar fusion without full retape-outs, compressing platform refresh cycles from 36 months to 18.
The EU AI Act's high-risk system classification is forcing documentation traceability into hardware development flows. Edge AI processors destined for medical triage or biometric identification must now ship with model cards, training data provenance logs, and conformity assessment body signatures. German automotive suppliers are embedding tamper-evident secure enclaves to satisfy these audit requirements, adding 8-12 percent die area overhead.
Industrial buyers are consolidating inference procurement around vertically integrated platform vendors rather than discrete silicon. Smart factory operators in Michigan and Bavaria now specify complete edge-to-cloud stacks with guaranteed latency SLAs, displacing component-level RFQ processes. This bundling favors vendors with in-house model optimization services and on-premise MLOps infrastructure over pure-play chip suppliers.
Edge AI Processor Market Segmentation
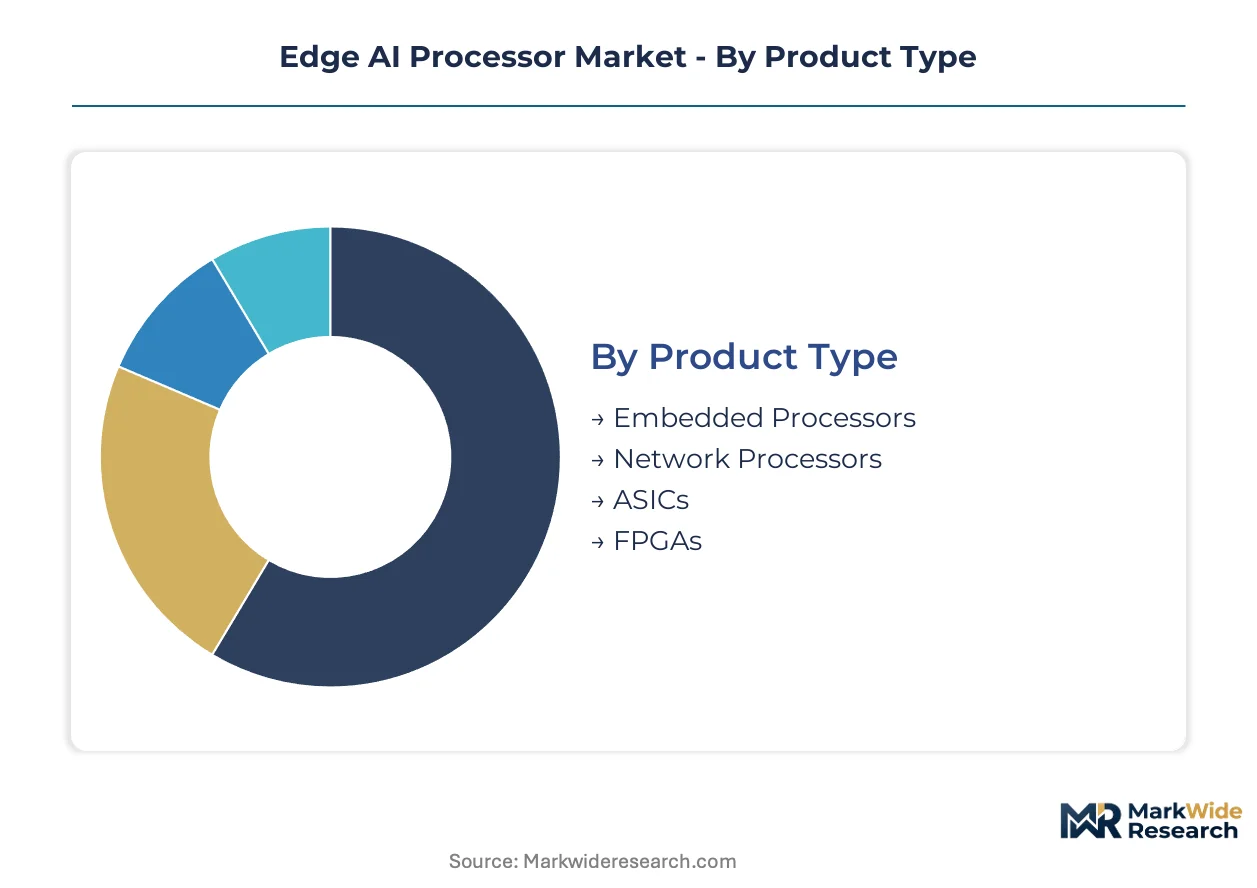
Edge AI processor segmentation reveals how architectural specialization tracks power budgets, latency requirements, and algorithmic workloads across industrial and consumer deployments. Understanding these category boundaries helps procurement teams match silicon selection to functional safety tiers and software ecosystem constraints.
Product Type:
Cost tier stratification separates high-volume consumer deployments from mission-critical industrial systems where qualification cycles justify custom silicon investment.
- ASICs:Purpose-built inference engines eliminate programmable logic overhead to minimize die area and power draw. Automotive OEMs in Germany and Japan commission ASIC tape-outs for Level 2+ autonomous driving platforms where ISO 26262 ASIL-D certification demands deterministic latency guarantees.
- FPGAs:Reconfigurable logic fabrics adapt to evolving neural network topologies without hardware respins. Smart surveillance system integrators in Shenzhen deploy Xilinx and Intel FPGA modules for algorithm updates that outpace fixed-function silicon refresh cycles.
- Embedded Processors:General-purpose CPU cores with modest AI acceleration serve cost-constrained endpoints.
- Network Processors:Data plane-optimized architectures handle packet inspection and edge gateway workloads.
ASICs hold installed capacity. FPGAs are rotating up the share rankings.
End User:
Application maturity varies sharply across verticals, with automotive and healthcare facing the steepest regulatory barriers to deployment.
- Automotive:Multi-camera fusion and lidar point cloud processing demand dedicated neural accelerators with functional safety documentation. NHTSA validation protocols and KBA type-approval processes in Germany extend qualification timelines to 24 months for inference chips destined for ADAS platforms.
- Healthcare:FDA breakthrough device pathways accelerate reimbursement for AI-enabled diagnostics, though 510(k) submissions require training data provenance and model performance benchmarking. Home-based cardiac monitoring peripherals in the United States now specify sub-500mW inference engines for battery-operated adherence.
- Manufacturing:Predictive maintenance vibration analysis and visual defect detection drive edge server deployments.
- Retail:Facial recognition terminals and inventory tracking cameras prioritize cost-optimized silicon over precision.
Manufacturing holds installed capacity. Healthcare is rotating up the share rankings.
Application:
Latency tolerance thresholds determine whether workloads tolerate cloud round-trips or mandate on-device execution.
- Smart Surveillance:Always-on video analytics at the network edge reduces backhaul bandwidth and storage costs. Seoul metropolitan authorities deploy INT4-quantized accelerators in public safety cameras to extend battery-operated deployment windows without sacrificing detection accuracy.
- Predictive Maintenance:Vibration and thermal sensor fusion on factory floors enables sub-millisecond anomaly detection. Bavarian automotive suppliers embed inference engines directly into CNC machine controllers to trigger immediate shutdowns before tool degradation propagates.
- Real-Time Analytics:Stream processing for industrial IoT telemetry demands deterministic throughput.
- Facial Recognition:Biometric authentication endpoints balance accuracy against privacy-preserving local processing.
Smart Surveillance holds installed capacity. Predictive Maintenance is rotating up the share rankings.
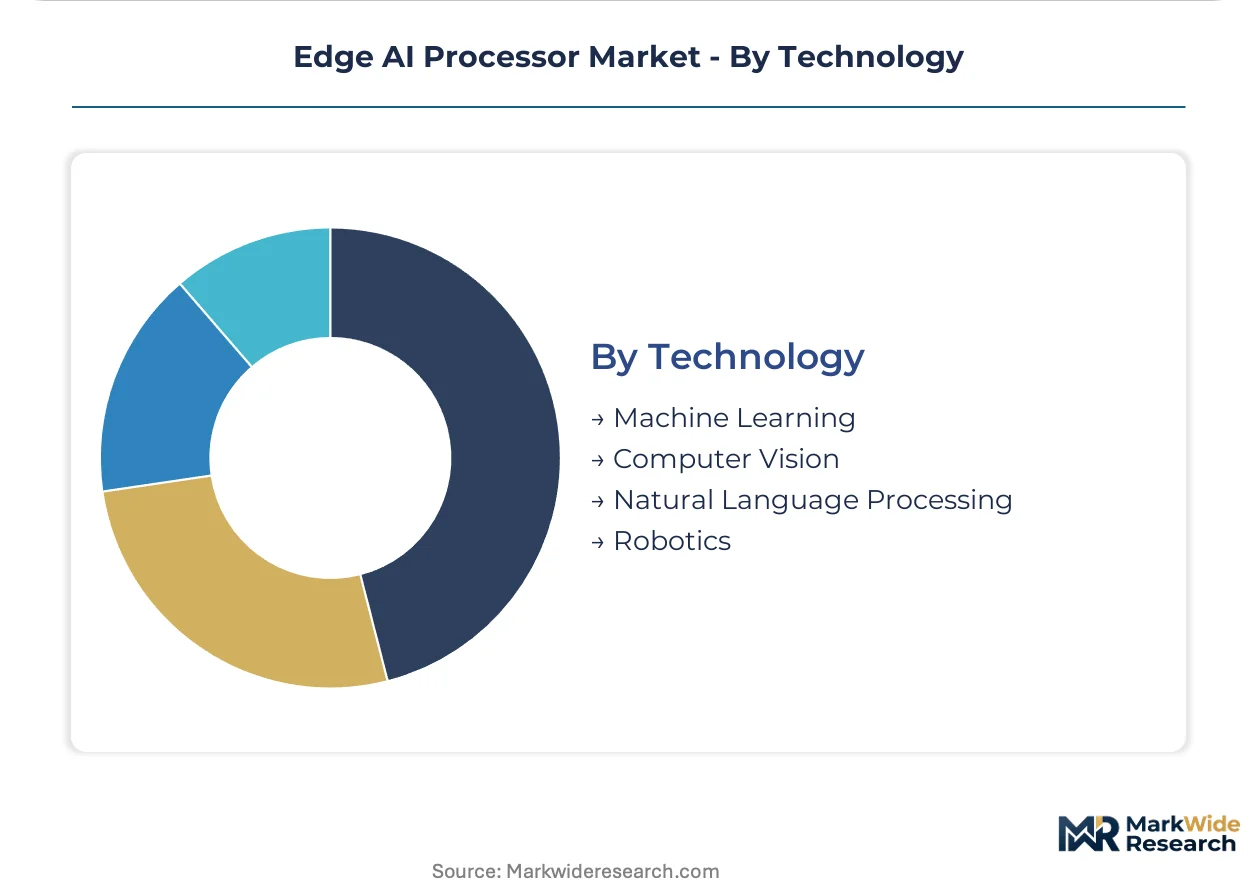
Technology:
Algorithmic workload characteristics drive divergent memory hierarchy and precision requirements across inference engines.
- Computer Vision:Convolutional and transformer-based architectures for object detection and segmentation dominate edge AI silicon roadmaps. NVIDIA CUDA-optimized vision pipelines anchor design wins across robotics deployments in Michigan and smart agriculture drones in the Netherlands.
- Machine Learning:Traditional statistical models and shallow neural networks serve resource-constrained microcontrollers.
- Natural Language Processing:Transformer compression techniques enable on-device speech recognition and sentiment analysis.
- Robotics:Simultaneous localization and mapping (SLAM) accelerators fuse sensor streams for autonomous navigation.
Computer Vision holds installed capacity. Robotics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export controls on advanced lithography equipment have inverted traditional trade flows in edge AI silicon. Taiwan and South Korea now dominate leading-edge wafer output while Chinese designers source legacy-node alternatives. German and Japanese automotive OEMs accelerate nearshoring of inference chip packaging to reduce geographic chokepoint exposure.
United States
NHTSA validation protocols for autonomous driving systems drive qualification demand for automotive-grade inference engines. The CHIPS and Science Act directs federal subsidies toward domestic semiconductor fabrication capacity expansion. Arizona and Texas host emerging foundry clusters where Intel and TSMC anchor advanced packaging operations for edge AI accelerators.
Germany
KBA type-approval processes extend qualification timelines to 24 months for ADAS-bound inference chips. The EU AI Act mandates conformity assessment for high-risk embedded AI applications entering European markets. Bavarian automotive suppliers embed secure enclaves in silicon designs to satisfy audit requirements for medical triage and biometric identification endpoints.
China
Smart surveillance camera manufacturers in Shenzhen deploy INT4-quantized accelerators for battery-operated deployment windows. Export restrictions on EUV equipment force fabless designers toward 12nm and larger geometries. The MIIT steers domestic semiconductor self-sufficiency programs toward mature-node edge AI specialization.
Japan
METI industrial policy prioritizes neuromorphic sensing fusion for sub-milliwatt always-on perception. Automotive OEMs in Nagoya and Tokyo qualify multi-die chiplet packages for 2026 vehicle platforms. Japanese robotics manufacturers anchor demand for SLAM accelerators in autonomous navigation applications.
India
PLI scheme subsidies attract edge AI module packaging to Bengaluru and Chennai facilities. Foxconn and Tata qualify automotive-grade SiP production for export markets. The country's electronics manufacturing incentives concentrate assembly and testing capacity while design activity clusters in Karnataka's semiconductor ecosystem.
Edge AI Processor Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated platform vendors with in-house model optimization services. Fabless licensing narrows capital barriers for new entrants while foundry capacity constraints favor established volume committers. Three archetypes dominate: CUDA-anchored software ecosystems, mobile-automotive SoC integrators, and custom ASIC specialists serving automotive OEMs. Competitive moves concentrate on strategic partnerships for foundry allocation security and portfolio diversification into healthcare and industrial safety segments.
Within the software-ecosystem tier, NVIDIA Corporation occupies a position exemplifying CUDA-anchored design wins across robotics and smart surveillance deployments. Qualcomm Technologies, Inc. and Intel Corporation sit within the platform-integration archetype, with the former representing mobile-automotive SoC convergence and the latter exemplifying foundry-partnership strategies for manufacturing predictive maintenance systems. These three entities anchor the competitive structure without exhausting its variation.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Qualcomm Technologies, Inc. |
| Intel Corporation |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Advanced Micro Devices, Inc. |
| Huawei Technologies Co., Ltd. |
| MediaTek Inc. |
| Mythic |
| Others |
Supply Flow & Price Mechanics
Kaohsiung-to-Los Angeles container freight corridors transmit foundry capacity scarcity directly into downstream silicon pricing, compressing margins for fabless designers while amplifying differentiation premiums for ASIC specialists with secured wafer commitments. Automotive OEM procurement teams now absorb logistics surcharges into landed chip costs, forcing tiered qualification fees that separate volume committers from spot-market buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade premiums for ISO 26262 ASIL-D qualified silicon, while economy tiers serve facial recognition terminals with stripped-down inference engines. Pricing pressure stems from INT4 quantization commoditizing mid-range accelerators, squeezing margin for second-tier vendors without automotive volume commitments. Healthcare device manufacturers exhibit lowest price sensitivity due to FDA breakthrough pathway reimbursement, whereas retail surveillance integrators face acute cost compression from Shenzhen module competition.
Supply Chain Analysis
300mm silicon wafer feedstock draws from Taiwan, South Korea, and Arizona fabrication complexes. Advanced packaging substrates hinge on ABF laminate supply from Japanese suppliers, while EUV lithography equipment remains concentrated in Dutch and Japanese vendor hands. Single-source vulnerability concentrates in Taiwan's foundry cluster, where 90 percent of leading-edge AI silicon capacity creates chokepoint exposure for automotive qualification timelines. Distribution runs through authorized distributor networks serving Tier 1 automotive suppliers, with direct foundry relationships reserved for top-five silicon vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI processor markets increasingly monetize through MLOps platform subscriptions and model optimization services, where recurring revenue layers expand faster than per-unit silicon margins. Hardware vendors capturing design wins now attach annual software maintenance contracts exceeding initial chip procurement value.
For Market Incumbents: Build compiler toolchain moats by unifying graph optimization stacks across Qualcomm, MediaTek, and Ambarella SDKs. Defensive moves center on securing multi-year foundry allocation agreements with TSMC and Samsung to guarantee 52-week supply continuity against startup competitors. Threat substitution from cloud-based inference demands embedding on-premise latency SLAs into platform bundles. Capacity addition in Arizona and Texas foundry clusters anchors geographic diversification against Taiwan chokepoint risk.
For New Entrants and Emerging Players: Pursue neuromorphic sensing fusion applications where Swiss and Dutch research consortia lack commercialization partners. White-space concentrates in sub-milliwatt always-on perception for drone navigation and predictive maintenance, segments underserved by CUDA-anchored incumbents. Target India's PLI-subsidized Bengaluru and Chennai packaging facilities for automotive-grade SiP production, leveraging Foxconn and Tata qualification pathways. Go-to-market angle emphasizes INT4-quantized accelerators for battery-operated smart surveillance cameras in Seoul and Shenzhen municipal deployments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom ASIC specialists with automotive OEM tape-out relationships over general-purpose GPU vendors facing cloud training substitution. Long-term viability across the projection horizon rests on functional-safety certification depth and secure enclave IP for EU AI Act compliance. Acquisition target archetype: fabless designers with pre-certified inference engines for medical imaging and industrial safety systems. Signal to watch is NHTSA autonomous vehicle validation protocol acceleration, which would compress automotive qualification cycles and favor incumbents with existing ASIL-D documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Allocation Security Agreement | Multi-year wafer commitments with TSMC anchor automotive qualification timelines for German OEMs. |
| Compiler Toolchain Unification | Graph optimization stack consolidation reduces ML engineer porting costs across Qualcomm and MediaTek SDKs. |
| EU AI Act Pre-Certification | Conformity assessment body signatures accelerate European market access for medical triage endpoints. |
| Neuromorphic Sensing Fusion Partnership | Event-based vision sensor integration enables sub-milliwatt perception for Swiss drone navigation applications. |
| India PLI Facility Qualification | Bengaluru and Chennai SiP production attracts Foxconn and Tata automotive-grade packaging investment. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with automotive platform engineers, medical device regulatory leads, foundry procurement managers, and smart factory operations directors; and secondary validation through SEC semiconductor filings, NHTSA autonomous vehicle validation protocols, EU AI Act conformity assessment documentation, and Taiwan semiconductor trade statistics. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, application, and technology segmentation dimensions.
Forecast inputs considered automotive inference demand trajectories, INT4 quantization adoption curves, and foundry capacity expansion announcements across the analysis window. Segmentation modeling captured ASIC, FPGA, embedded processor, and network processor architectures; automotive, healthcare, manufacturing, and retail end users; smart surveillance, predictive maintenance, real-time analytics, and facial recognition applications; plus computer vision, machine learning, natural language processing, and robotics technologies. CAGRs derived from regression analysis of historical qualification timelines and OEM platform refresh cycles, cross-referenced against EU AI Act implementation schedules and FDA breakthrough device pathway acceleration.
Sensitivities concentrate around export control enforcement on EUV lithography equipment, foundry customer concentration risk, and automotive OEM platform delay cascades. Forecasts reflect assumptions regarding Taiwan supply continuity and INT4 hardware maturation timelines. Cross-checking against IHS Markit vehicle production databases and SEMI capital equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Power Architecture Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Battery Monitoring IC Market