
 Global ARM Microcontrollers Market | 2026-2036
Global ARM Microcontrollers Market Size, Share, and Industry Trends Forecast 2026-2036
Global ARM Microcontrollers Market Analysis
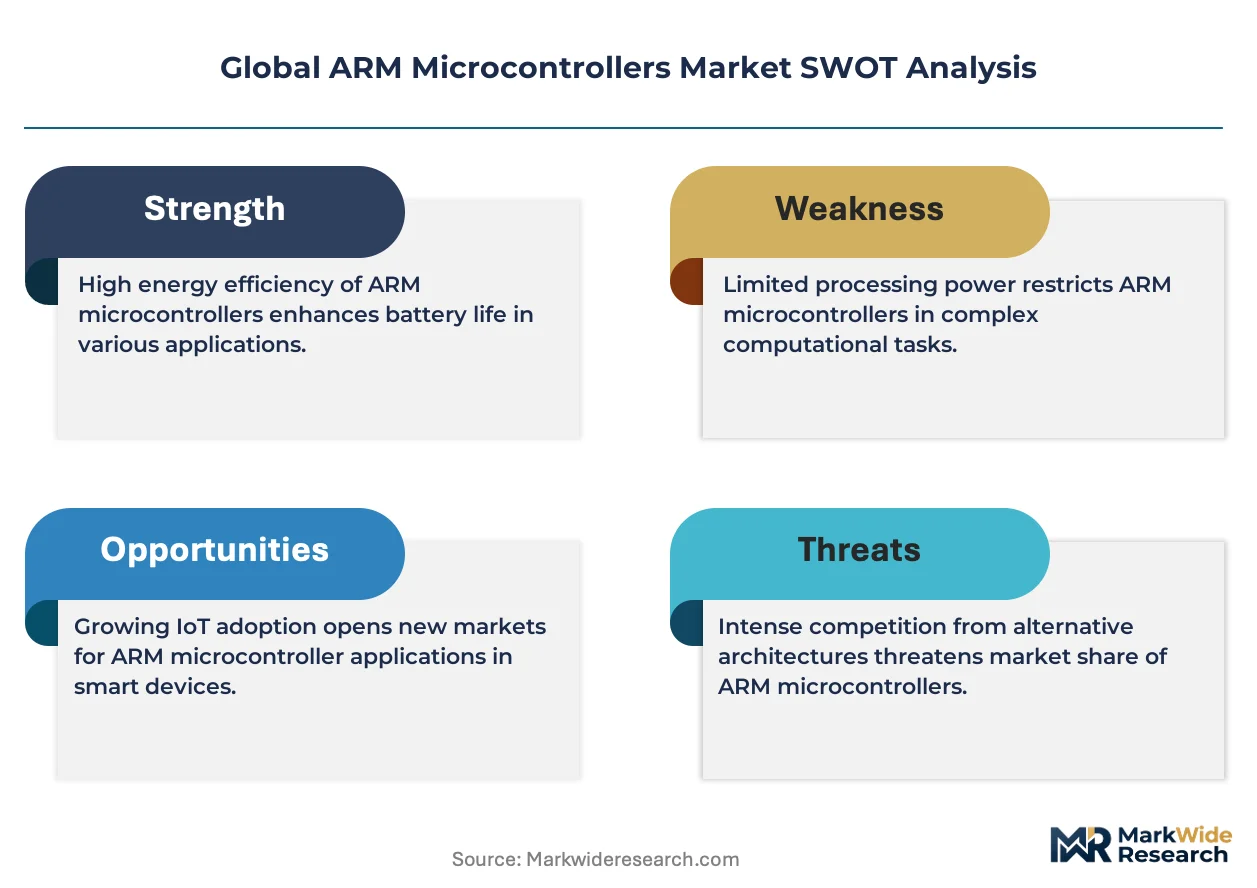
The gap between automotive-grade safety controllers and cost-optimized consumer chips is recalibrating procurement strategies across the ARM microcontroller value chain. NXP Semiconductors N.V. dominates automotive Cortex-R deployments with ASIL-D certified portfolios. Texas Instruments Incorporated anchors industrial automation through its Sitara and MSP430 ARM lines with extensive analog integration. STMicroelectronics N.V. leverages its STM32 ecosystem to sustain developer loyalty across low-power and high-performance tiers.
ARM microcontrollers are 32-bit and 64-bit reduced instruction set computing devices built on ARM Holdings processor architectures, operating at clock speeds from 24 MHz to over 1 GHz with flash memory densities spanning 32 KB to 2 MB. They execute real-time control, signal processing, and connectivity tasks in embedded systems where deterministic response and energy efficiency matter. Cortex-M Series devices lead unit shipments due to their balance of performance and die-size economics, while Cortex-R Series controllers command premium positioning in automotive and medical safety systems. Low-Power Microcontrollers represent the fastest-growing product type as battery-operated IoT endpoints multiply across consumer and industrial networks.
FCC certification requirements shape wireless-enabled ARM controller designs for US market entry, while REACH and RoHS directives in Europe restrict hazardous substances in semiconductor packaging and assembly processes. China's GB standards and MIIT regulations govern electromagnetic compatibility and network access for connected microcontroller applications. Stakeholders must monitor how the EU AI Act and emerging functional-safety mandates in automotive redefine certification burdens for edge-computing controllers.
Market Dynamics
Automotive electrification programs and ISO 26262 functional-safety mandates are compressing development cycles for Cortex-R certified controllers while fragmenting procurement across safety-grade and cost-optimized tiers.
Growth Catalysts
- EV Powertrain Electrification:Battery management systems and motor control units in Germany, China, and the US are pulling ASIL-D certified ARM controllers into high-volume automotive platforms.
- REACH and RoHS Directives:European hazardous-substance restrictions are accelerating lead-free packaging transitions that favor advanced ARM foundry processes with integrated environmental compliance.
- Shenzhen Electronics Corridor:System integrators in China's Pearl River Delta are consolidating embedded sourcing for industrial automation, creating concentrated demand pools for high-volume Cortex-M deployments.
Market Restraints
- Wafer Capacity Concentration:Advanced node production for automotive-grade microcontrollers clusters at Taiwan and South Korea foundries, exposing supply chains to single-point geographic risk.
- FCC Certification Burden:US market entry for wireless-enabled ARM controllers requires extensive electromagnetic testing that extends time-to-revenue by six to nine months for new designs.
- Legacy 8-bit Substitution Ceiling:Cost-sensitive appliance and toy segments in Southeast Asia continue sourcing 8051 and AVR architectures below the ARM Cortex-M0 price-performance crossover threshold.
Strategic Opportunities
- EU AI Act Edge-Computing Mandates:European requirements for transparent, auditable inference at the device level are opening certification-driven demand for secure enclave-equipped Cortex-M55 implementations.
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and testing are attracting ARM licensee packaging investments in Gujarat and Tamil Nadu corridors.
- Digital Twin Convergence:Pairing physics-modeled ARM controller behavior with cloud-based simulation environments is enabling pre-certified virtual prototyping that compresses automotive development timelines.
Industry Challenges
- Functional-Safety Engineering Scarcity:ASIL-D certification expertise resides at a handful of automotive Tier-1 suppliers in Germany and Japan, creating bidding wars for qualified validation engineers.
- Multi-Domain Integration Complexity:Combining real-time control, wireless connectivity, and machine learning inference on single-die ARM controllers is stretching verification methodologies beyond current tool capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ARM Microcontrollers Market |
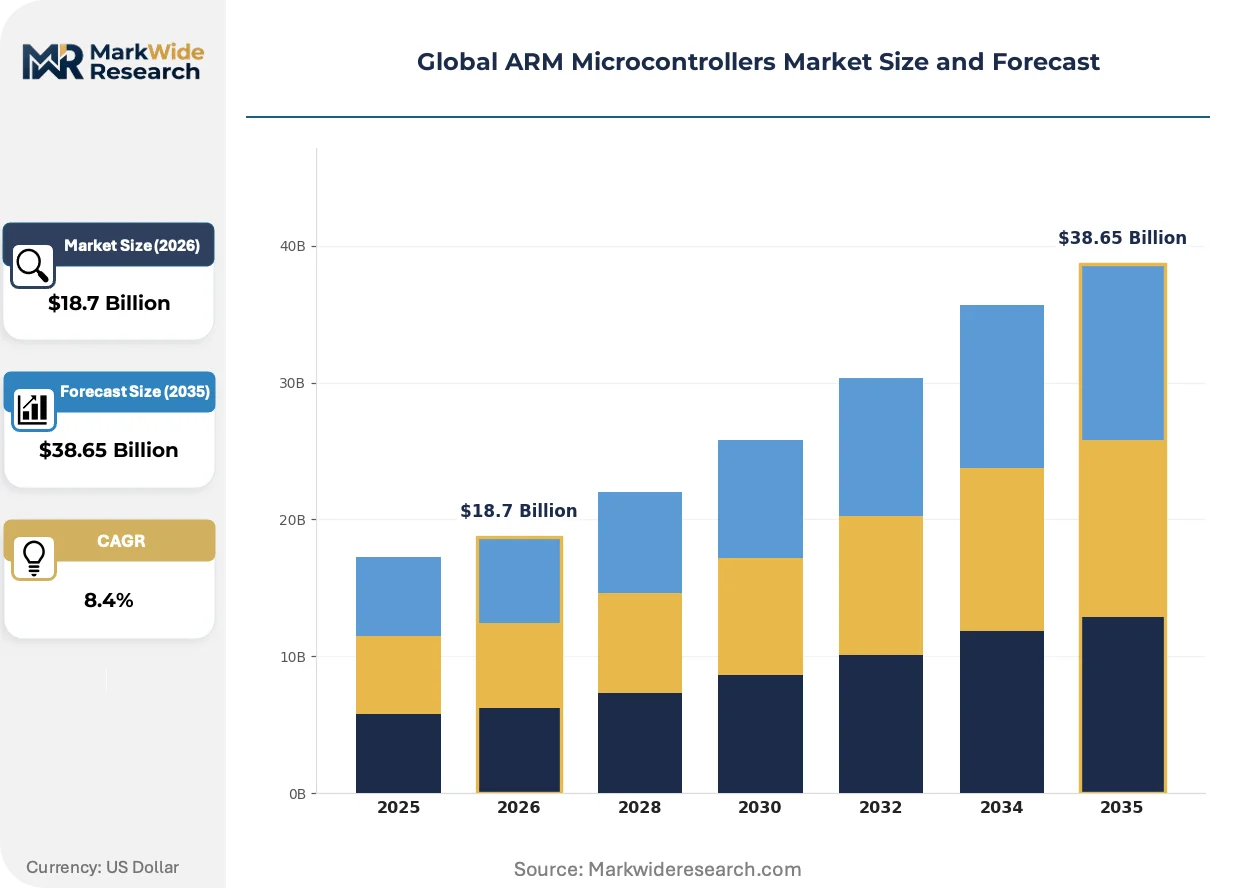
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Microcontrollers, High-Performance Microcontrollers, Low-Power Microcontrollers, Embedded Microcontrollers Application: Automotive Systems, Consumer Electronics, Industrial Automation, Medical Devices End User: OEMs, Aftermarket Manufacturers, System Integrators, Developers Technology: Cortex-M Series, Cortex-R Series, Cortex-A Series, Others |
| Companies Covered | Microchip Technology Incorporated, Renesas Electronics Corporation, Infineon Technologies AG, Holtek Semiconductor Inc., GigaDevice Semiconductor Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, ASR Microelectronics (Shanghai) Co., Ltd., STMicroelectronics N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ARM Microcontrollers Market Emerging Trajectories
Edge AI inference, automotive safety certification, and procurement model compression are actively restructuring how ARM microcontroller value is created and captured across the supply chain.
Neural processing unit (NPU) integration into Cortex-M55 and Cortex-M85 cores is rewriting the performance economics of voice recognition and vibration analysis at battery-powered endpoints. Industrial predictive maintenance OEMs in Germany and Japan are adopting these heterogeneous architectures to displace discrete DSP-plus-MCU board stacks. The result is die-area consolidation that collapses bill-of-materials counts while extending single-chip ASPs into premium tiers.
The EU AI Act's risk-based classification system for embedded inference engines is forcing ARM licensees to document training data provenance and model drift boundaries. Medical device manufacturers targeting European markets must now maintain post-market monitoring systems that trace algorithm updates through secure over-the-air pipelines. This regulatory architecture favors microcontroller vendors with pre-certified secure boot and encrypted firmware update hardware roots.
Automotive Tier-1 suppliers are consolidating microcontroller procurement through multi-year framework agreements that bundle volume commitments with joint development funding. Traditional distribution through Arrow and Avnet is losing share to direct foundry relationships and captive sourcing arms of major OEMs. This channel compression is most advanced in Germany's Baden-Württemberg automotive cluster, where Bosch and Continental have established dedicated ARM controller supply programs with NXP and Infineon.
Global ARM Microcontrollers Market Segmentation
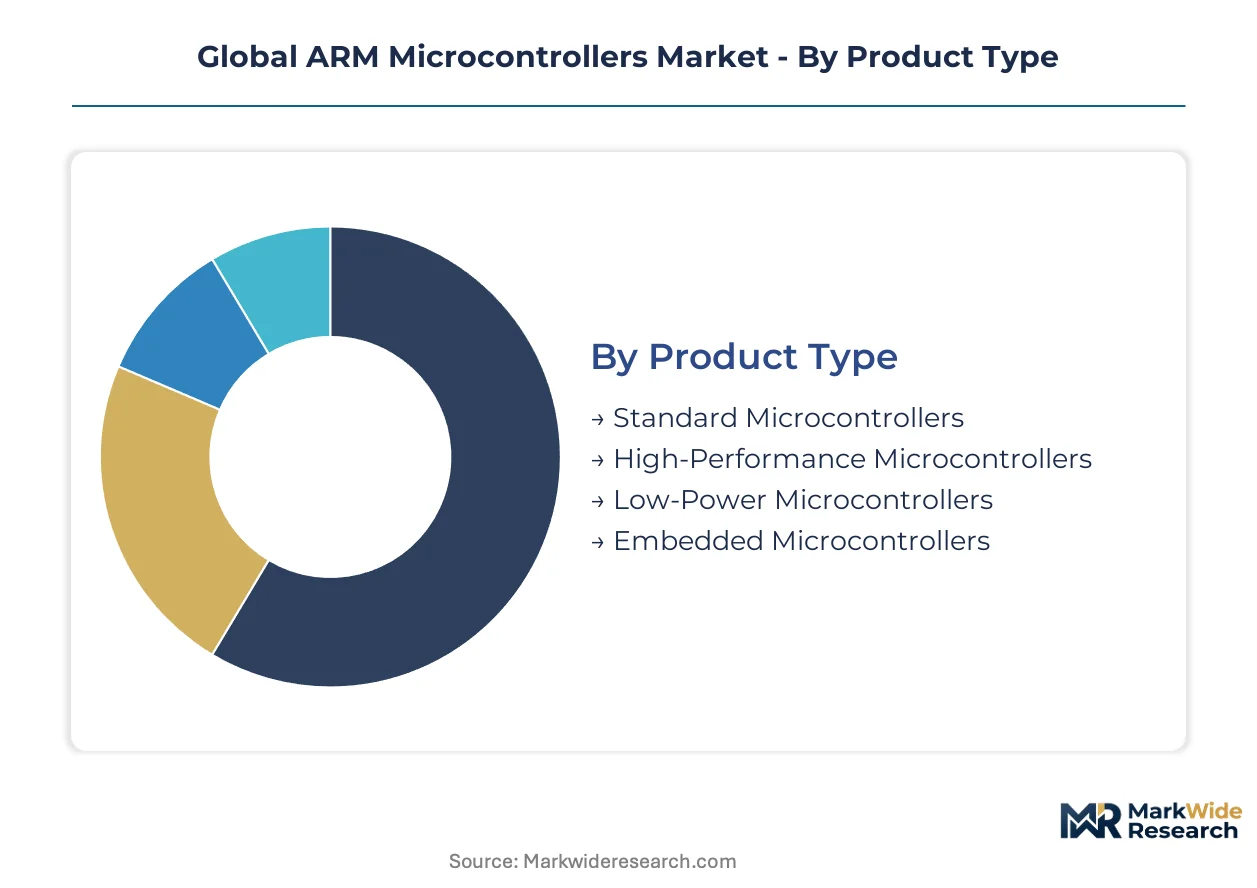
ARM microcontroller procurement fractures across performance tiers, safety certification grades, and integration complexity levels. Buyers optimize for die-size economics in high-volume consumer applications while paying premiums for deterministic response in automotive and medical safety systems.
Product Type:
Clock speed and power budgets differentiate how semiconductor fabs allocate wafer starts across ARM product families.
- Low-Power Microcontrollers:Sub-100 MHz operation with sub-mA sleep currents enables multi-year battery life in IoT endpoints. Shenzhen system integrators source these in volume for environmental sensors and wearable platforms where energy harvesting replaces wired power.
- High-Performance Microcontrollers:Cortex-M7 and M55 cores exceeding 400 MHz execute DSP and machine learning workloads without external accelerators. German industrial automation OEMs deploy these for real-time motor control and predictive maintenance algorithms.
- Standard Microcontrollers:Mid-range Cortex-M4 devices balance peripheral integration with cost targets for appliance and white-goods controllers.
- Embedded Microcontrollers:Application-specific variants with integrated RF transceivers or power management units reduce board-level component counts.
Low-Power Microcontrollers lead on scale; High-Performance Microcontrollers lead on momentum.
Application:
End-use certification burdens and volume economics pull ARM controller specifications in divergent directions.
- Automotive Systems:ASIL-D functional safety mandates govern battery management and powertrain control units. KBA certification requirements in Germany and NHTSA traceability rules in the US extend validation cycles but lock in multi-year supply agreements.
- Industrial Automation:Programmable logic controllers and robotic motor drives demand deterministic interrupt latency below 12 clock cycles. Japanese machine tool builders specify extended temperature grades for factory floor reliability.
- Consumer Electronics:Smart home devices and personal electronics prioritize BOM cost over absolute performance, sourcing Cortex-M0+ variants from high-volume Asian foundries.
- Medical Devices:FDA and MDR compliance for patient-connected equipment restricts component sourcing to qualified supplier lists with full traceability documentation.
Automotive Systems lead on scale; Industrial Automation leads on momentum.
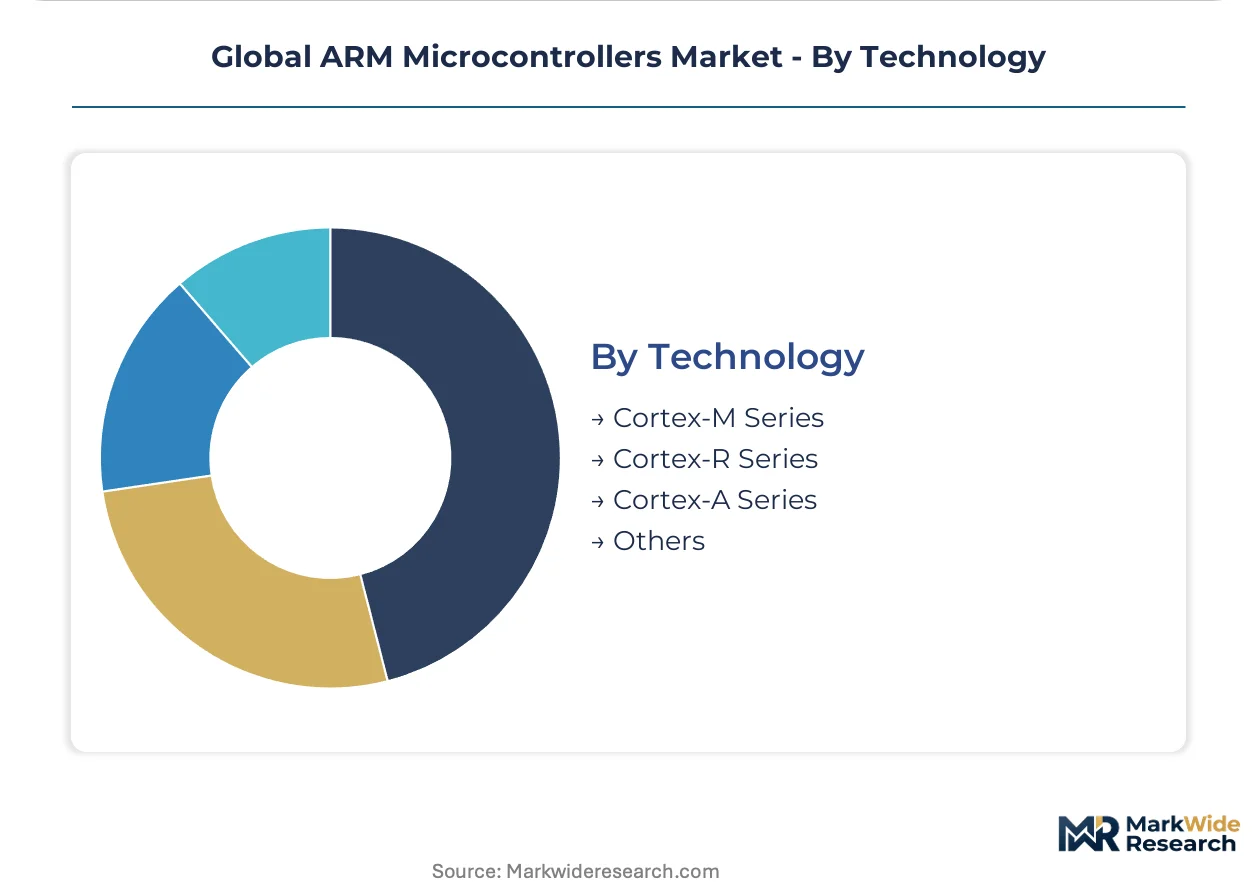
Technology:
Core architecture selection determines toolchain investment, software ecosystem access, and long-term vendor roadmaps.
- Cortex-M Series:Thumb-2 instruction set variants from M0+ to M85 span ultra-low-cost to machine-learning-capable implementations. The M4 and M7 cores dominate industrial motor control with hardware floating-point units.
- Cortex-R Series:Dual-core lockstep configurations with error-correcting memory satisfy ISO 26262 ASIL-D requirements for autonomous vehicle compute and electric powertrain management.
- Cortex-A Series:Application-class processors with memory management units run Linux and Android in human-machine interface panels and infotainment head units.
- Others:Legacy ARM7TDMI and ARM9 cores persist in long-lifecycle industrial equipment where requalification costs exceed silicon replacement savings.
Cortex-M Series leads on scale; Cortex-R Series leads on momentum.
End User:
Procurement authority and technical specification control vary sharply across buyer categories.
- OEMs:Automotive and industrial equipment builders define controller specifications through multi-year framework agreements with direct foundry allocation.
- System Integrators:Shenzhen-based automation specialists consolidate demand across multiple end-customers, negotiating volume pricing for standardized Cortex-M platforms.
- Developers:Individual engineers and small design houses evaluate parts through dev-kit ecosystems before influencing BOM decisions at production scale.
- Aftermarket Manufacturers:Replacement part builders reverse-engineer controller specifications for compatibility with legacy equipment fleets.
OEMs lead on scale; System Integrators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electrification programs pull ASIL-D certified controllers into high-volume production lines, while China's Shenzhen corridor concentrates sourcing for industrial automation platforms at vastly different certification tiers.
United States
EV powertrain electrification and battery management systems drive demand for automotive-grade ARM controllers. NHTSA traceability rules and FCC certification requirements for wireless-enabled designs extend validation timelines. Austin and Detroit automotive clusters host Tier-1 supplier engineering centers specifying Cortex-R deployments.
Germany
ISO 26262 functional-safety mandates govern autonomous vehicle compute and electric powertrain management. KBA certification requirements lock in multi-year supply agreements with qualified vendors. Baden-Württemberg's automotive cluster anchors Bosch and Continental procurement programs for safety-certified controllers.
China
Industrial automation and smart manufacturing platforms source high-volume embedded solutions from Shenzhen system integrators. MIIT regulations and GB standards govern electromagnetic compatibility for connected applications. The Pearl River Delta corridor concentrates Cortex-M procurement for environmental sensors and wearable platforms.
Japan
Machine tool builders specify extended temperature grades for factory floor reliability in robotic motor drives. METI industrial policy supports domestic semiconductor ecosystem development. Nagoya's Chubu region hosts precision manufacturing OEMs adopting heterogeneous ARM architectures for predictive maintenance.
India
Production-linked incentives for semiconductor assembly and testing attract ARM licensee packaging investments. BIS standards govern electronics imports while PLI schemes target Gujarat and Tamil Nadu corridors. Bangalore and Hyderabad engineering centers influence controller specifications for industrial automation deployments.
Global ARM Microcontrollers Market Vendor Landscape
Top-tier vendors anchor automotive safety certification, while mid-tier specialists compete on die-size economics for high-volume consumer applications. The vendor base stratifies across three tiers: integrated IDMs with captive foundry access, fabless licensees leveraging Asian foundry partnerships, and regional specialists serving cost-optimized segments. Strategic archetypes include safety-certification leaders, ecosystem platform builders, and high-volume commodity suppliers. Competitive moves center on multi-year framework agreements bundling volume commitments with joint development funding, plus NPU integration into heterogeneous architectures.
Within the integrated IDM tier, NXP Semiconductors N.V., Infineon Technologies AG, and Texas Instruments Incorporated exemplify divergent positioning strategies. NXP occupies a position representing automotive Cortex-R deployments with functional-safety certification depth. Infineon anchors European industrial and automotive controller supply through its German manufacturing heritage. Texas Instruments sits within the analog-integrated ARM controller segment, leveraging extensive mixed-signal integration for industrial automation platforms.
| Leading Market Players |
|---|
| Microchip Technology Incorporated |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Holtek Semiconductor Inc. |
| GigaDevice Semiconductor Inc. |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| ASR Microelectronics (Shanghai) Co., Ltd. |
| STMicroelectronics N.V. |
| Others |
Supply Flow & Price Mechanics
Automotive Tier-1 procurement concentration in Germany and Japan anchors contract-based long-term offtake agreements that bundle volume commitments with joint development funding, compressing spot-market liquidity for safety-certified controllers while elevating premium tiers.
Pricing Analysis
Bundled framework agreements dominate automotive procurement, while unbundled spot purchasing persists in Shenzhen's industrial automation corridor. Three-tier pricing structure across ASIL-D certified, industrial-grade, and consumer-optimized tiers reflects certification investment recovery and die-size economics. Pricing pressure stems from 8-bit architecture substitution ceilings in Southeast Asian appliance markets where 8051 and AVR cores undercut Cortex-M0 crossover points. Consumer electronics buyers exhibit highest price sensitivity, whereas medical device manufacturers prioritize qualified supplier list compliance over unit cost.
Supply Chain Analysis
ISO 26262 and ASIL-D qualification gating restricts automotive-grade controller supply to certified fabrication flows at Taiwan and South Korea foundries. Raw material dependencies span 300mm silicon wafers, advanced packaging substrates, and rare-earth elements for magnetic components. Single-source vulnerability concentrates at Taiwan Semiconductor Manufacturing nodes where automotive microcontroller production clusters. Distribution runs through direct foundry relationships and captive OEM sourcing arms, displacing traditional Arrow and Avnet channels in Germany's Baden-Württemberg cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's PLI scheme for semiconductor assembly offers 25-30% cost arbitrage against European packaging economics, creating geographic repositioning incentives for ARM licensees seeking tariff-advantaged supply corridors.
For Market Incumbents: Anchor ASIL-D certification depth against emerging fabless competitors from China by accelerating heterogeneous NPU integration into Cortex-M55 and M85 cores. Defensive moves require captive foundry allocation agreements at Taiwan and South Korea nodes, plus backward integration into advanced packaging at Gujarat and Tamil Nadu corridors under India's production-linked incentive schemes. Channel control through multi-year framework agreements with Bosch and Continental procurement programs locks out secondary distributors. For New Entrants and Emerging Players: Begin with environmental sensor and wearable platforms in Shenzhen's Pearl River Delta corridor where system integrators consolidate high-volume Cortex-M demand without safety certification barriers. White-space targets include battery-operated IoT endpoints with energy harvesting requirements and industrial predictive maintenance OEMs seeking die-area consolidation. Go-to-market angles should emphasize developer ecosystem tooling and dev-kit availability to influence BOM decisions before production scale. For Investors and Strategic Acquirers: Automotive Tier-1 suppliers are the most active acquirer in this space, seeking secure boot and encrypted firmware update capabilities for EU AI Act compliance. Long-term viability favors fabless licensees with heterogeneous architecture roadmaps and pre-certified secure enclave implementations. The signal to watch is consolidation of microcontroller procurement through direct foundry relationships, indicating channel compression maturity and pricing power capture by integrated device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | NXP and Infineon lock in multi-year supply agreements with KBA-qualified vendors in Germany. |
| Heterogeneous NPU Integration | Cortex-M55 implementations displace discrete DSP-plus-MCU board stacks in Japanese predictive maintenance. |
| Direct Foundry Relationship | Bosch and Continental bypass Arrow and Avnet through captive sourcing arms in Baden-Württemberg. |
| India PLI Packaging Investment | ARM licensees establish assembly and testing corridors in Gujarat and Tamil Nadu for tariff advantage. |
| Secure Enclave Pre-Certification | EU AI Act compliance favors vendors with hardware roots for encrypted firmware update pipelines. |
Methodological Framework
Bottom-up automotive and industrial automation modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, platform engineers at German automotive OEMs, Shenzhen system integrators, and biomedical equipment manufacturers combined with secondary validation against SEC 10-K filings, MIIT electromagnetic compatibility registrations, and KBA certification databases. Triangulation across bottom-up segment builds and top-down wafer start allocations ensures consistency.
Input-output matrices map Cortex-M, Cortex-R, and Cortex-A unit shipments through application tiers and certification grades across the projection horizon. Segmentation dimensions include product type, application vertical, core architecture, and end-user procurement authority. CAGRs derive from regression analysis of historical semiconductor content per vehicle and industrial automation platform deployment rates. Forecast inputs incorporate EV powertrain electrification timelines and REACH packaging transition schedules.
Caveats apply where Taiwan foundry capacity constraints or EU AI Act implementation delays could materially shift the outlook. Forecasts reflect documented assumptions regarding automotive electrification program cadence and ISO 26262 certification pipeline throughput. A model refresh is warranted upon material change in ASIL-D qualified engineering capacity or MIIT regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Nano Chip Market