
 Asia Pacific Data Center Processor Market | 2026-2036
Asia Pacific Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Data Center Processor Market Insights
Software-defined networking feature licensing is rebalancing procurement economics away from raw silicon toward bundled compute-network packages. NVIDIA Corporation leverages its CUDA ecosystem to anchor premium positioning in AI training clusters. Intel Corporation sustains manufacturing scale through captive foundry relationships and x86 architecture dominance in enterprise cloud. Huawei Technologies navigates export control complexity by deepening in-house production of Ascend AI chips for domestic Chinese deployment.
Data center processors are integrated circuits engineered for sustained high-throughput computation in thermally constrained server environments, typically fabricated on sub-7nm process nodes with power envelopes exceeding 200 watts per socket. Their primary purpose is to execute parallelized workloads—training neural networks, querying distributed databases, rendering virtualized infrastructure—at latency and throughput thresholds unreachable by consumer-grade silicon. GPU segments command the fastest expansion trajectory as generative AI training and inference workloads displace general-purpose CPU cycles in hyperscaler fleets. CPU categories retain structural importance in relational database and legacy enterprise application hosting, where single-thread performance and software compatibility preserve installed-base value. ASIC deployments concentrate among telecommunications end users seeking power-optimized 5G baseband and routing acceleration at national carrier scale.
China's MIIT enforces domestic semiconductor content benchmarks through GB standards and dual carbon goals that constrain data center power density, directly shaping processor efficiency requirements. India's BIS certification and PLI scheme for electronics manufacturing condition market access on local assembly and testing infrastructure investment. Japan's METI subsidizes advanced packaging research through JIS-aligned consortia, influencing regional supply chain geography for chiplet-based designs. Stakeholders must weigh sovereign technology mandates against the concentration risk of Taiwan Semiconductor Manufacturing Company's leading-edge foundry output when calibrating procurement and partnership strategies.
Market Dynamics
AI inference workloads across Southeast Asian cloud operators are redistributing processor procurement toward GPU-heavy configurations, while sovereign semiconductor mandates in China and India reconfigure supply chain geography away from Taiwan-centric foundry dependence.
Growth Catalysts
- China's MIIT semiconductor self-sufficiency directives:Domestic content benchmarks through GB standards redirect capital toward in-house Ascend AI chip production, insulating hyperscaler deployment from export control volatility.
- India's PLI scheme for electronics manufacturing:State-level IT policies in Maharashtra and Telangana attract hyperscaler buildouts, conditioning market access on local assembly and testing infrastructure investment.
- GPU acceleration for generative AI training:Cloud computing operators multiply processor procurement as neural network training cycles displace general-purpose CPU workloads in regional hyperscaler fleets.
Market Restraints
- Leading-edge foundry concentration:Taiwan Semiconductor Manufacturing Company's dominance in sub-7nm fabrication creates single-point vulnerability for advanced AI training silicon procurement across the region.
- Dual carbon goals constraining power density:China's MEE enforcement of data center efficiency standards limits thermal envelope expansion, compressing socket power scaling headroom for high-throughput processors.
- Legacy x86 software compatibility:Enterprise relational database hosting preserves installed-base CPU value, slowing heterogeneous architecture migration despite GPU performance advantages.
Strategic Opportunities
- Underpenetrated Indian data center corridors:State-level IT policies in Karnataka and Tamil Nadu offer greenfield buildout potential for domestic foundry-linked processor deployment.
- Chiplet-based design adoption:Japan's METI subsidization of advanced packaging research through JIS-aligned consortia creates regional supply chain alternatives to monolithic die fabrication.
- 5G baseband ASIC acceleration:Telecommunications end users at national carrier scale seek power-optimized routing silicon, opening specialized procurement channels distinct from general-purpose cloud compute.
Industry Challenges
- Advanced packaging talent scarcity:Chiplet integration expertise concentrates in Japanese and Taiwanese engineering pools, constraining domestic capability buildout in Indian and Southeast Asian assembly operations.
- Export control compliance timeline complexity:Multinational hyperscalers face divergent national security review processes across Chinese, Indian, and ASEAN regulatory frameworks when deploying AI training clusters.
- Thermal design power escalation:200+ watt socket envelopes demand liquid cooling infrastructure retrofitting, compressing depreciation schedules for legacy air-cooled facilities across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Data Center Processor Market |
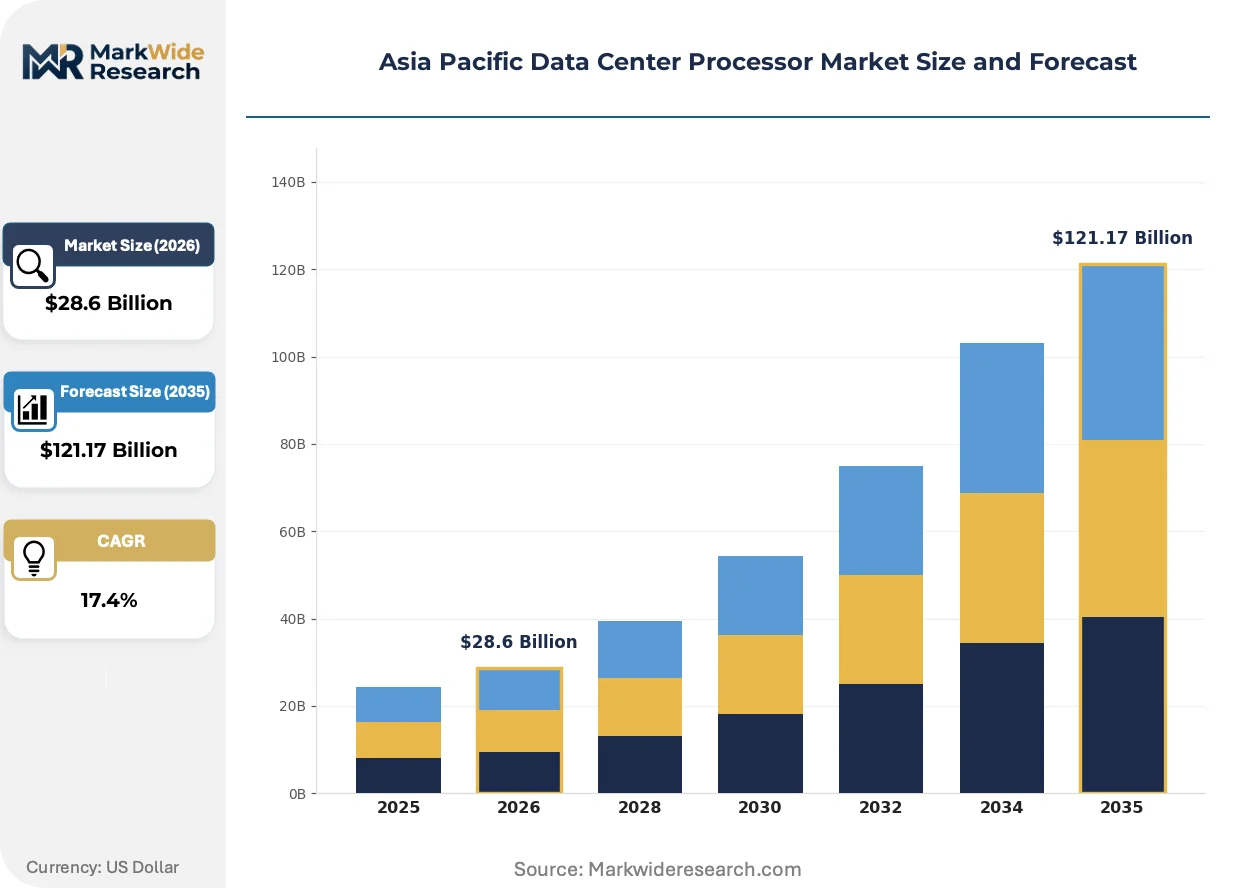
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPU, GPU, FPGA, ASIC Application: Cloud Computing, Big Data, AI, High-Performance Computing End User: Telecommunications, Government, BFSI, E-Commerce Deployment Model: On-Premises, Colocation, Managed Service, Hybrid Cloud |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, Huawei Technologies, Qualcomm, Ampere Computing, Arm Limited, Broadcom, Taiwan Semiconductor Manufacturing Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Data Center Processor Market Trends and Innovations
Software-defined networking feature licensing is rebalancing procurement economics toward bundled compute-network packages, while sovereign technology mandates accelerate domestic foundry investment across the region's major economies.
Chiplet-based processor architectures are absorbing heterogeneous integration complexity by disaggregating memory controllers, I/O dies, and compute tiles into separately optimized silicon pieces. Hyperscalers in Singapore and Australia are piloting these designs for AI inference workloads where modular upgrade paths outweigh monolithic die yield advantages. This packaging approach is absorbing capital expenditure that previously flowed toward leading-edge node migration, compressing the effective cost-per-transistor curve for regional cloud operators.
China's MIIT enforcement of GB standards for domestic semiconductor content is mandating local foundry utilization percentages in government-affiliated data center procurement. Industrial consequence includes accelerated tape-out of Ascend AI chips at domestic fabs, even at process node penalties versus Taiwan-sourced alternatives. State-owned cloud operators are most affected, accepting performance trade-offs to satisfy sovereign technology mandates while private hyperscalers maintain dual-source strategies.
Hyperscaler procurement consolidation is compressing vendor negotiation cycles from annual frameworks to quarterly volume commitments with price renegotiation triggers. Distributor and systems integrator margins face compression as direct OEM relationships displace channel-heavy procurement in India's Maharashtra corridor. This behavioral shift is most visible among Chinese internet platform operators consolidating training cluster purchases to capture volume-tiered pricing from captive foundry partnerships.
Asia Pacific Data Center Processor Market Segmentation
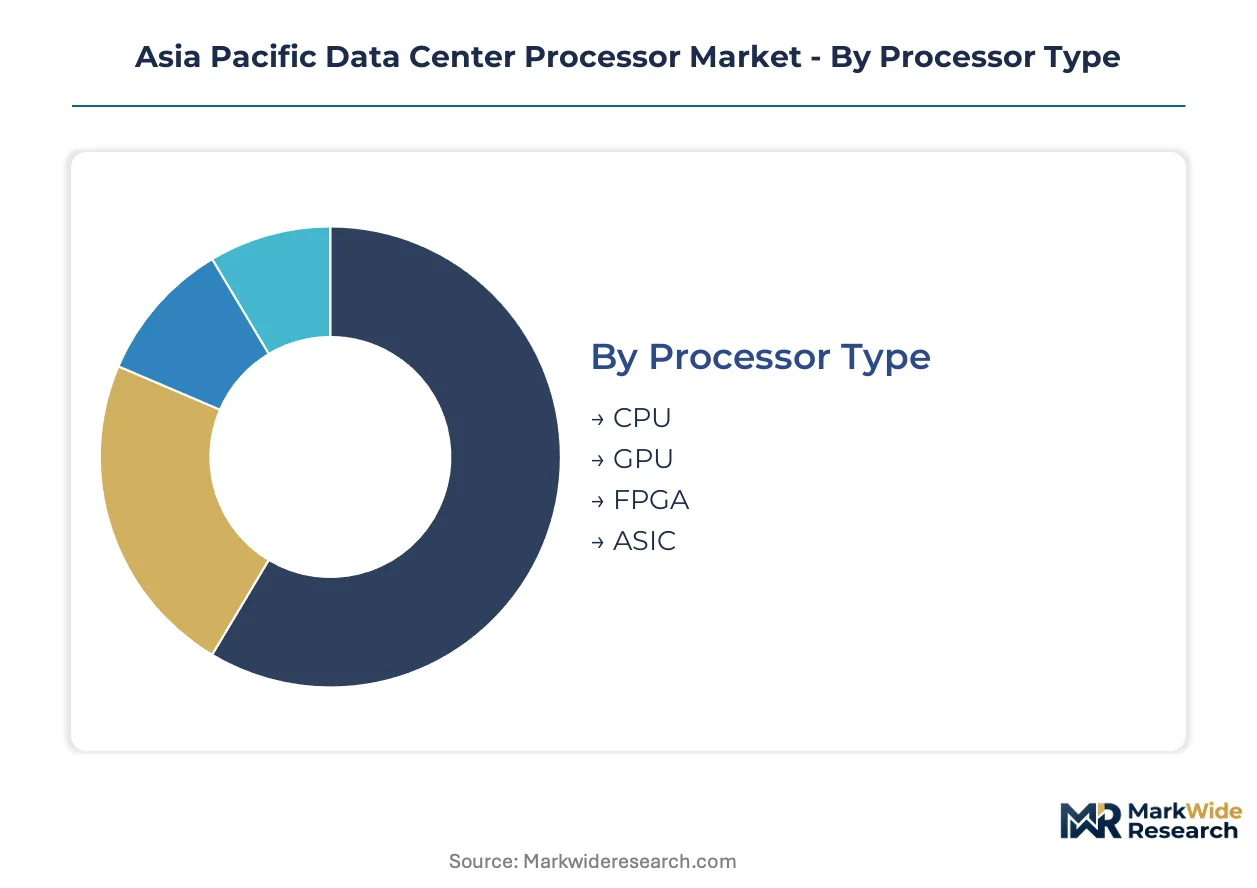
Processor segmentation in the Asia Pacific data center market reveals how workload specialization is fragmenting procurement strategies across hyperscaler and enterprise deployments. Technical architecture choices now cascade through cooling infrastructure, software licensing, and sovereign compliance requirements.
Processor Type:
Silicon architecture determines thermal envelope, software ecosystem lock-in, and foundry sourcing flexibility for regional operators.
- CPU:x86 and ARM-based designs handle relational database workloads and legacy enterprise applications where single-thread performance preserves software compatibility. Maharashtra and Telangana data center corridors prioritize CPU-heavy configurations for BFSI and government hosting where certification requirements favor established instruction sets.
- GPU:Massively parallel architectures from NVIDIA and domestic Chinese suppliers execute neural network training and inference at throughput levels unreachable by general-purpose silicon. Cloud operators across Southeast Asia are expanding GPU procurement fastest as generative AI workloads displace CPU cycles in regional hyperscaler fleets.
- FPGA:Reconfigurable logic devices offer workload-specific acceleration with post-deployment flexibility for protocol processing and encryption offloading.
- ASIC:Application-specific designs deliver optimal power efficiency for fixed-function tasks including 5G baseband processing at national carrier scale.
GPU leads on momentum; CPU leads on installed base scale.
Application:
Workload category shapes socket configuration, memory hierarchy investment, and network bandwidth provisioning.
- Cloud Computing:Virtualized infrastructure hosting demands balanced compute-memory ratios with emphasis on core density per rack unit. Indian PLI-linked hyperscaler buildouts in Karnataka and Tamil Nadu prioritize cloud-optimized processors with local assembly certification.
- AI:Training and inference pipelines require high-bandwidth memory integration and tensor acceleration units. Chinese MIIT domestic content benchmarks redirect AI processor procurement toward in-house Ascend chips even at node penalties versus Taiwan-sourced alternatives.
- Big Data:Distributed analytics frameworks stress memory bandwidth and I/O throughput over raw compute frequency.
- High-Performance Computing:Scientific simulation workloads exploit tightly coupled interconnects and specialized floating-point units.
AI climbs the fastest; Cloud Computing holds the broadest addressable base.
End User:
Customer vertical determines security certification requirements, procurement cycle length, and sovereign technology compliance intensity.
- Telecommunications:National carriers in Japan and South Korea deploy power-optimized silicon for 5G core and edge aggregation with METI-subsidized packaging research influencing supply chain geography.
- Government:State-affiliated data centers in China face MIIT GB standard enforcement mandating domestic foundry utilization percentages, accepting performance trade-offs for sovereign technology compliance.
- BFSI:Financial services operators in Singapore and Australia emphasize transactional latency and disaster recovery redundancy over raw throughput.
- E-Commerce:Platform operators consolidate training cluster purchases to capture volume-tiered pricing from captive foundry partnerships.
Government leads on compliance-driven procurement; E-Commerce leads on volume consolidation.
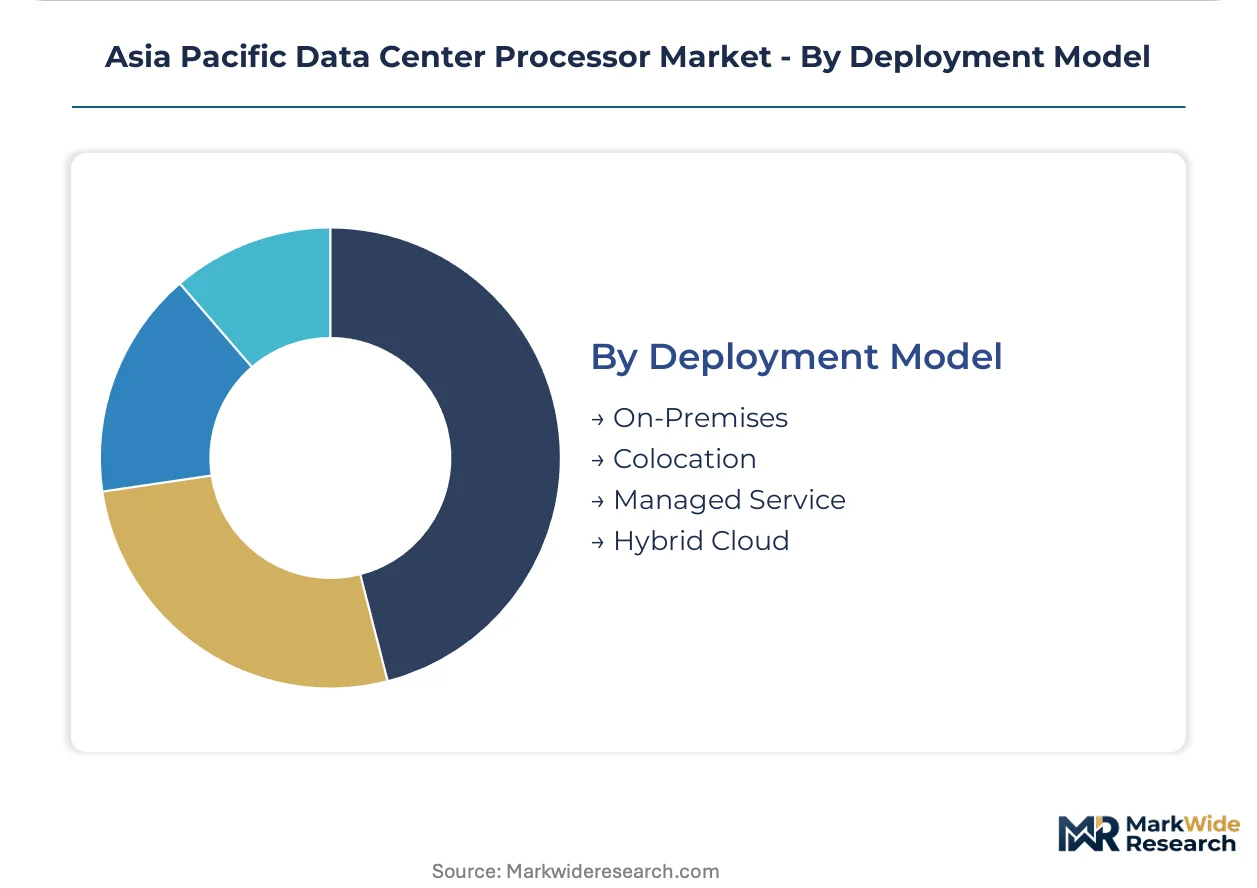
Deployment Model:
Infrastructure ownership structure dictates depreciation schedules, cooling retrofit obligations, and processor upgrade flexibility.
- On-Premises:Enterprise-owned facilities in Japan and Australia retain legacy air-cooled designs, compressing socket power scaling headroom as 200+ watt thermal envelopes demand liquid cooling infrastructure investment.
- Colocation:Third-party data center operators in India's Maharashtra corridor offer standardized power densities, constraining heterogeneous processor deployment for tenants.
- Managed Service:Outsourced infrastructure providers absorb hardware refresh cycles, shifting technology risk from end-user to operator.
- Hybrid Cloud:Mixed ownership models fragment processor procurement across on-premise legacy estates and cloud-bursting capacity, complicating software licensing and workload portability.
Colocation leads on facility scale; On-Premises faces the steepest retrofit pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT directives and India's PLI scheme are diverging procurement patterns across the Asia Pacific, with domestic content mandates reshaping foundry relationships faster in Beijing than in Mumbai.
China
State-owned cloud operators are scaling Ascend AI chip deployments under MIIT GB standards, accepting node penalties to satisfy sovereign technology mandates. The dual carbon goals enforced by MEE compress thermal envelope expansion, limiting socket power scaling in government-affiliated facilities. Yangtze River Delta clusters around Shanghai and Hangzhou absorb the bulk of domestic foundry-linked processor procurement.
India
Hyperscaler buildouts in Maharashtra and Telangana corridors are accelerating processor procurement as BFSI and e-commerce operators expand cloud infrastructure. BIS certification requirements and PLI scheme incentives condition market access on local assembly and testing infrastructure investment. Karnataka and Tamil Nadu data center corridors offer greenfield deployment potential for domestic foundry-linked capacity.
Japan
METI subsidization of advanced packaging research through JIS-aligned consortia is redirecting capital toward chiplet-based design alternatives. National carriers deploy power-optimized silicon for 5G core infrastructure, with procurement influenced by regional supply chain geography. Kanto and Kansai industrial zones concentrate engineering expertise for heterogeneous integration.
South Korea
Memory-integrated processor architectures dominate hyperscaler procurement as cloud operators seek high-bandwidth configurations for AI inference workloads. National semiconductor subsidies accelerate domestic foundry capacity expansion beyond memory-centric legacy positioning. Seoul Capital Area and Busan-Ulsan corridors anchor advanced packaging and testing infrastructure.
Singapore
Hyperscalers are piloting chiplet-based processor designs for AI inference workloads where modular upgrade paths outweigh monolithic die yield advantages. State-level data center policies attract regional cloud computing headquarters, concentrating procurement decision-making authority. The city-state's advanced logistics infrastructure supports rapid deployment cycles for heterogeneous compute configurations.
Asia Pacific Data Center Processor Market Competitive Landscape
Top-tier vendors anchor premium AI training silicon, while mid-tier specialists capture sovereign-compliant procurement channels. The vendor base stratifies across CUDA-ecosystem incumbents, x86 architecture incumbents, and domestic Chinese suppliers navigating export control complexity. Three archetypes dominate: ecosystem-locked premium players, manufacturing-scale generalists, and sovereign-mandate domestic suppliers. Competitive moves concentrate on captive foundry partnerships and software-defined networking feature bundling.
Within the ecosystem-locked tier, NVIDIA Corporation and Intel Corporation occupy positions reflecting divergent strategic bets on AI training versus enterprise cloud retention. NVIDIA leverages CUDA ecosystem density to anchor premium positioning in regional hyperscaler procurement. Intel sustains manufacturing scale through captive foundry relationships and x86 dominance in legacy enterprise hosting. Huawei Technologies exemplifies the sovereign-mandate archetype, deepening in-house Ascend production for domestic Chinese deployment under MIIT content benchmarks.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices |
| Huawei Technologies |
| Qualcomm |
| Ampere Computing |
| Arm Limited |
| Broadcom |
| Taiwan Semiconductor Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
Sub-7nm process node migration simultaneously compresses die yields and concentrates foundry bargaining power, reshaping procurement economics as hyperscalers absorb node-premium costs while domestic Chinese operators trade performance for sovereign sourcing flexibility.
Pricing Analysis
Capacity additions in South Korea and domestic Chinese foundries are reshaping price floors for mature-node processors while Taiwan-sourced leading-edge silicon maintains premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal envelope and software ecosystem lock-in, with NVIDIA's CUDA-anchored training clusters commanding the highest tier. Cost compression in mid-range CPU sockets is intensifying because Intel's captive foundry relationships enable aggressive volume pricing for enterprise cloud retention. E-commerce platform operators in India demonstrate the sharpest price sensitivity, while government-affiliated Chinese data centers accept node penalties to satisfy MIIT domestic content benchmarks.
Supply Chain Analysis
GB standards certification and BIS compliance requirements gate market access, forcing procurement officers to maintain dual-qualified supplier rosters across Taiwan, South Korea, and domestic Chinese foundries. Advanced packaging capacity draws from Japanese METI-subsidized consortia and Taiwanese engineering pools, creating chokepoint vulnerability for chiplet-based designs. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing Company's sub-7nm fabrication, where export control restrictions compound geographic risk. Distribution runs through direct OEM relationships displacing channel-heavy procurement in India's Maharashtra corridor, compressing systems integrator margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific data center processor market functions as a stable compounder, with AI inference workload multiplication across Southeast Asian cloud operators providing durable demand visibility regardless of cyclical enterprise IT spending fluctuations.
For Market Incumbents: Hedge against foundry concentration risk by diversifying tape-out partnerships across South Korean and domestic Chinese facilities, while defending x86 enterprise installed base through software-defined networking feature bundling that raises switching costs for relational database workloads. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for domestic assembly and testing specialists to capture hyperscaler procurement conditioned on local certification. Target Karnataka and Tamil Nadu greenfield corridors with chiplet packaging expertise, leveraging JIS-aligned consortia knowledge transfer to differentiate from established monolithic die suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among sovereign-compliant domestic Chinese suppliers with captive Ascend production and state-owned cloud operator offtake agreements. Monitor MIIT enforcement intensity as the inflection indicator for performance-trade-off acceptance rates in government-affiliated procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Partnership | Intel's manufacturing scale preserves x86 pricing power against ARM-based challengers in enterprise cloud. |
| Software Ecosystem Lock-in | NVIDIA's CUDA density anchors premium positioning for AI training clusters across Southeast Asian hyperscalers. |
| Domestic Content Compliance | Huawei's Ascend production satisfies MIIT GB standards while insulating from export control volatility. |
| Advanced Packaging Investment | Japan's METI-subsidized consortia create regional alternatives to Taiwan-centric chiplet integration. |
| Direct Procurement Consolidation | Chinese internet platforms capture volume-tiered pricing through quarterly renegotiation frameworks. |
Research Methodology
Multiple input streams — hyperscaler capex disclosures, foundry utilization reports, and regulatory filing databases — were reconciled to construct segment-level demand estimates. Primary interviews with cloud infrastructure procurement officers, semiconductor foundry account managers, and data center facility engineers were validated against secondary sources including SEC filings, MIIT policy circulars, and PLI scheme implementation records. Bottom-up socket deployment counts and top-down foundry revenue attribution were triangulated to resolve discrepancies.
Data-stream reconciliation across processor architecture, application workload, and end-user vertical dimensions informed the analytical framework over the projection horizon. CAGRs were derived from trend-line extrapolation of hyperscaler fleet expansion rates, adjusted for sovereign procurement mandate phase-in schedules and thermal envelope constraints under China's dual carbon goals. Foundry capacity buildout timelines and advanced packaging yield curves served as industry-specific forecast inputs.
Revisions become necessary when export control restriction scope expands, domestic foundry yield trajectories diverge from baseline assumptions, or sovereign content benchmark enforcement intensifies beyond modeled thresholds. A model refresh is warranted upon material change in Taiwan Strait logistics reliability or MIIT GB standards revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Coprocessor Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
NFC Chips Market