
 Accelerated Processing Unit (APU) Market | 2026-2036
Accelerated Processing Unit (APU) Market Size, Share, and Industry Trends Forecast 2026-2036
Accelerated Processing Unit (APU) Market Analysis
Enterprise data center procurement is rotating toward hybrid-cloud deployments that favor tightly coupled compute-graphics silicon. Advanced Micro Devices anchors the x86-integrated segment through Zen-and-RDNA convergence, while NVIDIA dominates discrete GPU-CPU combinations for AI training workloads. Intel Corporation competes aggressively with its Core Ultra architecture, leveraging Foveros packaging to sustain manufacturing relevance against fabless rivals.
An Accelerated Processing Unit fuses general-purpose CPU cores with specialized graphics or AI accelerator engines on a single die or multi-chip package, typically manufactured at 5nm to 3nm process nodes with high-bandwidth memory interfaces. Its primary purpose is eliminating data movement bottlenecks between discrete processors in latency-sensitive workloads. SoC integration captures the broadest volume as mobile and automotive buyers demand complete system-miniaturization, while discrete technology commands premium positioning in hyperscaler AI clusters where thermal headroom permits separate socketed components. FPGA-based APUs occupy a narrow but defensible niche in embedded systems requiring field-reconfigurable logic.
The US FCC and FDA shape demand through emissions and medical-device compute standards, while EPA energy-efficiency thresholds push OEMs toward integrated rather than discrete configurations. China's MIIT and SAMR enforce domestic semiconductor certification that limits foreign APU access to government and telecom procurement. Stakeholders must monitor how export control frameworks from Washington and Beijing reshape foundry access for advanced-node designs before committing to long-term architecture roadmaps.
Market Dynamics
Foundry access concentration at Taiwan's leading-edge nodes is forcing APU designers toward multi-chiplet packaging strategies that decouple compute and I/O dies. This structural dependency on advanced packaging capacity is reshaping how vendors architect their product roadmaps and secure manufacturing commitments.
Growth Catalysts
- Gaming console unified architecture migration:Console manufacturers are consolidating CPU-GPU silicon onto single dies to reduce thermal envelopes and bill-of-materials complexity. This end-use vertical now accounts for substantial APU procurement volume.
- China's MIIT semiconductor self-sufficiency mandates:Domestic certification requirements under GB standards and SAMR procurement rules are accelerating indigenous APU design capabilities for government and telecom applications.
- Hyperscaler AI inference densification:Cloud operators are deploying tightly coupled CPU-GPU packages to minimize memory latency in recommendation and generative inference workloads.
Market Restraints
- CoWoS packaging bottleneck:Advanced 2.5D interposer capacity at Taiwan foundries remains constrained, limiting high-bandwidth APU output regardless of front-end wafer availability.
- EUV lithography equipment access restrictions:Export control frameworks from Washington are tightening foundry access for sub-5nm designs, compressing architecture roadmaps for China-based designers.
- High-bandwidth memory supply concentration:HBM3 and HBM3E supply concentrates among three Korean suppliers, creating input cost volatility for premium APU configurations.
Strategic Opportunities
- Automotive zonal compute architectures:Tier-1 suppliers are specifying fused CPU-GPU silicon for cabin infotainment and ADAS sensor fusion, opening a new procurement vertical with decade-long design cycles.
- India's PLI scheme for semiconductor assembly:Domestic packaging incentives are attracting OSAT investment that could diversify backend capacity for mid-range APU variants.
- FPGA-APU hybrid convergence:Field-programmable logic integrated with fixed-function accelerators is capturing embedded defense and industrial automation applications requiring post-deployment reconfigurability.
Industry Challenges
- 3nm design-technology co-optimization complexity:Physical design teams face escalating tape-out costs and verification cycles as transistor density scaling slows.
- Cross-border IP licensing fragmentation:Arm architecture licenses and RISC-V patent pools are creating negotiation friction for new APU entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accelerated Processing Unit (APU) Market |
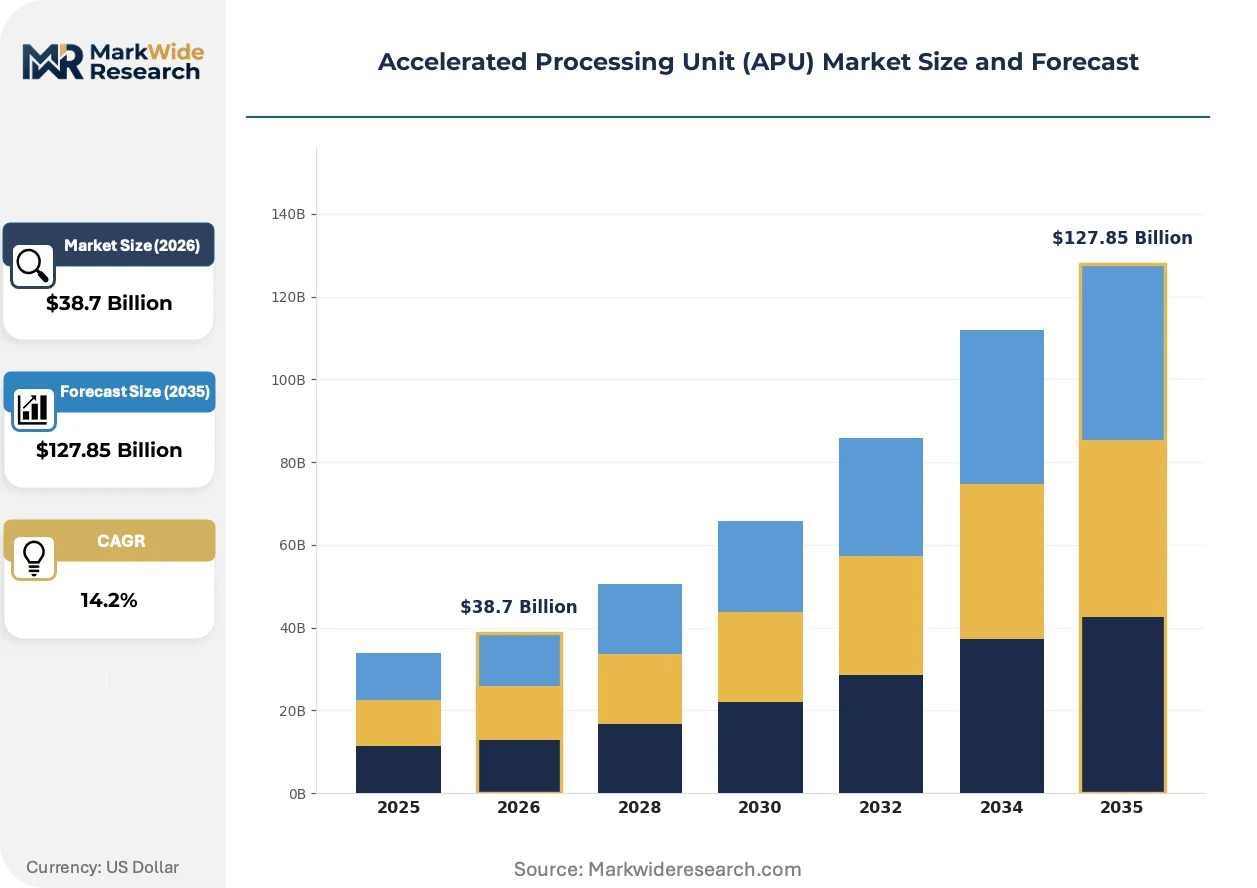
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPU, FPGA, ASIC, SoC Application: Gaming, Data Analytics, Machine Learning, Embedded Systems Technology: Integrated, Discrete, Hybrid, Cloud-Based End User: Consumer Electronics, Enterprises, Automotive, Industrial |
| Companies Covered | Arm Limited, Broadcom Corporation, Advanced Micro Devices, Inc., IBM Corporation, NXP Semiconductors, Intel Corporation, Qualcomm Technologies, Inc., Marvell Technologies, Inc., NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accelerated Processing Unit (APU) Market Emerging Trajectories
Chiplet-based disaggregation is fundamentally altering how APU vendors partition functionality across process nodes. This architectural pivot enables cost optimization but introduces new verification and thermal management complexities.
Monolithic die integration is supplanting traditional CPU-GPU discrete configurations in mainstream gaming and mobile compute segments. Valve Corporation and Sony Interactive Entertainment have committed to unified APU architectures for next-generation console refreshes. This technology shift is compressing motherboard real estate requirements and reducing system power budgets by eliminating inter-socket signaling.
The EPA's updated ENERGY STAR computer specifications are tightening idle and active power thresholds for desktop and mobile systems. OEMs are responding by specifying integrated rather than discrete graphics for volume SKUs. This regulatory pressure is most acute in North American and European enterprise PC procurement, where sustainability scorecards influence vendor selection.
Hyperscalers are consolidating APU procurement around direct foundry relationships rather than merchant silicon vendors. Amazon Web Services and Microsoft Azure are negotiating custom APU tape-outs that bypass traditional semiconductor distribution channels. This behavioral shift is most visible in US and European cloud infrastructure deployment, where vertical integration into silicon design is becoming a competitive differentiator.
Accelerated Processing Unit (APU) Market Segmentation
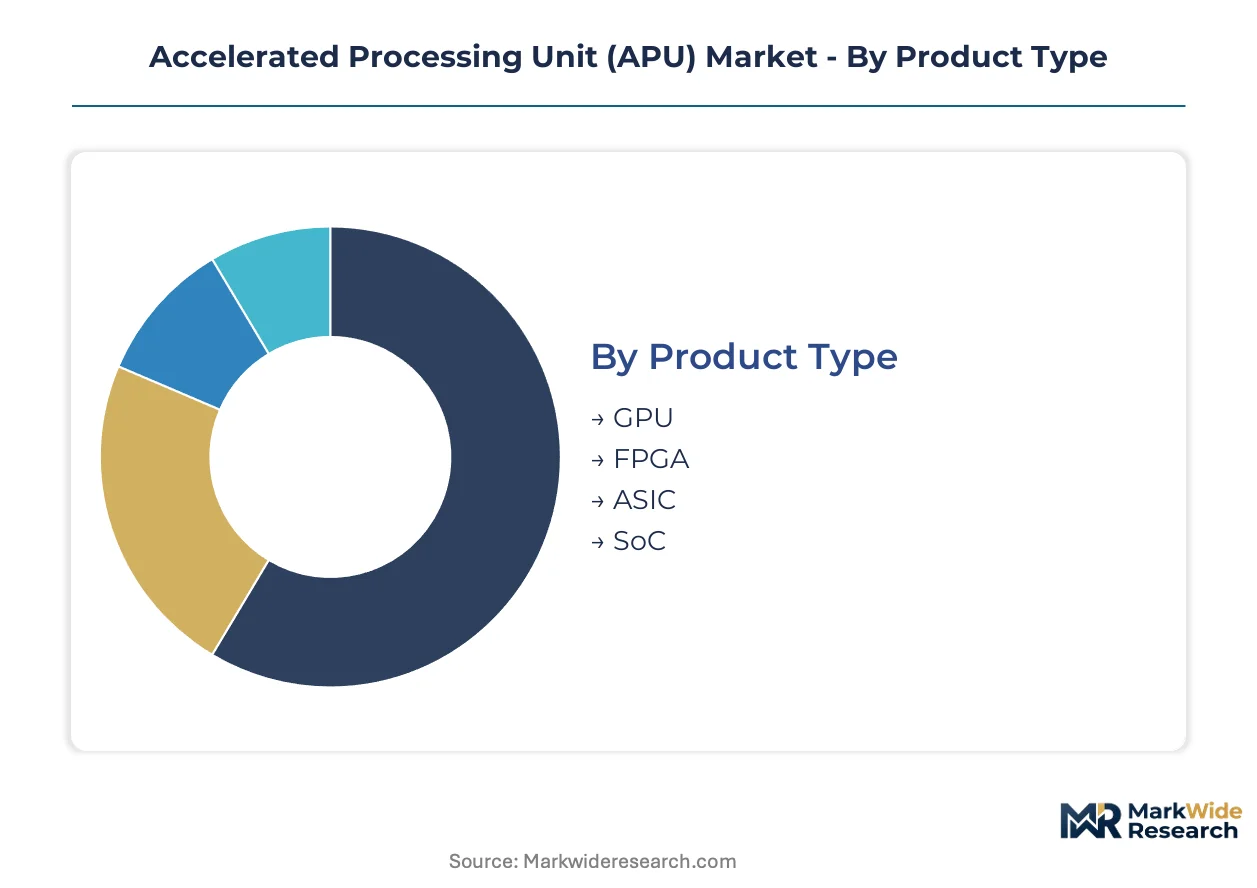
APU segmentation reveals how architectural choices map to divergent cost structures and thermal constraints. Product-level distinctions determine whether vendors pursue monolithic integration or chiplet-based disaggregation, while application splits expose which workloads justify premium packaging investments.
Product Type:
GPU and ASIC segments face acute substitution pressure from software-programmable alternatives as inference workloads shift toward flexible execution models. FPGA vendors are repositioning toward adaptive compute platforms that erode fixed-function silicon's historical latency advantages.
- GPU:Massively parallel shader arrays coupled with tensor cores enable real-time ray tracing and neural network acceleration. Gaming console manufacturers in Japan and the United States now specify unified GPU-CPU dies to compress thermal envelopes and reduce motherboard complexity.
- SoC:Complete system integration incorporating CPU clusters, graphics engines, and I/O controllers on a single substrate. Mobile handset designers in South Korea and Taiwan are driving process migration toward 3nm nodes to maximize battery endurance in thin-form-factor devices.
- FPGA:Field-reconfigurable logic fabrics suit defense and industrial automation requiring post-deployment algorithm updates.
- ASIC:Custom silicon optimized for specific inference or mining workloads sacrifices flexibility for power efficiency and unit economics.
SoC retains volume leadership across consumer and mobile compute; GPU holds the steepest expansion curve as gaming and AI inference demands converge.
Application:
Cost-tier stratification separates high-volume consumer gaming from capital-intensive hyperscaler deployments where thermal budgets permit discrete socketed configurations.
- Gaming:Real-time rendering pipelines demand low-latency CPU-GPU memory coherence. Valve Corporation and Sony Interactive Entertainment have committed to unified APU architectures for next-generation console refreshes, eliminating inter-socket signaling overhead.
- Machine Learning:Training and inference workloads require high-bandwidth memory interfaces and specialized matrix multiplication units. Cloud operators in the United States are deploying tightly coupled CPU-GPU packages to minimize memory latency in recommendation engines.
- Data Analytics:Columnar query processing and stream analytics benefit from integrated acceleration for compression and encryption operations.
- Embedded Systems:Size-constrained deployments in automotive and industrial contexts prioritize deterministic latency over peak throughput.
Gaming commands the largest procurement volume; machine learning is expanding most quickly as generative AI workloads proliferate through cloud infrastructure.
Technology:
Customer-type splits reveal how enterprise buyers with direct foundry relationships pursue custom silicon while consumer OEMs rely on merchant APU portfolios.
- Integrated:CPU and graphics engines share a single die or multi-chip package with unified memory addressing. EPA energy-efficiency thresholds in the United States are pushing OEMs toward integrated configurations for volume desktop and mobile SKUs.
- Discrete:Separate socketed components preserve thermal headroom and upgrade flexibility for enthusiast segments and hyperscaler AI clusters.
- Hybrid:Chiplet-based partitioning couples compute dies fabricated at leading-edge nodes with I/O tiles at mature processes.
- Cloud-Based:Virtualized acceleration resources delivered through infrastructure-as-a-service models abstract physical silicon from end-user hardware decisions.
Integrated technology dominates unit shipments; hybrid architectures are climbing the fastest as chiplet disaggregation spreads across vendor roadmaps.
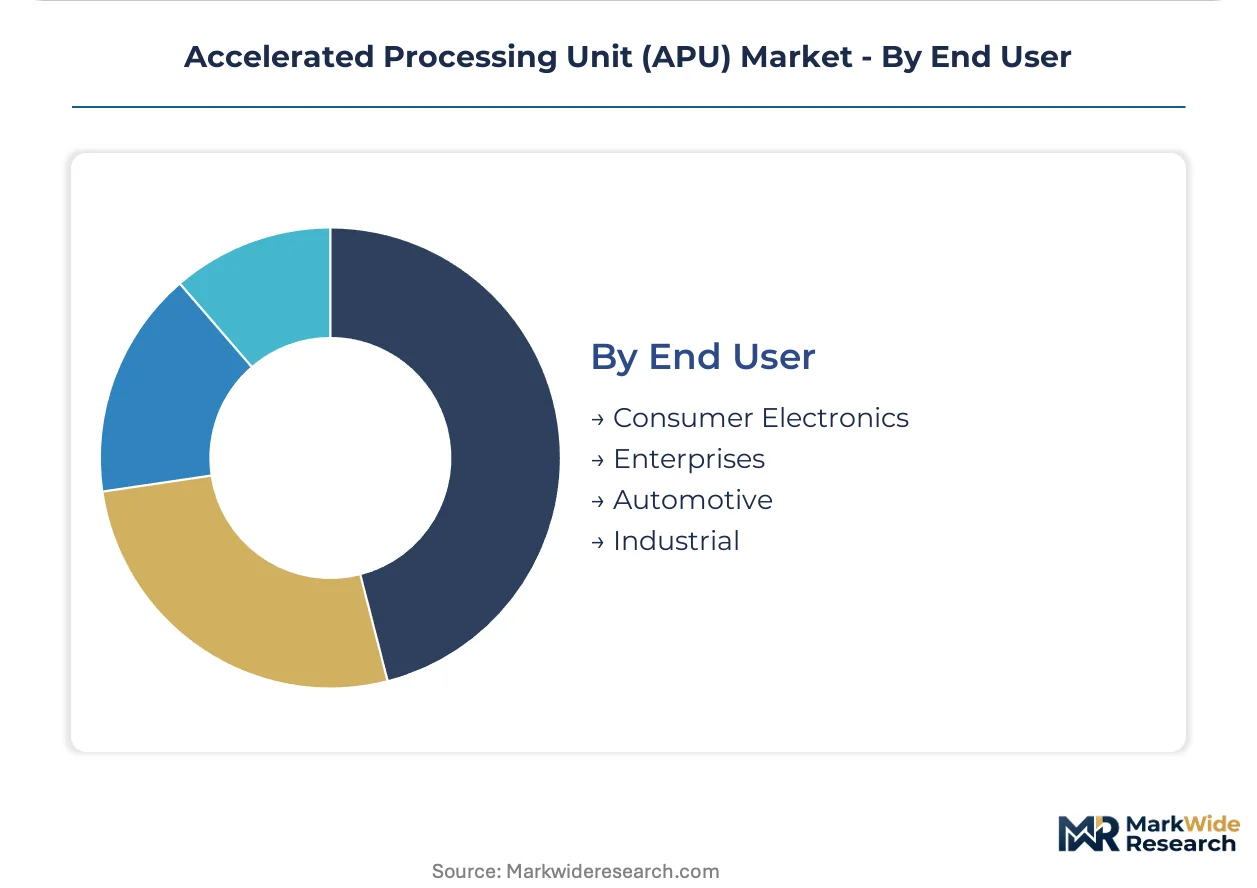
End User:
Supply concentration in Taiwan's foundry ecosystem shapes how each vertical secures packaging capacity for advanced-node designs.
- Consumer Electronics:Handset, tablet, and notebook manufacturers specify thin-form-factor APUs with aggressive power budgets. China's MIIT certification requirements are accelerating domestic APU design capabilities for government and telecom procurement.
- Automotive:Zonal compute architectures for cabin infotainment and ADAS sensor fusion require automotive-grade silicon with decade-long supply commitments. Tier-1 suppliers in Germany and Japan are specifying fused CPU-GPU silicon for next-generation vehicle platforms.
- Enterprises:Data center and edge server deployments favor configurations balancing throughput with total cost of ownership.
- Industrial:Factory automation and robotics applications demand deterministic real-time response and extended temperature operating ranges.
Consumer electronics maintains volume leadership; automotive is gaining share fastest as software-defined vehicle architectures proliferate through European and Asian supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports the majority of advanced-node APU wafers to US hyperscalers and Japanese gaming console manufacturers. This trade corridor concentrates packaging capacity at TSMC's foundries while driving design partnerships in Austin, Tokyo, and Shanghai.
United States
Hyperscaler AI inference densification and gaming console refreshes drive procurement from domestic cloud operators and console manufacturers. The EPA's updated ENERGY STAR specifications tighten idle power thresholds for desktop systems. Austin's semiconductor design cluster hosts multiple APU architecture teams negotiating direct foundry relationships.
China
Domestic handset manufacturers and telecom infrastructure builders accelerate APU consumption for 5G baseband and AI edge devices. MIIT semiconductor self-sufficiency mandates and GB standards certification restrict foreign silicon in government procurement. Shanghai's Zhangjiang Hi-Tech Park houses indigenous design houses developing 7nm-class integrated solutions.
Japan
Gaming console manufacturers and automotive Tier-1s dominate demand for unified CPU-GPU architectures in entertainment and zonal compute applications. METI's semiconductor revival subsidies support domestic advanced packaging investments. Tokyo-Osaka corridor engineering centers collaborate with Taiwan foundries on custom APU tape-outs.
South Korea
Memory suppliers and mobile handset designers anchor demand for high-bandwidth integrated solutions with HBM3E interfaces. The national semiconductor competitiveness program funds advanced packaging R&D consortiums. Seoul-Pyeongtaek region concentration spans HBM fabrication, mobile SoC design, and OSAT backend capacity.
Germany
Automotive OEMs specify fused CPU-GPU silicon for software-defined vehicle architectures and cabin infotainment systems. KBA type-approval processes and EU automotive safety regulations mandate deterministic latency certification. Munich-Stuttgart engineering corridor hosts Tier-1 development centers qualifying automotive-grade APU designs.
Accelerated Processing Unit (APU) Market Vendor Landscape
Player mix skews toward integrated device manufacturers with captive foundry relationships and fabless designers dependent on Taiwan packaging capacity. Three archetypes dominate: x86-integrated vendors converging CPU-GPU architectures, Arm-licensee specialists serving mobile and embedded verticals, and discrete GPU-CPU combination providers targeting AI training clusters. Competitive moves concentrate on multi-chiplet packaging partnerships and direct hyperscaler silicon customization agreements.
Within the x86-integrated tier, Advanced Micro Devices and Intel Corporation exemplify contrasting approaches to unified architecture development. Among Arm-licensee specialists, Arm Limited and Qualcomm Technologies occupy positions serving mobile handset and embedded compute demand. NVIDIA Corporation anchors the discrete combination segment where thermal headroom permits separate socketed components. Each archetype faces distinct constraints from Taiwan foundry access concentration and CoWoS packaging bottlenecks.
| Leading Market Players |
|---|
| Arm Limited |
| Broadcom Corporation |
| Advanced Micro Devices, Inc. |
| IBM Corporation |
| NXP Semiconductors |
| Intel Corporation |
| Qualcomm Technologies, Inc. |
| Marvell Technologies, Inc. |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
TSMC's 5nm and 3nm node utilization rates above 90 percent compress cost curves for leading-edge APU designs while simultaneously hardening price floors for mid-range alternatives stuck at mature nodes. This scale asymmetry between Taiwan's foundry ecosystem and trailing-edge capacity elsewhere concentrates margin capture upstream and forces second-tier designers into cost-plus pricing models.
Pricing Analysis
Current-generation 3nm APU tape-outs command 40-60 percent premiums over 5nm equivalents, while next-generation 2nm risk production quotes already diverge sharply from mainstream 7nm-optimized offerings. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler custom silicon from merchant gaming APUs and entry-level mobile SoCs. Price differentiation rests on HBM3E memory bundling and CoWoS packaging access, with cost compression in the standard tier intensifying because 7nm wafer supply is overshooting handset demand. Hyperscalers exhibit lowest price sensitivity due to workload-specific latency requirements, while white-box PC OEMs in emerging markets face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of HBM3E memory and advanced substrate materials has displaced just-in-time inventory norms as lead times for CoWoS packaging extend beyond 40 weeks. Geographic supply concentration centers on Taiwan for front-end wafer fabrication, South Korea for HBM3E supply, and Japan for advanced substrate and chemical inputs. Raw material dependencies include EUV photoresists, high-purity silicon wafers, and copper pillar bumping materials. Single-source vulnerability at TSMC's CoWoS lines represents the dominant structural risk. Distribution runs through direct foundry relationships for hyperscalers and merchant semiconductor distributors for consumer OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Discrete GPU-CPU combinations threaten monolithic APU architectures in high-margin AI training clusters where thermal budgets permit socketed flexibility. Incumbents must defend integrated positioning through packaging innovation and memory bandwidth consolidation.
For Market Incumbents: Consolidate CoWoS packaging commitments through multi-year capacity reservations at TSMC and Samsung Foundry to lock out fabless rivals. Deepen backward integration into HBM3E supply through Korean memory house partnerships or captive testing facilities. Arm-licensee entrants and RISC-V chiplet startups represent the primary substitution threat requiring defensive patent portfolio expansion.
For New Entrants and Emerging Players: Automotive-grade AEC-Q100 certification fast-tracks open a defensible white-space corridor with decade-long supply commitments and limited incumbent presence. Target zonal compute architectures for cabin infotainment and ADAS sensor fusion in European and Japanese supply chains. Go-to-market leverage rests on Tier-1 supplier co-development agreements rather than merchant silicon distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chiplet-based disaggregation specialists with proven advanced packaging partnerships and automotive qualification pipelines. Long-term viability hinges on 5-10 year foundry access security rather than architectural differentiation alone. Acquisition targets should display captive backend capacity or binding CoWoS allocation agreements. The signal to watch is MIIT domestic certification acceleration in China, which would compress foreign APU access to government and telecom procurement channels.
| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Reservation | Multi-year foundry commitments at TSMC secure packaging access for high-bandwidth APU output. |
| HBM3E Supply Partnership | Korean memory house alliances reduce input cost volatility for premium APU configurations. |
| Automotive Certification Pipeline | AEC-Q100 qualification opens decade-long supply commitments with European and Japanese Tier-1s. |
| Chiplet Architecture Standardization | UCIe protocol adoption enables cost optimization across heterogeneous compute and I/O tiles. |
| Direct Hyperscaler Silicon Customization | AWS and Azure tape-out agreements bypass merchant distribution and capture cloud infrastructure margin. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foundry account managers, APU architecture leads at fabless designers, hyperscaler infrastructure procurement officers, and automotive Tier-1 platform engineers. Secondary validation drew from SEC 10-K filings, TSMC and Samsung Foundry capacity disclosures, MIIT certification registries, and EPA ENERGY STAR specification updates. Bottom-up wafer shipment estimates triangulated against top-down gaming console and data center capex forecasts.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, application, technology, and end user dimensions, with additional granularity for process node migration and packaging technology adoption. CAGRs were derived from regression analysis of historical foundry revenue correlation with downstream device shipments. Industry-specific inputs included CoWoS capacity expansion schedules, HBM3E supply ramp curves, and gaming console refresh cycle timing.
Decision-makers should treat outputs as directional under assumptions of sustained Taiwan foundry access and stable HBM3E supply concentration; material deviation would warrant model refresh. Specific risk factors include export control tightening on EUV equipment access, automotive demand cyclicality, and hyperscaler vertical integration into captive silicon design. Revision becomes warranted when CoWoS packaging utilization crosses 95 percent sustained thresholds or when MIIT certification timelines accelerate beyond baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
NFC Chips Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
PC Processor Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market