
 Wireless Charging Ics Market | 2026-2036
Wireless Charging Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Charging Ics Market Intelligence
The bundling of transmitter, receiver, and power management functions into highly integrated system-on-chip (SoC) solutions is consolidating the component count for device manufacturers. Texas Instruments leverages its broad portfolio in power management to offer complete reference designs for automotive and industrial applications. NXP Semiconductors specializes in secure, high-performance solutions for the automotive in-cabin charging segment. Qualcomm Technologies, Inc. dominates the high-end smartphone market with its Quick Charge and WiPower technologies.
Wireless charging ICs are integrated circuits designed to manage the transfer of electrical power between a transmitter and a receiver without a physical connection. These components typically operate at frequencies between 100-205 kHz for inductive systems and manage power delivery from 5W in consumer devices to several kilowatts in industrial applications. Receiver ICs integrated into consumer electronics like smartphones and wearables represent the largest volume segment. Transmitter ICs for industrial automation and electric vehicles are experiencing rapid development, often utilizing resonant charging technology for greater spatial freedom.
The Wireless Power Consortium (WPC) and its Qi standard dictate interoperability requirements, particularly for consumer electronics. In parallel, regulators like the FCC in the United States and equivalent bodies in Europe and Asia enforce strict electromagnetic interference (EMI) limits, shaping IC design and shielding. IC manufacturers must navigate the evolving standards landscape, deciding on investments between established inductive technologies and emerging resonant or RF-based charging solutions.
Market Dynamics
The central dynamic in the wireless charging IC market is the drive toward higher integration, where power management, transmitter, and receiver functions are consolidated into single System-on-Chip solutions to meet OEM demands for smaller footprints and simplified designs.
Growth Catalysts
- Qi2 Standard Adoption:The new Qi2 standard, based on magnetic power profiles, is triggering a significant product refresh cycle in consumer electronics, compelling device makers to integrate new, compliant ICs for enhanced interoperability and efficiency.
- Automotive Integration:The expansion of the electric vehicle market is a primary catalyst, with automotive manufacturers increasingly specifying wireless charging ICs for in-cabin convenience features, creating a high-volume, high-reliability demand segment.
- Manufacturing Ecosystems:Demand is concentrating in China, whose extensive consumer electronics and automotive manufacturing infrastructure provides a scaled ecosystem for the rapid deployment and integration of wireless charging technologies into finished goods.
Market Restraints
- Thermal Management Limits:At higher power levels required for industrial and automotive applications, significant heat generation reduces charging efficiency and poses a safety risk, requiring complex and costly thermal management solutions within the IC design.
- Regulatory Compliance Burden:ICs must adhere to stringent electromagnetic interference (EMI) limits set by bodies like the FCC in the United States and through CE marking in Europe, adding significant design, testing, and shielding costs.
- High-Power Standardization Gaps:While the Qi standard governs low-power consumer devices, a lack of mature, universally adopted standards for higher-power (kilowatt-range) applications creates interoperability risks and deters investment in industrial and EV charging solutions.
Strategic Opportunities
- Industrial Automation:A significant opportunity exists in industrial settings for charging automated guided vehicles (AGVs), drones, and robotic tools, where wireless power transfer can increase operational uptime by eliminating manual battery swaps. *Medical and Healthcare Devices: Sealed, waterproof medical devices benefit from wireless charging, as it eliminates physical ports that can be points of failure or contamination. This creates a niche for high-reliability ICs in medical wearables and diagnostic equipment.
- Data and Power Convergence:Combining power transfer with low-rate data transmission on the same IC offers an opportunity for smart charging applications, enabling device authentication, battery health monitoring, and personalized charging profiles in IoT ecosystems.
Industry Challenges
- Patent Licensing Complexity:The technology landscape is protected by a dense web of patents related to inductive and resonant charging, forcing IC designers to navigate complex and often costly cross-licensing agreements to avoid litigation.
- Multi-Standard Interoperability:Developing ICs that can seamlessly switch between different standards, such as Qi inductive and AirFuel resonant, presents a significant technical challenge, increasing chip complexity and validation time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Charging Ics Market |
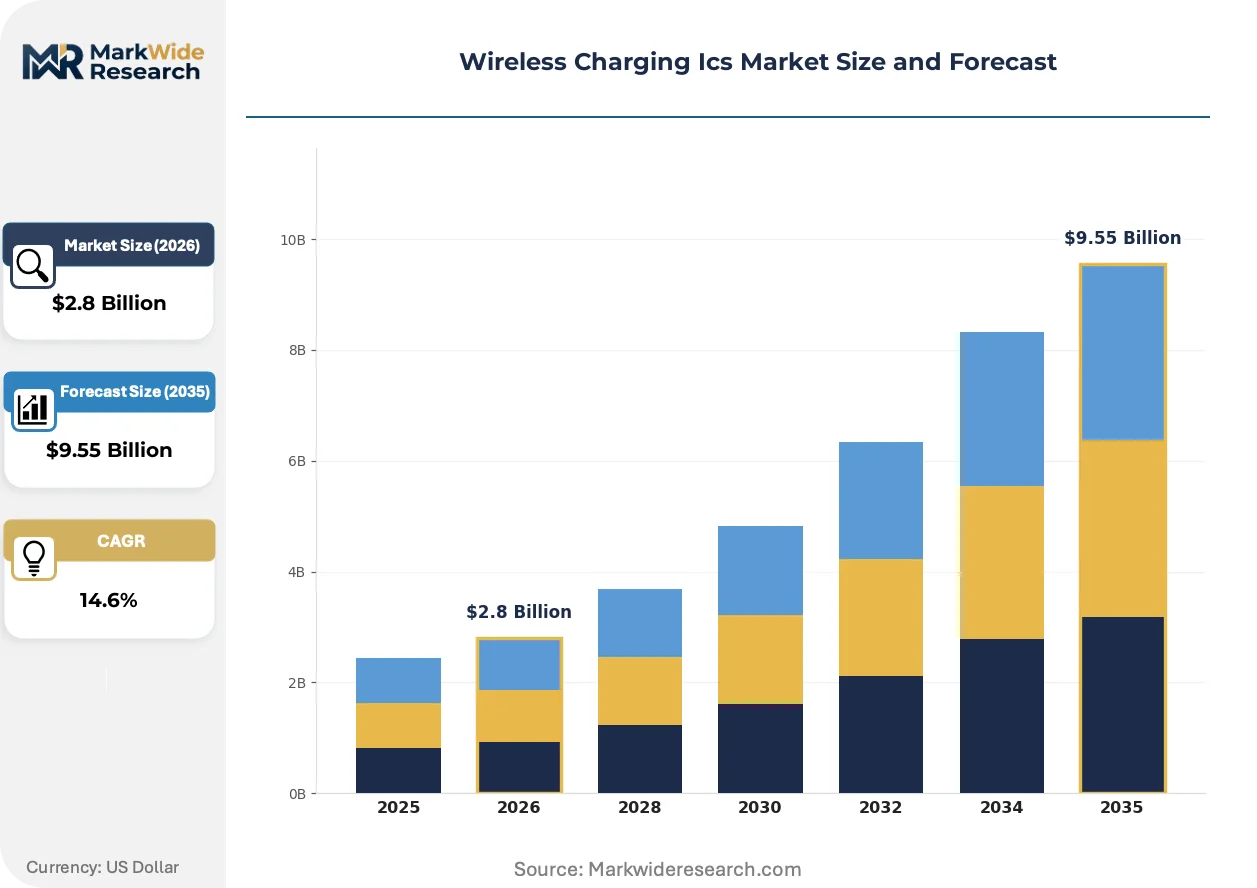
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
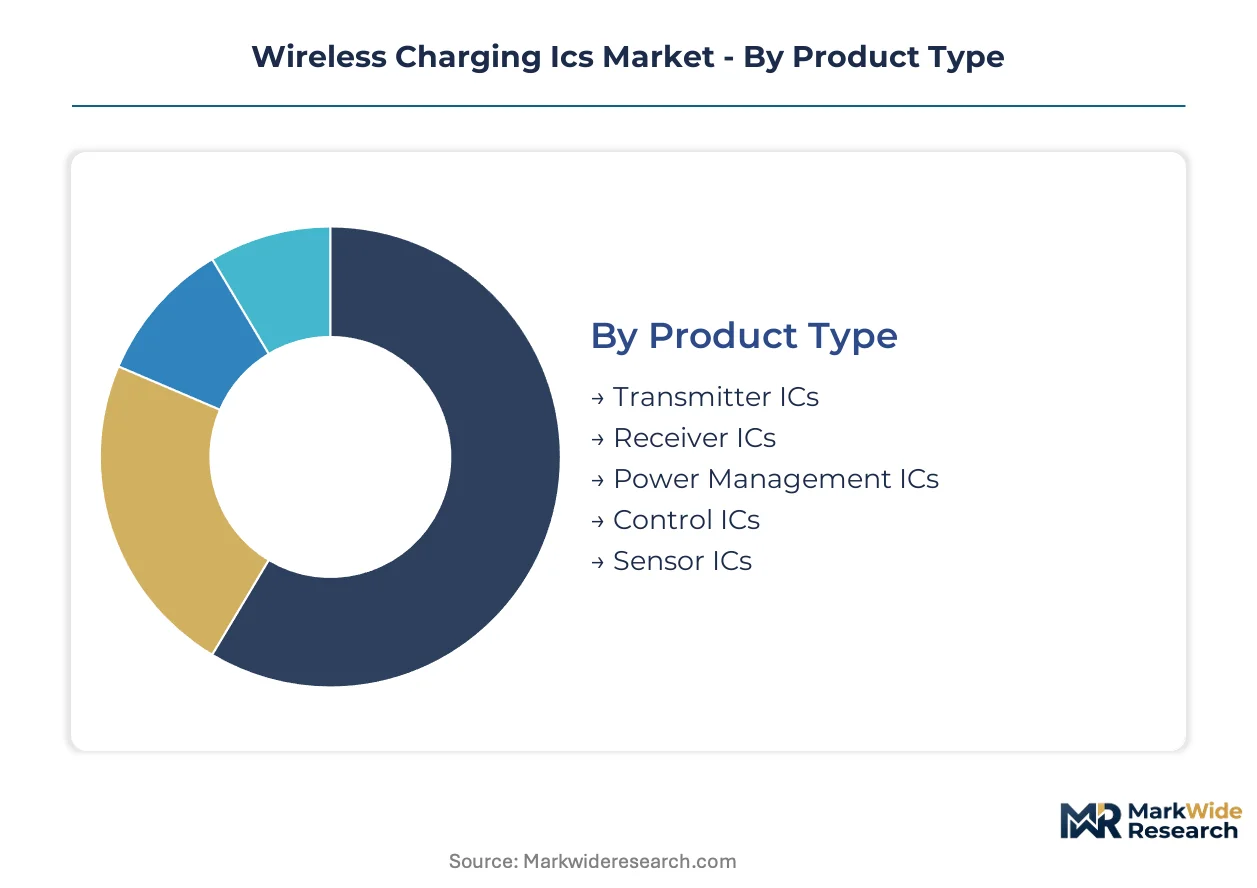
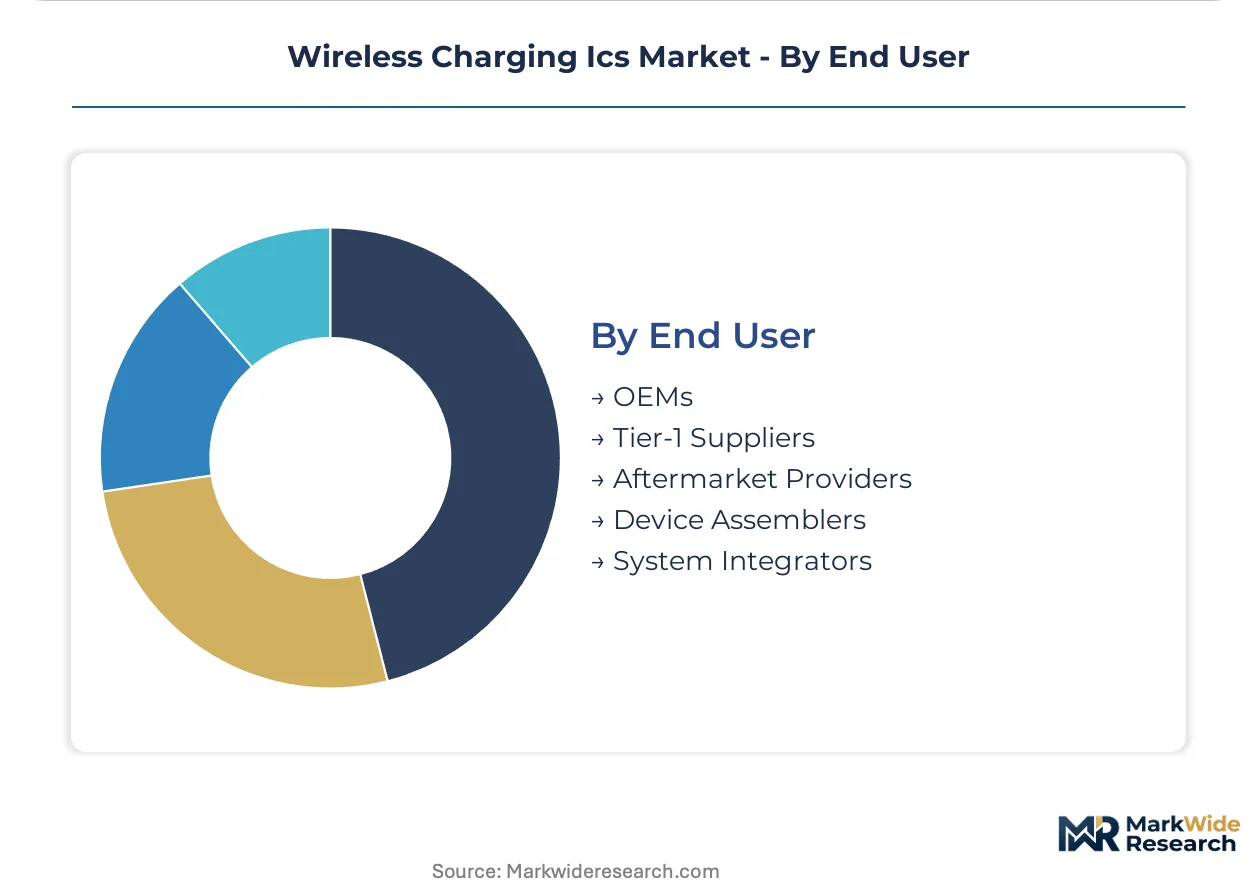
| Segmentation | Product Type: Transmitter ICs, Receiver ICs, Power Management ICs, Control ICs, Sensor ICs Technology: Inductive Charging, Resonant Charging, Magnetic Resonance, Radio Frequency, Ultrasound Application: Consumer Electronics, Industrial Automation, Wearable Devices, Electric Vehicles, Smart Homes End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Device Assemblers, System Integrators |
| Companies Covered | Texas Instruments Incorporated, Qualcomm Technologies, Inc., NXP Semiconductors N.V., Infineon Technologies AG, ROHM Semiconductor, Broadcom Inc., Analog Devices, Inc., ON Semiconductor Corporation, STMicroelectronics N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Charging Ics Market Strategic Shifts & Innovations
The market's trajectory is defined by the consolidation of discrete power and control functions into highly integrated System-on-Chip (SoC) architectures. This integration addresses OEM demands for reduced component count, smaller physical footprints, and simplified product development cycles across all end-use segments.
System-on-Chip (SoC) solutions integrate the transmitter or receiver coil drivers, power management units, and microcontrollers onto a single piece of silicon. This approach is being rapidly adopted by smartphone and wearable manufacturers seeking to minimize board space and assembly costs. The drive for higher integration is converging with the need for on-chip secure elements, which are required to authenticate devices and manage proprietary fast-charging protocols.
In Europe, the Radio Equipment Directive (RED) establishes essential requirements for safety and electromagnetic compatibility that all wireless charging products must meet to receive CE marking. This regulation compels IC designers to incorporate advanced filtering and EMI mitigation techniques directly into the chip architecture. The automotive segment is particularly impacted, as ICs must simultaneously satisfy RED and the stringent AEC-Q100 automotive reliability standards.
A distinct behavioral shift is occurring as device manufacturers pivot from sourcing individual ICs to procuring complete, pre-certified reference designs from semiconductor suppliers. This model allows smaller OEMs and new market entrants to bypass the complexities of RF design, antenna tuning, and regulatory certification, significantly accelerating their time to market. This trend is most prominent in the fast-paced consumer electronics and IoT device sectors, particularly within Asian manufacturing hubs.
Wireless Charging Ics Market Segmentation
Understanding the market for wireless charging ICs requires a granular breakdown of its components and applications. This segmentation reveals distinct value pools and technological pathways influencing product development cycles. Analyzing these segments helps stakeholders identify areas of concentrated demand and emerging growth opportunities across the ecosystem.
Product Type:
Supply concentration for wireless charging ICs often dictates the integration complexity and bill of materials for device manufacturers.
- Receiver ICs:These integrated circuits are embedded in consumer electronic devices like smartphones and wearables, managing power reception from a transmitter. Demand is concentrating in Asia, driven by an extensive consumer electronics manufacturing base and the rapid adoption of new Qi2-compliant devices.
- Transmitter ICs:These components manage power delivery from the charging source, often utilizing resonant charging for greater spatial freedom in industrial and automotive applications. The electric vehicle sector is a significant demand driver, requiring robust solutions for in-cabin charging.
- Power Management ICs:These circuits regulate voltage and current, optimizing energy transfer efficiency and ensuring device safety during wireless charging.
- Control ICs:These components handle communication protocols and power regulation algorithms between the transmitter and receiver, ensuring interoperability.
- Sensor ICs:These integrated circuits detect objects, temperature, and foreign metallic items on the charging surface, enhancing safety and efficiency.
Today's leader: Receiver ICs. Tomorrow's challenger: Transmitter ICs.
Technology:
The application requirements for wireless charging ICs heavily influence the choice of underlying technology, from established standards to emerging high-power solutions.
- Inductive Charging:This technology operates at frequencies like 100-205 kHz, transferring power over short distances through magnetic induction, adhering to the Qi standard. Consumer electronics, especially smartphones, demand these widely adopted, interoperable solutions for daily convenience.
- Resonant Charging:Utilizing magnetic resonance, this technology enables power transfer over longer distances and with greater spatial freedom compared to inductive methods. Industrial automation and electric vehicle applications are increasingly adopting resonant solutions for their higher power capabilities.
- Magnetic Resonance:This technology allows power transfer through non-metallic materials, offering flexibility in design and integration for various embedded applications.
- Radio Frequency:RF-based charging delivers low power over longer distances, suitable for small IoT devices and sensor networks requiring continuous, low-energy top-ups.
- Ultrasound:This emerging technology explores power transfer using ultrasonic waves, potentially offering precise and directional charging for specific niche applications.
Inductive Charging represents the most mature segment, while Resonant Charging is expanding most quickly.
Application:
The volume of wireless charging ICs deployed varies significantly across different end-use applications, with consumer electronics dominating current shipments.
- Consumer Electronics:This segment includes smartphones, smartwatches, and other personal gadgets, driven by the new Qi2 standard and continuous product refresh cycles. China's manufacturing ecosystem fuels the high-volume demand for these integrated solutions.
- Electric Vehicles:Wireless charging ICs are increasingly integrated into EVs for in-cabin phone charging and future vehicle-to-grid power transfer solutions. Automotive manufacturers prioritize high reliability and compliance with stringent AEC-Q100 standards.
- Industrial Automation:This application involves charging automated guided vehicles (AGVs), robots, and drones, where wireless power improves operational uptime. High-power resonant charging solutions are critical for these demanding environments.
- Wearable Devices:Small, low-power ICs enable convenient charging for smartwatches, fitness trackers, and hearables, often requiring compact and efficient designs.
- Smart Homes:Wireless charging ICs power various smart home devices, including sensors, thermostats, and small appliances, enhancing user convenience and reducing cable clutter.
Consumer Electronics holds the largest volume, while Electric Vehicles are gaining share fastest.
End User:
The specific customer type for wireless charging ICs influences design requirements, integration support, and supply chain dynamics.
- OEMs:Original Equipment Manufacturers integrate wireless charging ICs directly into their final products, demanding highly integrated System-on-Chip solutions for reduced footprint and simplified designs.
- Tier-1 Suppliers:These companies develop and supply larger sub-assemblies or modules to OEMs, often requiring pre-certified reference designs and robust automotive-grade ICs.
- Aftermarket Providers:This segment offers wireless charging accessories and retrofit solutions to consumers, focusing on compatibility and ease of installation.
- Device Assemblers:These companies specialize in the mass production and assembly of electronic devices, requiring reliable and readily available IC components.
- System Integrators:These firms design and implement complex wireless charging solutions for industrial and commercial environments, often requiring custom configurations.
OEMs represent the largest end-user segment, with Tier-1 Suppliers demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Wireless Charging ICs market scaled significantly through the extensive consumer electronics manufacturing ecosystems of Asia, particularly China. This region became central to widespread adoption and integration of wireless charging technologies. Global demand continues to expand, driven by diverse end-use applications across key economic regions.
China
China's vast consumer electronics manufacturing base drives substantial demand for wireless charging ICs, especially with the new Qi2 standard. The government's dual carbon goals accelerate electric vehicle adoption, boosting demand for in-cabin charging. Shenzhen's electronics manufacturing cluster serves as a global hub for rapid prototyping and mass production.
United States
The United States exhibits strong demand for high-end wireless charging ICs in electric vehicles and industrial automation. FCC regulations rigorously govern electromagnetic interference, ensuring compliant product development. Silicon Valley remains a critical innovation center, fostering advanced IC designs for resonant charging and IoT applications.
Germany
German automotive manufacturers increasingly integrate wireless charging ICs for in-cabin convenience, alongside robust demand from industrial automation. CE marking requirements under the Radio Equipment Directive compel IC designers to incorporate advanced EMI mitigation. Bavaria's strong automotive and industrial sectors concentrate development on high-power resonant charging.
Japan
Japanese consumer electronics companies consistently integrate innovative wireless charging ICs into their devices, alongside emerging demand from industrial robotics. METI standards influence product development, emphasizing efficiency and reliability. The Tokyo metropolitan area hosts significant research and development for next-generation RF-based charging technologies.
South Korea
South Korea's leading position in smartphone and automotive manufacturing fuels demand for highly integrated wireless charging ICs. The country's national regulatory bodies ensure compliance with safety and performance standards. Seoul's technology clusters are central to the design and mass production of advanced SoC solutions for consumer devices.
Wireless Charging Ics Market Key Industry Players
The competitive structure tilts toward integrated semiconductor specialists offering comprehensive solutions for wireless charging. This market features a mix of established players with broad portfolios and specialized firms focusing on niche applications. Strategic archetypes include diversified semiconductor giants, dedicated power management IC providers, and automotive-focused solution developers. Portfolio diversification and strategic partnerships drive competitive moves across the ecosystem.
Diversified semiconductor giants anchor the high-end market, exemplified by Texas Instruments Incorporated, which leverages its broad power management portfolio for automotive and industrial applications. Qualcomm Technologies, Inc. occupies a position in the premium smartphone segment with its advanced Quick Charge and WiPower technologies. NXP Semiconductors N.V. represents a specialist archetype, providing secure, high-performance solutions primarily for the automotive in-cabin charging segment. These companies continually integrate transmitter, receiver, and power management functions into highly integrated system-on-chip solutions, responding to OEM demands for smaller footprints. Their global presence and deep R&D capabilities define the technological trajectory of the market.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Qualcomm Technologies, Inc. |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| ROHM Semiconductor |
| Broadcom Inc. |
| Analog Devices, Inc. |
| ON Semiconductor Corporation |
| STMicroelectronics N.V. |
| Others |
Cost & Logistics Intelligence
Demand for Qi2-compliant devices in consumer electronics is forcing IC manufacturers to streamline production, influencing cost structures and per-unit pricing. This pressure from high-volume segments shapes the entire supply chain for wireless charging ICs.
Pricing Analysis
Per-unit transactional pricing dominates the wireless charging IC market, reflecting the high volume nature of components. Performance differentiation, tied to power efficiency, integration levels, and automotive-grade certifications like AEC-Q100, drives pricing tiers. Pricing pressure stems from intense competition among semiconductor vendors to secure design wins. Consumer electronics OEMs exhibit the highest price sensitivity, constantly seeking cost-optimized solutions for mass-market devices.
Supply Chain Analysis
Logistics and freight costs heavily influence the final price of wireless charging ICs, especially for high-volume shipments to global assembly hubs. Supply concentration for manufacturing centers on China and South Korea, leveraging their extensive electronics ecosystems. Key component dependencies include specialized silicon wafers and advanced packaging materials. Single-source vulnerability for specific high-performance or automotive-grade components presents a structural supply chain risk. Distribution primarily moves through direct sales channels to OEMs and Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
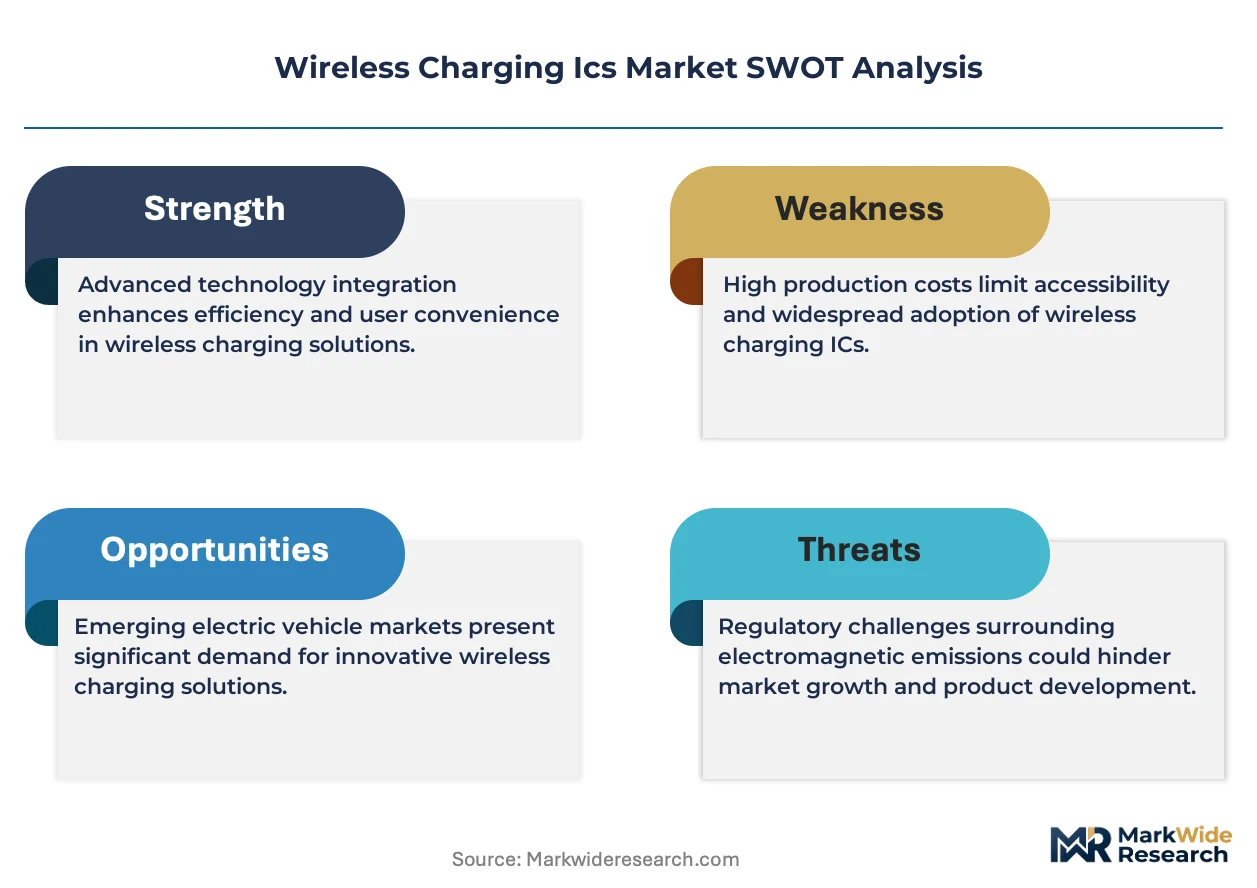
The Wireless Charging ICs market presents a geographic-arbitrage opportunity, given the cost advantages of manufacturing in Asia versus the premium pricing for high-reliability solutions in Western automotive segments.
For Market Incumbents: Acquire specialized IP portfolios in resonant charging to counter emerging RF-based solutions. Consolidate market share in automotive ICs through strategic partnerships with Tier-1 suppliers to defend against new entrants. Expanding design centers in Europe mitigates regulatory compliance risks from CE marking requirements.
For New Entrants and Emerging Players: Advanced resonant charging algorithms offer a technology-first wedge into industrial automation applications. Target the underpenetrated medical device segment with compact, high-reliability ICs for sealed enclosures. A direct-to-OEM sales model focusing on rapid customization can capture niche demand.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap firms specializing in high-power resonant charging for industrial applications. Long-term viability hinges on companies able to navigate complex patent landscapes and achieve multi-standard interoperability. A signal to watch is the widespread adoption of a high-power charging standard beyond Qi.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Resonant Charging R&D | Accelerates adoption in electric vehicles and industrial automation. |
| Secure AEC-Q100 Certification | Unlocks significant demand from automotive manufacturers. |
| Establish Asian Manufacturing Hub | Reduces production costs and improves supply chain responsiveness for consumer electronics. |
| Pursue IP Cross-Licensing Deals | Mitigates patent litigation risks for new product development. |
| Develop Integrated SoC Solutions | Addresses OEM demands for smaller footprints and simplified designs. |
Research Approach
Multiple input streams — executive interviews, technical whitepapers, and regulatory filings — were reconciled to build a comprehensive market view. Primary interviews with semiconductor R&D directors, automotive purchasing managers, and industrial automation engineers provided crucial insights. Secondary validation drew from WPC standards documents, FCC enforcement records, and company financial statements. Bottom-up sizing was reconciled with top-down market estimates.
Data-stream reconciliation established the analytical framework for market projections across the modeling period. Segmentation dimensions included product type, technology, application, and end-user, alongside regional manufacturing ecosystems. Compound annual growth rates were derived from historical trends and anticipated technological advancements. Key forecast inputs included Qi2 standard adoption rates and electric vehicle production forecasts.
The model holds under current technological and regulatory conditions; deviation in global trade policies or standardization efforts would shift forecast trajectories. Forecasts reflect assumptions regarding market evolution and competitive dynamics. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Microserver Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Micro Server IC Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Auto Chip Market