
 Africa Robotic Sensors Market | 2026-2036
Africa Robotic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Robotic Sensors Market Insights
A capital-intensity divergence between integrated sensor manufacturers and component assemblers is unwinding competitive dynamics across the continent. ABB leverages its integrated automation portfolio to anchor large-scale mining deployments in South Africa. FANUC Corporation sustains its position through dense distributor networks serving automotive manufacturing in Morocco. TE Connectivity Ltd. differentiates via specialized connectivity solutions for harsh-environment robotics.
Robotic sensors are electromechanical devices that detect physical properties including proximity, force, temperature, or visual data and convert them into processable signals for machine control systems. These devices typically operate within temperature ranges of minus forty to one hundred twenty-five degrees Celsius and rely on semiconductor-based transduction elements fabricated through MEMS processes. Vision sensors lead product type revenue due to precision requirements in automated inspection workflows, while force sensors represent the fastest-growing category as collaborative robotics expand across healthcare facilities. Infrared technology dominates current installations for obstacle detection, yet laser-based systems capture expanding margin pools in high-accuracy process control applications.
South Africa's National Regulator for Compulsory Specifications and Egypt's Egyptian Organization for Standardization and Quality enforce equipment safety and electromagnetic compatibility standards that shape product certification requirements for market entry. Nigeria's Standards Organization of Nigeria mandates conformity assessments that delay sensor imports but create structured pathways for compliant suppliers. Stakeholders must monitor evolving harmonization between national standards bodies and the African Continental Free Trade Area technical regulations to anticipate certification cost shifts and localized manufacturing incentives.
Market Dynamics
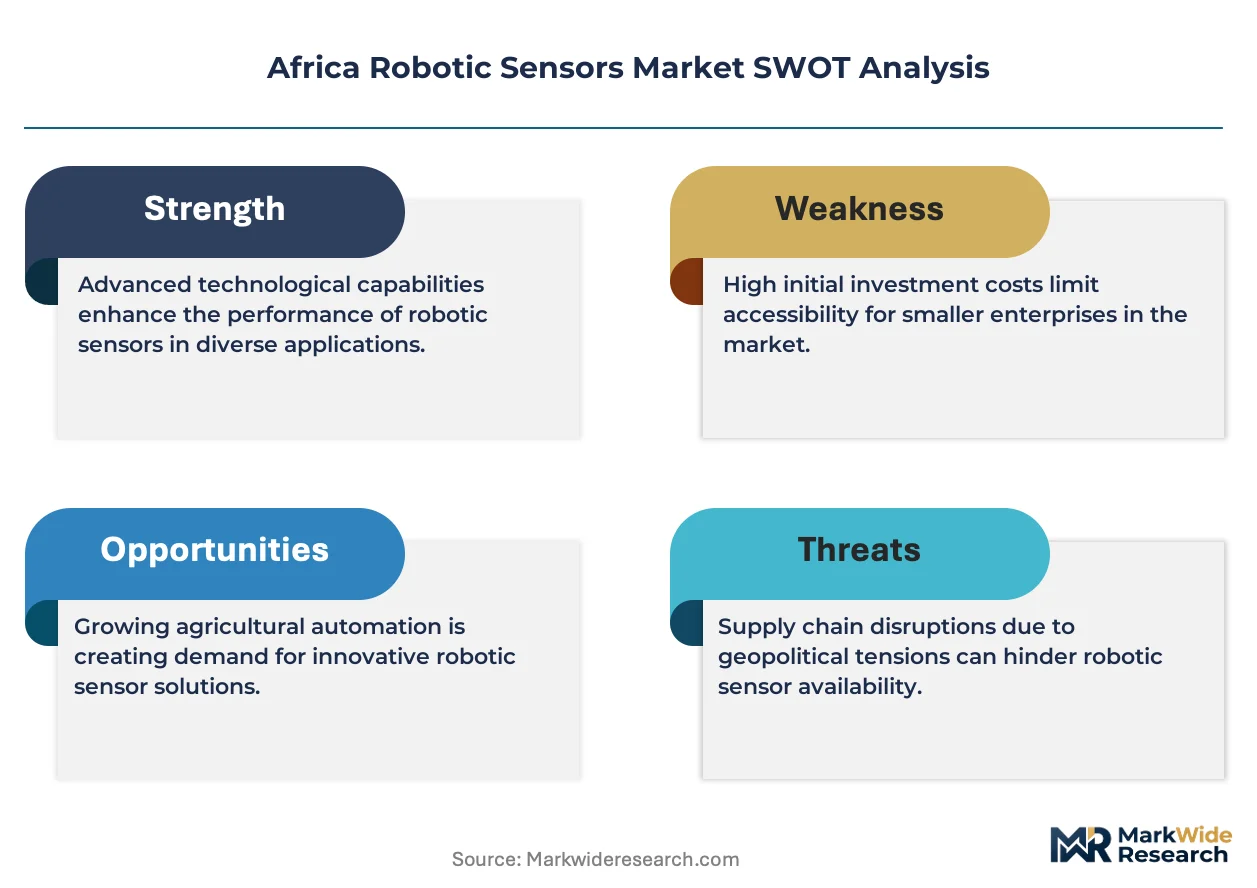
Capital-intensity divergence between integrated sensor manufacturers and component assemblers is unwinding competitive dynamics across Africa. This structural force is redistributing margin pools as mining automation in South Africa demands full-stack solutions while Nigerian manufacturing favors modular, price-optimized configurations.
Growth Catalysts
- Mining Automation Mandates:South Africa's National Regulator for Compulsory Specifications enforces equipment safety standards that accelerate sensor replacement cycles in platinum and gold extraction operations.
- Healthcare Robotics Expansion:Collaborative robotics deployment across Egyptian and Nigerian hospitals drives force sensor demand for surgical assistance and patient handling applications.
- AfCFTA Technical Harmonization:The African Continental Free Trade Area's evolving technical regulations create structured pathways for compliant suppliers, reducing certification duplication costs across member states.
Market Restraints
- Semiconductor Input Volatility:MEMS fabrication relies on silicon wafer supplies concentrated in East Asian foundries, exposing African assemblers to freight cost spikes and extended lead times.
- Electromagnetic Compatibility Certification:Egypt's Egyptian Organization for Standardization and Quality mandates pre-market testing that delays sensor imports by four to eight months.
- Vision System Substitution:Low-cost camera modules from consumer electronics supply chains displace purpose-built robotic vision sensors in price-sensitive Nigerian packaging applications.
Strategic Opportunities
- Underpenetrated East African Manufacturing:Ethiopia's industrial parks and Kenya's automotive component sector remain below replacement-level sensor penetration, offering first-mover positioning for compliant entrants.
- Laser-Based Process Control:Convergence of LiDAR hardware with industrial ethernet protocols enables high-accuracy metrology in South African precision machining workflows.
- Local Assembly Incentives:Nigeria's Standards Organization of Nigeria conformity assessment pathways reward localized final assembly with expedited certification timelines.
Industry Challenges
- MEMS Process Engineering Talent Gap:African universities produce insufficient graduates trained in semiconductor transduction element design, forcing manufacturers to import technical staff.
- Legacy System Integration Complexity:South African mining operations run thirty-year-old control architectures that resist seamless sensor data integration without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Robotic Sensors Market |
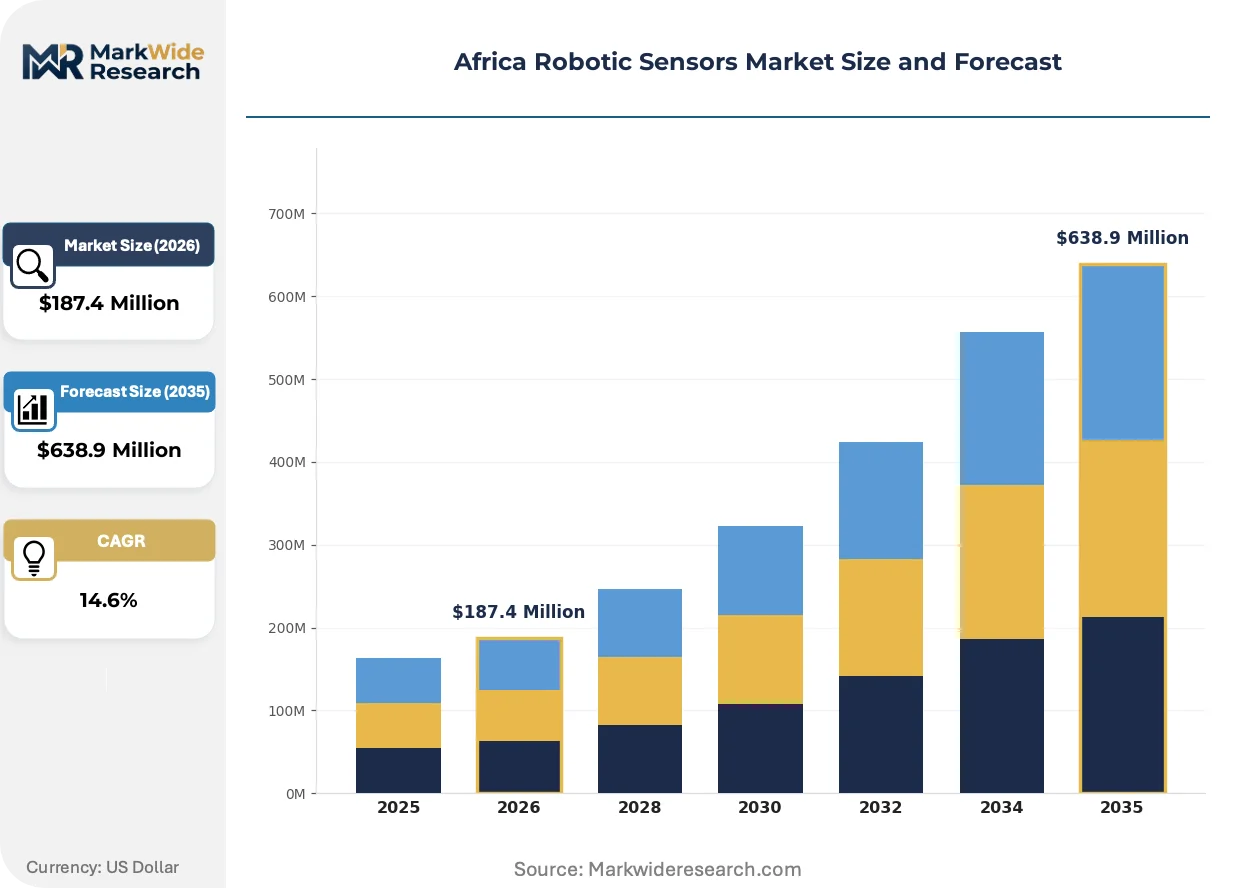
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vision Sensors, Proximity Sensors, Force Sensors, Temperature Sensors End User: Healthcare Facilities, Manufacturing Units, Agricultural Sector, Educational Institutions Technology: Infrared, Ultrasonic, Laser, RFID Application: Automated Inspection, Process Control, Data Collection, Research & Development |
| Companies Covered | ABB, FANUC Corporation, Yaskawa Electric Corporation, TE Connectivity Ltd., Honeywell International Inc., Baumer Group, Universal Robots, Omron Corporation, Sensata Technologies, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Robotic Sensors Market Trends and Innovations
Sensor fusion architectures are actively reshaping how robotic systems process multimodal data streams across African industrial deployments. This evolution is compressing the gap between research-grade precision and production-floor durability.
Time-of-flight depth sensing is fragmenting the obstacle detection category that infrared technology has dominated for two decades. South African mining operators now deploy hybrid vision systems combining structured light with thermal imaging for personnel safety in dust-heavy environments. This convergence is fragmenting supplier relationships as end-users bypass single-technology vendors for integrated perception stacks.
Egypt's Egyptian Organization for Standardization and Quality is tightening electromagnetic compatibility testing protocols for industrial automation equipment. The regulation now requires third-party validation of sensor immunity to power grid fluctuations common in North African manufacturing zones. Medical robotics manufacturers serving Cairo's hospital networks face the steepest compliance cost increases and are consolidating supplier lists to pre-certified vendors.
Buying committees at Nigerian automotive component plants are unbundling sensor procurement from system integrator contracts. Tier-two manufacturers now source force and proximity sensors directly through industrial distributors, compressing the traditional two-step channel. This disintermediation is most visible in Lagos and Kano manufacturing clusters where price transparency from Asian supplier catalogs has eroded integrator markup power.
Africa Robotic Sensors Market Segmentation
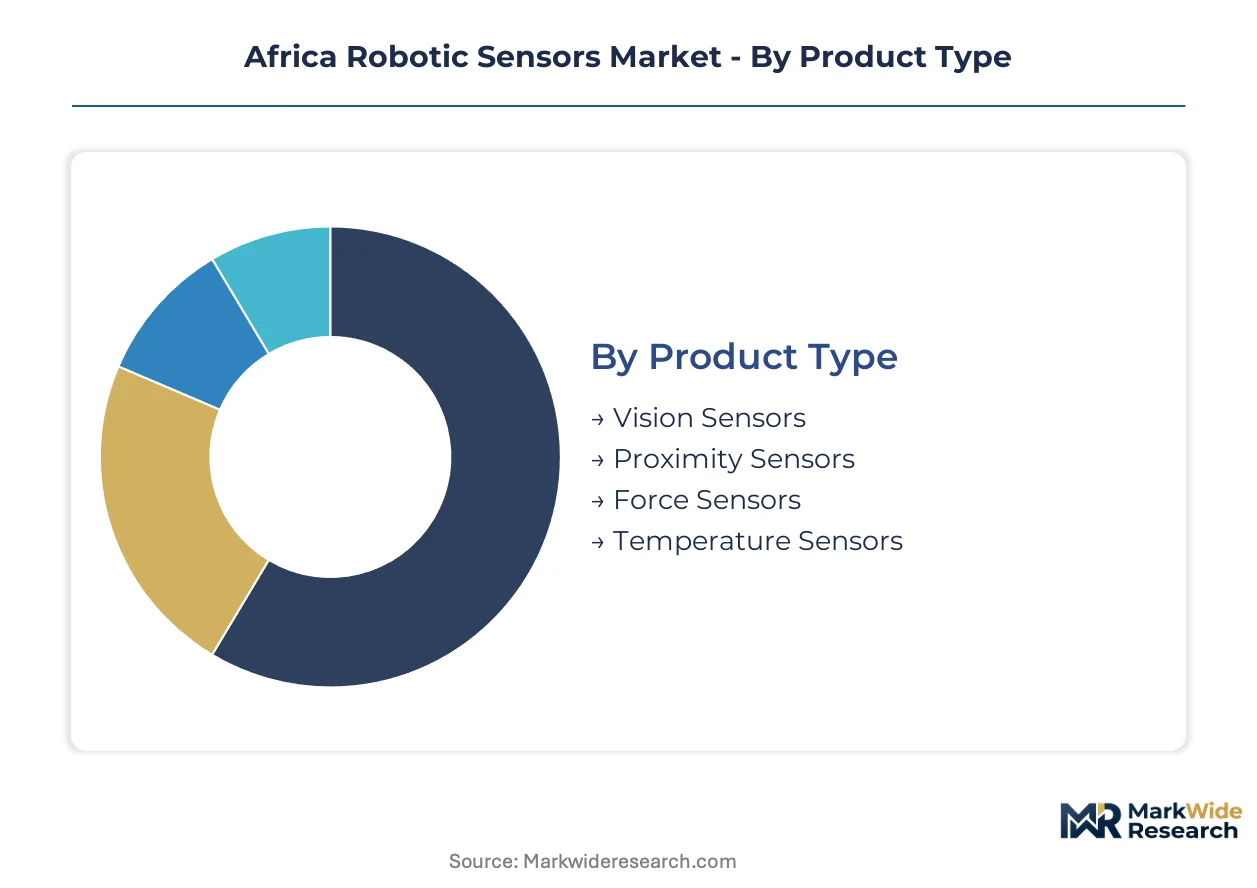
Segmentation in the Africa Robotic Sensors Market reveals divergent channel strategies across product categories. Mining automation in South Africa pulls full-stack solutions through system integrators, while Nigerian manufacturing favors distributor-direct procurement for modular sensor components.
Product Type:
Vision sensors and force sensors flow primarily through mining system integrators in South Africa, whereas proximity and temperature sensors reach Nigerian manufacturing via industrial distributors.
- Vision Sensors:These devices capture optical data through CMOS or CCD arrays, processing images at frame rates exceeding sixty per second for real-time quality inspection. South African platinum extraction operations deploy these for ore sorting and personnel safety monitoring, driven by National Regulator for Compulsory Specifications mandates for automated hazard detection.
- Force Sensors:Strain-gauge or piezoelectric elements measure contact forces with resolutions down to millinewtons, enabling precise robotic manipulation. Egyptian and Nigerian hospitals are expanding collaborative robotics for surgical assistance and patient handling, creating concentrated demand for torque and pressure feedback systems.
- Proximity Sensors:Inductive and capacitive variants detect object presence without physical contact, operating reliably in dusty mining environments.
- Temperature Sensors:Thermocouple and RTD-based devices monitor thermal conditions in process equipment across Moroccan automotive plants.
By volume, proximity sensors lead due to ubiquitous deployment in material handling. By growth pace, force sensors are climbing the fastest as healthcare robotics expand.
End User:
Cost tier stratification separates premium-certified healthcare deployments from price-optimized agricultural and educational procurement.
- Healthcare Facilities:Surgical robotics and patient handling systems in Cairo and Lagos hospitals demand ISO-certified force and vision sensors with electromagnetic compatibility validation.
- Manufacturing Units:Automotive component plants in Morocco and Nigeria source proximity and vision sensors through unbundled distributor channels, bypassing traditional system integrators.
- Agricultural Sector:Kenyan and Ethiopian farming operations deploy ultrasonic and RFID sensors for livestock monitoring and crop automation.
- Educational Institutions:South African technical universities and Egyptian engineering programs acquire entry-level sensor kits for robotics training curricula.
Manufacturing units generate the highest shipment volumes. Healthcare facilities show the steepest expansion trajectory as surgical robotics penetrate North and West Africa.
Technology:
Application requirements determine technology selection, with obstacle detection favoring established infrared while precision metrology shifts toward laser systems.
- Infrared:Passive thermal and active infrared systems dominate personnel detection in South African mining safety applications, with decades of proven dust-penetration capability.
- Laser:Time-of-flight and structured light systems enable sub-millimeter dimensional accuracy for precision machining workflows in South African automotive component manufacturing.
- Ultrasonic:Cost-effective distance measurement serves agricultural automation and basic material handling across East African industrial parks.
- RFID:Radio-frequency identification tracks work-in-progress inventory and automated guided vehicle routing in Nigerian packaging facilities.
Infrared technology holds the largest installed base. Laser systems are gaining share fastest as LiDAR hardware converges with industrial ethernet protocols.
Application:
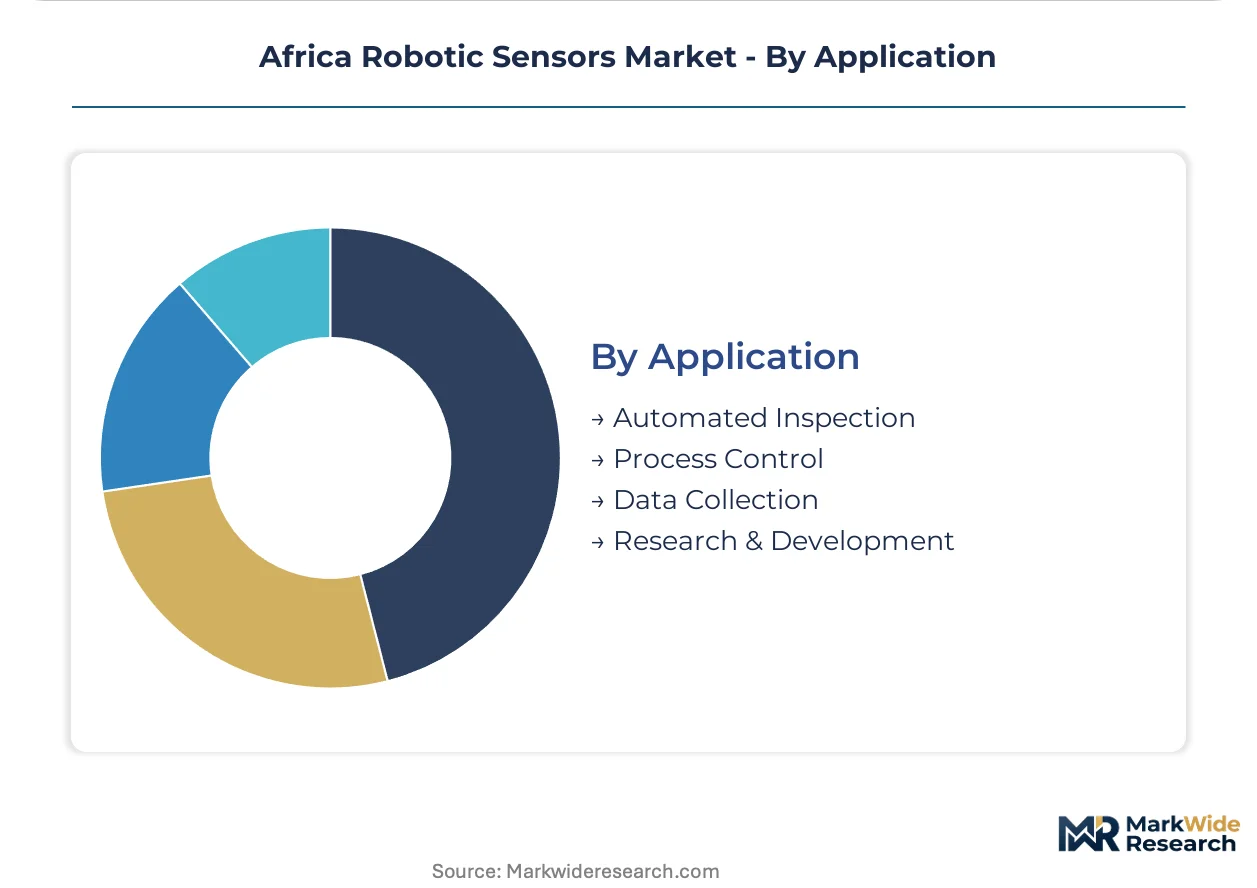
Customer type splits between capital-intensive process industries seeking integrated solutions and research-oriented buyers prioritizing configurability.
- Automated Inspection:Vision-guided quality control systems in Moroccan automotive plants detect surface defects and dimensional deviations at production line speeds.
- Process Control:Closed-loop sensor feedback regulates temperature, pressure, and position in South African mining and petrochemical operations.
- Data Collection:Environmental and operational telemetry from distributed sensor networks feeds predictive maintenance platforms.
- Research & Development:Universities and technology incubators in Egypt and South Africa prototype next-generation robotics applications using modular sensor platforms.
Automated inspection accounts for the greatest deployment volume. Research and development is expanding most quickly as regional innovation hubs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity splits sharply across the continent. South African mining buyers absorb premium pricing for certified safety systems, while Nigerian manufacturing procurement prioritizes cost-optimized modular configurations.
South Africa
Platinum and gold extraction operations drive sensor replacement cycles under National Regulator for Compulsory Specifications mandates. Johannesburg-Pretoria mining clusters deploy hybrid vision systems combining structured light with thermal imaging for personnel safety. Rustenburg platinum belt operations represent the continent's densest concentration of force and proximity sensors in hazardous automation.
Nigeria
Automotive component plants and packaging facilities concentrate demand for distributor-direct proximity and vision sensors. Standards Organization of Nigeria conformity assessments delay imports but reward localized assembly with expedited certification. Lagos and Kano manufacturing clusters show the most visible procurement disintermediation as tier-two manufacturers bypass system integrators.
Egypt
Cairo hospital networks expand collaborative robotics for surgical assistance and patient handling, driving ISO-certified force sensor demand. Egyptian Organization for Standardization and Quality tightened electromagnetic compatibility testing protocols, consolidating supplier lists to pre-certified vendors. Alexandria medical device manufacturing zones face steepest compliance cost increases from third-party validation requirements.
Morocco
Automotive component plants source proximity and vision sensors through unbundled distributor channels for quality inspection workflows. Tangier-Med industrial port zone anchors precision machining sensor deployments. Casablanca manufacturing clusters show rising laser-based system adoption for sub-millimeter dimensional accuracy in production line metrology.
Kenya
Livestock monitoring and crop automation applications deploy ultrasonic and RFID sensors across agricultural operations. Nairobi industrial parks remain below replacement-level sensor penetration, offering positioning for compliant entrants. Mombasa logistics corridors test automated guided vehicle routing systems with distributed sensor networks for inventory tracking.
Africa Robotic Sensors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Africa robotic sensors market. Integrated automation portfolios anchor large-scale mining deployments where full-stack solutions command premium positioning, while modular component specialists serve price-sensitive manufacturing through dense distributor networks. Three archetypes dominate: diversified industrial conglomerates with captive sensor divisions, pure-play connectivity specialists, and collaborative robotics originators with integrated sensing. Competitive moves concentrate on strategic partnerships for local certification compliance and portfolio diversification into harsh-environment specifications.
Within the integrated automation tier, ABB and FANUC Corporation exemplify archetypes serving divergent demand profiles. ABB anchors full-stack mining deployments through its automation portfolio breadth. FANUC Corporation occupies a position within automotive manufacturing channels through established distributor density. TE Connectivity Ltd. represents the specialized connectivity archetype, differentiated by harsh-environment solutions. These three companies illustrate how technology specialization, geographic channel control, and application-specific durability each carve defensible positions across African industrial automation.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| TE Connectivity Ltd. |
| Honeywell International Inc. |
| Baumer Group |
| Universal Robots |
| Omron Corporation |
| Sensata Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for MEMS wafer deliveries from East Asian foundries concentrate pricing power among integrated manufacturers serving South African mining automation, while Nigerian manufacturing buyers exploit distributor fragmentation to compress component margins. This inventory-to-pricing linkage intensifies as semiconductor input volatility forces African assemblers to choose between premium-certified stockpiling and price-optimized just-in-time procurement.
Pricing Analysis
After-sales service contracts and replacement parts revenue anchor lifetime value for established suppliers defending positions in South African platinum extraction. Three-tier pricing structure across premium-certified, standard-compliant, and economy-modular levels separates mining system integrators from Nigerian tier-two manufacturers. Cost compression in the economy tier is intensifying because consumer-grade vision modules displace purpose-built sensors in Lagos packaging applications. Healthcare facilities in Cairo show least price sensitivity due to Egyptian Organization for Standardization and Quality compliance mandates, while Kenyan agricultural buyers drive hardest bargain negotiations.
Supply Chain Analysis
Suez Canal transit disruptions and Red Sea routing alternatives expose African sensor assemblers to freight cost spikes from East Asian MEMS foundries. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, while specialty connectivity components source from Germany and the United States. Silicon wafer supplies, rare-earth magnetic materials, and industrial-grade epoxy packaging constitute critical input dependencies. Single-source vulnerability in MEMS process engineering talent forces manufacturers to import technical staff. Distribution runs through Johannesburg mining system integrators, Lagos industrial distributors, and Cairo medical device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward unbundled procurement as Nigerian automotive component plants bypass traditional system integrators, fragmenting what was once a consolidated two-step channel. This disintermediation concentrates negotiating leverage among tier-two manufacturers with direct Asian supplier relationships.
For Market Incumbents: Compound defensive positioning through backward integration into harsh-environment connectivity manufacturing and captive certification investment for Egyptian electromagnetic compatibility protocols. FANUC Corporation's distributor density in Morocco demonstrates how channel control resists price erosion from direct procurement trends. Threat substitution from consumer electronics vision modules demands accelerated R&D in sensor fusion architectures.
For New Entrants and Emerging Players: Differentiate on AfCFTA technical harmonization compliance to capture cross-border certification efficiency that incumbents with legacy national registrations cannot match. Ethiopia's industrial parks and Kenya's automotive component sector represent the most penetrable white-space geographies. A distributor-direct go-to-market angle bypassing integrator markups aligns with Lagos and Kano procurement patterns.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive sensor divisions underperforming against pure-play harsh-environment specialists. Long-term viability over the next decade hinges on positioning for healthcare robotics expansion and mining automation replacement cycles. Watch for AfCFTA technical regulation finalization as the inflection signal triggering consolidation among nationally certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Investment | Nigeria's Standards Organization of Nigeria rewards localized final assembly with expedited certification timelines. |
| Sensor Fusion R&D Partnership | Hybrid vision combining structured light with thermal imaging addresses South African mining dust-penetration requirements. |
| Certification Pre-Validation | Third-party electromagnetic compatibility testing with Egyptian Organization for Standardization and Quality consolidates supplier lists. |
| Distributor Network Expansion | Direct channel control in Lagos and Kano manufacturing clusters captures procurement disintermediation momentum. |
| Healthcare Robotics Integration | Force sensor development for Cairo and Lagos hospital surgical assistance systems targets steepest expansion trajectory. |
Research Methodology
Operator-level perspectives from mining automation engineers, hospital biomedical equipment managers, automotive component procurement leads, and industrial distributor principals anchored the qualitative base for this analysis. Primary interview findings triangulated against customs and trade data for sensor component imports, National Regulator for Compulsory Specifications enforcement records, SEC filings from listed automation suppliers, and AfCFTA technical regulation draft documents. Bottom-up demand modeling from end-user deployment data and top-down supply validation from manufacturer capacity disclosures converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across semiconductor input cost volatility scenarios and AfCFTA implementation timing variants over the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, technology category, and application workflow, with additional granularity on certification tier and channel structure. CAGRs derived from fitted growth curves applied to base-year market sizing, with cross-checks against mining automation capital expenditure cycles and healthcare robotics procurement pipelines.
Decision-makers should treat outputs as directional under assumptions of continued AfCFTA technical harmonization progress and stable East Asian semiconductor supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Egyptian electromagnetic compatibility enforcement intensity and Nigerian procurement channel evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
TMAH Concentration Monitor Market