
 Server Microprocessor Market | 2026-2036
Server Microprocessor Market Size, Share, and Industry Trends Forecast 2026-2036
Server Microprocessor Market Intelligence
The capital-intensity divergence between foundry-dependent designers and vertically integrated manufacturers is unwinding traditional competitive hierarchies in server silicon. Intel Corporation sustains massive fabrication investments across Arizona and Oregon to reclaim process leadership. Advanced Micro Devices, Inc. leverages fabless agility to capture share in cloud-optimized x86 sockets. NVIDIA Corporation dominates AI-training silicon through proprietary interconnect architectures that lock in hyperscaler procurement cycles.
A server microprocessor is a central processing unit engineered for rack-mounted and blade server environments, typically fabricated on advanced nodes with transistor densities exceeding 100 million per square millimeter and designed for 24/7 operation at thermal design powers between 150 and 400 watts. Its primary purpose is to execute concurrent virtualized workloads, database transactions, and distributed computing tasks across enterprise and cloud infrastructure. Multi-core configurations anchor mainstream revenue as cloud providers standardize on 64- to 96-core dies for general-purpose compute, while custom ASICs capture the fastest-expansion margin pool as Google, Amazon, and Microsoft develop in-house accelerators for search, recommendation, and training inference. The x86 architecture still occupies the majority of socket shipments, though ARM designs are positioning for material share in power-constrained edge data centers.
The U.S. CHIPS and Science Act directs federal subsidies toward domestic wafer fabrication, reshaping where server microprocessors can be legally sourced for federal cloud contracts. The EU F-Gas Regulation constrains fluorinated greenhouse gas use in semiconductor etching, forcing European-located fabs to retool process chemistry. China's dual carbon goals and GB standards on data center power usage effectiveness are capping facility expansion unless domestic chip efficiency improves markedly. Stakeholders must monitor which regulatory jurisdiction ultimately governs the carbon accounting of AI training clusters, as this will determine foundry location decisions and export compliance burdens for the next fabrication investment cycle.
Market Dynamics
Hyperscaler procurement cycles are compressing design-to-deployment timelines from 36 months to 18 months, forcing foundry capacity commitments before silicon validation completes. This structural acceleration favors vertically integrated manufacturers with captive wafer supply over fabless competitors dependent on third-party fabrication slots.
Growth Catalysts
- Generative AI training clusters:Cloud providers in the United States are deploying specialized accelerators alongside x86 hosts, creating socket demand for heterogeneous compute architectures.
- EU AI Act transparency mandates:Power consumption disclosure requirements are accelerating adoption of high-efficiency ARM-based designs in European edge data centers.
- CHIPS Act subsidies:Federal wafer fabrication incentives in Arizona and Texas are reshoring advanced node production for defense and intelligence cloud contracts.
Market Restraints
- EUV lithography equipment concentration:Single-source dependency on Dutch lithography systems creates 18-month lead time bottlenecks for sub-3nm process ramps.
- Fluorinated gas constraints:The EU F-Gas Regulation limits etching chemistry availability at European-located foundries, constraining capacity expansion.
- High-bandwidth memory supply:HBM3E stack shortages from Korean suppliers are throttling AI accelerator output regardless of logic die availability.
Strategic Opportunities
- India data center buildout:PLI scheme incentives for semiconductor assembly and test are positioning the country as a regional hub for mid-range server silicon packaging.
- Edge inference acceleration:5G base station deployments and autonomous vehicle fleets are creating demand for sub-75W TDP processors outside hyperscale data centers.
- Carbon accounting convergence:Scope 3 emissions tracking requirements from the EU CSRD are creating first-mover advantage for chipmakers with transparent supply chain carbon data.
Industry Challenges
- Packaging substrate shortage:ABF substrate capacity from Japanese suppliers trails advanced package demand by 30 percent, forcing allocation rationing among fabless designers.
- Legacy x86 software inertia:Enterprise workload migration to ARM architectures requires multi-year recompilation and validation cycles that delay procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Microprocessor Market |
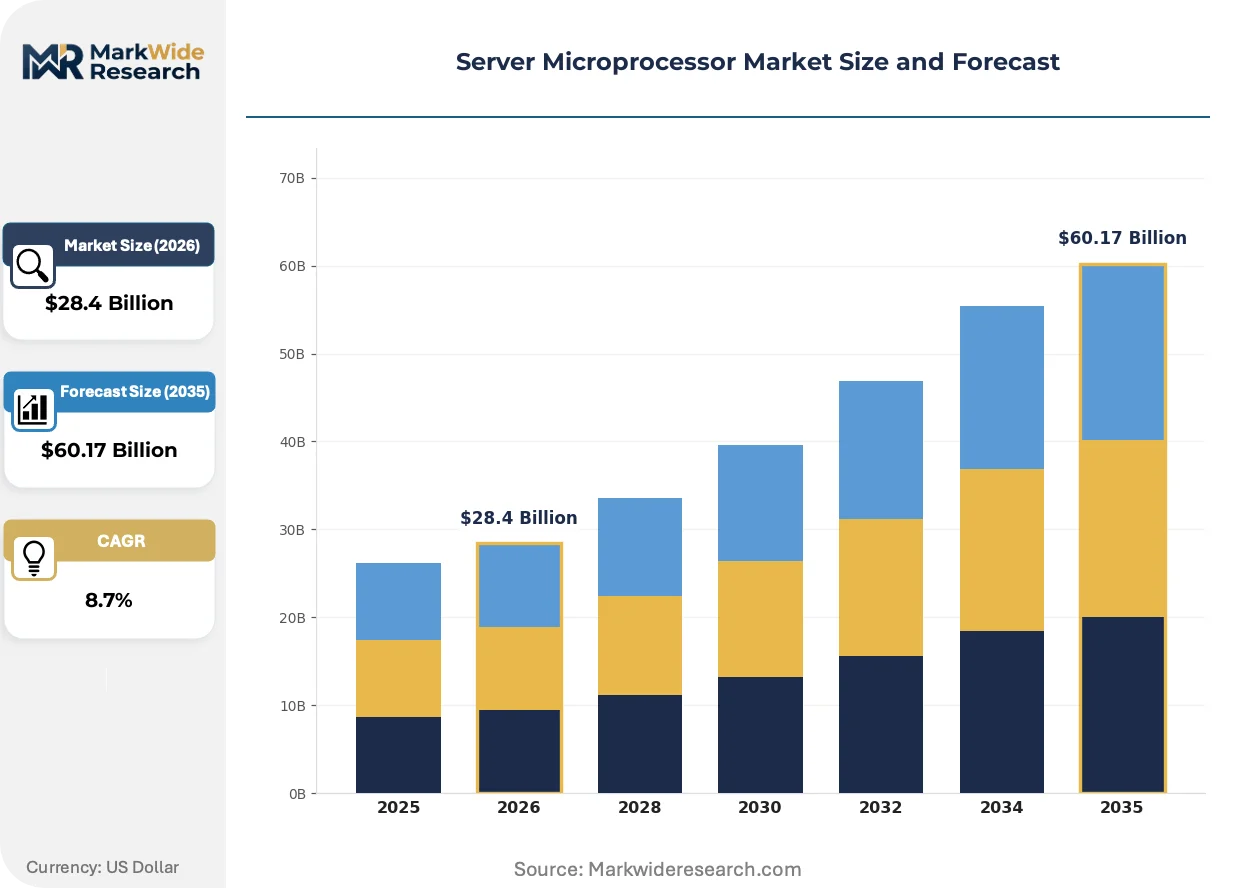
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Core, Multi-Core, Many-Core, Custom ASICs Architecture: x86, ARM, SPARC, RISC-V End User: Cloud Providers, Data Centers, Enterprises, Research Institutions Performance Metric: Compute Density, Thermal Efficiency, Bandwidth, Power Consumption |
| Companies Covered | Intel Corporation, Advanced Micro Devices, Inc., NVIDIA Corporation, Arm Ltd., Broadcom Inc., International Business Machines Corporation, Oracle Corporation, Qualcomm Incorporated, Marvell Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Microprocessor Market Strategic Shifts & Innovations
Silicon photonics integration is collapsing electrical interconnect power budgets while chiplets are fragmenting monolithic die economics. These converging forces are restructuring competitive advantage around packaging expertise rather than transistor density alone.
Optical I/O chiplets are supplanting copper SerDes in training cluster backplanes. Google and Microsoft are qualifying 800G optical links for rack-scale fabrics, eliminating signal integrity constraints that previously limited cluster scale. This transition is compressing NVIDIA's interconnect moat and opening socket opportunities for second-source accelerator vendors.
The EU F-Gas Regulation is forcing etching chemistry substitutions at European-located foundries. Process engineers are qualifying C4F6 and C3F8 alternatives for dielectric etch steps, adding 6-9 months to process qualification timelines. Memory manufacturers with European DRAM fabs are absorbing the highest compliance costs and accelerating migration to Asian-located expansion plans.
Hyperscalers are consolidating procurement around direct foundry relationships, bypassing traditional distributor channels. Amazon Web Services and Meta Platforms now negotiate wafer starts directly with TSMC and Samsung Foundry, securing allocation priority through volume commitments. This disintermediation is most advanced in the United States, where CHIPS Act domestic content requirements further incentivize direct supplier engagement over distributor-mediated sourcing.
Server Microprocessor Market Segmentation
Server microprocessor segmentation reveals how architectural choices translate into divergent margin structures. Product configurations and end-user procurement patterns determine which silicon categories capture premium pricing versus commodity volume.
Product Type:
Margin pools concentrate in heterogeneous compute configurations where general-purpose cores pair with specialized accelerators.
- Multi-Core:Dies integrating 64 to 96 cores on advanced nodes anchor mainstream cloud procurement. AWS and Microsoft Azure standardize these configurations for general-purpose virtual machine instances, with socket demand driven by hyperscale refresh cycles in Northern Virginia and Texas.
- Custom ASICs:Google TPU and Amazon Trainium architectures displace merchant silicon in training inference workloads. These designs capture the steepest expansion trajectory as procurement shifts toward in-house accelerators for search, recommendation, and generative AI clusters.
- Single-Core:Legacy enterprise applications and specialized real-time systems retain modest deployment in financial transaction processing.
- Many-Core:High-throughput parallel workloads in scientific simulation and media encoding utilize dense core arrays with shared memory architectures.
Multi-Core configurations hold installed capacity. Custom ASICs are rotating up the share rankings.
Architecture:
Socket economics split between mature software ecosystems and emerging efficiency-focused designs.
- x86:Dominant instruction set architecture with decades of enterprise software optimization. Intel and AMD supply the vast majority of cloud and on-premise servers, with procurement inertia preserving share despite power efficiency disadvantages.
- ARM:Neoverse-based designs from Ampere Computing and AWS Graviton are gaining hyperscale traction. European edge data centers under EU AI Act power disclosure mandates are expanding ARM adoption fastest.
- SPARC:Oracle-maintained architecture retains presence in legacy database appliances and vertical enterprise stacks.
- RISC-V:Open instruction set emerging in storage controllers and specialized accelerators where software stack maturity constraints limit general-purpose deployment.
x86 maintains deployment breadth. ARM is climbing the fastest in new socket wins.
End User:
Procurement scale and technical sophistication create tiered pricing structures across buyer categories.
- Cloud Providers:AWS, Microsoft Azure, and Google Cloud negotiate direct foundry relationships and custom silicon development. Their volume commitments drive process node transitions and packaging technology roadmaps.
- Data Centers:Colocation operators and wholesale facility providers balance x86 standardization against emerging ARM efficiency options for multi-tenant workloads.
- Enterprises:Fortune 500 IT departments prioritize software compatibility and vendor support over raw performance, sustaining premium pricing for established x86 platforms.
- Research Institutions:National laboratories and university clusters drive demand for many-core configurations and specialized interconnect fabrics in climate modeling and particle physics simulation.
Cloud Providers command the largest volume commitments. Data Centers are rotating up the share rankings as edge buildout accelerates.
Performance Metric:
Procurement evaluation criteria are shifting from raw compute throughput toward total cost of ownership metrics.
- Thermal Efficiency:Performance per watt determines facility-level power constraints and carbon accounting under EU CSRD Scope 3 tracking requirements. This metric now gates procurement decisions for European-located clusters.
- Compute Density:Cores per socket and per rack unit drive data center footprint economics, with hyperscalers optimizing for maximum throughput in constrained floor space.
- Bandwidth:Memory and interconnect throughput limits training cluster scale, with HBM3E stack availability currently throttling accelerator output regardless of logic performance.
- Power Consumption:TDP ratings between 150 and 400 watts define cooling infrastructure requirements and operational expenditure profiles for 24/7 deployment.
Thermal Efficiency holds regulatory priority. Compute Density is rotating up the share rankings as facility constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where hyperscale procurement volumes command foundry allocation priority, while European buyers absorb compliance premiums under EU AI Act disclosure mandates.
United States
Hyperscale cloud providers in Northern Virginia and Texas are expanding data center footprints to support generative AI training clusters. The CHIPS Act directs federal subsidies toward domestic wafer fabrication in Arizona and Oregon. Intel Corporation maintains fabrication investments across these states to reclaim process leadership for defense and intelligence cloud contracts.
China
Domestic chip designers are accelerating server silicon development under GB standards on data center power usage effectiveness. The dual carbon goals cap facility expansion unless domestic chip efficiency improves markedly. Yangtze River Delta clusters around Shanghai concentrate advanced packaging capacity for mid-range server processors.
Germany
European edge data centers under EU AI Act power disclosure mandates are expanding ARM-based server deployments. The EU F-Gas Regulation constrains fluorinated greenhouse gas use in semiconductor etching, forcing retooling of process chemistry. Dresden hosts advanced foundry operations serving regional cloud infrastructure demand.
India
PLI scheme incentives for semiconductor assembly and test are positioning the country as a regional hub for mid-range server silicon packaging. Karnataka and Telangana are attracting data center investments from global cloud providers seeking geographic diversification. Bangalore clusters house design centers supporting custom ASIC development for hyperscaler clients.
Japan
Memory manufacturers with European DRAM fabs are accelerating migration to Asian-located expansion plans under F-Gas compliance pressure. METI industrial policy supports advanced packaging substrate development. Kyushu hosts memory fabrication clusters critical for HBM3E supply to AI accelerator vendors.
Server Microprocessor Market Key Industry Players
Concentration sits with vertically integrated manufacturers possessing captive wafer supply, while fabless designers compete for third-party fabrication allocation. The vendor base splits between established x86 incumbents and emerging ARM-based challengers. Three archetypes dominate: integrated fabricators with in-house production, fabless designers leveraging foundry agility, and hyperscale captive silicon developers. Competitive moves center on process node transitions and direct foundry relationship consolidation.
Within the integrated fabrication tier, Intel Corporation represents the capital-intensive model of captive supply investment. Among fabless competitors, Advanced Micro Devices, Inc. and NVIDIA Corporation exemplify divergent strategies for cloud-optimized and AI-training silicon respectively. These three anchors illustrate how competitive positioning fragments across manufacturing model and workload specialization.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices, Inc. |
| NVIDIA Corporation |
| Arm Ltd. |
| Broadcom Inc. |
| International Business Machines Corporation |
| Oracle Corporation |
| Qualcomm Incorporated |
| Marvell Technology Group |
| Others |
Cost & Logistics Intelligence
Foundry utilization rates above 90 percent at TSMC and Samsung Foundry compress third-party fabrication slot availability and establish price floors for fabless designers. This capacity scarcity simultaneously elevates margins for vertically integrated manufacturers with captive wafer supply and forces procurement premiums for hyperscalers requiring advanced node allocation.
Pricing Analysis
Configured-to-order silicon commands 40-60 percent premiums over standard catalog SKUs as cloud providers negotiate custom core counts, interconnect configurations, and power-binning specifications. Pricing stratifies across premium, standard, and economy tiers based on process node maturity and volume commitment scale. Cost compression in mainstream x86 sockets is intensifying because AMD and Intel compete for hyperscale refresh cycles with aggressive die-per-wafer economics. Enterprise IT departments exhibit highest price sensitivity due to budget constraints and software migration inertia, while cloud providers prioritize total cost of ownership over unit socket pricing.
Supply Chain Analysis
Inventory buffers for EUV lithography systems and advanced packaging substrates extend to 18-24 months, constraining rapid capacity scaling regardless of downstream demand signals. Taiwan, South Korea, and the United States concentrate leading-edge wafer fabrication, while Japan and Southeast Asia anchor specialized materials and assembly-test operations. The supply chain draws from fluorinated gases for etching chemistry, silicon wafers, and high-bandwidth memory stacks as critical inputs. Single-source dependency on Dutch lithography equipment creates structural vulnerability to export control disruptions. Distribution runs through direct foundry relationships rather than traditional distributor channels as hyperscalers consolidate procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server microprocessor demand sits in early-cycle expansion as generative AI training clusters drive heterogeneous compute adoption beyond traditional x86 refresh patterns. Penetration of custom ASICs and ARM-based designs remains below 25 percent of socket volume, leaving substantial runway for architectural displacement.
For Market Incumbents: Secure captive wafer supply through foundry partnership prepayments or in-house fabrication investments in Arizona and Texas to defend against fabless competitors losing allocation priority. Lock hyperscalers into multi-year socket commitments before silicon photonics integration commoditizes interconnect differentiation. The CHIPS Act domestic content requirements create leverage for Intel to reclaim defense and intelligence cloud contracts.
For New Entrants and Emerging Players: Differentiate on thermal efficiency metrics under EU AI Act disclosure mandates to capture European edge data center procurement. Target India's PLI-subsidized assembly and test ecosystem for mid-range server silicon packaging cost advantages. Position ARM-based designs against legacy x86 software inertia in colocation and wholesale facility segments where workload flexibility exceeds enterprise compatibility requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors packaging expertise over transistor density as chiplets and optical I/O reshape competitive moats. Five-to-ten year viability hinges on securing direct foundry relationships rather than distributor-mediated sourcing. Watch hyperscaler custom silicon development timelines as the inflection indicator for merchant silicon displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Relationship Consolidation | AWS and Meta bypass distributors to secure TSMC allocation priority through volume wafer commitments. |
| Silicon Photonics Integration | Google qualifies 800G optical links to collapse NVIDIA's interconnect moat in training clusters. |
| Custom ASIC Development | Amazon Trainium and Google TPU displace merchant accelerators in search and recommendation workloads. |
| CHIPS Act Domestic Fabrication | Intel captures federal subsidies for Arizona and Oregon fabs serving defense cloud contracts. |
| EU F-Gas Compliance Retooling | European foundries absorb 6-9 month process qualification delays for alternative etching chemistry. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with cloud procurement executives, foundry account managers, semiconductor packaging engineers, and hyperscaler silicon architects; and secondary validation against SEC 10-K filings, hyperscaler capex disclosures, foundry utilization reports, and EU regulatory filings. Bottom-up triangulation against top-down market sizing anchored volume and value estimates across the projection horizon.
Across the modeling period, the analytical framework segmented demand by architecture type, product configuration, end-user procurement tier, and regional regulatory cluster. CAGRs were derived from rolling average capacity expansion schedules and hyperscaler server deployment disclosures. Forecast inputs incorporated EUV equipment lead times, HBM3E supply constraints, and CHIPS Act subsidy allocation timelines as industry-specific variables.
Material uncertainties — export control expansion, fluorinated gas supply disruptions, and hyperscaler in-sourcing acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about foundry capacity ramps and architectural transition speeds that could revise materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
China Edge AI Processor Market