
 Automotive Smart Chip Market | 2026-2036
Automotive Smart Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Chip Market Insights
Software-defined vehicle feature subscriptions is recalibrating how automotive smart chip value gets captured and monetized across the lifecycle. Infineon Technologies AG leverages its power semiconductor dominance to anchor high-voltage electrification platforms. NXP Semiconductors sustains broad microcontroller portfolios that span gateway and domain controller architectures. Qualcomm Technologies competes aggressively in digital cockpit and automated driving compute, extending its mobile silicon expertise into automotive-grade silicon.
Automotive smart chips are semiconductor devices engineered to operate across temperature extremes from negative forty to one hundred fifty degrees Celsius while meeting ASIL-D functional safety grades, serving as the computational substrate for powertrain control, sensor fusion, and in-vehicle networking. Microcontrollers retain the largest revenue share due to their ubiquity across body electronics and safety domains, though processors for ADAS and autonomous driving represent the fastest-growing margin pool. Mixed-signal technology bridges analog sensor inputs with digital processing pipelines, creating differentiated positions for suppliers who integrate both domains on single die architectures.
The EPA tailpipe standards in the United States, the EU Green Deal vehicle emissions framework, and China's MIIT new energy vehicle mandates collectively force chip architects to optimize for energy efficiency and thermal performance under stricter environmental compliance. ISO 26262 functional safety requirements and the EU AI Act's risk classification for automated driving systems further constrain design freedom while creating certification barriers for new entrants. Stakeholders must monitor how regulatory divergence between Washington, Brussels, and Beijing fragments validation requirements and multiplies qualification costs for unified product platforms.
Market Dynamics
Functional safety mandates under ISO 26262 and the EU's Vehicle General Safety Regulation are compressing design cycles while elevating validation costs for automotive smart chip suppliers serving electrification and automated driving platforms.
Growth Catalysts
- EU Green Deal vehicle emissions framework:Stringent CO2 targets force OEMs toward battery-electric architectures that demand high-voltage power semiconductors and intelligent battery management ICs.
- Sensor fusion compute:Multi-modal perception stacks integrating camera, radar, and lidar inputs require dedicated AI accelerators with deterministic latency guarantees.
- Germany-Japan-US semiconductor clusters:Concentrated design expertise and captive foundry partnerships in these geographies accelerate time-to-market for ASIL-D qualified devices.
Market Restraints
- 300mm silicon wafer supply concentration:Taiwan and South Korea dominate advanced node production, exposing automotive chip vendors to geopolitical disruption and allocation constraints.
- ISO 26262 certification timelines:Functional safety qualification cycles extending eighteen to thirty months delay revenue recognition for new entrants.
- Silicon carbide substrate costs:Wide-bandgap material scarcity inflates bill-of-materials for traction inverters and onboard chargers versus silicon IGBTs.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives attract semiconductor packaging and testing investments to serve domestic EV manufacturing.
- Chiplets and 3D integration:Disaggregated die architectures enable mix-and-match IP blocks across process nodes, reducing monolithic SoC development risk.
- Software-defined vehicle subscriptions:Over-the-air feature activation creates recurring revenue streams tied to compute headroom in domain controller silicon.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-D certified architects and verification engineers command premium compensation, constraining R&D scaling.
- Legacy vehicle network integration:CAN and LIN protocol coexistence with Ethernet backbone architectures complicates gateway chip validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Chip Market |
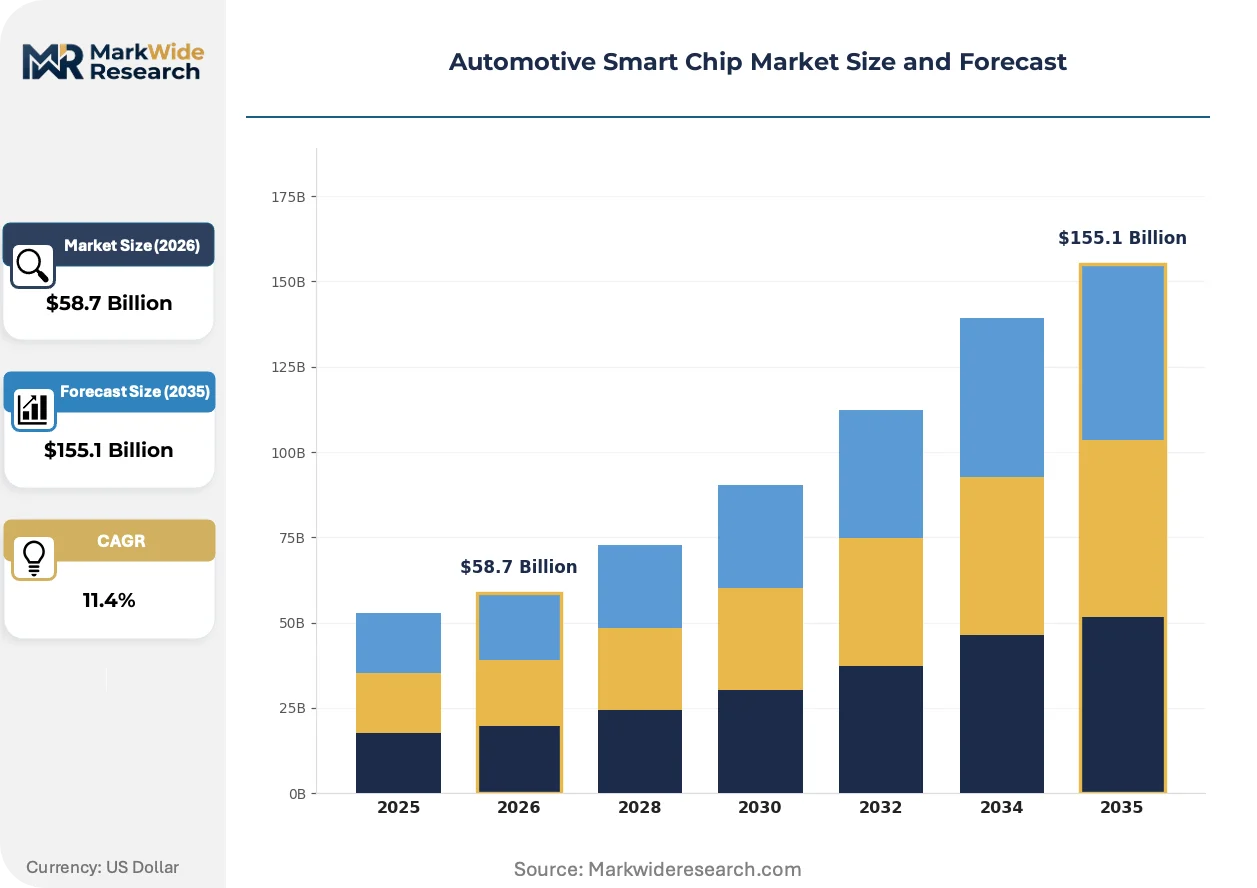
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Power Amplifiers, Sensors, Processors Technology: Analog, Digital, Mixed Signal, Embedded Application: Infotainment Systems, Advanced Driver Assistance Systems, Engine Control Units, Telematics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Texas Instruments, Renesas Electronics Corporation, ON Semiconductor, Robert Bosch GmbH, Analog Devices, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Chip Market Trends and Innovations
Silicon architectures are fragmenting across domain-specific accelerators as software-defined vehicle platforms demand heterogeneous compute with deterministic real-time guarantees alongside AI inference throughput.
Chiplets with standardized die-to-die interconnects are absorbing discrete functions previously integrated in monolithic SoCs. Tier-1 suppliers and OEM silicon teams adopt chiplet-based domain controllers to reduce non-recurring engineering costs and accelerate variant proliferation. This disaggregation is absorbing margin from traditional microcontroller vendors while enabling fabless entrants to specialize in AI or sensor interface chiplets.
The EU AI Act's risk classification for automated driving systems imposes conformity assessment burdens on chip suppliers whose silicon executes safety-critical neural networks. Automotive semiconductor vendors must document algorithmic transparency and fail-operational behavior to satisfy notified body scrutiny. High-autonomy compute platforms face the steepest compliance escalation, with German and French regulators already interpreting Article 6 thresholds conservatively.
Fleet operators and mobility service providers now specify chip longevity and upgradeability in procurement contracts rather than accepting fixed hardware roadmaps. This behavior shift pressures semiconductor suppliers to architect socket-compatible successors and extended availability commitments. The transformation is most visible in North American commercial vehicle and robotaxi deployments where total cost of ownership calculations dominate hardware selection.
Automotive Smart Chip Market Segmentation
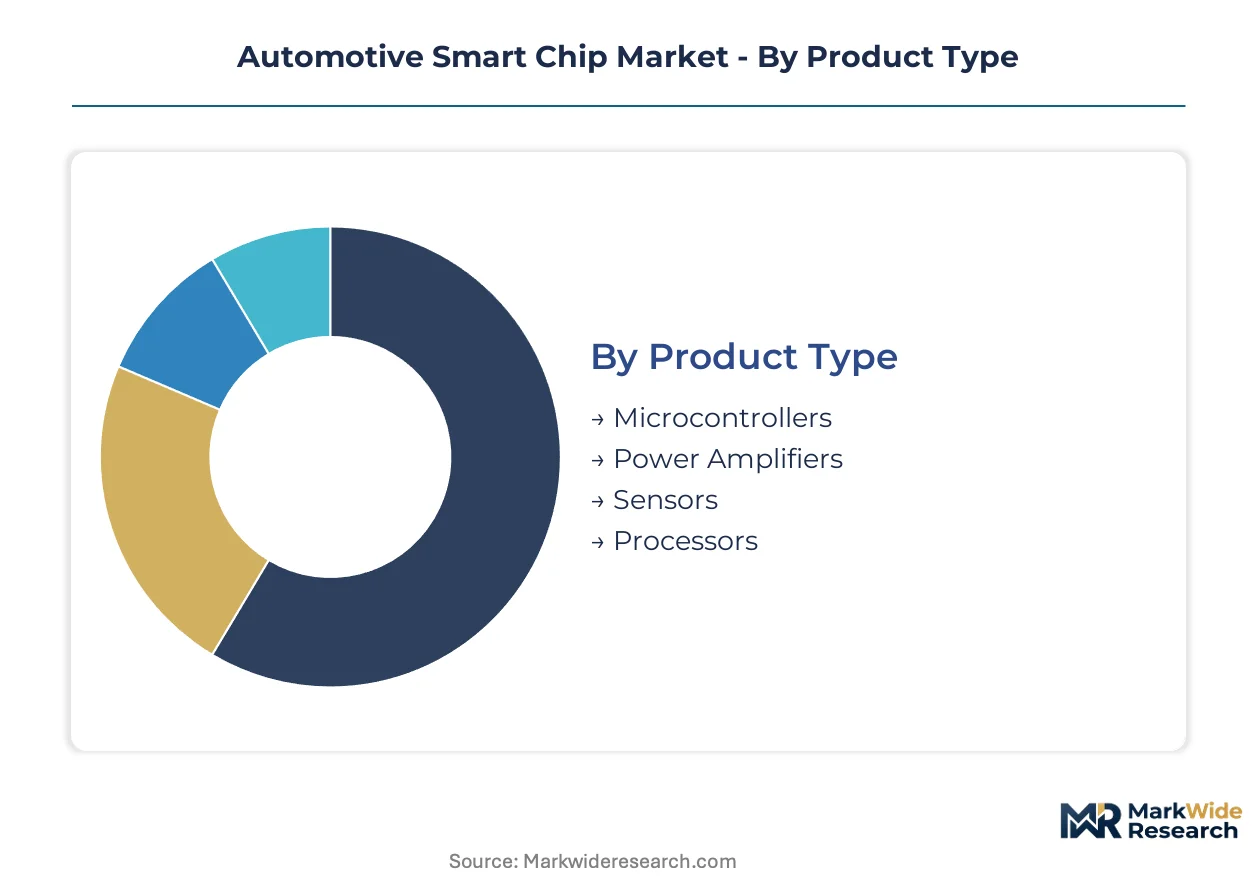
Automotive smart chip segmentation reveals how certification burdens concentrate differently across product architectures. ISO 26262 ASIL grades and the EU AI Act's risk tiers fragment validation pathways, forcing suppliers to align R&D portfolios with specific compliance cost structures.
Product Type:
Microcontrollers and processors carry ASIL-D certification requirements under ISO 26262, while power amplifiers and sensors face divergent thermal and electromagnetic compatibility testing protocols.
- Microcontrollers:These devices integrate CPU cores with embedded memory and peripheral interfaces on single die architectures. German and Japanese OEMs concentrate procurement for body electronics and safety-critical domains where deterministic real-time response is mandatory. Functional safety validation cycles extend eighteen to thirty months, creating certification barriers for new entrants.
- Processors:High-performance compute engines execute AI inference for automated driving and digital cockpit visualization. Demand concentrates in California and Bavaria where robotaxi developers and premium OEMs specify tera-operations-per-second throughput with deterministic latency guarantees. The EU AI Act's conformity assessment requirements impose additional algorithmic transparency documentation burdens.
- Power Amplifiers:High-voltage silicon carbide and IGBT modules drive traction inverters and onboard chargers.
- Sensors:MEMS and CMOS devices capture acceleration, pressure, and environmental data for fusion algorithms.
Leading the category by volume: Microcontrollers. Growing fastest: Processors.
Technology:
Cost tier stratification separates analog legacy designs from mixed-signal premium architectures requiring advanced node access.
- Mixed Signal:These architectures bridge analog sensor inputs with digital processing pipelines on unified die geometries. Infineon and NXP dominate positions where integration reduces bill-of-materials and electromagnetic interference susceptibility. German automotive clusters drive specification standards for resolver-to-digital conversion and battery monitoring interfaces.
- Digital:CMOS logic arrays execute deterministic control algorithms with nanosecond precision. Japanese OEMs and Tier-1 suppliers concentrate procurement for powertrain and chassis control domains where ISO 26262 ASIL-D grades are non-negotiable. Taiwan and South Korea foundry allocation constraints limit supply elasticity for advanced node variants.
- Analog:Continuous signal processing for power management and signal conditioning.
- Embedded:Application-specific hardwired logic for dedicated functional blocks.
Highest margin concentration: Mixed Signal. Steepest expansion trajectory: Digital.
Application:
Application segmentation maps directly to regulatory jurisdiction, with EPA tailpipe standards, EU Green Deal frameworks, and China's MIIT mandates each favoring distinct compute architectures.
- Advanced Driver Assistance Systems:Multi-modal perception stacks integrate camera, radar, and lidar inputs through dedicated AI accelerators. US and German regulators enforce divergent testing protocols for automated lane-keeping and emergency braking, fragmenting validation matrices. Sensor fusion compute requirements escalate with each SAE autonomy level advancement.
- Infotainment Systems:Digital cockpit platforms merge instrument clusters, navigation, and entertainment through high-resolution display controllers. Qualcomm's Snapdragon dominance reflects mobile silicon expertise transferred to automotive-grade thermal and vibration specifications. Over-the-air update capabilities now feature in procurement contracts from North American and European OEMs.
- Engine Control Units:Powertrain management processors optimize combustion and electrified propulsion efficiency.
- Telematics:Cellular and satellite connectivity modules enable fleet management and emergency services.
Dominant revenue share: Engine Control Units. Fastest share gain: Advanced Driver Assistance Systems.
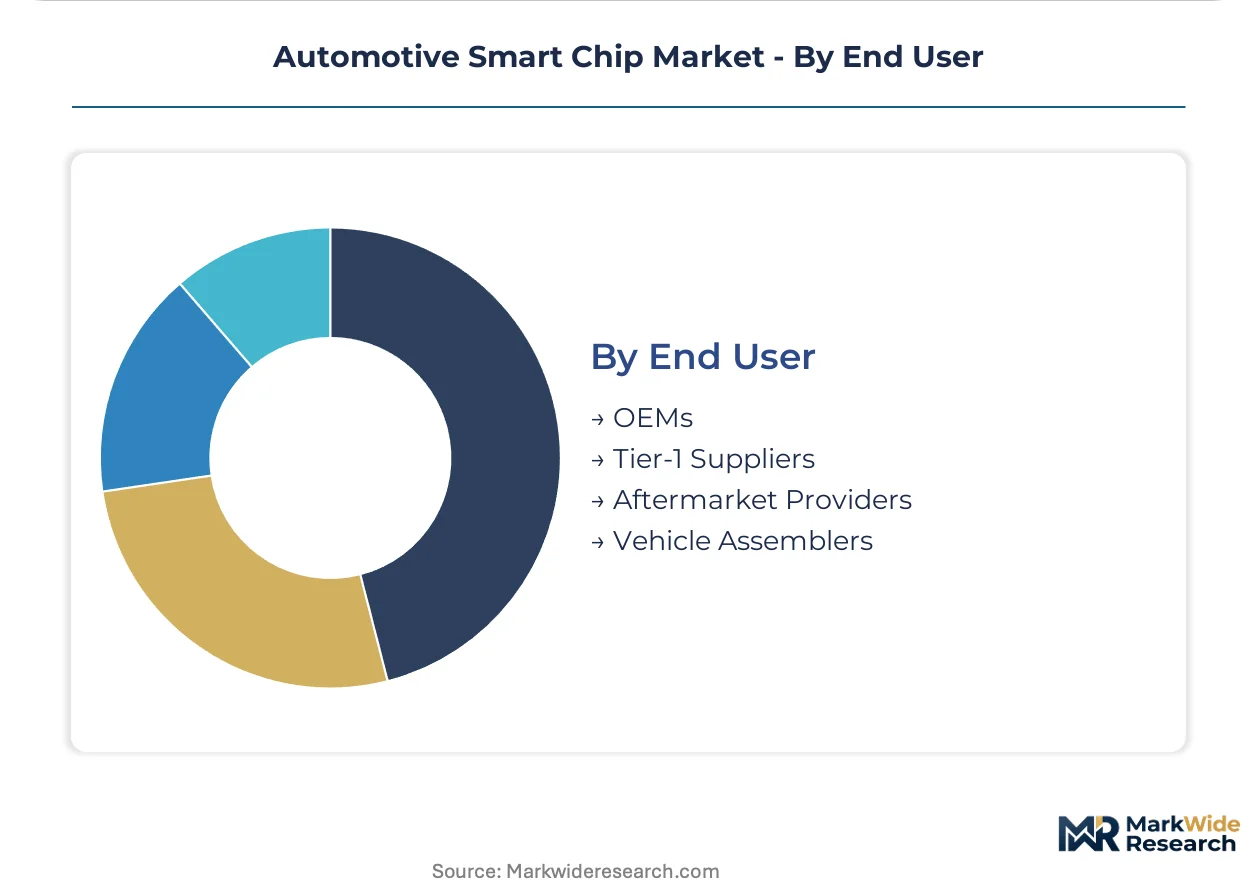
End User:
Customer type determines procurement leverage, with captive silicon teams at major OEMs displacing traditional Tier-1 supplier relationships.
- OEMs:Volkswagen, Toyota, and General Motors operate internal semiconductor architecture groups that specify domain controller designs and negotiate direct foundry allocation. Vertical integration into chip design accelerates with software-defined vehicle platform investments. These organizations capture margin previously retained by component suppliers.
- Tier-1 Suppliers:Bosch, Continental, and Denso maintain broad microcontroller portfolios spanning gateway and safety domains. Their historical ASIL-D certification expertise preserves relevance even as OEM silicon teams expand. German and Japanese Tier-1s leverage captive foundry partnerships to secure wafer supply.
- Aftermarket Providers:Independent distributors serve repair networks and vehicle modification specialists.
- Vehicle Assemblers:Contract manufacturers integrate chips from approved vendor lists without direct semiconductor procurement.
Procurement volume leader: OEMs. Margin compression target: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors the densest concentration of automotive semiconductor engineering talent, with Infineon and BMW co-located design teams shaping domain controller specifications for European electrification platforms.
United States
Detroit's electrification pivot and Silicon Valley's robotaxi deployments drive divergent chip procurement. EPA tailpipe standards under the Inflation Reduction Act accelerate battery-electric vehicle mandates. Austin and Phoenix clusters concentrate ADAS processor validation labs serving domestic OEM captive silicon programs.
Germany
Stuttgart and Ingolstadt OEMs specify ASIL-D qualified microcontrollers for powertrain and chassis domains. The EU's Vehicle General Safety Regulation and KBA enforcement tighten functional safety documentation requirements. Dresden's silicon foundry corridor anchors captive wafer supply agreements with Tier-1 suppliers.
China
MIIT new energy vehicle mandates force local chip procurement quotas for domestic EV platforms. Shanghai and Shenzhen clusters concentrate fabless design houses specializing in battery management ICs. Yangtze River Delta packaging facilities absorb regional substrate supply for traction inverter modules.
Japan
Toyota and Honda vertical integration strategies displace traditional Tier-1 microcontroller relationships. METI semiconductor revitalization subsidies accelerate domestic 300mm wafer capacity investments. Nagoya and Hiroshima industrial corridors concentrate power semiconductor packaging for hybrid powertrain applications.
South Korea
Hyundai and Kia software-defined vehicle platforms demand high-bandwidth memory integration with AI accelerators. Seoul government chip industry incentives attract foreign fabless design centers. Suwon and Pyeongtaek foundry complexes secure advanced node allocation for automotive-grade silicon.
Automotive Smart Chip Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Integrated device manufacturers retain captive foundry economics while fabless specialists access Taiwan and South Korea advanced nodes through purchase commitments. Three archetypes dominate: diversified semiconductor conglomerates with automotive divisions, pure-play automotive chip specialists, and mobile-compute transplants adapting consumer silicon for vehicle-grade specifications. Competitive moves concentrate on strategic foundry partnerships securing wafer allocation and vertical integration into chiplet packaging capabilities.
Within the diversified conglomerate tier, Infineon Technologies AG and NXP Semiconductors exemplify positions built through decades of automotive certification accumulation and captive manufacturing assets. Qualcomm Technologies occupies a distinct transplant archetype, leveraging mobile silicon expertise into digital cockpit and automated driving compute domains where thermal and vibration specifications diverge sharply from consumer applications.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Renesas Electronics Corporation |
| ON Semiconductor |
| Robert Bosch GmbH |
| Analog Devices |
| Qualcomm Technologies |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate costs cascade from mining operations in China through wafer fabrication in Taiwan to final module pricing for German traction inverter suppliers, stratifying automotive smart chip procurement across ASIL-D certified premium tiers and commodity microcontroller economy segments.
Pricing Analysis
Functional safety throughput anchors value-based pricing, with OEMs paying premiums for deterministic latency guarantees in automated driving compute. Three-tier pricing structure separates ASIL-D qualified processors from ASIL-B standard devices and uncertified economy microcontrollers. Pricing pressure stems from ISO 26262 certification timelines extending eighteen to thirty months, compressing margins for new entrants. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity, while premium passenger OEMs prioritize performance over unit cost.
Supply Chain Analysis
MIIT local-content mandates in China and India's PLI scheme for automotive electronics are reshaping sourcing patterns away from Taiwan-South Korea concentration. Advanced node production draws from 300mm silicon wafer supply anchored in Hsinchu and Pyeongtaek, with silicon carbide substrates feeding from Chinese mining operations. Single-source vulnerability concentrates in EUV lithography equipment. Distribution runs through captive foundry partnerships between German Tier-1 suppliers and Dresden-based wafer fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive smart chip competition is accelerating into a vertical-integration race, with OEM silicon teams and Tier-1 suppliers competing to capture margin through captive foundry economics and in-house packaging capabilities.
For Market Incumbents: Cement ASIL-D certification moats by accelerating functional safety engineer recruitment in Munich and Nagoya corridors. Deepen backward integration into 300mm wafer supply through long-term offtake agreements with Taiwan foundries, defending against fabless AI accelerator entrants targeting digital cockpit sockets.
For New Entrants and Emerging Players: The EU AI Act's risk classification for automated driving systems in Europe opens a window for algorithmic transparency documentation specialists. Target battery management IC procurement for domestic EV platforms in India and China where local-content rules displace incumbent suppliers. Lead with chiplet-based domain controller architectures to reduce non-recurring engineering costs.
For Investors and Strategic Acquirers: OEM captive silicon team formation is the leading indicator that traditional Tier-1 supplier relationships are structurally weakening. Frame long-term viability around suppliers controlling heterogeneous compute integration with deterministic real-time guarantees. Target acquisition archetypes: mixed-signal specialists with resolver-to-digital conversion expertise. Watch for MIIT procurement quota enforcement as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Over-the-air feature activation creates recurring revenue tied to compute headroom in domain controllers. |
| Battery Supply Agreement | Long-term silicon carbide module contracts secure traction inverter allocation for EU Green Deal compliance. |
| Geographic Manufacturing Footprint | Dresden foundry expansion anchors captive wafer supply for German OEM electrification platforms. |
| Platform Standardization | Chiplet interconnect standards reduce monolithic SoC development risk across heterogeneous compute architectures. |
| Charging Infrastructure Partnership | Onboard charger semiconductor procurement scales with DC fast-charging network deployment mandates. |
Research Methodology
Document review covered SEC 10-K semiconductor filings, IHS Markit vehicle production databases, and EU regulatory submissions, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, foundry planning officers, and automotive aftermarket distributors. Bottom-up demand modeling triangulated against top-down semiconductor consumption estimates across vehicle class, propulsion architecture, and content per vehicle segmentation.
Cross-reference between historical certification timeline patterns and panel input from functional safety engineers shaped the analytical framework across the projection horizon. CAGRs derived from unit-volume elasticity models incorporating electrification penetration curves and ADAS content-per-vehicle trajectories. Forecast inputs included MIIT new energy vehicle mandate enforcement schedules and EPA tailpipe standard implementation pacing.
Caveats apply where ISO 26262 certification timeline extensions or Taiwan Strait logistics disruptions could materially shift the outlook. Forecasts reflect assumptions about foundry allocation stability and silicon carbide substrate supply expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Battery Monitoring IC Market