
 Global Semiconductor Back-End Equipment Market | 2026-2036
Global Semiconductor Back-End Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Back-End Equipment Market Foresight
Market Context
IDM units are collapsing their legacy wire bonding purchases as AI accelerator foundries scale chiplet-based advanced packaging lines. ASM Pacific Technology Limited leverages its die bonder portfolio to dominate heterogeneous integration deployments across Southeast Asia. Kulicke & Soffa Industries anchors wire bonding maintenance revenue in mature automotive Tier-1 supply chains where flip chip conversion remains uneconomical. BE Semiconductor Industries specializes in high-accuracy die attach systems that compete for SiC power module contracts from industrial automation buyers.
Technical Definition and Segments
Semiconductor back-end equipment encompasses the machinery used to singulate, interconnect, encapsulate, and electrically test finished wafers into packaged devices, with wire bonders operating at placement accuracies below 3 micrometers and die bonders handling substrates up to 300mm. This equipment transforms bare dies into functional components for downstream integration into circuit boards and systems. Flip chip bonders command the deepest margin pools as AI training chips drive substrate-scale packaging, while wire bonding equipment sustains volume leadership across automotive and industrial end users where cost sensitivity prevails. Test handlers represent the fastest-growing technology segment as multi-site parallelism requirements intensify for 5G telecommunications chip validation.
Regulatory Environment
EPA energy efficiency standards in the United States and the EU F-Gas Regulation constrain refrigerant choices in thermal management subsystems within test handlers, while China's MEE enforces dual carbon disclosure for new equipment installations. Japan's METI coordinates JIS standards alignment with IEC frameworks to reduce cross-border certification friction for Tokyo Electron and Advantest Corporation exports. Stakeholders must monitor how REACH substance restrictions on lead-free solder alternatives reshape bonding wire alloy specifications before committing to multi-year equipment procurement cycles.
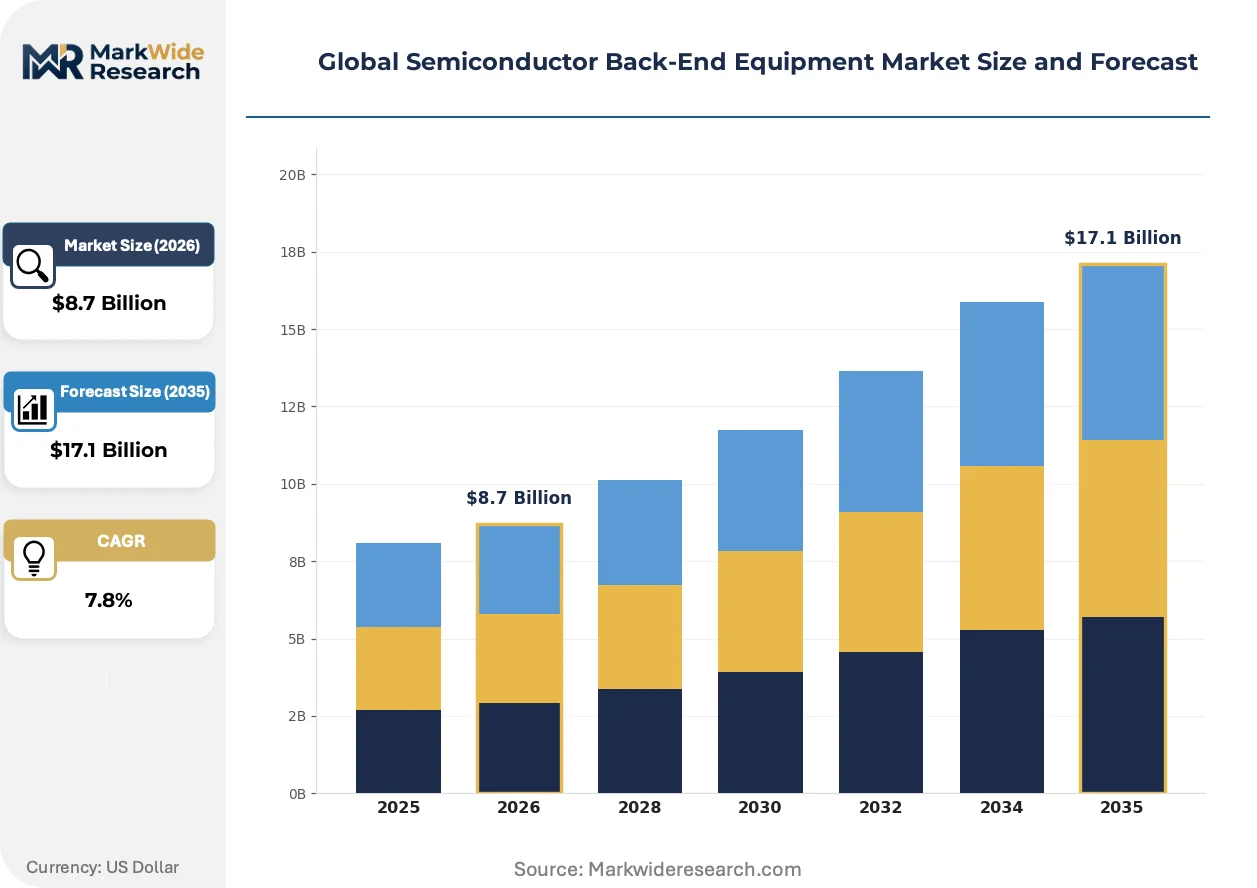
Market Dynamics
Chiplet-based AI accelerator architectures are collapsing legacy wire bonding volumes at leading foundries while simultaneously driving substrate-scale packaging equipment orders at unprecedented placement accuracy requirements.
Growth Catalysts
- Heterogeneous Integration Mandates:AI training chiplet architectures from hyperscale datacenter operators require die-to-wafer hybrid bonding systems that traditional wire bonders cannot execute.
- EU F-Gas Regulation:Thermal management subsystem redesigns for test handlers are accelerating refrigerant transition timelines, forcing equipment refresh cycles ahead of normal replacement schedules.
- Silicon Carbide Power Modules:Industrial automation and electric vehicle traction inverter demand is pulling high-accuracy die attach systems for wide-bandgap semiconductor packaging.
Market Restraints
- Precious Metal Volatility:Bonding wire alloy specifications containing gold and palladium expose equipment owners to raw material cost swings that compress maintenance contract margins.
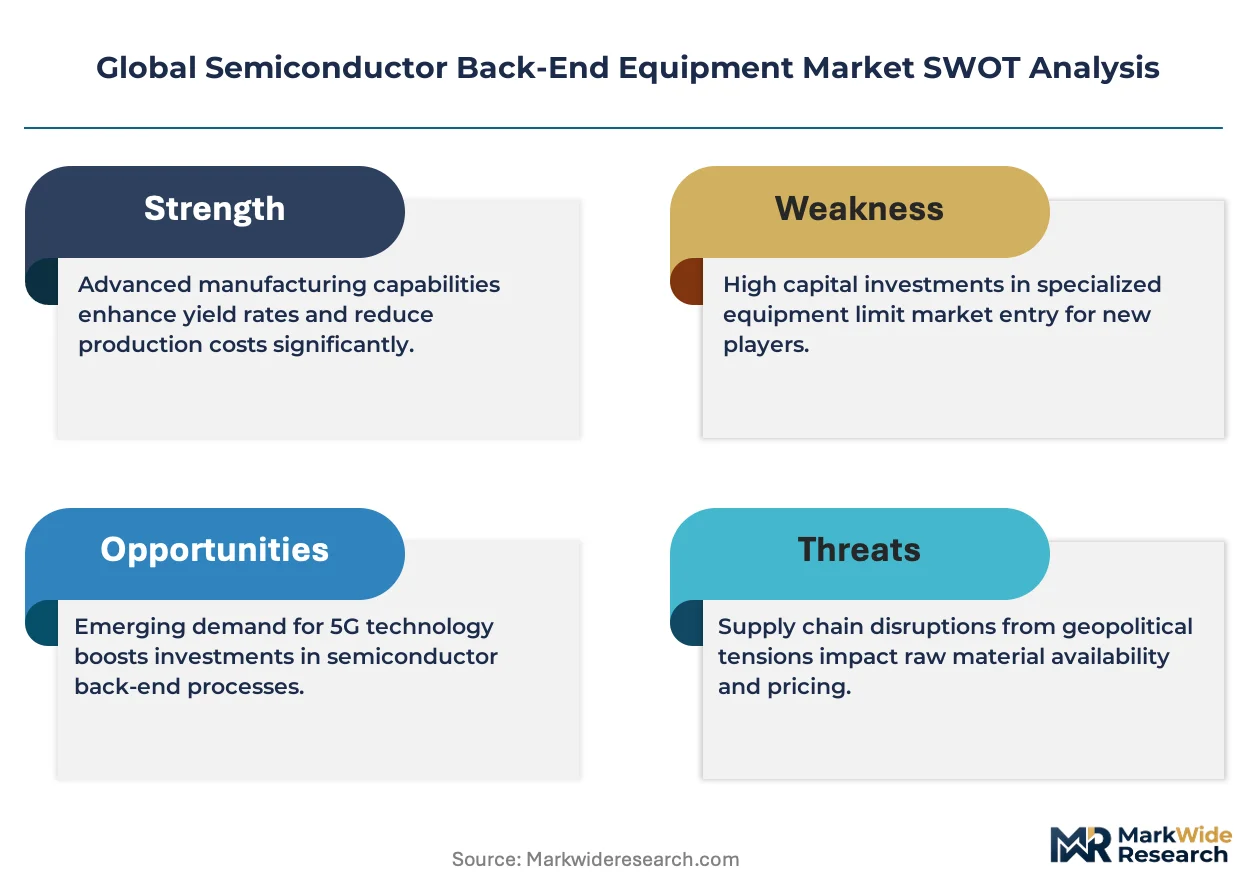
- Taiwan Concentration Risk:Hsinchu Science Park hosts the densest back-end capacity expansion globally, creating single-point vulnerability for equipment supply chains and service technician deployment.
- Flip Chip Technical Ceiling:Substrate warpage control at 300mm scale limits yield ramp speeds for advanced packaging lines serving AI accelerator foundries.
Strategic Opportunities
- India PLI Scheme:Semiconductor assembly and test incentive structures are attracting first-mover equipment deployments for mature-node automotive chip packaging.
- Japan METI Coordination:JIS standards alignment with IEC frameworks reduces cross-border certification friction for Tokyo Electron and Advantest exports into Southeast Asian greenfield fabs.
- Test Handler Parallelism Convergence:5G telecommunications chip validation requirements are merging with automotive functional safety testing protocols, opening multi-site handler retrofit markets.
Industry Challenges
- Bonding Technician Scarcity:Wire bonder calibration expertise is retiring faster than advanced packaging process engineering talent can be retrained, creating service response bottlenecks.
- Dual Carbon Disclosure Burden:China's MEE enforcement requires new equipment installations to document energy efficiency metrics that legacy machine bases cannot retroactively generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Back-End Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Die Bonders, Wire Bonders, Die Attachers, Test Handlers, Marking Systems, Final Assembly Tools Technology: Flip Chip, Wire Bonding, Die Sorting, Packaging, Inspection, Testing Application: Consumer Electronics, Telecommunications, Automotive Tier-1, Industrial Automation, Aerospace Systems, Defense Electronics End User: Foundries, OSAT Providers, IDM Units, Electronic Manufacturing Services |
| Companies Covered | ASM Pacific Technology Limited, Kulicke & Soffa Industries, BE Semiconductor Industries, Advantest Corporation, Teradyne, Applied Materials, Tokyo Electron, Camtek, ASML, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Back-End Equipment Market Shifts & Advancements
Thermal compression bonding is displacing traditional thermosonic methods as AI chiplet interconnect density requirements exceed copper pillar limitations. Equipment vendors are racing to integrate laser-assisted bonding modules into existing die bonder footprints.
Hybrid bonding technology is fragmenting the advanced packaging equipment landscape by enabling direct copper-to-copper interconnects without solder intermediates. Memory foundries in South Korea are adopting these systems for high-bandwidth memory stack assembly. The technology is fragmenting vendor portfolios into distinct wire bonding, flip chip, and hybrid bonding capability tiers that no single equipment line can bridge.
EPA energy efficiency standards are constraining refrigerant choices in thermal management subsystems within test handlers. Equipment manufacturers must redesign chiller units to accommodate low-global-warming-potential alternatives before 2027 compliance deadlines. Datacenter semiconductor test facilities in the United States are accelerating handler replacement schedules to preempt regulatory retrofit costs.
After-sales service unbundling is disrupting traditional equipment procurement relationships in mature automotive supply chains. Tier-1 semiconductor assemblers are separating maintenance contracts from initial capital purchases, forcing vendors to compete for multi-year service agreements on installed wire bonding bases. This pattern is most visible in German automotive microcontroller packaging operations where total cost of ownership calculations now dominate vendor selection.
Global Semiconductor Back-End Equipment Market Segmentation
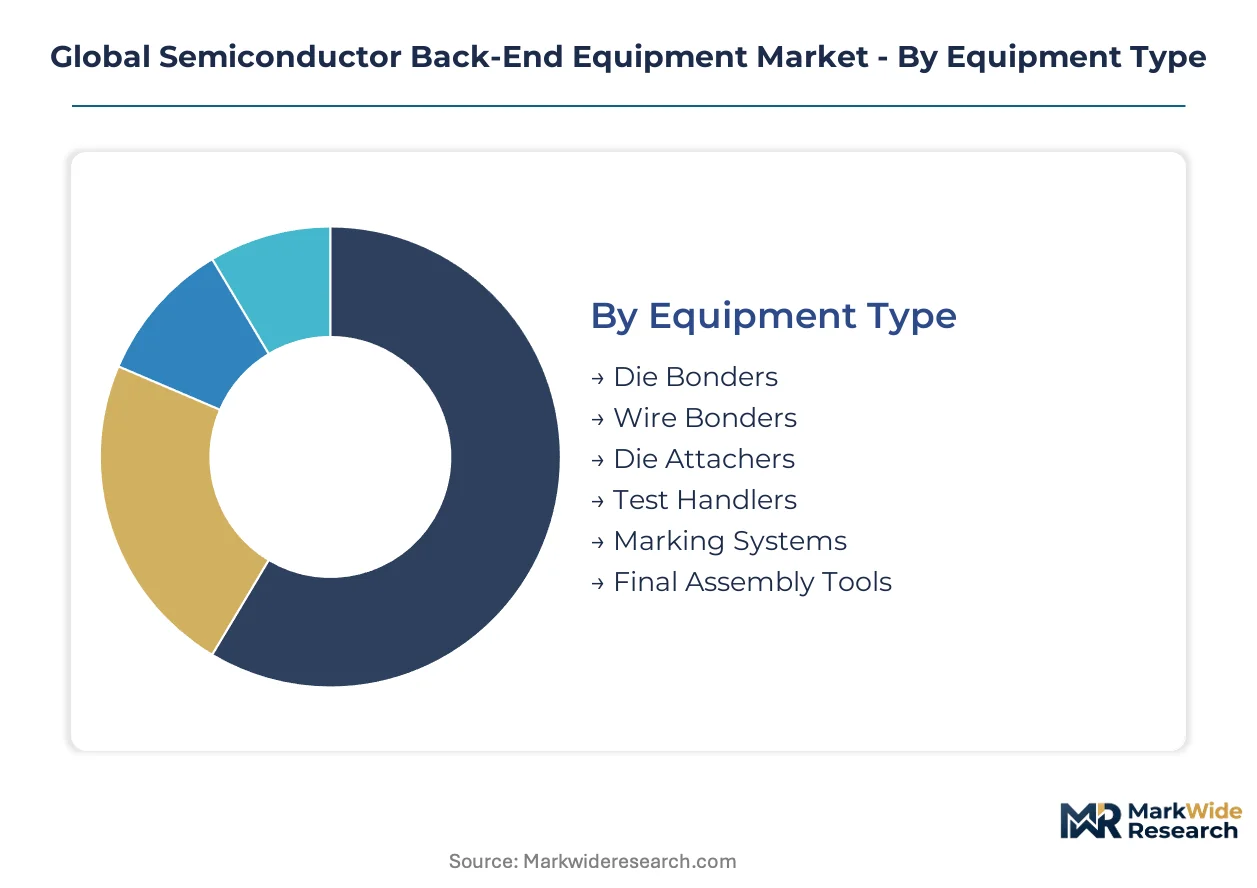
Equipment segmentation in semiconductor back-end operations reveals divergent fates under chiplet architecture migration. Substitution pressures from advanced packaging technologies are fragmenting vendor portfolios and redirecting capital allocation across heterogeneous integration value chains.
Equipment Type:
Wire bonders face the most acute substitution threat as die-to-wafer hybrid bonding displaces thermosonic interconnects in AI accelerator production.
- Die Bonders:These systems execute die placement with sub-5 micrometer accuracy on substrates up to 300mm. AI foundries in Taiwan and South Korea are pulling high-throughput models for chiplet-based heterogeneous integration, though substrate warpage control limits yield ramp speeds at scale.
- Wire Bonders:Operating at placement accuracies below 3 micrometers, these machines interconnect dies with gold, copper, or aluminum wire loops. Mature automotive Tier-1 supply chains in Germany and Japan sustain procurement volumes where flip chip conversion remains uneconomical for legacy microcontroller packaging.
- Die Attachers:High-accuracy systems for wide-bandgap semiconductor assembly serve silicon carbide power module demand from electric vehicle traction inverter manufacturers.
- Test Handlers:Multi-site parallelism capabilities address 5G telecommunications chip validation requirements with thermal management subsystems redesigned for EPA refrigerant compliance.
- Marking Systems:Laser and inkjet systems apply traceability codes for automotive functional safety documentation and defense electronics chain-of-custody requirements.
- Final Assembly Tools:Singulation and lead forming equipment complete package preparation for downstream circuit board integration in consumer electronics supply chains.
Wire bonders retain volume leadership across automotive and industrial end users; die bonders hold the steepest expansion curve from AI packaging investments.
Technology:
Cost tier stratification separates premium hybrid bonding installations from maintenance-heavy wire bonding bases in mature packaging facilities.
- Flip Chip:Substrate-scale packaging technology enables high-density interconnects through copper pillars and solder bumps. Hyperscale datacenter operators in the United States are driving capacity expansion for AI training chiplet architectures.
- Wire Bonding:Thermosonic and thermocompression methods interconnect dies with looped wire bonds. Industrial automation buyers in China sustain equipment refresh cycles for cost-sensitive power device packaging.
- Die Sorting:Automated inspection and binning systems classify dies by electrical performance for yield optimization in memory foundry operations.
- Packaging:Encapsulation and molding systems protect dies from environmental stress in automotive underhood applications.
- Inspection:Automated optical and X-ray systems detect voids, cracks, and alignment defects in solder joints and wire loops.
- Testing:Electrical validation systems execute burn-in and functional tests across temperature ranges for aerospace system reliability requirements.
Wire bonding commands the widest installed base; flip chip is climbing the fastest as substrate-scale packaging penetrates AI accelerator foundries.
Application:
Customer type differentiation separates high-mix low-volume defense electronics from high-volume consumer electronics procurement patterns.
- Consumer Electronics:Smartphone and wearable device packaging drives demand for miniaturized flip chip and wafer-level chip scale packaging equipment. Assembly operations in Vietnam and India are absorbing capacity migration from China.
- Telecommunications:5G baseband and radio frequency component testing requires multi-site handler parallelism. Network equipment manufacturers in Finland and Sweden are qualifying suppliers for Open RAN chipset packaging.
- Automotive Tier-1:Microcontroller and sensor packaging sustains wire bonding volumes where functional safety ISO 26262 documentation requirements favor qualified equipment bases.
- Industrial Automation:Silicon carbide power module assembly pulls high-accuracy die attach systems for motor drive and renewable energy inverter applications.
- Aerospace Systems:Radiation-hardened component packaging requires hermetic sealing and extended temperature range validation protocols.
- Defense Electronics:Trusted foundry requirements restrict equipment sourcing to domestic vendors with secure supply chain certifications.
Automotive Tier-1 applications anchor equipment replacement cycles; telecommunications is gaining share fastest from 5G infrastructure deployment.
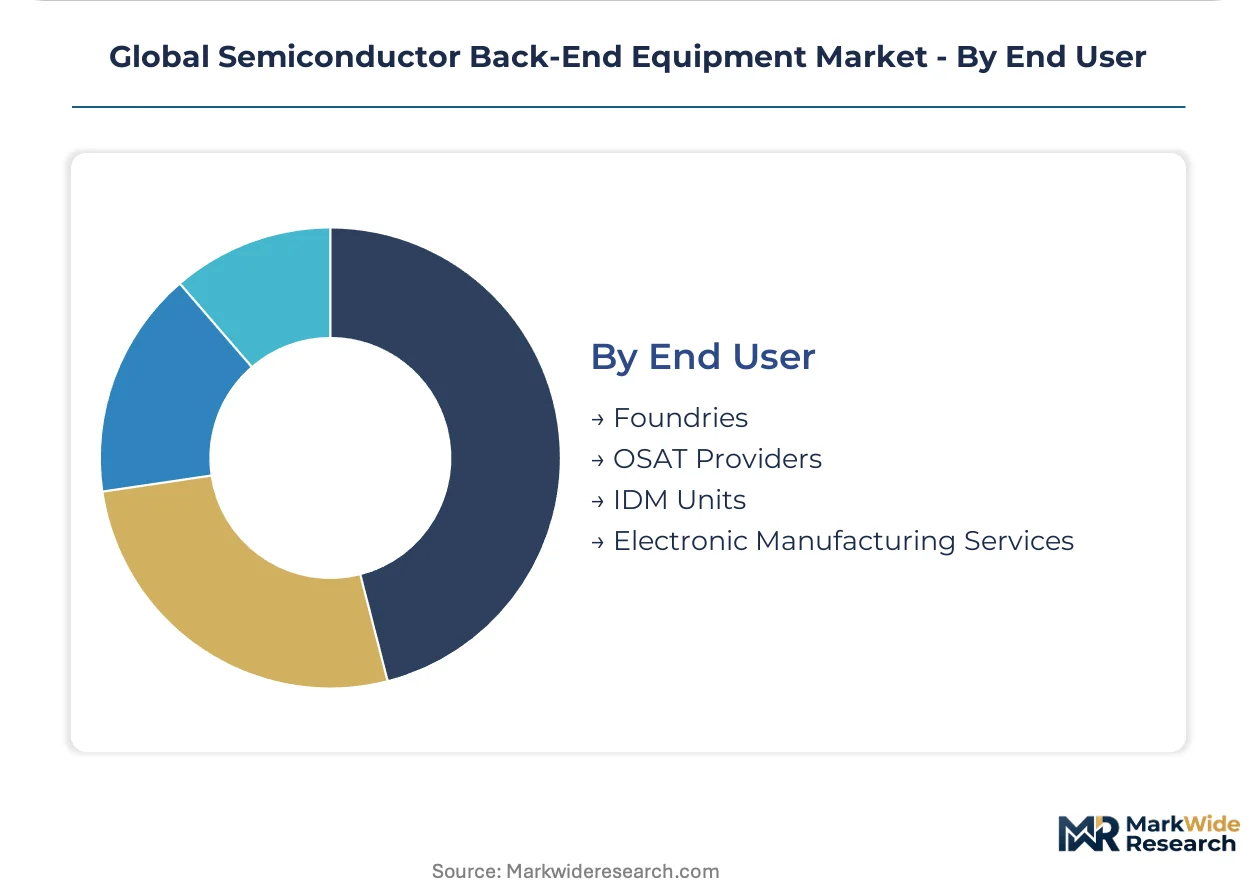
End User:
Supply concentration among foundry operators in Taiwan creates procurement power asymmetries against equipment vendors.
- Foundries:Taiwan Semiconductor Manufacturing Company and Samsung Foundry dominate advanced packaging equipment procurement for chiplet-based AI accelerators. These buyers dictate placement accuracy roadmaps and thermal management specifications.
- OSAT Providers:Outsourced semiconductor assembly and test companies in Malaysia and the Philippines aggregate demand from fabless design houses. Equipment vendors compete for multi-year service agreements as after-sales unbundling disrupts traditional procurement relationships.
- IDM Units:Integrated device manufacturers in the United States and Europe maintain captive back-end operations for proprietary power and analog device packaging.
- Electronic Manufacturing Services:Contract assemblers in Mexico and Eastern Europe handle final system integration for original equipment brands with limited semiconductor packaging expertise.
Foundries concentrate the highest-value equipment orders; OSAT providers are expanding most quickly from India PLI scheme incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment flows from Japanese and Dutch manufacturers concentrate in Taiwanese foundry installations, while Southeast Asian OSAT hubs absorb second-hand wire bonding assets from collapsing legacy lines.
United States
Hyperscale datacenter operators in Arizona and Texas are commissioning substrate-scale packaging lines for AI training chiplet architectures. EPA energy efficiency standards constrain refrigerant choices in thermal management subsystems for test handlers. Greater Phoenix anchors the densest concentration of advanced packaging greenfield investments outside Asia.
China
Industrial automation buyers in Jiangsu and Guangdong sustain equipment refresh cycles for cost-sensitive power device packaging. The MEE enforces dual carbon disclosure requirements for new equipment installations that legacy machine bases cannot retroactively satisfy. Yangtze River Delta clusters host the fastest-growing domestic die bonder assembly operations.
Japan
Tokyo Electron and Advantest Corporation exports dominate Southeast Asian greenfield fab equipment procurement. METI coordinates JIS standards alignment with IEC frameworks to reduce cross-border certification friction. Chubu-Nagoya industrial corridors concentrate precision automation component suppliers for bonding equipment subassemblies.
Germany
Automotive Tier-1 microcontroller packaging operations sustain wire bonding volumes where flip chip conversion remains uneconomical. After-sales service unbundling disrupts traditional procurement relationships as assemblers separate maintenance contracts from capital purchases. Bavarian industrial automation clusters pull high-accuracy die attach systems for silicon carbide power module integration.
South Korea
Memory foundries in Gyeonggi Province are adopting hybrid bonding systems for high-bandwidth memory stack assembly. MFDS semiconductor equipment certification requirements align with international standards to accelerate export approvals. Seoul Capital Area anchors the steepest expansion curve for die-to-wafer bonding capacity outside Taiwan.
Global Semiconductor Back-End Equipment Market Competitive Landscape
Listed leaders compete with private specialists across equipment financing structures, creating tiered competitive dynamics. The vendor base separates into consolidated precision automation conglomerates and focused bonding equipment pure-plays. Three archetypes dominate: diversified electronics equipment platforms, specialized back-end machinery developers, and test system integration houses. Competitive moves concentrate on portfolio diversification into adjacent packaging technologies and geographic expansion through localized service subsidiaries.
Within the diversified equipment platform tier, ASM Pacific Technology Limited and Applied Materials exemplify scale-driven market presence through broad semiconductor manufacturing exposure. Tokyo Electron occupies a position among precision automation conglomerates with significant back-end equipment representation. These three companies anchor the competitive structure without exhaustive market coverage, as specialized die bonder and wire bonding pure-plays retain distinct positioning in technology-specific procurement decisions.
| Leading Market Players |
|---|
| ASM Pacific Technology Limited |
| Kulicke & Soffa Industries |
| BE Semiconductor Industries |
| Advantest Corporation |
| Teradyne |
| Applied Materials |
| Tokyo Electron |
| Camtek |
| ASML |
| Others |
Supply & Pricing Matrix
Capacity utilization rates above 85 percent at Taiwanese foundry clusters compress price floors for wire bonding equipment while elevating premiums for hybrid bonding systems with sub-micron placement accuracy. This scale asymmetry concentrates procurement leverage among hyperscale datacenter operators and fragments vendor pricing power across technology tiers.
Pricing Analysis
Next-generation hybrid bonding equipment commands 3-4x price multiples over current-generation flip chip bonders, while prior-generation wire bonding systems face accelerated depreciation in secondary markets. Three-tier pricing structure across premium, standard, and economy levels separates AI foundry procurement from automotive Tier-1 maintenance contracts and industrial automation refresh cycles. Price differentiation hinges on placement accuracy certification tiers and after-sales service bundling. Cost compression in wire bonding tiers is intensifying because OSAT providers unbundle maintenance agreements from capital purchases. Automotive Tier-1 assemblers exhibit the highest price sensitivity due to ISO 26262 requalification costs, while AI foundries demonstrate the lowest sensitivity given yield ramp imperatives.
Supply Chain Analysis
Port congestion at Kaohsiung and Yokohama elevates inbound logistics costs for precision motion control subassemblies sourced from Japanese component suppliers. Equipment manufacturing concentrates in Taiwan, Japan, and the Netherlands, with assembly operations drawing from German precision optics and Swiss linear motor technologies. Raw material dependencies include high-purity copper bonding wire, ceramic substrate materials, and rare-earth magnets for servo systems. Single-source vulnerability in EUV-grade ceramic components creates supply chain risk for die bonder thermal management modules. Distribution runs through direct sales forces for foundry accounts and regional service subsidiaries for OSAT maintenance contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced packaging process engineering talent is retiring faster than training pipelines can replenish, creating acute capability scarcity that reshapes competitive positioning across equipment vendor tiers. This skill gap concentrates value capture among vendors with captive technician deployment networks.
For Market Incumbents: Secure calibration expertise retention through structured knowledge transfer programs before wire bonding technician retirement waves accelerate. Lock in multi-year service agreements with German automotive Tier-1 suppliers to defend against after-sales unbundling threats. Pursue backward integration into precision motion control subassemblies to reduce exposure to Japanese component supplier lead time volatility. For New Entrants and Emerging Players: Aftermarket retrofit services for legacy wire bonding bases represent an underserved layer where incumbents under-serve price-sensitive OSAT providers in Malaysia and the Philippines. Target India's PLI scheme incentive window for mature-node automotive packaging equipment deployments. Lead with total cost of ownership consulting to differentiate from capital-sales-focused incumbents. For Investors and Strategic Acquirers: Specialized die bonder pure-plays with heterogeneous integration roadmaps present acquisition targets with durable differentiation against diversified equipment platforms. Frame long-term viability around AI chiplet architecture proliferation extending across the analysis window. Monitor substrate warpage yield ramp speeds at 300mm scale as the inflection indicator for hybrid bonding equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Integration | Enables copper-to-copper interconnects for AI chiplet architectures at memory foundries in South Korea. |
| Service Contract Unbundling | Separates maintenance agreements from capital purchases for German automotive microcontroller packaging operations. |
| India PLI Scheme Localization | Captures semiconductor assembly and test incentives for mature-node automotive chip packaging deployments. |
| EPA Refrigerant Compliance Redesign | Accelerates test handler replacement schedules ahead of 2027 thermal management subsystem deadlines. |
| Precision Component Backward Integration | Reduces lead time exposure for ceramic substrate materials sourced through Japanese suppliers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with back-end equipment procurement managers, process engineering directors, and aftermarket service heads at foundry and OSAT operations; and secondary validation through SEC equipment vendor filings, customs import records for bonding wire alloys, and Taiwan Science Park capacity expansion permits. Semiconductor fabrication executives, bonding equipment maintenance technicians, and industrial automation purchasing leads contributed operational perspective. Bottom-up equipment shipment tallies triangulated against top-down foundry capex disclosure analysis.
Across the projection horizon, the analytical framework modeled segmentation across equipment type, interconnect technology, end-use application, and customer archetype dimensions. CAGRs were derived from equipment shipment run-rates, foundry capacity build-out schedules, and technology substitution curves for wire bonding-to-flip chip migration. Forecast inputs incorporated EPA refrigerant compliance timelines, India PLI scheme incentive trajectories, and AI accelerator chiplet architecture proliferation patterns.
Underlying assumptions cover sustained hyperscale datacenter investment levels and stable Taiwan Strait logistics corridors, with deviation risk concentrated in export control expansions affecting precision motion control technologies. Forecasts reflect these boundary conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market