
 Digital Signal Processor Market | 2026-2036
Digital Signal Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signal Processor Market Analysis
Consolidation among mobile device manufacturers is repositioning procurement leverage toward a handful of flagship-tier OEMs that now dictate DSP performance roadmaps. Texas Instruments Incorporated anchors its position through captive analog-DSP integration for industrial automation. Qualcomm Incorporated leads in modem-DSP fusion for cellular baseband, while NXP Semiconductors N.V differentiates via automotive radar signal processing specialization.
A digital signal processor is a specialized microprocessor optimized for mathematical operations on digitized signal streams, typically executing multiply-accumulate instructions in single clock cycles with deterministic latency. Fixed Point DSP architectures dominate telecommunications infrastructure for power-constrained baseband processing, while FPGA-based DSP variants capture defense and aerospace applications requiring field-reconfigurable algorithms. Neuromorphic DSP remains nascent but draws R&D concentration from edge-AI inference workloads where spiking neural networks promise order-of-magnitude efficiency gains.
FCC equipment authorization rules shape transmitter-DSP integration for US telecommunications gear, while EU REACH and RoHS frameworks constrain material composition across European-bound semiconductor packages. China's GB standards and MIIT certification gates govern domestic 5G base station DSP procurement, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor whether sovereign chip subsidies in the US, EU, and China fragment DSP design ecosystems into incompatible national standards.
Market Dynamics
Semiconductor foundry concentration in Taiwan and South Korea is rewriting DSP procurement risk calculations, as geopolitical exposure now rivals technical specifications in supplier selection criteria for telecommunications and automotive OEMs.
Growth Catalysts
- 5G baseband processing:Fixed-point DSP architectures execute multiply-accumulate operations with deterministic latency essential for massive MIMO beamforming in next-generation cellular infrastructure.
- EU Chips Act subsidies:Sovereign DSP supply chain investments are redirecting European fabrication capacity toward automotive radar and industrial automation signal processors.
- Automotive radar integration:Multicore DSP volumes are accelerating in China as domestic OEMs integrate 4D imaging radar for autonomous emergency braking systems.
Market Restraints
- Advanced node cost escalation:Sub-7nm DSP tape-out expenses now exceed $500 million per design, concentrating development among capital-flush integrated device manufacturers.
- Foundry geographic concentration:Over 80 percent of leading-edge DSP wafer supply originates from Taiwan, creating single-point-of-failure exposure for base station and defense programs.
- FPGA substitution threat:Field-programmable gate arrays with hardened DSP slices capture defense applications requiring algorithm reconfiguration without silicon respins.
Strategic Opportunities
- Neuromorphic edge AI:Spiking neural network accelerators promise order-of-magnitude efficiency gains for always-on voice and vibration classification in battery-constrained devices.
- India PLI scheme:Production-linked incentives for semiconductor packaging are attracting DSP module assembly investments serving domestic telecommunications and automotive markets.
- Software-defined radio convergence:DSP-FPGA heterogenous integration enables waveform reconfiguration for multi-band military and satellite communications terminals.
Industry Challenges
- MIIT certification timelines:China's GB standards for 5G base station DSP procurement impose 12-18 month homologation cycles that delay product launches versus unregulated markets.
- Legacy ISA fragmentation:Proprietary DSP instruction set architectures complicate code portability across Texas Instruments, Qualcomm, and NXP product families, inflating software development costs.
- Analog-DSP integration complexity:Mixed-signal design expertise scarcity extends development schedules for industrial automation controllers requiring precision data converter interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signal Processor Market |
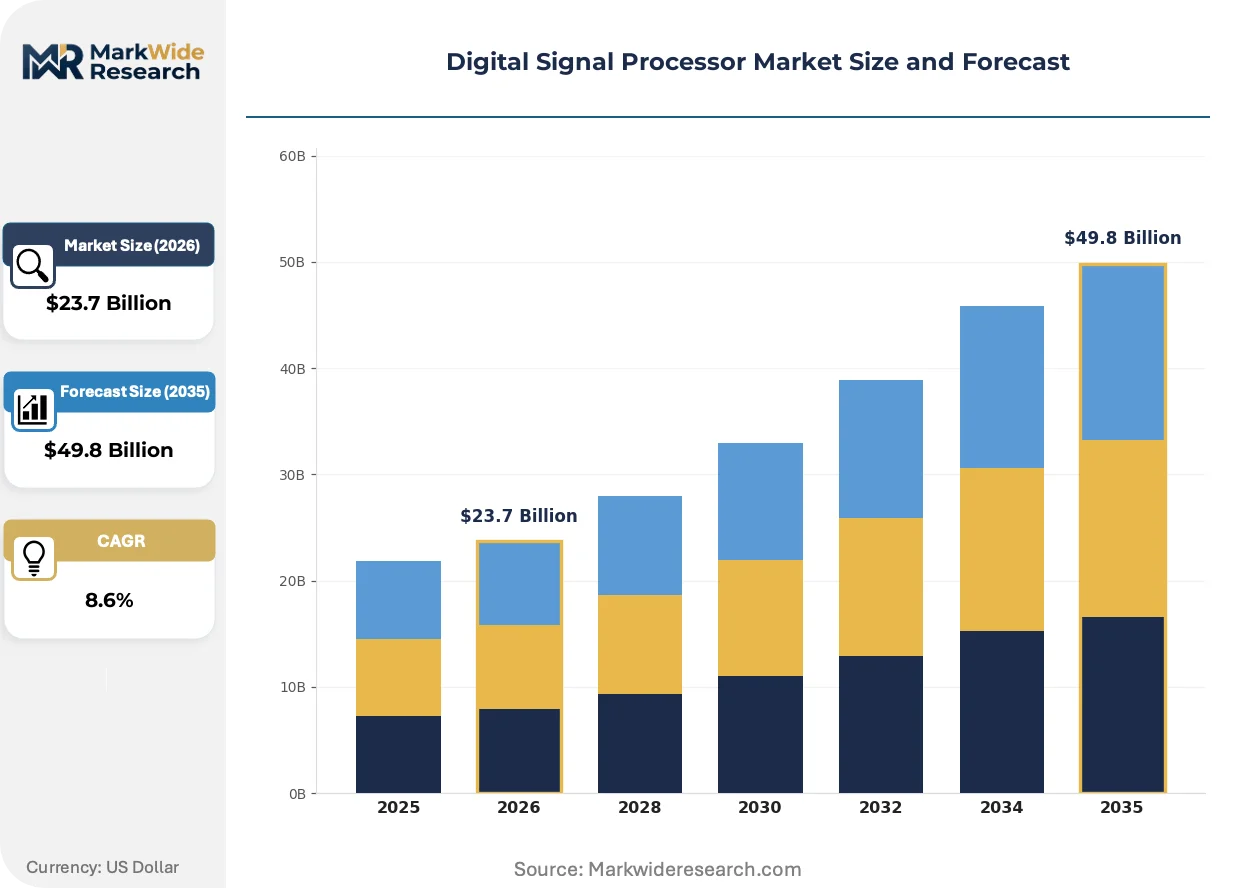
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Point DSP, Floating Point DSP, Mixed Signal DSP, Quantum DSP, Neuromorphic DSP Technology: Multicore Processing, SIMD Architecture, VLIW Architecture, FPGA-based DSP, ASIC-based DSP Application: Telecommunications, Consumer Electronics, Defense Systems, Industrial Automation, Aerospace Control End User: Mobile Device Manufacturers, Semiconductor Foundries, Network Operators, Audio Equipment Makers, Satellite Firms |
| Companies Covered | Intel Corporation, Infineon Technologies AG, Texas Instruments Incorporated, Broadcom Inc, STMicroelectronics N.V, Analog Devices Inc, NXP Semiconductors N.V, Asahi Kasei Microdevices Corporation, Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signal Processor Market Emerging Trajectories
Algorithm-hardware co-design is displacing conventional DSP architecture roadmaps, as machine learning operators reshape silicon resource allocation and memory hierarchy priorities across telecommunications and sensing applications.
Neuromorphic DSP accelerators are rewriting power-performance tradeoffs for edge inference workloads. Spiking neural network architectures from BrainChip and Intel Labs execute event-driven computation at sub-milliwatt levels. Automotive Tier-1s are sampling these devices for occupant monitoring and predictive maintenance, compressing the viable market for conventional von Neumann DSPs in always-on sensing nodes.
EU AI Act risk classification rules are mandating deterministic execution guarantees for high-risk signal processing applications. Medical imaging and autonomous vehicle DSP subsystems must demonstrate traceable, reproducible outputs under formal verification standards. Semiconductor vendors are responding with lockstep dual-core DSP architectures and error-correcting memory controllers for European-bound designs.
Automotive OEMs are consolidating DSP procurement through direct foundry relationships rather than merchant silicon distributors. Tesla, BYD, and BMW negotiate wafer allocation agreements for radar and audio processing die, bypassing traditional component distributors. This disintermediation concentrates in China and Germany where vertical integration strategies dominate electric vehicle platform development.
Digital Signal Processor Market Segmentation
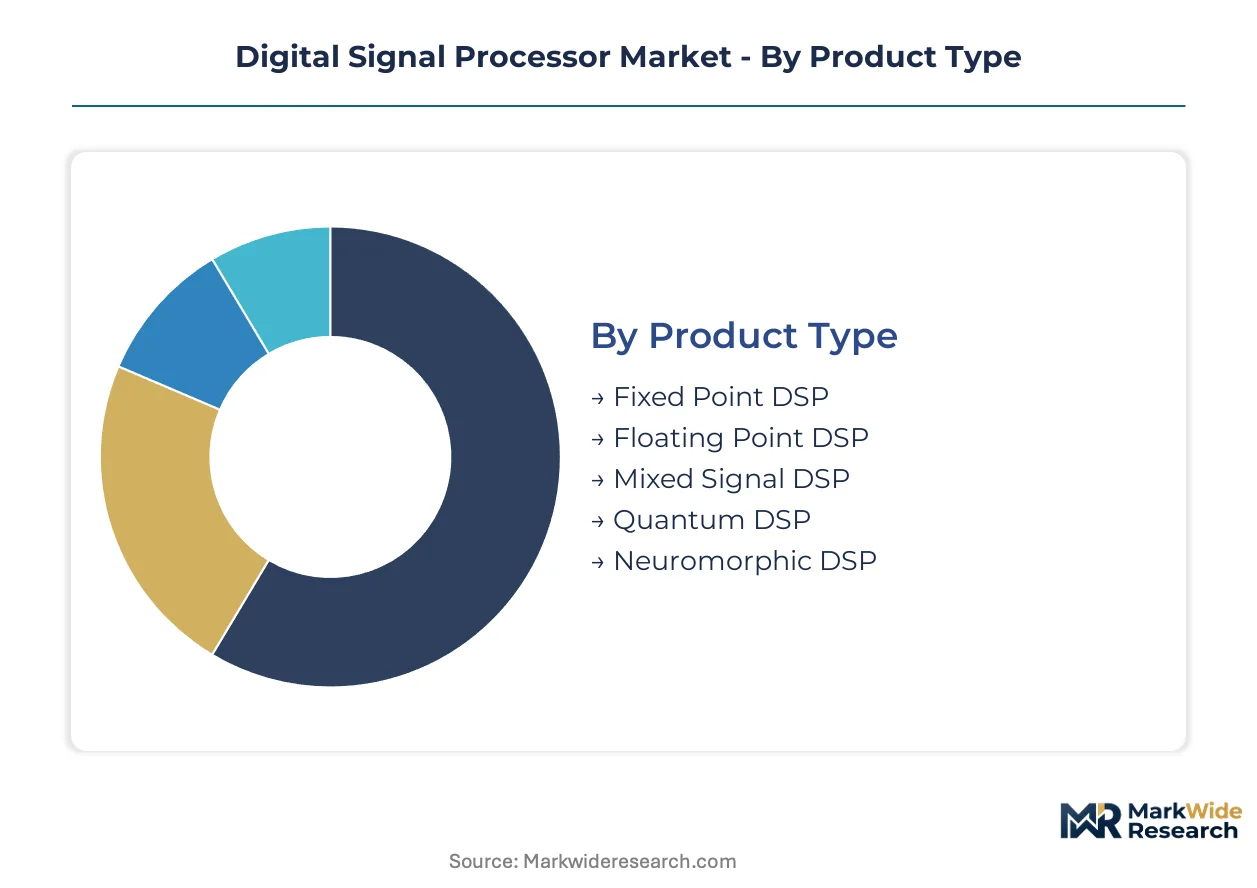
DSP architecture selection dictates power budgets, latency guarantees, and algorithm flexibility across telecommunications, automotive, and defense procurement cycles. Upgrade decisions hinge on whether existing fixed-point implementations satisfy beamforming throughput or whether floating-point precision becomes mandatory for radar signal chains.
Product Type:
Replacement cycles vary dramatically across precision classes, with infrastructure operators running fixed-point DSPs for 7-10 years while edge-AI developers cycle neuromorphic silicon every 18-24 months.
- Fixed Point DSP:Integer arithmetic units execute multiply-accumulate operations in single clock cycles with deterministic latency. Chinese base station deployments and Korean automotive radar modules pull the highest volumes, constrained by MIIT certification timelines that extend procurement cycles.
- Floating Point DSP:IEEE-754 compliant datapaths handle dynamic range requirements for medical imaging and software-defined radio applications. Defense programs in the US and satellite operators in Europe concentrate demand where algorithm precision outweighs power penalties.
- Mixed Signal DSP:Integrated analog front-ends reduce component count for industrial sensor nodes.
- Quantum DSP:Cryogenic control electronics for superconducting qubit manipulation remain confined to national laboratory procurement.
- Neuromorphic DSP:Spiking neural network accelerators from BrainChip and Intel Labs target sub-milliwatt voice classification endpoints.
Volume placements concentrate in Fixed Point DSP; the faster expansion belongs to Neuromorphic DSP.
Technology:
Silicon efficiency gains now derive from datapath parallelism rather than frequency scaling, reshaping how semiconductor foundries allocate mask layers across DSP product lines.
- Multicore Processing:Homogeneous core clusters partition baseband workloads across independent execution domains with shared L2 coherence. 5G massive MIMO implementations in China and automated optical inspection systems in Germany drive the steepest expansion trajectory for this architecture class.
- SIMD Architecture:Single-instruction multiple-data units vectorize FIR filtering and FFT butterflies for audio post-processing. Professional mixing consoles and hearing aid DSPs from Danish and Swiss manufacturers anchor demand.
- VLIW Architecture:Statically scheduled instruction bundles expose parallelism without runtime speculation overhead.
- FPGA-based DSP:Field-reconfigurable logic with hardened multiply-accumulate tiles enables algorithm updates without respinning silicon.
- ASIC-based DSP:Full-custom implementations minimize unit cost at million-unit annual volumes.
ASIC-based DSP captures the highest shipment volumes; FPGA-based DSP gains share fastest in defense and satellite communications.
Application:
End-use requirements fragment DSP specifications, with telecommunications demanding deterministic latency while consumer electronics prioritize die area minimization.
- Telecommunications:Baseband processors execute channel estimation and precoding under 3GPP timing constraints. Network operators in China, South Korea, and the US commission the largest procurement volumes, subject to FCC equipment authorization and MIIT certification gates.
- Consumer Electronics:Audio DSPs handle active noise cancellation and spatial audio rendering at sub-50mW budgets. TWS earbud manufacturers in Shenzhen and Seoul dominate procurement.
- Defense Systems:Tempest-rated silicon with anti-tamper mesh satisfies NSA supply chain requirements.
- Industrial Automation:Real-time motor control loops demand sub-microsecond interrupt response.
- Aerospace Control:DO-254 certified designs govern flight surface actuation and engine monitoring.
Telecommunications absorbs the greatest volume; Defense Systems climbs fastest on classified program spending.
End User:
Procurement authority is consolidating among integrated device manufacturers that internalize DSP design rather than sourcing merchant silicon.
- Mobile Device Manufacturers:Flagship-tier OEMs specify modem-DSP fusion architectures that Qualcomm, MediaTek, and Samsung LSI fabricate on leading-edge nodes. Apple and Google vertical integration into baseband DSP design alters competitive dynamics.
- Semiconductor Foundries:TSMC and Samsung Foundry allocate capacity for fabless DSP vendors and captive automotive programs. Taiwan concentration creates geopolitical exposure for European and US defense contractors.
- Network Operators:China Mobile, Verizon, and Deutsche Telekom issue RFPs for 5G baseband silicon with 10-year supply guarantees.
- Audio Equipment Makers:Professional studio and live sound vendors specify 32-bit floating-point precision.
- Satellite Firms:Starlink, OneWeb, and national programs demand radiation-tolerant DSPs for onboard processing.
Mobile Device Manufacturers place the highest volumes; Satellite Firms expand procurement fastest on constellation deployment schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the steepest demand trajectory for digital signal processors, driven by domestic 5G base station deployment and automotive radar integration. Procurement patterns in Germany, South Korea, and the United States follow distinct regulatory and industrial logics that reshape supplier strategies across each jurisdiction.
China
Domestic OEMs pull advanced multicore DSP volumes for 4D imaging radar and massive MIMO beamforming infrastructure. MIIT certification gates impose 12-18 month homologation cycles that delay product launches versus unregulated markets. Shenzhen and Shanghai anchor the densest clusters of baseband processor procurement and radar module integration.
Germany
Automotive Tier-1s negotiate direct foundry relationships for radar and audio processing die, bypassing traditional component distributors. EU AI Act risk classification rules mandate deterministic execution guarantees for autonomous vehicle DSP subsystems. Bavaria concentrates the highest density of industrial automation controller design requiring precision data converter interfaces.
South Korea
Semiconductor foundries expand DSP fabrication capacity for 5G baseband processing alongside captive automotive programs. The country's national telecommunications regulator shapes equipment authorization timelines for network operator procurement. Seoul and Busan-Ulsan host the dominant concentration of fabless DSP vendor partnerships and wafer allocation agreements.
United States
Defense programs and satellite operators concentrate demand for floating-point precision and radiation-tolerant implementations. FCC equipment authorization rules shape transmitter-DSP integration for telecommunications gear. Greater Boston and the Pacific Northwest anchor the densest R&D clusters for neuromorphic edge AI and software-defined radio convergence.
India
Production-linked incentives for semiconductor packaging attract DSP module assembly investments serving domestic telecommunications and automotive markets. The country's national electronics regulator governs equipment type approval for network infrastructure deployment. Karnataka and Telangana concentrate the fastest-growing clusters of TWS earbud manufacturing and audio DSP procurement.
Digital Signal Processor Market Vendor Landscape
United States producers anchor one tier; European specialists hold differentiated positions in automotive and industrial automation signal processing. The vendor base concentrates among integrated device manufacturers with captive analog-DSP integration capabilities and fabless vendors reliant on Taiwan and South Korea foundry access. Three strategic archetypes dominate: modem-DSP fusion specialists, mixed-signal industrial automation suppliers, and neuromorphic edge AI pioneers. Competitive moves center on direct foundry relationship consolidation and algorithm-hardware co-design investments.
Within the integrated device manufacturer tier, Texas Instruments Incorporated and Qualcomm Incorporated exemplify divergent strategic positions. NXP Semiconductors N.V occupies a distinct specialization zone in automotive radar signal processing. These three entities represent the dominant competitive anchors against which fabless vendors and neuromorphic challengers position their alternative architectures.
| Leading Market Players |
|---|
| Intel Corporation |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Broadcom Inc |
| STMicroelectronics N.V |
| Analog Devices Inc |
| NXP Semiconductors N.V |
| Asahi Kasei Microdevices Corporation |
| Qualcomm Incorporated |
| Others |
Supply Flow & Price Mechanics
Algorithm-hardware co-design is compressing development timelines while simultaneously concentrating fabrication leverage among leading-edge foundries, creating a pricing environment where architectural differentiation commands premiums but node access determines margin sustainability.
Pricing Analysis
Volume shipments of fixed-point DSPs for telecommunications infrastructure operate on thin margins at million-unit scales, while neuromorphic edge-AI silicon captures premium positioning through sub-milliwatt efficiency claims. Price differentiation centers on MIIT certification grade for China-bound baseband processors and EU AI Act deterministic execution guarantees for automotive radar subsystems. Cost compression in mature-node industrial automation DSPs is intensifying as Texas Instruments and NXP consolidate mixed-signal integration capabilities. Network operators in China and South Korea exhibit the highest price sensitivity due to procurement scale, whereas defense programs in the United States prioritize radiation tolerance and traceability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from European automotive OEMs and US defense contractors now require qualified secondary foundry relationships beyond Taiwan, accelerating qualification timelines for Samsung Foundry in South Korea and emerging capacity in Japan. Raw material dependencies center on 300mm silicon wafers, advanced photoresists, and high-purity specialty gases for EUV lithography. Single-source vulnerability concentrates in TSMC's N5 and N3 nodes where over 80 percent of leading-edge DSP wafer supply originates. Distribution runs through direct foundry relationships for automotive and defense Tier-1s, while merchant silicon flows through authorized distributors serving industrial automation and consumer electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-point DSP architectures face displacement pressure from neuromorphic accelerators and FPGA-based reconfigurable alternatives, compressing the viable window for conventional von Neumann designs in always-on sensing applications.
For Market Incumbents: Anticipate neuromorphic substitution in edge-AI voice and vibration classification nodes by accelerating algorithm-hardware co-design investments for spiking neural network compatibility. Defensive consolidation should prioritize captive analog-DSP integration for industrial automation to offset margin erosion in commoditized telecommunications baseband silicon. Lockstep dual-core architectures with error-correcting memory controllers will satisfy EU AI Act deterministic execution mandates for high-risk automotive signal processing applications.
For New Entrants and Emerging Players: The EU Chips Act subsidy flows toward sovereign DSP supply chains in Europe open a window for automotive radar and industrial automation specialization targeting German Tier-1 direct procurement relationships. India's PLI scheme for semiconductor packaging presents the most penetrable geography for DSP module assembly serving domestic telecommunications and TWS earbud manufacturing clusters. A go-to-market angle centered on software-defined radio DSP-FPGA heterogenous integration for military and satellite communications terminals bypasses incumbent dominance in cellular baseband.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated device manufacturers seeking neuromorphic capability or automotive radar signal processing specialization. Long-term viability favors vendors with qualified multi-foundry relationships and MIIT certification track records for China market access. The signal to watch is BYD and Tesla vertical integration momentum into in-house radar and audio DSP design, which would disintermediate merchant silicon vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Relationship Consolidation | BMW and Tesla negotiate wafer allocation agreements that bypass traditional component distributors. |
| Algorithm-Hardware Co-Design Investment | Machine learning operators reshape silicon resource allocation across telecommunications beamforming applications. |
| MIIT Certification Pre-Qualification | 12-18 month homologation cycles for 5G base station DSP procurement create first-mover advantages in China. |
| Neuromorphic Architecture Licensing | BrainChip and Intel Labs spiking neural network IP enables sub-milliwatt voice classification for battery-constrained devices. |
| EU AI Act Deterministic Execution Compliance | Lockstep dual-core DSP architectures with formal verification satisfy high-risk medical imaging and autonomous vehicle requirements. |
Methodological Framework
Multi-period observation of DSP architecture roadmaps, foundry capacity allocations, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with semiconductor foundry planning officers, fabless DSP vendor product managers, automotive Tier-1 procurement leads, and network operator RFP specialists. Secondary validation drew from MIIT equipment type approval databases, FCC equipment authorization filings, EU Chips Act subsidy disbursement records, and SEC 10-K disclosures from integrated device manufacturers. Bottom-up shipment estimates by product type and application were triangulated against top-down wafer allocation data from TSMC and Samsung Foundry.
Input-output matrices modeled DSP demand across fixed-point, floating-point, and neuromorphic architectures against 5G baseband deployment schedules, automotive radar integration timelines, and defense program spending trajectories over the projection horizon. Segmentation dimensions included precision class, core architecture, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical foundry utilization rates and forward-looking equipment procurement disclosures. Industry-specific forecast inputs incorporated massive MIMO beamforming throughput requirements and 4D imaging radar signal chain precision specifications.
The model assumes a particular technology adoption path; alternative pathways for neuromorphic edge-AI acceleration would alter the outlook if spiking neural network efficiency claims achieve production scale faster than projected. Forecasts reflect assumptions regarding MIIT certification timeline stability, Taiwan Strait geopolitical continuity, and EU AI Act enforcement consistency. A model refresh is warranted upon material change in foundry geographic concentration or sovereign chip subsidy fragmentation into incompatible national standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Wearable Processor Market