
 Canada Data Center Processor Market | 2026-2036
Canada Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Processor Market Insights
The capital-intensity divergence between custom silicon designers and merchant processor vendors is unwinding competitive dynamics across Canadian deployments. Intel Corporation sustains manufacturing scale through its foundry partnerships serving domestic colocation operators. NVIDIA Corporation dominates AI accelerator procurement cycles as Montreal-based research institutes expand GPU-intensive workloads. Advanced Micro Devices Inc. leverages chiplet architectures to compete for enterprise refresh contracts in Toronto financial services data centers.
Canada data center processors are integrated circuits engineered to execute compute workloads within centralized and distributed IT facilities, typically fabricated on process nodes ranging from 5nm to 7nm for leading-edge devices and designed to manage thermal design power between 150W and 400W in high-performance configurations. CPU architectures anchor general-purpose virtualization workloads across enterprise and managed service provider facilities, while GPU segments capture accelerating margin pools from generative AI training and inference deployments. Edge Computing technology is expanding fastest as telecom operators deploy low-latency processing nodes in Vancouver and Calgary to support 5G network slicing applications.
Health Canada and the Canadian Centre for Cyber Security establish product integrity and supply chain security expectations for critical infrastructure processors deployed in government and telecom environments. Natural Resources Canada's energy efficiency regulations and provincial clean electricity standards in Quebec and Ontario shape procurement criteria toward processors with superior performance-per-watt metrics. Stakeholders must monitor how forthcoming federal critical technology procurement guidelines alter vendor qualification pathways for domestic data center builds.
Market Dynamics
Hyperscale cloud operators are deploying AI training clusters across Ontario and Quebec, forcing domestic colocation providers to accelerate processor refresh cycles to match workload density requirements.
Growth Catalysts
- Natural Resources Canada Clean Electricity Regulations:Federal efficiency mandates compel facility operators to prioritize processors with superior performance-per-watt metrics, directly stimulating demand for advanced node silicon.
- Generative AI Workload Expansion:Montreal-based research institutes and Toronto financial institutions are scaling GPU-intensive inference deployments, creating sustained procurement pull for accelerator architectures.
- Quebec Hydroelectric Advantage:Abundant low-carbon baseload power in the Montreal corridor attracts hyperscale buildouts, anchoring processor demand concentration in the province.
Market Restraints
- Foundry Capacity Concentration:Leading-edge fabrication for 5nm-7nm processors depends on Taiwan-based and South Korea-based facilities, exposing Canadian deployments to geopolitical supply disruption risk.
- Memory-DDR5 Cost Volatility:High-bandwidth memory modules required for AI accelerators exhibit price instability that compresses total cost of ownership calculations for domestic operators.
- Health Canada Supply Chain Security Requirements:Mandatory vendor qualification pathways for government and telecom processors extend procurement timelines and limit qualified supplier pools.
Strategic Opportunities
- Western Canada Edge Expansion:Vancouver and Calgary telecom operators are deploying 5G network slicing nodes, creating processor demand for low-latency edge compute outside the Ontario-Quebec corridor.
- Chiplet Architecture Convergence:Modular processor designs enable Canadian system integrators to customize configurations for financial services latency requirements without full silicon redesign.
- Provincial Clean Electricity Standards:Ontario and Quebec carbon intensity benchmarks reward facilities deploying energy-efficient processors with preferential interconnection treatment and accelerated permitting.
Industry Challenges
- Specialized Thermal Engineering Talent:Domestic labor pools lack sufficient depth in 400W+ thermal design power management, forcing operators to import expertise for high-density deployments.
- Legacy x86 Integration Complexity:Financial services data centers in Toronto face extended validation cycles when heterogeneous accelerators must interoperate with established virtualization stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Processor Market |
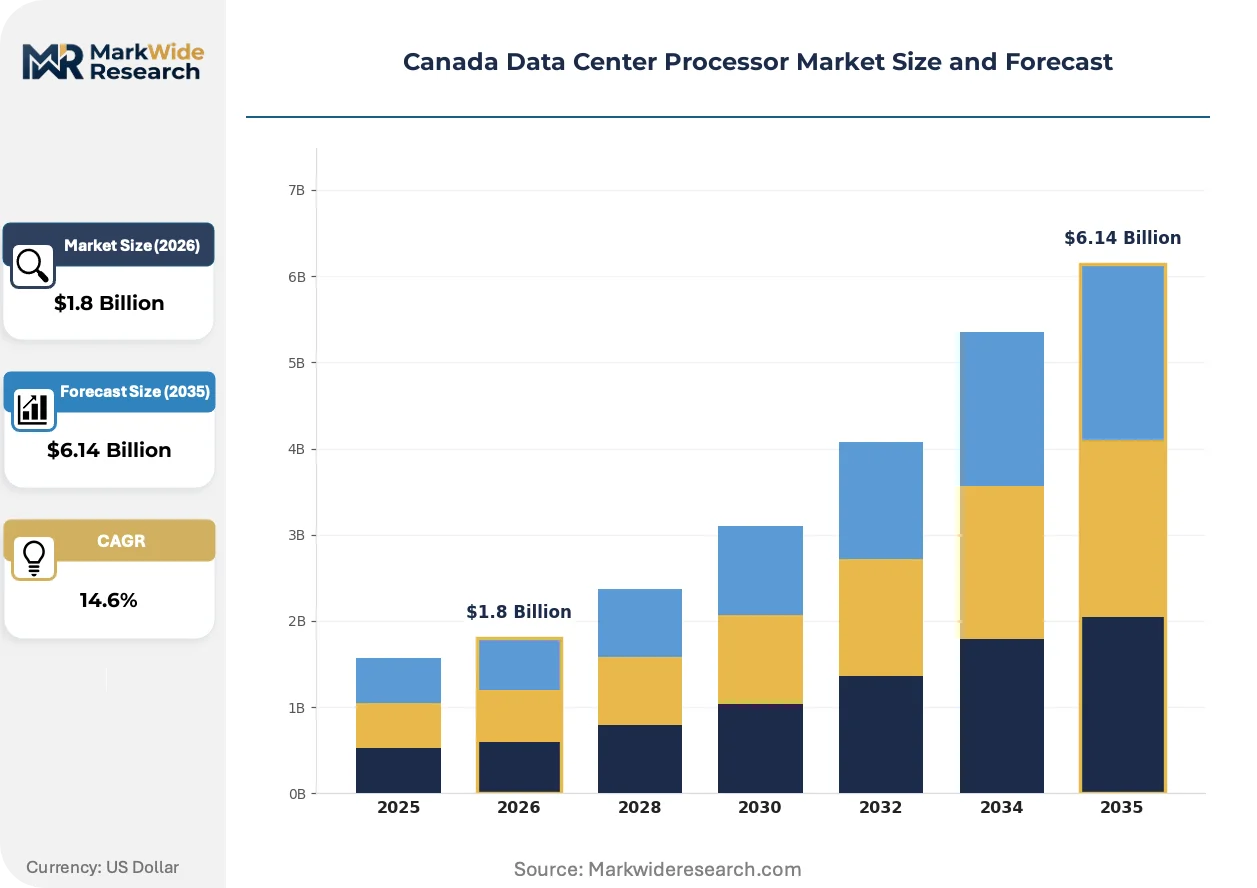
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Technology: Cloud Computing, Edge Computing, Virtualization, Big Data Analytics End User: Enterprise, Telecom, Government, Managed Service Providers Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Backup Solutions |
| Companies Covered | Arm Holdings plc, Amazon Web Services, Intel Corporation, Qualcomm Incorporated, IBM Corporation, Advanced Micro Devices Inc., Ampere Computing, Broadcom Inc., NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Processor Market Trends and Innovations
Processor architectures are fragmenting across workload-specific designs, with Canadian deployments at the forefront of heterogeneous compute integration driven by AI training and inference demands.
Chiplet-based CPU designs are decomposing monolithic silicon into modular compute, memory, and I/O tiles. Toronto financial services operators are adopting these architectures for enterprise refresh cycles to optimize price-performance for mixed virtualization workloads. This modularity is decomposing traditional socket-level upgrade cycles into component-level refresh decisions, compressing replacement timelines and expanding addressable silicon content per rack.
Natural Resources Canada's forthcoming critical technology procurement guidelines will impose supply chain attestation requirements on processors deployed in federal and telecom infrastructure. The industrial consequence is mandatory vendor documentation of fabrication origin and component provenance. Government data center operators in Ottawa and classified facilities are pre-qualifying suppliers with established domestic security clearance pathways.
Canadian hyperscale buyers are consolidating procurement authority into centralized technical sourcing teams with direct foundry relationships, displacing traditional distributor and value-added reseller channels. This concentration is visible in Montreal and Toronto corridor negotiations where cloud operators negotiate volume commitments directly with merchant silicon vendors. The shift compresses margin capture by intermediate channels while accelerating custom SKU development for domestic climate and power constraints.
Canada Data Center Processor Market Segmentation
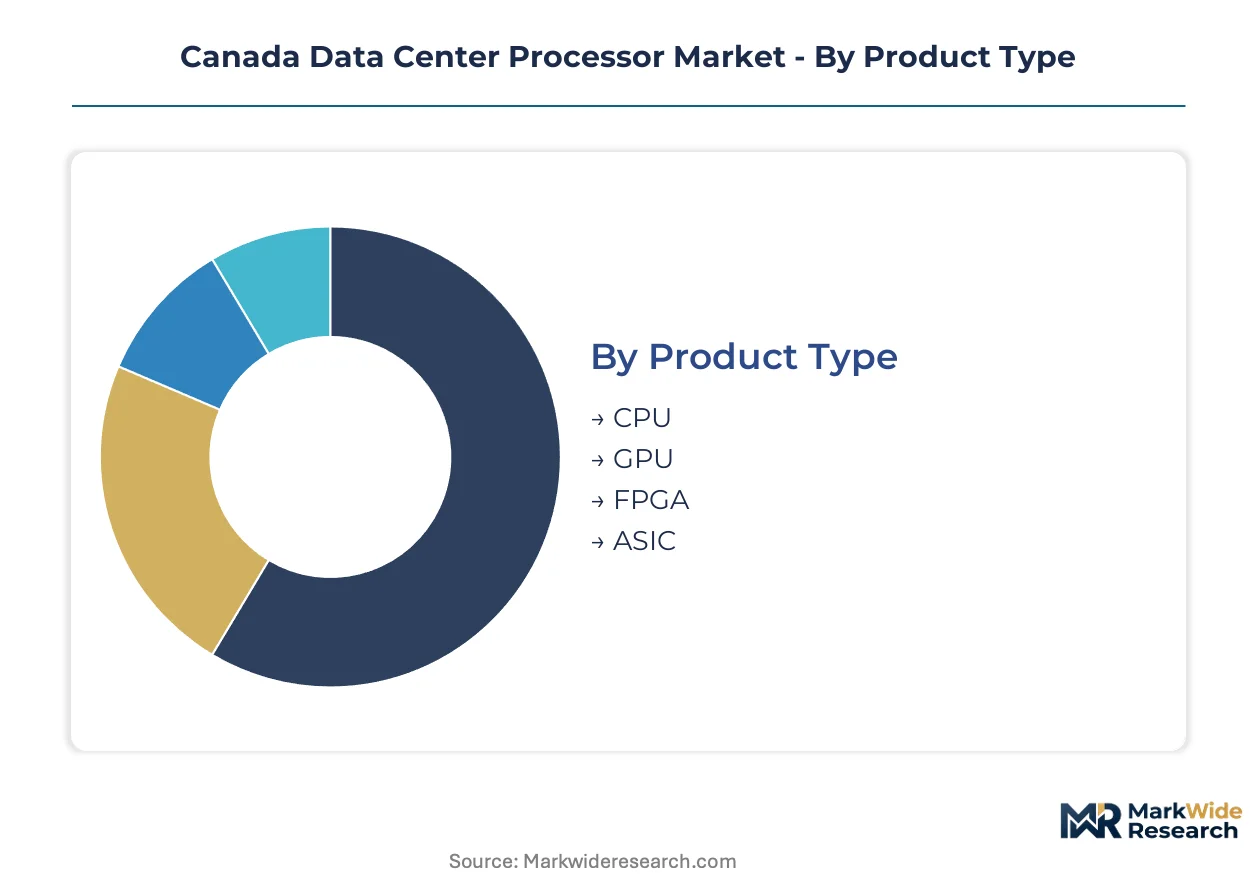
Processor segmentation across Canadian data center deployments reflects divergent workload requirements between AI training clusters and enterprise virtualization. Each category captures distinct procurement patterns shaped by thermal constraints, latency tolerances, and federal efficiency mandates.
Product Type:
FPGA and ASIC segments face accelerating substitution pressure from programmable GPU architectures as hyperscale operators prioritize software-defined flexibility over fixed-function silicon.
- CPU:General-purpose x86 and ARM architectures anchor virtualization workloads across Toronto financial services and Ottawa government facilities. Enterprise refresh cycles in Ontario concentrate procurement toward processors with integrated AI acceleration blocks, responding to Natural Resources Canada performance-per-watt benchmarks.
- GPU:Parallel compute engines with high-bandwidth memory interfaces dominate Montreal-based AI training clusters and Quebec hyperscale buildouts. NVIDIA and AMD accelerator procurement cycles expand as research institutes scale generative inference deployments, exploiting Quebec Hydroelectric low-carbon baseload.
- FPGA:Reconfigurable logic devices retain niche positioning for low-latency financial trading applications requiring deterministic execution.
- ASIC:Custom silicon designs serve specialized inference workloads where power efficiency outweighs programmability requirements.
CPU retains volume leadership across domestic installations; GPU holds the steepest expansion curve.
Technology:
Cost tier differentiation separates capital-intensive cloud deployments from distributed edge infrastructure requiring minimal unit economics.
- Cloud Computing:Centralized hyperscale processing aggregates compute, storage, and networking resources across Ontario and Quebec facilities. Montreal corridor operators negotiate direct foundry relationships for custom silicon SKUs matching regional climate constraints.
- Edge Computing:Distributed low-latency nodes process 5G network slicing workloads in Vancouver and Calgary telecom environments. Telus and Rogers deploy compact processors with sub-75W thermal envelopes to minimize remote cooling requirements.
- Virtualization:Hypervisor-optimized silicon enables multi-tenant resource pooling for Toronto managed service providers.
- Big Data Analytics:Memory-bandwidth-intensive configurations support batch processing pipelines in enterprise data lakes.
Cloud Computing dominates capital deployment; Edge Computing is climbing the fastest.
End User:
Customer type fragmentation produces divergent procurement authority structures, with government security clearances filtering vendor pools differently than enterprise technical evaluations.
- Enterprise:Toronto financial services and Calgary energy sector operators drive heterogeneous compute adoption, integrating GPU accelerators with established x86 virtualization stacks. Extended validation cycles complicate refresh timelines when legacy infrastructure must interoperate with new silicon generations.
- Telecom:National carriers deploy processors across 5G core networks and edge aggregation points, prioritizing supply chain security attestations under Health Canada guidelines.
- Government:Federal facilities in Ottawa and classified installations require processors with documented fabrication provenance and domestic security clearance pathways.
- Managed Service Providers:Colocation operators aggregate fragmented enterprise demand into volume procurement negotiations with merchant silicon vendors.
Enterprise maintains the largest installed base; Government procurement is expanding most quickly under critical infrastructure mandates.
Service Type:
Margin concentration varies across infrastructure, platform, and software layers, with hardware procurement patterns tracking service monetization models.
- Infrastructure as a Service:Bare-metal and virtualized compute provisioning requires high-core-count processors with robust memory channel support. Quebec hyperscale operators prioritize energy-efficient silicon to maximize rack density within provincial clean electricity standards.
- Platform as a Service:Container orchestration and serverless execution environments drive demand for processors with hardware-assisted virtualization extensions.
- Software as a Service:Application-layer services abstract underlying silicon specifications, though latency-sensitive SaaS workloads still influence edge processor selection.
- Backup Solutions:Secondary storage and disaster recovery infrastructure utilizes cost-optimized processor configurations with reduced compute intensity.
Infrastructure as a Service commands the dominant hardware spend; Platform as a Service shows the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processor procurement elasticity varies sharply across Canadian provinces. Quebec hyperscale operators exhibit price-inelastic demand for AI accelerators, while Alberta edge deployments prioritize unit economics above performance-per-watt optimization.
Ontario
Toronto financial services operators drive heterogeneous compute integration, mixing GPU accelerators with legacy x86 virtualization stacks. Natural Resources Canada clean electricity regulations compel facility operators toward processors with documented performance-per-watt superiority. The Toronto corridor anchors domestic hyperscale buildout concentration, with cloud operators negotiating direct foundry relationships for climate-customized silicon SKUs.
Quebec
Montreal-based research institutes scale GPU-intensive generative AI inference deployments, exploiting Quebec Hydroelectric low-carbon baseload power. Health Canada supply chain security requirements filter vendor pools for federal and telecom infrastructure deployments. The Montreal corridor attracts international hyperscale investment through provincial clean electricity standards that reward energy-efficient processor deployments with preferential interconnection treatment.
British Columbia
Vancouver telecom operators deploy 5G network slicing nodes requiring compact processors with sub-75W thermal envelopes. Telus prioritizes supply chain security attestations under federal critical infrastructure guidelines. The Pacific coast concentration supports low-latency edge compute for transpacific cable termination points and Asia-Pacific data routing.
Alberta
Calgary energy sector data centers face compressed margins that prioritize cost-optimized processor configurations over leading-edge node silicon. Provincial carbon pricing mechanisms create procurement complexity for operators balancing performance requirements against compliance costs. The Prairie region exhibits slower refresh cycles than Ontario-Quebec corridors due to heterogeneous workload fragmentation across oilfield services and agricultural technology applications.
Canada Data Center Processor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Canadian deployments. The vendor base concentrates around three strategic tiers: merchant silicon vendors with direct hyperscale relationships, custom silicon designers serving cloud operators, and specialized accelerator providers targeting AI workloads. Competitive moves cluster on foundry partnership formations and chiplet architecture licensing arrangements that enable modular system configurations.
Within the merchant silicon tier, Intel Corporation and NVIDIA Corporation exemplify divergent specialization vectors—Intel anchors general-purpose virtualization procurement through established x86 socket compatibility, while NVIDIA occupies the accelerator-dominant position for Montreal-based AI training clusters. Advanced Micro Devices Inc. sits within the challenger archetype, leveraging chiplet modularity to compete for enterprise refresh contracts in Toronto financial services facilities. These three anchors collectively represent the procurement concentration patterns visible across Ontario and Quebec hyperscale negotiations.
| Leading Market Players |
|---|
| Arm Holdings plc |
| Amazon Web Services |
| Intel Corporation |
| Qualcomm Incorporated |
| IBM Corporation |
| Advanced Micro Devices Inc. |
| Ampere Computing |
| Broadcom Inc. |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
GPU-to-custom-ASIC substitution in Montreal AI training clusters simultaneously redraws procurement geography toward Taiwan-based foundries and compresses accelerator pricing economics as hyperscale operators negotiate direct volume commitments. This displacement forces merchant silicon vendors to bundle extended service contracts to defend margin pools against programmable logic erosion.
Pricing Analysis
After-sales service revenue from thermal engineering support and extended firmware maintenance drives lifetime value capture for domestic deployments. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale direct-foundry contracts from distributor-mediated enterprise procurement and cost-optimized edge configurations. Pricing pressure stems from memory-DDR5 cost volatility compressing total cost of ownership calculations for Toronto financial services operators. Government facilities in Ottawa exhibit lowest price sensitivity due to mandatory vendor qualification pathways, while Calgary energy sector data centers face acute unit economics constraints.
Supply Chain Analysis
Taiwan Strait transit risk underwrites supply continuity planning for Canadian hyperscale operators dependent on leading-edge 5nm-7nm fabrication. Taiwan, South Korea, and the United States anchor wafer supply concentration, with high-bandwidth memory modules and advanced packaging substrates feeding from Japan and Singapore. Single-source vulnerability in EUV lithography equipment creates structural exposure to export control adjustments. Distribution runs through consolidated technical sourcing teams with direct foundry relationships, displacing traditional value-added reseller channels across Ontario and Quebec corridor negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating into centralized hyperscale procurement teams, fragmenting vendor negotiation leverage as cloud operators bypass intermediate distribution layers. This consolidation reshapes competitive dynamics across domestic silicon procurement.
For Market Incumbents: Fortify foundry partnership exclusivity through volume commitments tied to Quebec Hydroelectric interconnection advantages. Defend against chiplet architecture challengers by accelerating custom SKU development for Natural Resources Canada efficiency benchmarks. Prioritize domestic security clearance pathway investments to maintain government facility access against emerging merchant silicon competitors. For New Entrants and Emerging Players: Edge orchestration software gaps in Vancouver 5G network slicing deployments offer white-space entry points outside Ontario-Quebec hyperscale concentration. Target Calgary energy sector latency requirements with modular processor configurations bypassing legacy x86 validation complexity. Pursue Telus and Rogers channel partnerships to establish supply chain security attestation credibility under Health Canada guidelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed colocation operators in Toronto corridor seeking processor refresh financing across extended enterprise validation timelines. Five-to-ten year viability hinges on heterogeneous compute integration capabilities rather than single-architecture dominance. Monitor Natural Resources Canada critical technology procurement guideline finalization as inflection indicator for vendor qualification pathway restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Formation | Direct wafer supply agreements with TSMC secure capacity allocation for Quebec hyperscale buildouts. |
| Chiplet Architecture Licensing | Modular IP arrangements enable Toronto financial services customization without full silicon redesign cycles. |
| Domestic Security Clearance Investment | Health Canada attestation pathways unlock Ottawa government facility procurement beyond merchant silicon tiers. |
| Edge Compute Platform Launch | Sub-75W thermal envelope processors address Vancouver telecom 5G network slicing requirements. |
| Energy Efficiency Certification Program | Natural Resources Canada performance-per-watt documentation accelerates provincial interconnection approvals. |
Research Methodology
Operator-level perspectives from hyperscale procurement directors, colocation facility engineers, and telecom network architects anchored the qualitative base for this analysis. Primary field engagement with Toronto financial services IT infrastructure leads and Montreal research institute compute directors combined with secondary validation against foundry capacity disclosures, hyperscaler capex filings, and provincial clean electricity regulatory texts. Bottom-up installation tracking across Ontario and Quebec facilities triangulated against top-down semiconductor trade flow analysis.
Sensitivity analysis tested forecast outputs against alternative scenarios for foundry capacity allocation and memory cost trajectory assumptions across the projection horizon. Segmentation modeling incorporated processor architecture type, deployment technology tier, end-user category, and service layer monetization structure. CAGR derivation rested on installation base expansion rates, refresh cycle compression factors, and workload density requirements from generative AI inference scaling. Quebec Hydroelectric interconnection queue dynamics and Health Canada vendor qualification timeline assumptions shaped regional outlook calibration.
Underlying assumptions cover sustained hyperscale investment commitment, stable Taiwan-based fabrication access, and consistent federal efficiency regulation enforcement, with deviation risk concentrated in export control expansion and domestic thermal engineering labor availability constraints. Practitioners should keep alternative scenarios live as geopolitical supply disruption probabilities and provincial carbon pricing mechanism adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Server Microprocessor Market