
 Global LCD TV Core Chip Market | 2026-2036
Global LCD TV Core Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Global LCD TV Core Chip Market Intelligence
A deep divergence in capital investment for advanced process node fabrication is unwinding the traditional competitive landscape. Fabless leaders like MediaTek leverage third-party foundries to focus on SoC design innovation for smart TVs. In contrast, Samsung Electronics sustains its market position through significant in-house semiconductor manufacturing scale. Broadcom Corporation competes by specializing in high-performance connectivity and processing solutions for the premium TV segment.
An LCD TV core chip is a specialized semiconductor, typically a System-on-Chip (SoC), that integrates multiple processing functions for a television display. These chips manage critical tasks including video signal decoding, image scaling, and user interface control, utilizing advanced CMOS process technology. SoC Chips command the largest value share due to their high integration complexity. The Smart TVs application drives the majority of volume, while Gaming Monitors represent a high-margin growth niche.
Energy efficiency standards, such as the EPA's ENERGY STAR program in the United States and EU Ecodesign requirements, influence power management IC design. Substance restrictions like the EU's RoHS directive and China's GB standards mandate the removal of hazardous materials, impacting supply chain sourcing. Chip vendors must therefore balance performance improvements with a complex and diverging set of international compliance obligations.
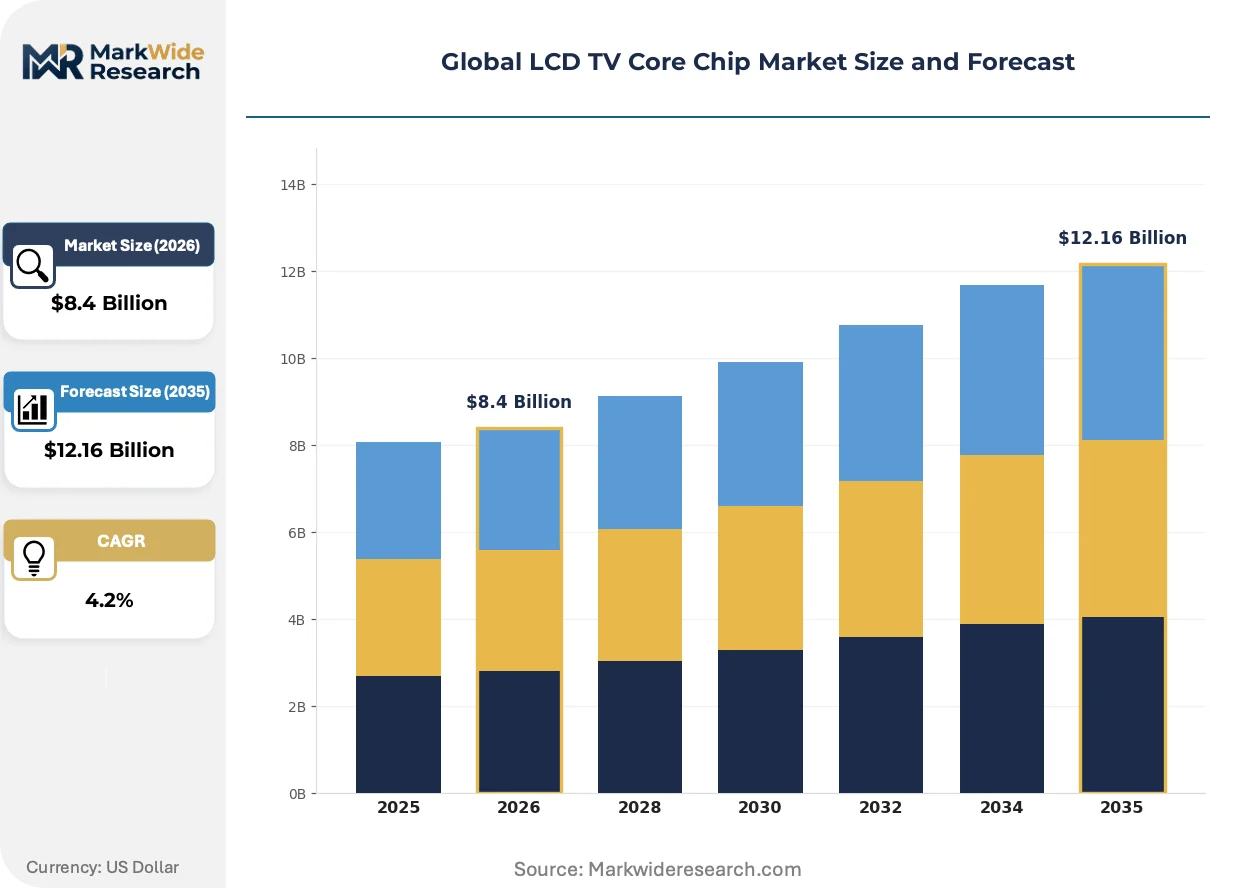
Market Dynamics
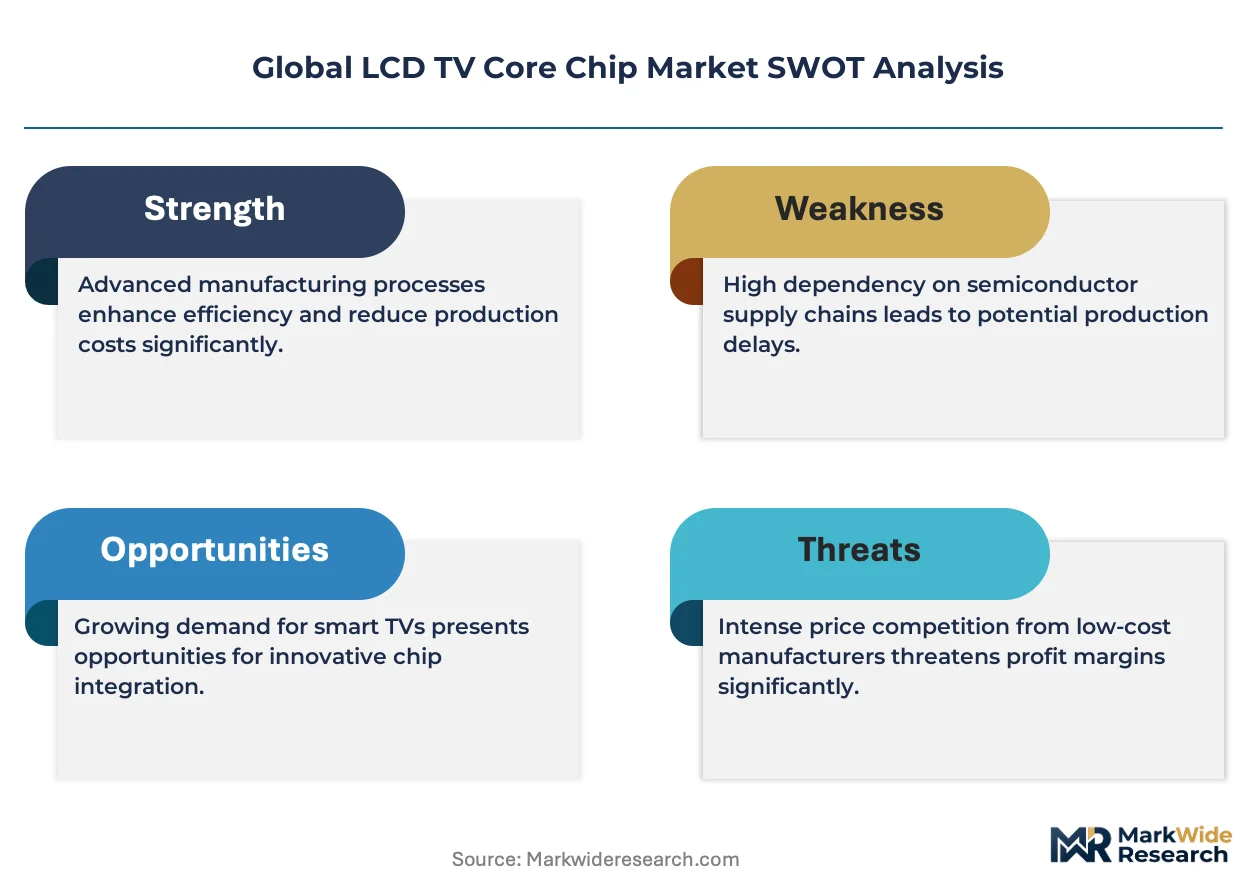
Divergence in semiconductor manufacturing strategies is the central force. Fabless firms focus on design while integrated device manufacturers leverage in-house fabrication, creating distinct pressures on cost, innovation, and supply chain control.
Growth Catalysts
- 8K and HDR Content:The transition to ultra-high-definition formats requires more powerful SoCs with advanced video decoding and image processing, driving upgrades.
- Gaming Monitor Segment:Demand from gaming for high-refresh-rate displays accelerates the need for specialized SoCs that can handle faster signal processing.
- Energy Efficiency Standards:Regulations like the EU Ecodesign directive push vendors to innovate in low-power chip design and integrated power management.
Market Restraints
- Advanced Node Costs:High capital expenditure for designing chips on sub-7nm process nodes creates a significant barrier to entry for new competitors.
- Foundry Concentration:Heavy reliance on a few advanced foundries, primarily in Taiwan, introduces significant geopolitical and supply chain risks for the industry.
- Alternative Display Technologies:The rise of OLED and MicroLED displays, which use different driver IC architectures, poses a long-term substitution threat.
Strategic Opportunities
- Automotive Display Systems:Large, high-resolution screens in vehicle cockpits are opening a new market for specialized media processing SoCs.
- Embedded AI Processing:Integrating dedicated AI cores into the SoC enables advanced features like real-time content upscaling, creating new product differentiation.
- Smart TV Growth in India:Rising disposable incomes and India's PLI scheme create opportunities for chip vendors in its expanding smart TV market.
Industry Challenges
- Diverging Compliance Standards:Vendors navigate complex substance restrictions like the EU's RoHS directive and China's GB standards, alongside energy rules, increasing design costs.
- SoC Design Talent Scarcity:A global shortage of skilled engineers for complex SoC design and verification creates a bottleneck for innovation and product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LCD TV Core Chip Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SoC Chips, T-Con Boards, Timing Controllers, Power Management ICs, LED Drivers Technology: CMOS, GaAs, Bipolar, SiGe, FinFET Application: Smart TVs, Commercial Displays, Projectors, Digital Signage, Gaming Monitors End User: TV Manufacturers, Display Module Suppliers, Electronics ODMs, Assembly Plants |
| Companies Covered | Broadcom Corporation, Realtek Semiconductor, MediaTek, Panasonic, Sony, Amlogic, Novatek Microelectronics, Toshiba, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LCD TV Core Chip Market Strategic Shifts & Innovations
Software-defined features and direct-to-consumer content delivery are transforming the core chip from a simple signal processor into an intelligent, connected hub. This evolution prioritizes processing power for AI-driven user experiences and seamless integration with diverse content ecosystems.
Dedicated Neural Processing Units (NPUs) are being integrated directly into television SoCs to accelerate artificial intelligence workloads. Premium and mid-range smart TV segments are rapidly adopting this technology for enhanced picture quality. This on-chip AI acceleration is displacing older, CPU-bound algorithms for tasks like real-time object recognition and sophisticated content upscaling.
European Union Ecodesign requirements for electronic displays mandate stringent limits on power consumption in both on-mode and standby. This regulation forces chip designers to innovate in low-power architectures and advanced power management ICs. The high-performance 8K TV segment is particularly impacted, needing to balance immense processing demands with these efficiency targets.
Television manufacturers are migrating from proprietary operating systems to licensed, open platforms like Google TV and other Android TV variants. This shift disrupts the traditional model where chip vendors supplied tightly integrated hardware and software, favoring SoCs optimized for these open ecosystems. This trend is most prominent in North America, where app availability is a key consumer purchase criterion.
Global LCD TV Core Chip Market Segmentation
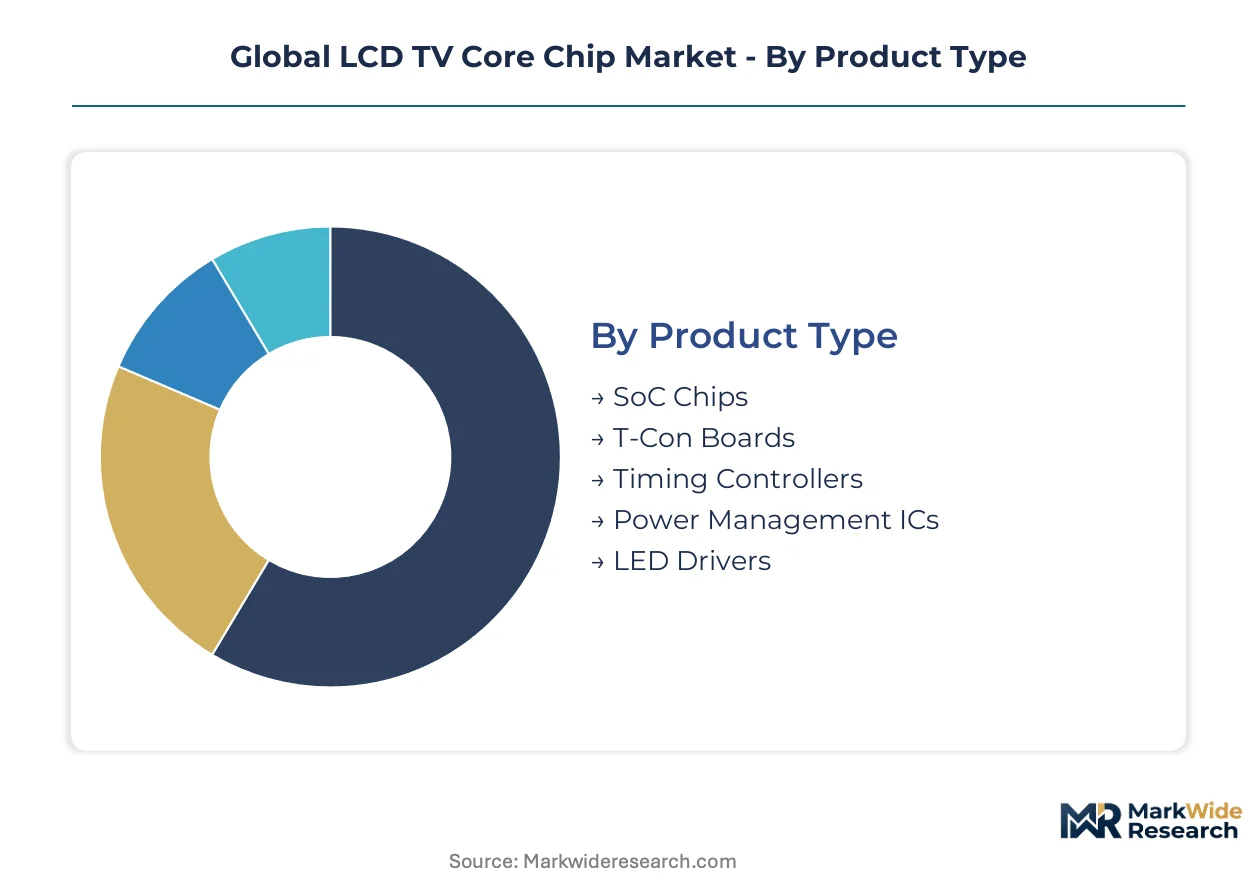
Understanding the market segmentation for LCD TV core chips is critical for identifying specific demand drivers and technological shifts. This detailed categorization reveals how diverse product types, underlying technologies, application areas, and end-user structures contribute to the market's overall dynamics and value distribution.
Product Type:
Regulatory mandates, such as the EU Ecodesign directive and EPA's ENERGY STAR program, significantly differentiate product type development within the LCD TV core chip market.
- SoC Chips:These highly integrated System-on-Chip solutions combine multiple processing functions, including video decoding, image scaling, and user interface control, onto a single die. Demand for SoC Chips is concentrating in the 8K and HDR content segments, driven by the need for advanced video processing capabilities.
- Power Management ICs:Specialized integrated circuits regulate and distribute power efficiently across the various components of an LCD TV core chip system. The EU Ecodesign requirements are a primary driver for innovation in low-power architectures and integrated power management ICs.
- T-Con Boards:Timing controller boards manage the data flow from the SoC to the display panel, ensuring precise synchronization and image quality. These boards are essential for maintaining picture integrity across various refresh rates.
- Timing Controllers:These components specifically synchronize video signals and display panel operations. Precision timing controllers are crucial for high-refresh-rate gaming monitors.
- LED Drivers:Circuits designed to control the current supplied to the LED backlights of LCD panels, influencing brightness and local dimming capabilities. Energy efficiency standards globally influence LED driver design.
SoC Chips handle the majority of processing throughput; Power Management ICs are the fastest mover on share due to efficiency demands.
Technology:
Cost tiers for advanced process nodes heavily influence technology segment adoption, creating distinct competitive advantages.
- CMOS:Complementary Metal-Oxide-Semiconductor technology forms the foundation for most digital integrated circuits, offering high integration density and low power consumption. CMOS remains the dominant technology for LCD TV core chips due to its proven scalability and cost-effectiveness.
- FinFET:Fin Field-Effect Transistor technology represents an advanced semiconductor device architecture, enabling smaller, faster, and more energy-efficient chips, particularly for sub-7nm process nodes. The transition to 8K processing and embedded AI cores is accelerating FinFET adoption in premium SoC designs.
- GaAs:Gallium Arsenide is a compound semiconductor known for its high-speed electronic properties, often used in specialized high-frequency applications. GaAs technology finds niche use in specific high-speed interfaces within some core chip designs.
- Bipolar:Bipolar junction transistors offer high current handling capabilities and are used in certain analog and power management sections of core chips. Bipolar technology provides robust performance for specific voltage regulation tasks.
- SiGe:Silicon Germanium alloys combine silicon's processing advantages with germanium's higher electron mobility, offering improved high-frequency performance. SiGe is employed in specific RF and mixed-signal components within complex SoC architectures.
CMOS technology retains its foundational role, while FinFET architectures are rapidly gaining ground for high-performance applications.
Application:
Volume demand from diverse end-use applications shapes the market's application segmentation, driving specialized chip development.
- Smart TVs:Televisions integrated with internet connectivity and interactive features, supporting streaming services, apps, and voice control. Smart TVs drive the majority of volume demand for LCD TV core chips globally.
- Gaming Monitors:High-performance display devices optimized for gaming, featuring high refresh rates, low input lag, and advanced synchronization technologies. Demand from the gaming monitor segment accelerates the need for high-refresh-rate processing capabilities in SoCs.
- Commercial Displays:Large-format screens used in public and business environments for advertising, information dissemination, and presentations. Commercial displays require robust chipsets for continuous operation and diverse content playback.
- Projectors:Devices that project images onto a surface, utilizing core chips for video processing and scaling before image projection. Projectors demand specialized image processing capabilities for various resolutions.
- Digital Signage:Electronic displays used for public information, advertising, and wayfinding in various commercial settings. Digital signage applications require reliable video decoding and content management from their core chips.
Smart TVs generate the largest volume of chip demand, with Gaming Monitors showing the steepest expansion trajectory.
End User:
Supply chain concentration among key manufacturing hubs in China and Taiwan dictates the market's end-user dynamics.
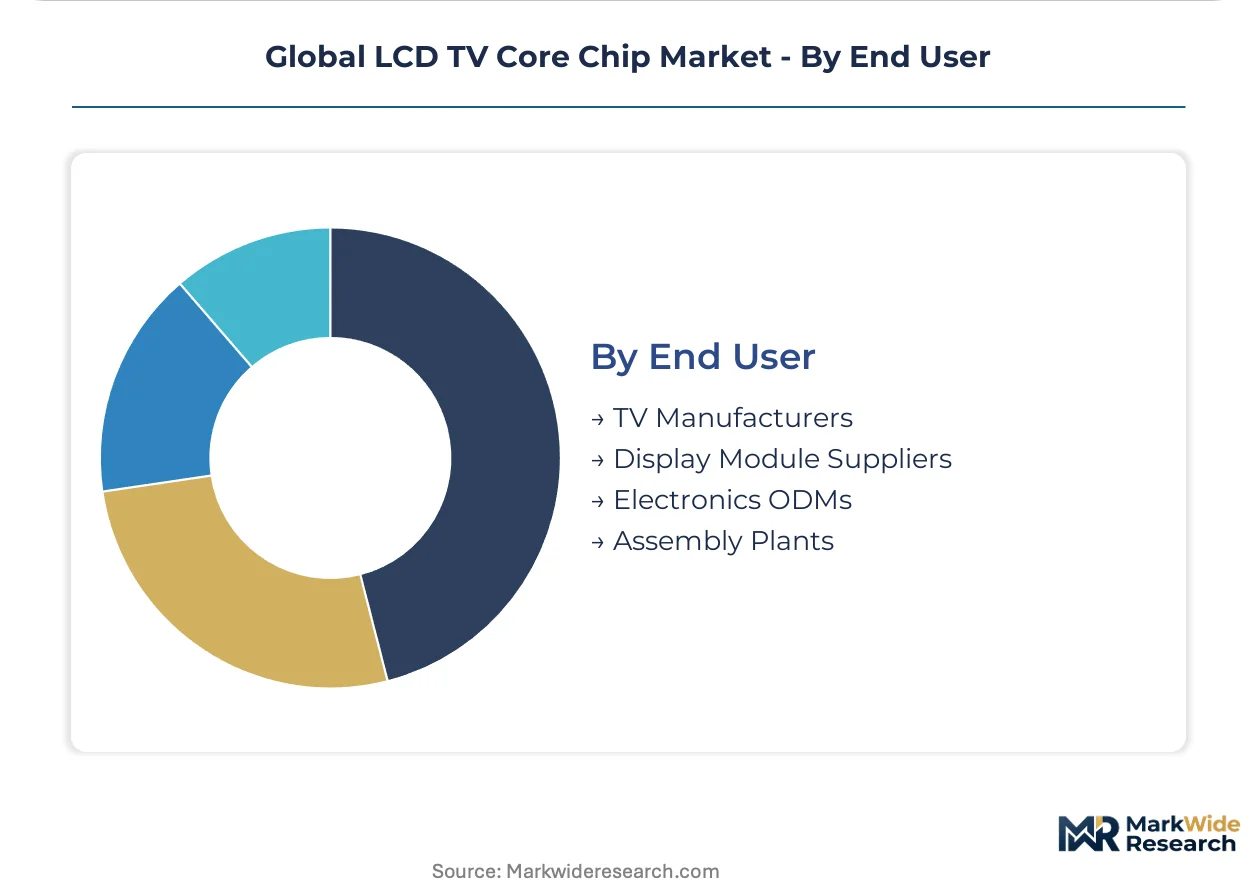
- TV Manufacturers:Companies that design, assemble, and market complete television sets to consumers. TV manufacturers represent the primary direct purchasers of LCD TV core chips.
- Electronics ODMs:Original Design Manufacturers that design and produce electronic products or components for other companies under their brand. Electronics ODMs, particularly in China, play a significant role in the supply chain for various display products.
- Display Module Suppliers:Companies that produce integrated display modules, often including the panel, backlight, and basic driver electronics, for TV manufacturers and other integrators. Display module suppliers procure timing controllers and LED drivers.
- Assembly Plants:Facilities focused on the final assembly of electronic devices from pre-fabricated components. Assembly plants integrate core chips into the final TV product.
TV Manufacturers command the largest procurement volumes, and Electronics ODMs are steadily increasing their influence in the supply chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for LCD TV core chips varies significantly across segments. Smart TVs drive high-volume, cost-sensitive procurement, while high-refresh-rate gaming monitors command premium pricing due to specialized performance requirements. Ultra-high-definition 8K and HDR content segments also prioritize performance over cost.
China
China's vast domestic market drives substantial demand for cost-effective Smart TV core chips. The country's GB standards influence material sourcing and design practices for local production. Manufacturing and design activities in Shenzhen and the Yangtze River Delta concentrate chip production near panel producers.
United States
United States consumers prioritize advanced features like high-refresh-rate gaming and seamless app integration for Smart TVs. The EPA's ENERGY STAR program mandates strict power efficiency for display components, impacting chip design. Technology hubs in Silicon Valley and Texas foster innovation in high-performance SoC architectures.
India
India's rapidly expanding Smart TV market, fueled by rising disposable incomes, presents a significant growth opportunity for chip vendors. The Indian government's PLI scheme incentivizes local electronics manufacturing, including display components. Bengaluru and Hyderabad are emerging as key centers for semiconductor design and software development.
Germany
Germany's market emphasizes premium television experiences and stringent energy efficiency in consumer electronics. EU Ecodesign requirements and the RoHS directive significantly influence power management IC design and material compliance. Dresden and Munich host advanced semiconductor research and manufacturing, focusing on high-performance and low-power solutions.
Global LCD TV Core Chip Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the LCD TV core chip market. The competitive landscape bifurcates between fabless design innovators and integrated device manufacturers with significant in-house fabrication capabilities. Strategic archetypes include specialized performance providers, high-volume SoC producers, and connectivity solution experts. Companies pursue design innovation and manufacturing scale to secure their market positions.
Specialists in high-performance connectivity solutions like Broadcom Corporation occupy a distinct position within the premium TV segment. Fabless leaders such as MediaTek leverage third-party foundries to focus on System-on-Chip design innovation for smart televisions. Samsung Electronics sustains its market position through significant in-house semiconductor manufacturing scale, integrating chip production with its display business.
| Leading Market Players |
|---|
| Broadcom Corporation |
| Realtek Semiconductor |
| MediaTek |
| Panasonic |
| Sony |
| Amlogic |
| Novatek Microelectronics |
| Toshiba |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts for advanced process nodes lock in both supply access and price visibility for LCD TV core chip vendors. This structure moderates short-term price volatility but cements cost structures linked to foundry investments.
Pricing Analysis
After-sales support contracts for premium SoC designs drive lifetime value for chip manufacturers. Per-unit transactional pricing dominates for standard SoC chips, while value-based pricing applies to specialized FinFET solutions. Brand premium and volume scale are key price differentiation drivers. Pricing softness stems from intense competition in the Smart TV segment. Smart TV ODMs are the most price-sensitive buyers, while gaming monitor manufacturers prioritize performance over cost.
Supply Chain Analysis
Foundry concentration in Taiwan underpins the global supply chain for advanced LCD TV core chips. The industry draws heavily from silicon wafers and specialized process chemicals for FinFET fabrication. Single-source vulnerability to these advanced foundries creates a significant supply chain risk. Direct sales to TV manufacturers and through electronics ODMs form the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A fragmentation opportunity exists within the LCD TV core chip market, driven by the demand-side shift toward specialized processing for gaming monitors and automotive displays.
For Market Incumbents: Shield core SoC market share by deepening R&D investment in dedicated NPU architectures. Vertical integration into advanced process node development helps mitigate the threat from rising foundry costs. Consolidate market position through strategic partnerships with 8K panel manufacturers. Talent scarcity in SoC design poses a continuous threat to innovation cycles.
For New Entrants and Emerging Players: A service-layer gap in optimized software-hardware co-design for specific regional ecosystems offers a white-space target. Focus on niche applications like automotive display systems or specialized AI upscaling solutions. India's expanding Smart TV market represents a penetrable geography. Go-to-market via direct engagement with emerging display module suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized fabless design houses with strong IP portfolios in AI processing or ultra-low-power architectures. Long-term viability hinges on the ability to adapt to next-generation display technologies. Target companies with proven expertise in FinFET or advanced CMOS designs. The signal to watch is the adoption rate of embedded AI cores in mid-range Smart TVs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in NPU Development | Accelerates on-chip AI processing for advanced picture quality and user experiences in smart TVs. |
| Expand Automotive SoC Portfolio | Captures new demand for high-resolution media processing in rapidly evolving vehicle cockpits. |
| Form Foundry Partnerships | Secures access to advanced process nodes critical for next-generation 8K and HDR chip designs. |
| Strengthen IP Licensing Agreements | Enables broader market penetration and revenue streams for specialized video processing algorithms. |
| Develop Ultra-Low-Power Architectures | Meets stringent energy efficiency standards, particularly the EU Ecodesign requirements, for global markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive view of the LCD TV core chip market. Primary interviews included TV manufacturers' procurement leads, SoC design engineers, foundry executives, and gaming monitor developers. Secondary validation drew from SEC filings, government trade data, industry association reports, and patent databases. A bottom-up and top-down triangulation approach ensured data consistency.
The market forecasting over the projection horizon utilized a robust analytical framework. Segmentation dimensions modeled included product type, underlying technology, application area, end-user structure, and regional regulatory influence. Compound Annual Growth Rates were derived from historical trends and projected technological adoption curves. Key forecast inputs included 8K panel penetration rates and NPU integration across TV segments.
Forecasts assume regulatory continuity in the EU, US, and China; material policy shifts would require re-modeling. Geopolitical shifts affecting advanced foundries or rapid adoption of alternative display technologies represent key risk factors. Practitioners should keep alternative scenarios live as content consumption patterns and display technology roadmaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
Car Chip Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Electric Vehicle Silicon Chip Market