
 Digital Signal Controller and Processor Market | 2026-2036
Digital Signal Controller and Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signal Controller and Processor Market Outlook
South Korea is fragmenting as new foundry investments from Samsung and SK Hynix diversify digital signal processor supply beyond traditional strongholds. Texas Instruments leverages its 300-millimeter analog-digital integration to sustain cost leadership in mixed-signal controllers. Analog Devices anchors high-performance DSP architectures for radar and software-defined radio. NXP Semiconductors dominates automotive-grade signal processing with ASIL-certified controller portfolios.
A digital signal controller and processor is a programmable integrated circuit that executes mathematical operations on sampled analog signals converted to digital form, typically operating at clock speeds from tens to hundreds of megahertz with dedicated multiply-accumulate units and hardware circular buffering. Its primary industrial purpose is real-time closed-loop control and deterministic signal conditioning across power electronics, motor drives, and communication infrastructure. Mixed-signal controllers capture expanding margin pools as OEMs consolidate analog front-end and digital processing onto single die to reduce board space and electromagnetic interference. Automotive Systems represents the fastest-growing application segment, driven by electric powertrain inverters, battery management systems, and advanced driver-assistance sensor fusion. Data Processing functionality maintains the largest revenue share, though Signal Filtering is gaining traction in 5G baseband and audio processing endpoints.
FCC equipment authorization rules in the United States, EU CE marking under the Radio Equipment Directive, and China's GB standards for electromagnetic compatibility collectively shape product certification timelines and regional market access requirements. REACH substance restrictions and RoHS hazardous material limits further constrain packaging and substrate material choices for European-bound shipments. Stakeholders must monitor evolving semiconductor export control classifications and carbon-border adjustment mechanisms as these frameworks increasingly determine competitive eligibility across major demand centers.
Market Dynamics
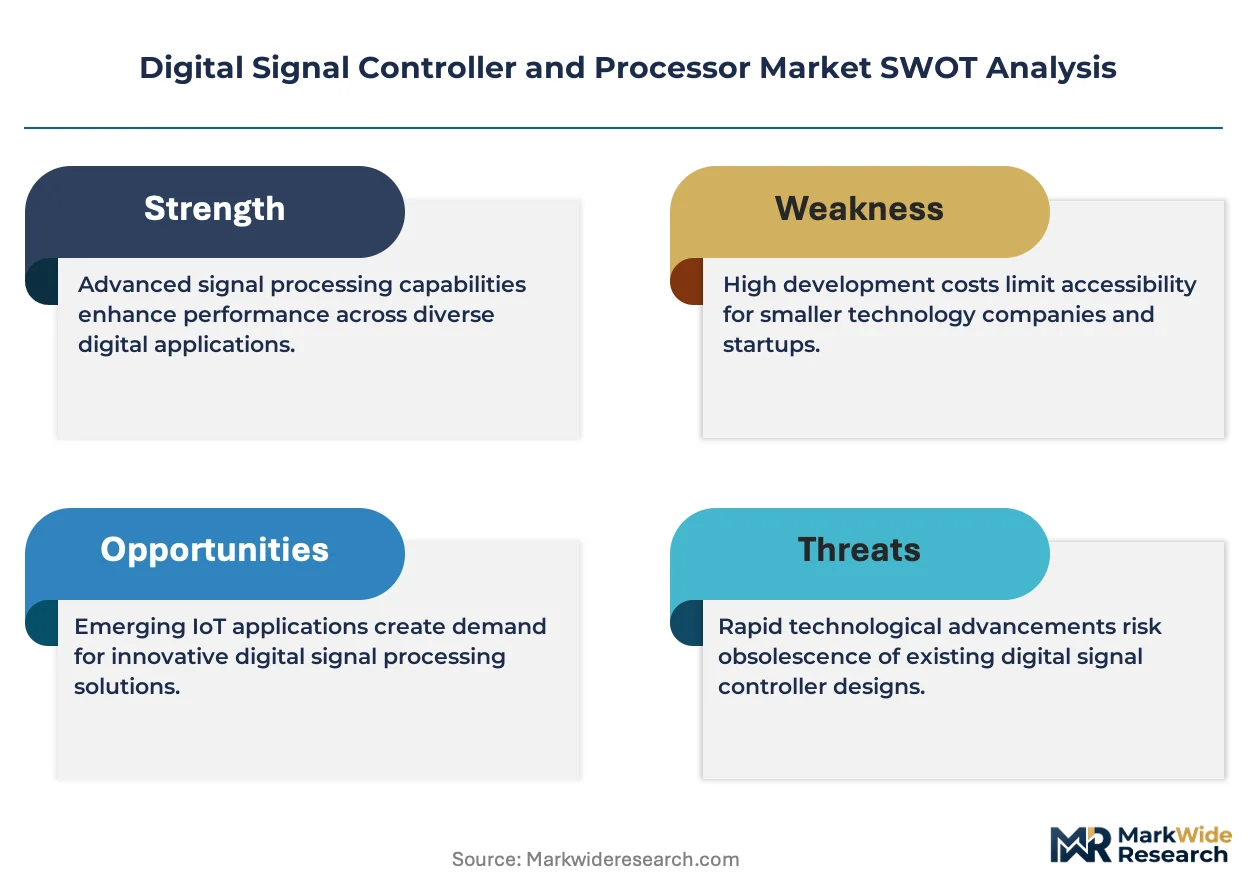
Automotive electrification is consolidating analog-digital integration requirements, forcing semiconductor vendors to merge power management, signal conditioning, and deterministic processing onto single die architectures to meet OEM board-space and electromagnetic interference constraints.
Growth Catalysts
- EU Green Deal efficiency mandates:The F-Gas Regulation and carbon-border adjustment mechanisms compel power electronics manufacturers to adopt higher-efficiency mixed-signal controllers for inverter and motor-drive applications.
- Electric powertrain proliferation:Battery management systems and traction inverters require ASIL-certified signal processing, creating deterministic demand for automotive-grade digital signal controllers across German and South Korean OEM supply chains.
- 5G baseband deployment:Massive MIMO antenna arrays and software-defined radio infrastructure require hardware-accelerated filtering and Fourier transform capabilities, pulling high-throughput DSP architectures into telecommunications capital expenditure cycles.
Market Restraints
- 300-millimeter fab concentration:Advanced mixed-signal integration depends on analog-digital co-fabrication capacity concentrated at Texas Instruments and Samsung facilities, creating geographic supply risk around Austin and Pyeongtaek.
- REACH substance restrictions:RoHS hazardous material limits and ECHA candidate list constraints restrict lead-free solder alternatives and substrate material choices, complicating packaging qualification for European-bound shipments.
- Silicon carbide controller substitution:Wide-bandgap power devices with integrated gate drivers are displacing discrete DSP-plus-MCU architectures in high-frequency inverter applications above 100 kilohertz.
Strategic Opportunities
- India PLI scheme for semiconductors:Production-linked incentives for electronics manufacturing and designated semiconductor clusters in Gujarat and Tamil Nadu offer greenfield fabrication and assembly opportunities for automotive and industrial signal processors.
- Radar sensor fusion architectures:Convergence of millimeter-wave front-ends with machine-learning accelerators creates demand for heterogeneous signal controllers in advanced driver-assistance systems.
- Direct OEM contracting:Tier-1 supplier consolidation is opening direct procurement channels between semiconductor vendors and automotive manufacturers, bypassing traditional distribution margins.
Industry Challenges
- Functional safety certification timelines:ASIL-D qualification for automotive signal controllers requires 18-24 month validation cycles against ISO 26262, compressing product development windows relative to consumer electronics.
- Multiply-accumulate hardware-software co-design:Shortage of engineers proficient in fixed-point arithmetic optimization and circular buffer memory architecture limits firmware development throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signal Controller and Processor Market |
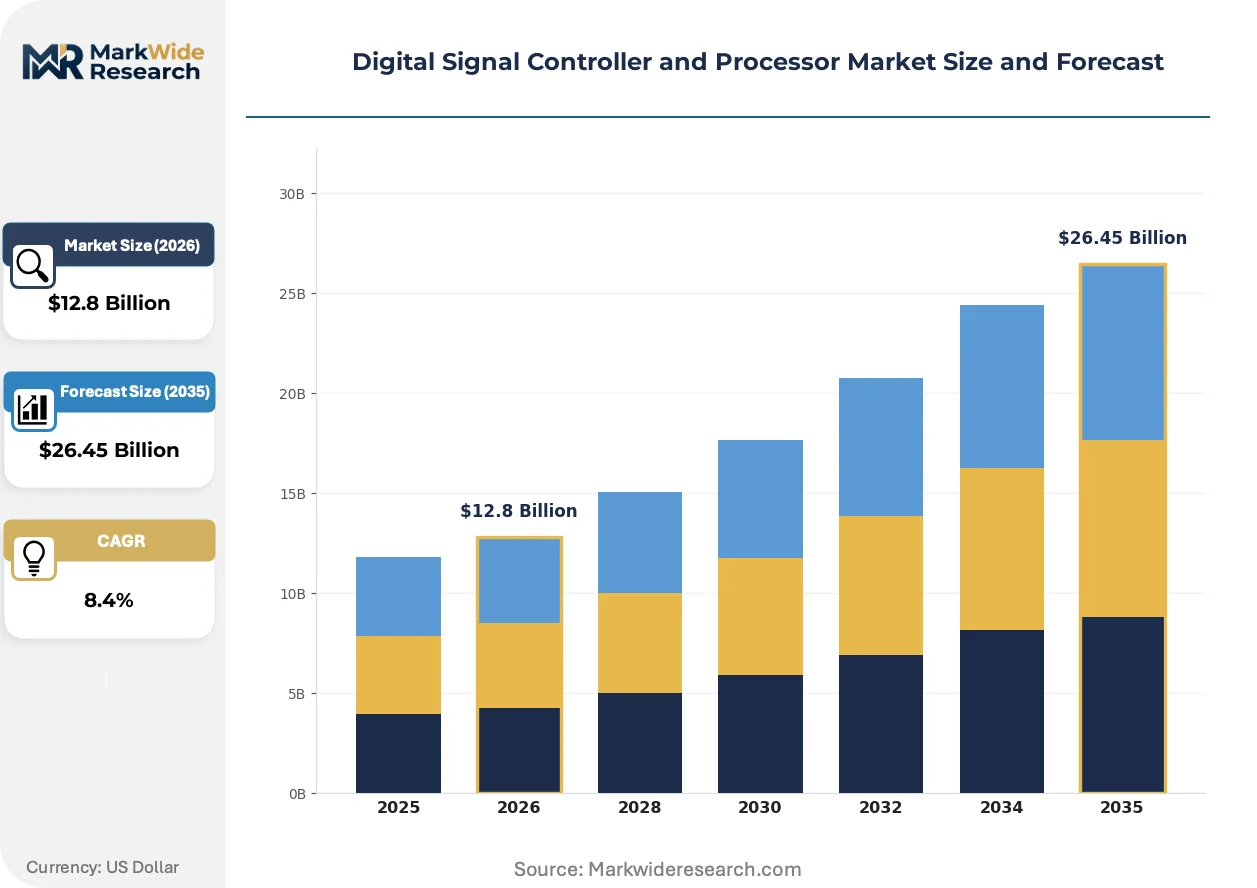
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Controllers, Digital Processors, Mixed-Signal Controllers, DSPs Application: Consumer Electronics, Automotive Systems, Telecommunication, Industrial Automation End User: OEMs, System Integrators, Research Institutions, Technology Providers Functionality: Data Processing, Signal Filtering, Control Systems, Power Management |
| Companies Covered | Texas Instruments, Analog Devices, NXP Semiconductors, STMicroelectronics, Infineon Technologies, Qualcomm, Broadcom, Microchip Technology, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signal Controller and Processor Market Strategic Shifts
Deterministic edge computing architectures are compressing the boundary between real-time control and predictive analytics, embedding inference engines directly within signal processing pipelines previously reserved for pure mathematical operations.
Chiplets with dedicated neural processing units are rendering obsolete discrete DSP-plus-FPGA combinations in radar signal processing chains. Automotive Tier-1 suppliers in Germany and Japan are qualifying these heterogeneous packages for 2025 model-year sensor fusion modules. The integration collapses board area and inter-chip latency while forcing legacy vendors to abandon modular product strategies.
China's GB standards for electromagnetic compatibility are tightening conducted and radiated emission limits for industrial controllers, compelling redesign of switching regulator circuits and PCB layout rules. Domestic manufacturers in Shenzhen and Suzhou are accelerating compliance investments ahead of 2026 enforcement deadlines. European exporters face retesting costs and certification delays for power electronics bound for Chinese battery gigafactories.
Automotive OEMs are unbundling after-sales software calibration from hardware procurement, shifting to subscription-based feature activation for signal processing algorithms. This severs traditional component pricing from lifetime value capture, concentrating margin in firmware licensing. The model is most advanced in German premium electric vehicle programs, where over-the-air updates now deliver adaptive filter tuning and motor control parameter optimization post-delivery.
Digital Signal Controller and Processor Market Segmentation
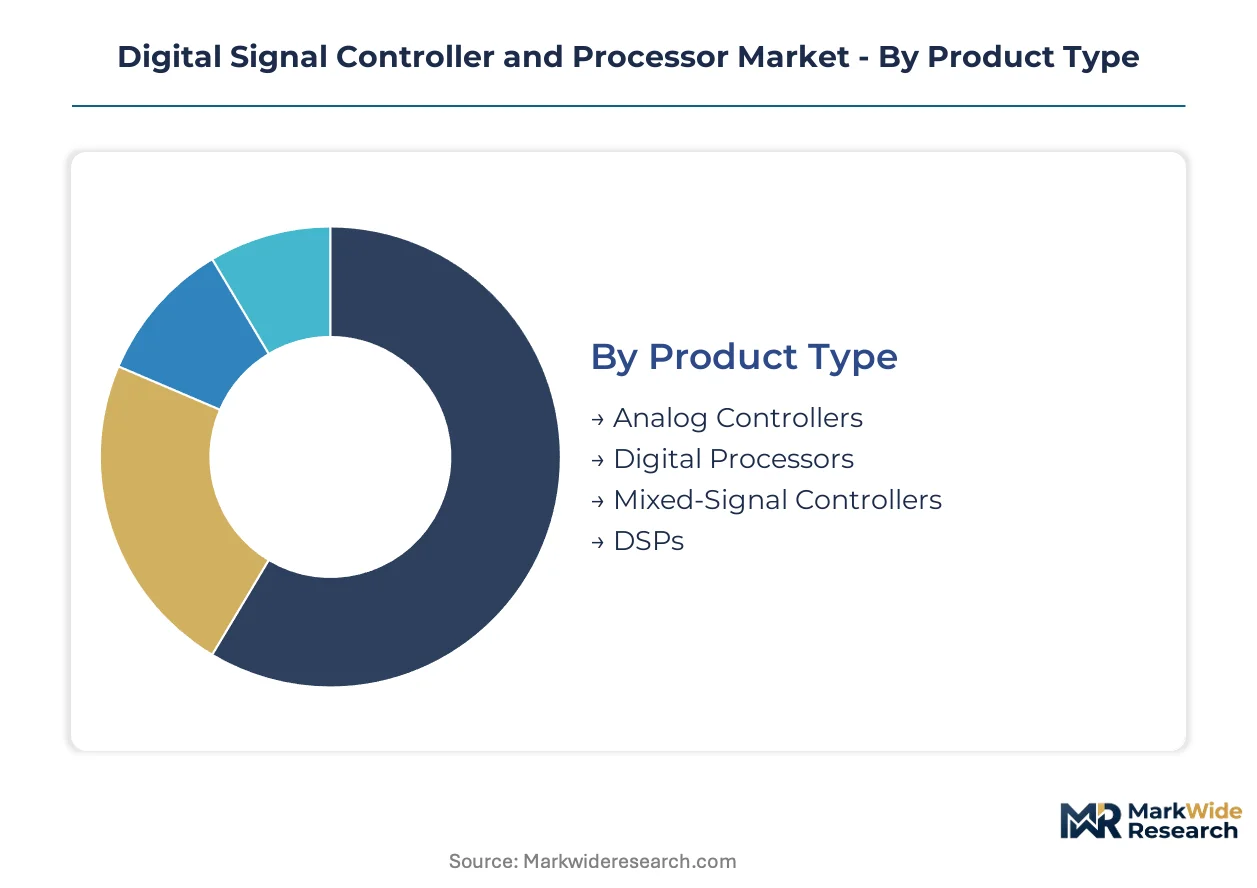
Segmentation reveals how product lifecycle velocity varies dramatically across the digital signal controller and processor landscape. Mixed-signal integration cycles compress to 18-24 months in automotive applications while industrial data processing architectures refresh over 5-7 year horizons.
Product Type:
Cycle times diverge sharply: mixed-signal controllers refresh fastest as OEMs consolidate analog-digital functions, while discrete DSPs maintain longest design-in persistence due to firmware legacy.
- Mixed-Signal Controllers:These devices merge power management, signal conditioning, and deterministic processing onto single die architectures. Battery management systems and traction inverters across German and South Korean OEM supply chains are pulling these controllers into ASIL-certified qualification pipelines. REACH substance restrictions and RoHS hazardous material limits constrain packaging material choices for European-bound shipments.
- Digital Processors:Programmable integrated circuits executing mathematical operations on sampled analog signals at clock speeds from tens to hundreds of megahertz. 5G baseband deployment and massive MIMO antenna arrays in telecommunications infrastructure are accelerating hardware-accelerated Fourier transform capabilities. FCC equipment authorization rules shape product certification timelines for US-bound equipment.
- Analog Controllers:Dedicated circuits managing continuous signal paths without digital conversion stages.
- DSPs:Specialized processors with dedicated multiply-accumulate units and hardware circular buffering for real-time algorithms.
Digital processors anchor the volume base while mixed-signal controllers gain share at the steepest rate.
Application:
Margin structures stratify across application tiers, with automotive commanding premium pricing for functional safety certification while consumer electronics operates at cost-optimized scale.
- Automotive Systems:Electric powertrain inverters, battery management systems, and advanced driver-assistance sensor fusion demand ASIL-certified signal processing. NXP Semiconductors and Texas Instruments compete fiercely for socket wins across Munich and Stuttgart semiconductor corridors. ISO 26262 qualification cycles compress product development windows relative to consumer electronics.
- Telecommunication:Software-defined radio infrastructure and 5G baseband deployment require high-throughput architectures with hardware-accelerated filtering. Massive MIMO antenna arrays in South Korean and US metropolitan deployments pull DSPs into telecommunications capital expenditure cycles.
- Industrial Automation:Motor drives and power electronics for factory automation.
- Consumer Electronics:Audio processing endpoints and portable device signal conditioning.
Automotive systems command the highest margin tier while telecommunication applications expand most quickly.
End User:
Procurement concentration varies by buyer type, with OEMs consolidating direct vendor relationships while system integrators maintain multi-source flexibility.
- OEMs:Automotive and industrial original equipment manufacturers are unbundling after-sales software calibration from hardware procurement. German premium electric vehicle programs now deliver adaptive filter tuning through over-the-air updates post-delivery. Direct OEM contracting is bypassing traditional distribution margins.
- System Integrators:Firms assembling subsystems from discrete components for end-equipment manufacturers.
- Research Institutions:Universities and national laboratories developing next-generation signal processing algorithms.
- Technology Providers:Companies licensing intellectual property and reference designs.
OEMs concentrate procurement volume while system integrators maintain the broadest vendor diversification.
Functionality:
Technical complexity gradients separate functionality tiers, with data processing demanding highest compute density and power management emphasizing analog precision.
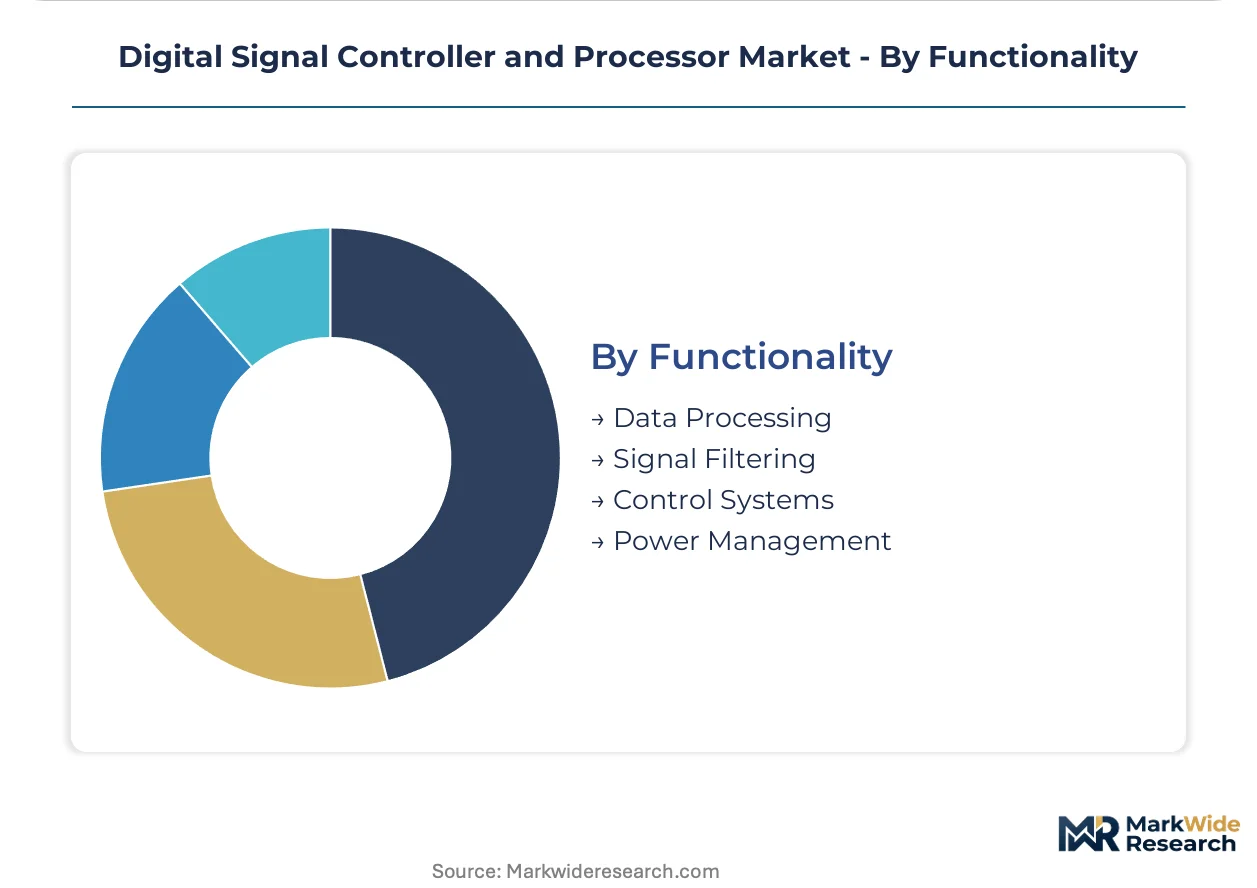
- Data Processing:Core mathematical operations on digital signal streams including FFTs, convolution, and correlation algorithms. This functionality maintains the largest revenue share across telecommunications and industrial endpoints. Deterministic edge computing architectures are embedding inference engines directly within processing pipelines.
- Signal Filtering:Hardware-accelerated digital filter implementations for noise reduction and channel separation. 5G baseband and audio processing endpoints are pulling filtering capabilities into heterogeneous chiplet architectures. Chiplets with dedicated neural processing units are displacing discrete DSP-plus-FPGA combinations.
- Control Systems:Real-time closed-loop feedback for motor drives and robotics.
- Power Management:Voltage regulation and energy efficiency optimization circuits.
Data processing anchors the revenue base while signal filtering climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's semiconductor logistics corridor, while the Texas Triangle's interstate highway network underwrites Austin's analog-digital fabrication cluster. These infrastructure assets concentrate mixed-signal controller procurement and qualification pipelines across automotive and telecommunications supply chains.
United States
Telecommunications capital expenditure cycles and 5G baseband deployment drive demand for hardware-accelerated DSP architectures. FCC equipment authorization rules shape product certification timelines for US-bound equipment. Austin's 300-millimeter analog-digital integration facilities sustain cost leadership in mixed-signal controllers for power electronics and motor-drive applications.
Germany
Electric powertrain inverters and battery management systems from Munich and Stuttgart OEMs pull ASIL-certified signal processing into automotive-grade qualification pipelines. EU Green Deal efficiency mandates and F-Gas Regulation compel higher-efficiency mixed-signal controller adoption for inverter applications. The Baden-Württemberg semiconductor corridor concentrates NXP and Texas Instruments socket competition for traction inverter modules.
South Korea
Massive MIMO antenna arrays and software-defined radio infrastructure in metropolitan deployments accelerate high-throughput DSP architectures. Samsung and SK Hynix foundry investments diversify digital signal processor supply beyond traditional strongholds. The Pyeongtaek semiconductor complex anchors analog-digital co-fabrication capacity for telecommunications and automotive Tier-1 suppliers.
China
Domestic battery gigafactories and industrial automation drive demand for real-time closed-loop control systems. GB standards for electromagnetic compatibility tighten conducted and radiated emission limits, compelling redesign of switching regulator circuits. Shenzhen and Suzhou manufacturers accelerate compliance investments ahead of enforcement deadlines for power electronics shipments.
India
Production-linked incentives for electronics manufacturing and designated semiconductor clusters attract greenfield fabrication investment for automotive signal processors. BIS standards and PLI scheme requirements shape local content and certification pathways. Gujarat and Tamil Nadu semiconductor parks emerge as assembly and test locations for mixed-signal controllers serving domestic OEM procurement.
Digital Signal Controller and Processor Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with deterministic processing IP. The vendor base concentrates around analog-digital integration leaders and automotive-grade certification holders. Three archetypes dominate: scale-driven mixed-signal fabricators, ASIL-certified automotive specialists, and telecommunications-focused high-throughput architects. Competitive moves center on foundry capacity expansion for 300-millimeter analog-digital co-fabrication and direct OEM contracting to bypass traditional distribution margins.
Within the scale-driven integration tier, Texas Instruments anchors cost leadership through analog-digital fabrication scale. Analog Devices occupies a position exemplifying high-performance DSP architectures for radar and software-defined radio applications. NXP Semiconductors represents the ASIL-certified automotive specialist archetype with deterministic signal processing portfolios for electric powertrain and battery management systems.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies |
| Qualcomm |
| Broadcom |
| Microchip Technology |
| Renesas Electronics |
| Others |
Value Chain & Pricing Dynamics
Austin's 300-millimeter analog-digital fabrication cluster concentrates mixed-signal controller capacity, translating into asymmetric pricing power for automotive-grade ASIL-certified devices. German OEM procurement from Munich and Stuttgart semiconductor corridors faces premium tiering against cost-optimized industrial controllers sourced through Pyeongtaek foundry networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations. Premium tiering attaches to ASIL-D certification and direct OEM contracting, while economy tiers serve industrial motor-drive applications through distribution channels. Cost compression in standard-tier mixed-signal controllers is intensifying because Samsung and SK Hynix foundry expansions diversify supply. Automotive OEMs exhibit lowest price sensitivity due to functional safety mandates; consumer audio processing endpoints show highest elasticity.
Supply Chain Analysis
TSMC, Samsung Foundry, and Texas Instruments captive fabrication hold contract-manufacturing concentration for advanced mixed-signal integration. Raw material dependencies include 300-millimeter silicon wafers, lead-free solder alloys constrained by REACH, and specialized ceramic substrates for high-temperature automotive modules. Single-source vulnerability clusters around Austin and Pyeongtaek analog-digital co-fabrication facilities. Distribution runs through Arrow Electronics and Avnet for industrial segments; automotive Tier-1 suppliers increasingly bypass these channels through direct vendor-managed inventory agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. ISO 26262 certification cycles create 18-24 month switching costs that freeze out unqualified competitors from automotive sockets.
For Market Incumbents: Pre-empt silicon carbide controller substitution by embedding gate-drive logic into heterogeneous chiplet architectures before wide-bandgap power devices displace discrete DSP-plus-MCU combinations above 100 kilohertz. Accelerate backward integration into 300-millimeter analog-digital fabrication capacity in Pyeongtaek or Austin to defend cost leadership against emerging foundry competition. ASIL-D certification investment remains the priority defensive lever. For New Entrants and Emerging Players: Build out radar sensor fusion architectures for advanced driver-assistance systems where machine-learning accelerator integration creates whitespace beyond legacy DSP-plus-FPGA incumbents. India's PLI scheme for Gujarat and Tamil Nadu semiconductor clusters offers the most penetrable geographic entry point with production-linked incentives for automotive signal processor assembly. Target direct OEM contracting relationships with South Korean battery gigafactory suppliers as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ASIL-certified automotive specialists with deterministic processing IP and established foundry relationships over telecommunications-focused high-throughput architects facing 5G capital expenditure cyclicality. Long-term viability over the next decade rests on firmware licensing models that capture subscription-based feature activation revenue. Watch for inflection through over-the-air update penetration rates in German premium electric vehicle programs as the signal indicating margin migration from hardware to software.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Opens automotive socket access across Munich and Stuttgart OEM corridors. |
| 300-Millimeter Fab Expansion | Secures analog-digital co-fabrication capacity against Pyeongtaek concentration risk. |
| Direct OEM Contracting | Bypasses Arrow and Avnet distribution margins in automotive procurement. |
| Heterogeneous Chiplet Integration | Collapses board area for radar sensor fusion against discrete FPGA competition. |
| Firmware Licensing Model Shift | Captures subscription revenue from over-the-air motor control updates. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with semiconductor vendor product managers, automotive Tier-1 supplier procurement directors, and foundry capacity planners; and secondary validation through SEC 10-K filings, customs trade data for mixed-signal controller shipments, IHS Markit vehicle production databases, and FCC equipment authorization records. Bottom-up triangulation against top-down market sizing cross-checked segment-level estimates.
Forecast inputs considered product type segmentation across mixed-signal controllers, digital processors, and DSPs; application tiering through automotive systems, telecommunications infrastructure, and industrial automation; and functionality splits between data processing and signal filtering. CAGRs were derived from installed base erosion rates and replacement cycle compression across the projection horizon. Industry-specific inputs included ASIL certification pipeline visibility and 5G baseband deployment schedules from South Korean and US metropolitan carriers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers ahead of GB standards enforcement deadlines would shift outcomes. Quarterly review of foundry utilization rates at Samsung Pyeongtaek and Texas Instruments Austin facilities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
5G Processor Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Poe Chipsets Market