
 Global Neuromorphic Computing Market | 2026-2036
Global Neuromorphic Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuromorphic Computing Market Foresight
Neuromorphic computing is decoupling into two distinct tiers: high-performance defense-grade silicon commanding premium engineering resources, and commodity edge inference chips priced for mass IoT deployment. Intel Corporation leverages its foundry scale to dominate the capital-intensive hardware layer, while BrainChip Holdings Ltd. differentiates through event-based processor architectures optimized for ultra-low power budgets. SynSense competes in the European research corridor with mixed-signal designs that anchor its position in academic and industrial partnerships.
Neuromorphic computing refers to computational architectures that emulate biological neural structures through spiking neural networks, memristive crossbar arrays, and asynchronous event-driven processing, typically operating below one milliwatt per synaptic operation for edge inference tasks. Its primary commercial purpose is to execute pattern recognition, sensory processing, and adaptive learning in power-constrained environments where conventional von Neumann architectures face thermal and latency barriers. Hardware currently captures the dominant share of value creation, though software frameworks for spiking neural network training are expanding fastest as tooling gaps constrain developer adoption. Analog technology leads in energy efficiency metrics, while hybrid digital-analog approaches are maturing for automotive qualification timelines where fault tolerance requirements are stringent.
The FDA and FAA in the United States impose distinct validation frameworks on neuromorphic systems deployed in medical diagnostics and autonomous flight systems, respectively, forcing vendors to maintain parallel certification tracks that inflate development overhead. The EU AI Act and REACH compliance through ECHA further fragment market access by mandating explainability and material traceability for chips entering European healthcare and industrial robotics supply chains. Stakeholders must monitor how NMPA in China and METI in Japan evolve their semiconductor procurement standards, as divergent national requirements for AI chip security and supply chain provenance will determine which architectural approaches achieve cross-border scale.
Market Dynamics
The EU AI Act's risk-based classification system is compressing development timelines for certifiable neuromorphic architectures, forcing vendors to engineer explainability into ultra-low-power silicon from the design phase rather than retrofitting compliance later.
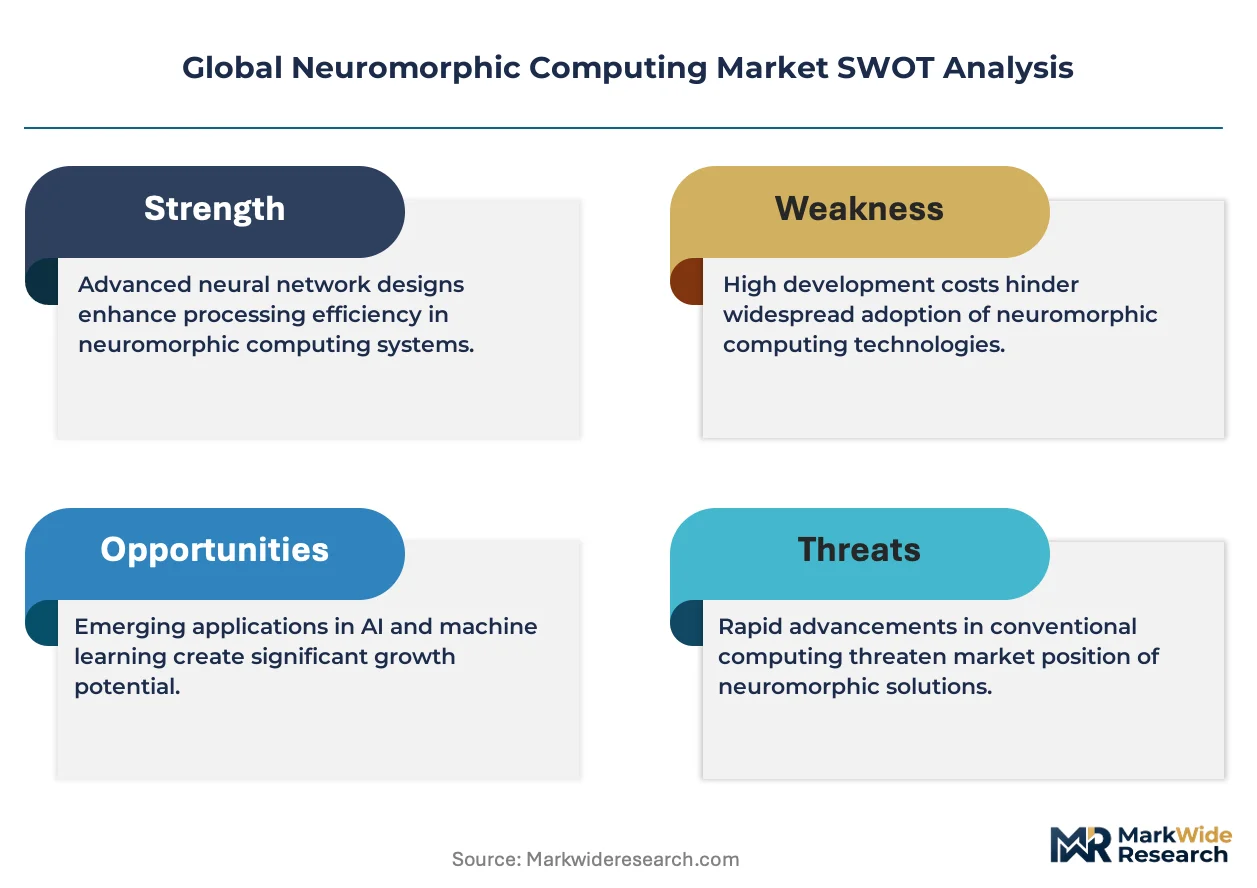
Growth Catalysts
- Defense procurement acceleration:Unmanned aerial systems and autonomous maritime platforms in the United States are absorbing event-based processors for real-time threat detection at the edge, with Pentagon R&D contracts expanding foundry capacity for radiation-hardened designs.
- REACH compliance through ECHA:Material traceability mandates for European industrial robotics supply chains are favoring neuromorphic chips with documented rare-earth sourcing, creating preference for EU-based mixed-signal foundries.
- Spiking neural network tooling:Academic frameworks migrating to production-grade compilers are collapsing the skill barrier for embedded engineers, accelerating developer adoption beyond neuroscience specialists.
Market Restraints
- Memristor foundry concentration:Crossbar array fabrication for analog synaptic elements depends on a handful of specialty CMOS facilities in Taiwan and South Korea, exposing supply chains to geopolitical disruption.
- FDA validation overhead:Neuromorphic diagnostic systems for continuous patient monitoring face parallel clinical trial tracks for algorithmic explainability and hardware reliability, inflating time-to-revenue by 18-36 months versus conventional ASICs.
- Von Neumann substitution:Quantized transformer accelerators on mature nodes are narrowing the energy-efficiency gap for static inference workloads, limiting neuromorphic penetration in non-adaptive applications.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic chip fabrication incentives are attracting neuromorphic IP licensors to establish joint development centers for agricultural drone and smart grid applications.
- Automotive sensor fusion:Event cameras paired with spiking processors for sub-millisecond object tracking represent uncontracted demand from German Tier-1 suppliers seeking ASIL-D qualified perception stacks.
- Convergence with memristive storage:In-memory computing architectures combining ReRAM arrays with neuromorphic controllers are opening architectural white space for unified inference-and-retrieval systems in financial surveillance.
Industry Challenges
- Spiking neural network training expertise:The shortage of engineers proficient in surrogate gradient methods and temporal coding schemes is constraining productization timelines for venture-backed startups.
- FAA certification parallelism:Autonomous flight systems deploying neuromorphic navigation must satisfy both software airworthiness standards and novel hardware reliability criteria, creating documentation burdens without precedent.
- Legacy system integration:Event-driven processors require asynchronous interface redesigns for existing synchronous sensor buses, complicating retrofit deployments in industrial automation brownfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuromorphic Computing Market |
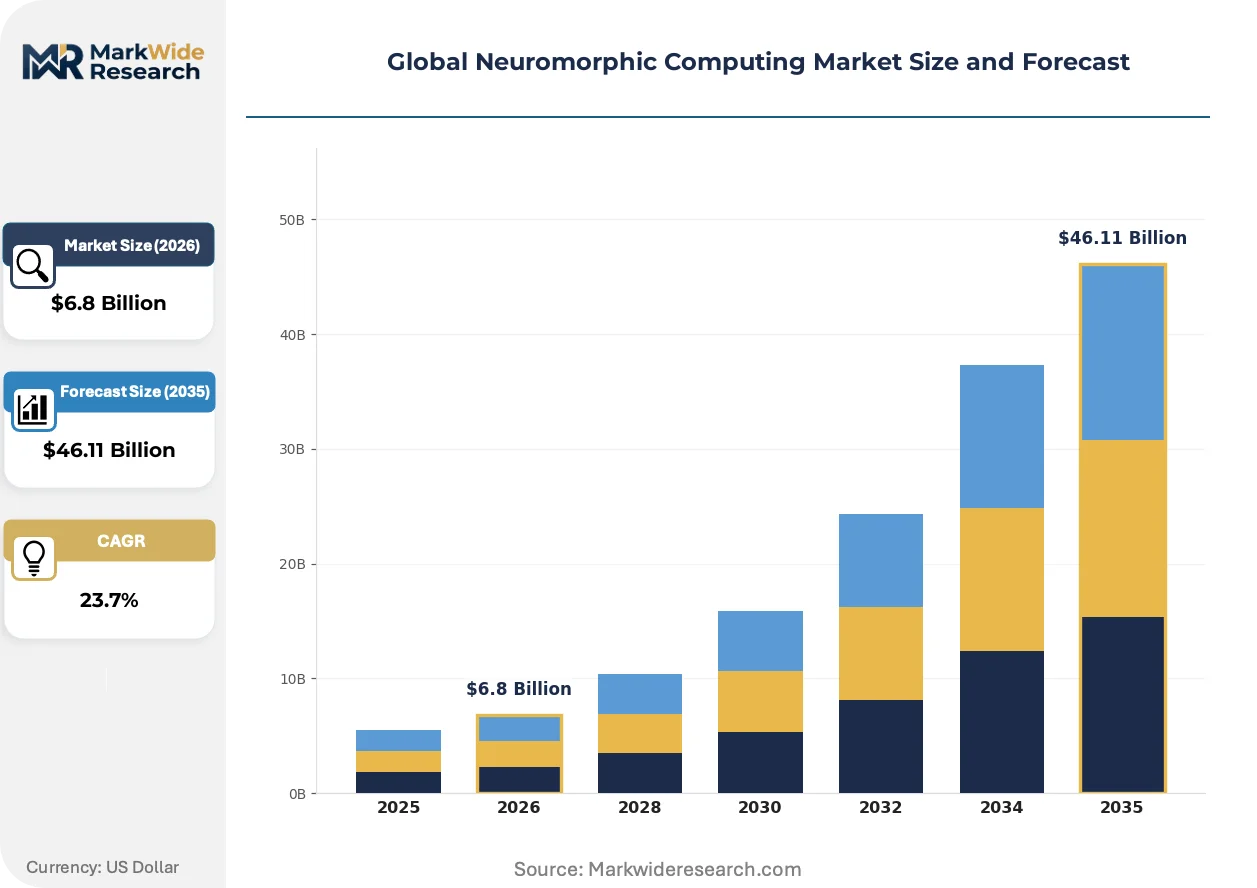
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $46.11 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Frameworks, Tools Technology: Analog, Digital, Hybrid, Biologically Inspired Application: Robotics, Image Recognition, Natural Language Processing, Autonomous Vehicles End User: Aerospace, Healthcare, Finance, Telecommunications |
| Companies Covered | Intel Corporation, IBM Corporation, Qualcomm Technologies, Inc., Samsung Electronics Co., Ltd., BrainChip Holdings Ltd., SynSense, Hewlett Packard Enterprise Development LP, General Vision Inc., GrAI Matter Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuromorphic Computing Market Shifts & Advancements
Neuromorphic hardware is bifurcating into defense-grade radiation-tolerant designs and mass-market edge inference silicon, with process node choices and packaging strategies diverging sharply between these tiers.
Memristive crossbar arrays are consolidating position as the dominant analog synaptic technology for sub-milliwatt pattern recognition. Aerospace contractors in the United States are qualifying TaOx and HfO2-based devices for satellite-borne adaptive learning, compressing the competitive window for competing resistive RAM approaches that lack flight heritage.
REACH compliance through ECHA is mandating full material disclosure for chips entering European healthcare and robotics supply chains. Vendors are responding by engineering out conflict minerals and establishing EU-based packaging facilities, with medical diagnostic applications facing the most stringent documentation requirements.
Buyer concentration among defense primes and automotive Tier-1s is collapsing the traditional distribution channel for discrete neuromorphic components. Direct foundry relationships and co-development agreements are displacing standard semiconductor distribution in Germany and Japan, where procurement teams prioritize supply chain provenance over catalog availability.
Global Neuromorphic Computing Market Segmentation
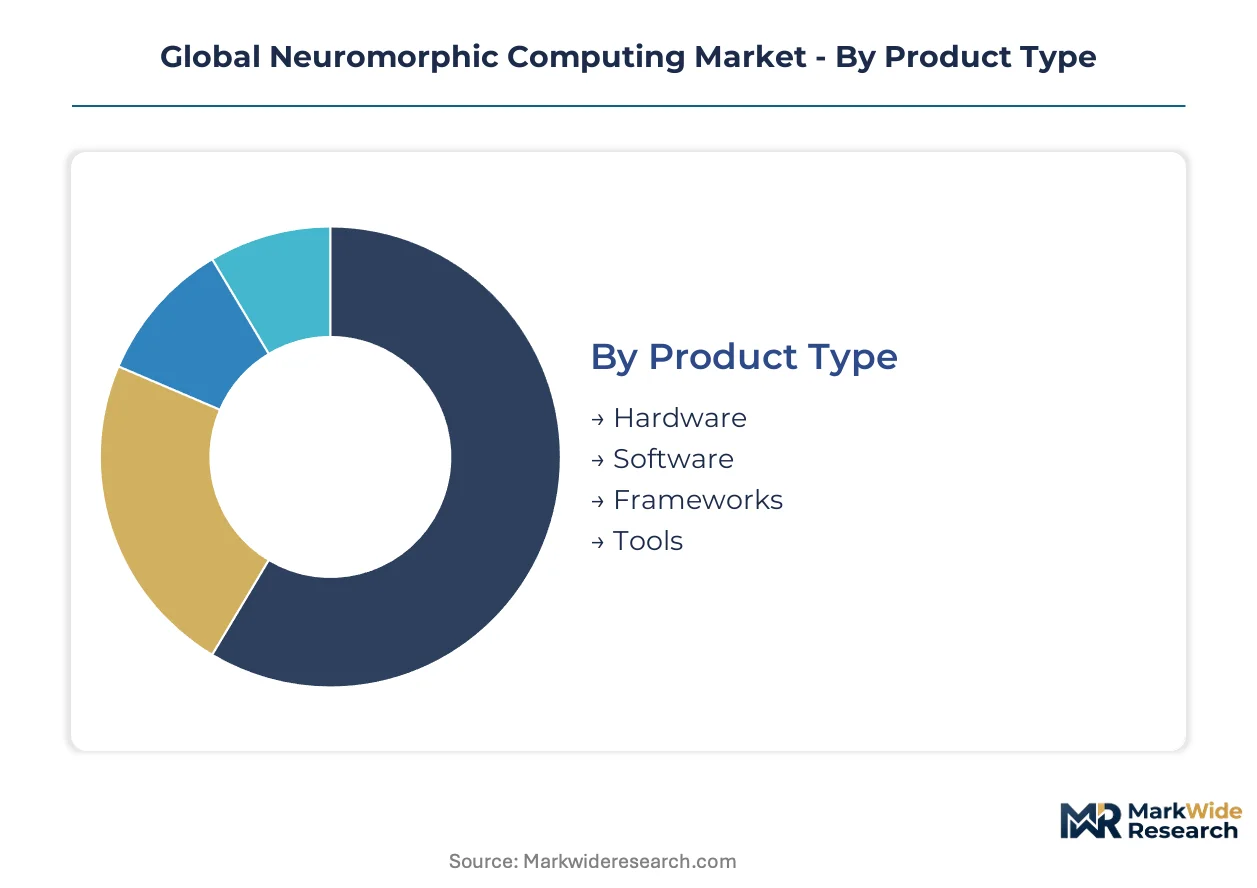
Neuromorphic computing markets fragment sharply across product layers and deployment contexts. Procurement patterns diverge between defense contractors seeking radiation-hardened silicon and industrial integrators prioritizing software tooling for rapid algorithm deployment.
Product Type:
Hardware buyers prioritize foundry relationships and thermal specifications, while software purchasers evaluate compiler maturity and SNN training ecosystem breadth.
- Hardware:Spiking neural network processors, memristive crossbar arrays, and event-driven sensor interfaces fabricated at specialty CMOS nodes. Pentagon R&D contracts for unmanned aerial systems are absorbing the highest-margin radiation-tolerant designs from United States foundries.
- Software:Production-grade compilers for surrogate gradient training and temporal coding optimization. Academic frameworks migrating from Python prototypes to embedded C++ runtimes are collapsing the skill barrier for conventional embedded engineers in Boston and Silicon Valley research clusters.
- Frameworks:Open-source libraries for SNN simulation and neuromorphic hardware abstraction layers.
- Tools:Debuggers, profilers, and visualization utilities for spiking network behavior analysis.
Hardware leads volumes today; software is gaining share fastest as tooling gaps constrain developer adoption across industrial segments.
Technology:
Energy efficiency thresholds and fault tolerance requirements separate commercial viability from laboratory curiosity across these architectural approaches.
- Analog:Memristive crossbar arrays executing vector-matrix multiplication in the analog domain below one milliwatt per synaptic operation. Sub-milliwatt pattern recognition demand from satellite-borne adaptive learning systems in United States aerospace procurement is consolidating TaOx and HfO2 device qualification.
- Digital:Synchronous CMOS implementations of spiking neurons with deterministic timing behavior. Automotive Tier-1 suppliers in Germany are prioritizing digital approaches for ASIL-D qualified perception stacks where fault tolerance requirements are stringent.
- Hybrid:Mixed-signal architectures combining analog synaptic arrays with digital control logic.
- Biologically Inspired:Architectures emulating specific neural structures like olfactory processing or retina-inspired event encoding.
Analog dominates energy efficiency metrics; hybrid approaches are climbing the fastest as automotive qualification timelines demand fault tolerance without sacrificing power budgets.
Application:
Latency requirements and sensory modality determine whether neuromorphic architectures outperform quantized transformer accelerators on conventional silicon.
- Robotics:Tactile sensing integration and adaptive motor control through spiking cerebellar models. Industrial automation brownfield sites in Germany and Japan are driving demand for asynchronous interface redesigns compatible with existing synchronous sensor buses.
- Image Recognition:Event camera fusion for sub-millisecond object tracking in dynamic scenes. German Tier-1 automotive suppliers represent uncontracted demand for ASIL-D qualified perception stacks pairing event cameras with spiking processors.
- Natural Language Processing:Temporal pattern recognition in audio streams and low-power keyword spotting.
- Autonomous Vehicles:Multi-sensor fusion and predictive path planning under severe thermal constraints.
Image recognition leads volumes today; robotics is expanding most quickly as event-driven tactile sensing penetrates industrial automation retrofit deployments.
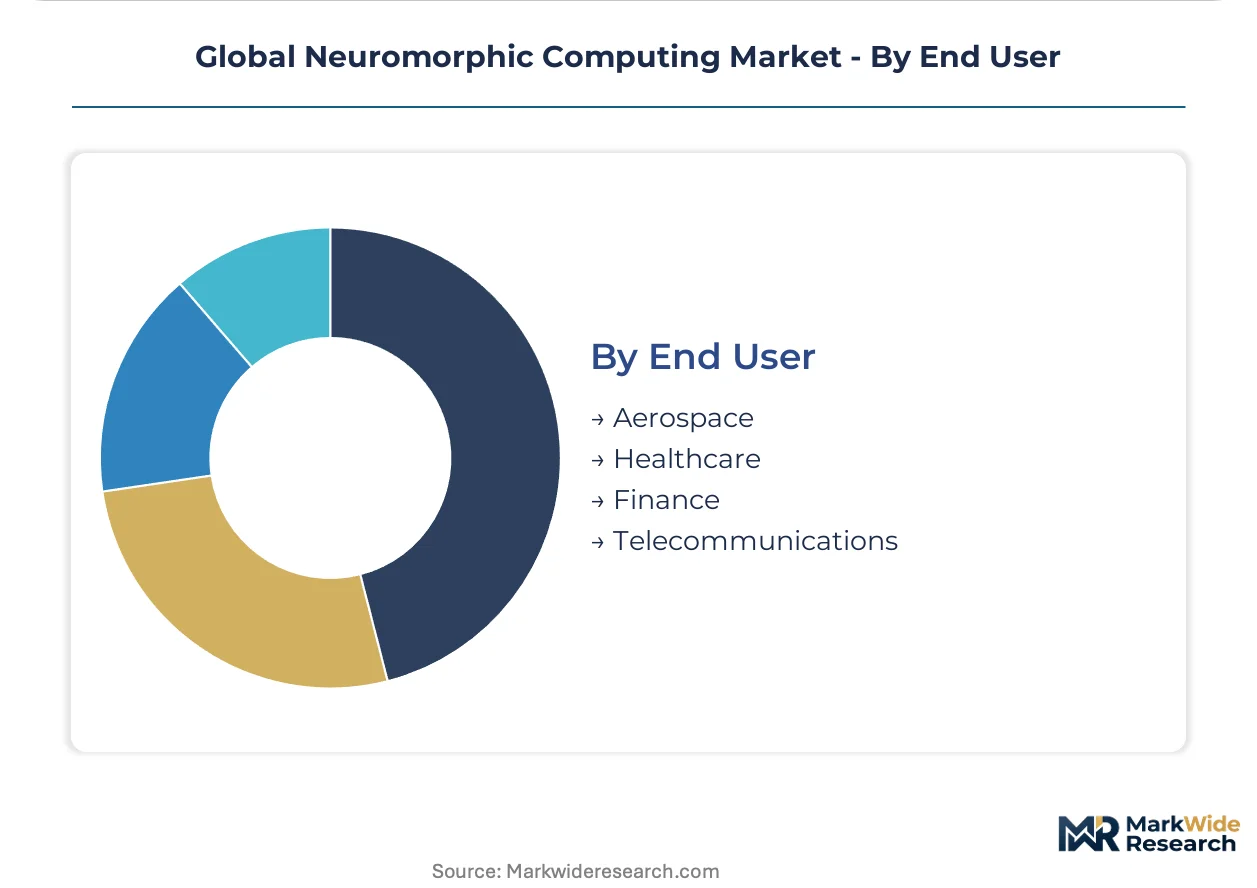
End User:
Regulatory validation frameworks and procurement security requirements fragment demand across these verticals.
- Aerospace:Satellite-borne adaptive learning and unmanned platform edge intelligence. FAA certification parallelism for autonomous flight systems in the United States is forcing vendors to satisfy both software airworthiness standards and novel hardware reliability criteria without precedent.
- Healthcare:Continuous patient monitoring and diagnostic pattern recognition. FDA validation overhead for neuromorphic diagnostic systems is inflating time-to-revenue by 18-36 months versus conventional ASICs through parallel clinical trial tracks for algorithmic explainability.
- Finance:Real-time surveillance and anomaly detection in trading infrastructure.
- Telecommunications:Baseband processing and spectrum sensing for cognitive radio applications.
Aerospace leads volumes today; healthcare is gaining share fastest as EU AI Act risk classifications push developers toward certifiable, low-power architectures from the design phase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neuromorphic engineering talent clusters in Boston, Munich, and Tsukuba anchor regional development capacity. National procurement programs and divergent regulatory frameworks fragment market access across jurisdictions. Each geography cultivates distinct architectural specializations tied to local industrial demand.
United States
Pentagon R&D contracts for unmanned aerial systems and satellite-borne adaptive learning absorb the highest-margin radiation-tolerant designs. FAA certification parallelism forces vendors to satisfy both software airworthiness standards and novel hardware reliability criteria for autonomous flight systems. The Boston and Silicon Valley research clusters concentrate spiking neural network compiler development migrating from academic frameworks to production-grade tooling.
Germany
Automotive Tier-1 suppliers represent uncontracted demand for ASIL-D qualified perception stacks pairing event cameras with spiking processors. REACH compliance through ECHA mandates full material disclosure for chips entering industrial robotics supply chains, favoring mixed-signal foundries with documented rare-earth sourcing. The Baden-Württemberg and Bavaria automotive corridors anchor qualification timelines for hybrid digital-analog fault-tolerant architectures.
China
NMPA evolving procurement standards for AI chip security and supply chain provenance determine which architectural approaches achieve cross-border scale. Domestic agricultural drone and smart grid applications attract neuromorphic IP licensors to joint development centers under semiconductor fabrication incentives. The Yangtze River Delta and Pearl River Delta clusters concentrate memristive crossbar array packaging for sub-milliwatt pattern recognition demand.
Japan
METI semiconductor procurement standards shape architectural requirements for industrial automation retrofit deployments requiring asynchronous interface redesigns. Event-driven tactile sensing penetrates brownfield sites in the Chubu and Kansai manufacturing belts. The Tsukuba research corridor anchors mixed-signal academic partnerships bridging neuroscience and embedded engineering expertise.
United Kingdom
CSRD disclosure requirements and EU AI Act risk classifications push healthcare developers toward certifiable low-power architectures from the design phase. The Cambridge and London research clusters concentrate spiking neural network training expertise for financial surveillance and anomaly detection applications. Academic frameworks from these hubs migrate toward production compilers collapsing skill barriers for conventional embedded engineers.
Global Neuromorphic Computing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent process node strategies. Foundry-scale incumbents leverage captive fabrication capacity while neuromorphic specialists rely on specialty CMOS partnerships. The market structures around three archetypes: integrated device manufacturers with radiation-hardened foundry lines, fabless event-based processor architects, and mixed-signal research-to-product bridges. Dominant competitive moves include direct foundry relationship cultivation displacing standard distribution and co-development agreements with defense primes and automotive Tier-1s securing supply chain provenance preference.
Within the integrated manufacturer tier, Intel Corporation occupies a position exemplifying foundry-scale leverage over capital-intensive hardware layers. Among fabless specialists, BrainChip Holdings Ltd. and SynSense represent archetypes of event-based and mixed-signal architectural differentiation respectively. These three companies anchor the competitive spectrum from commodity edge inference silicon to defense-grade radiation-tolerant designs, with each sitting within distinct procurement channels shaped by certification requirements and power budget constraints.
| Leading Market Players |
|---|
| Intel Corporation |
| IBM Corporation |
| Qualcomm Technologies, Inc. |
| Samsung Electronics Co., Ltd. |
| BrainChip Holdings Ltd. |
| SynSense |
| Hewlett Packard Enterprise Development LP |
| General Vision Inc. |
| GrAI Matter Labs |
| Others |
Supply & Pricing Matrix
REACH compliance through ECHA gates qualified supply for European healthcare and robotics procurement, reserving premium-tier pricing access to vendors with documented rare-earth sourcing and EU-based packaging facilities. Defense primes absorb radiation-hardened designs at cost-plus margins while mass-market edge inference chips face commoditization pressure from quantized transformer alternatives.
Pricing Analysis
Hardware-software bundling separates defense-grade neuromorphic systems from unbundled commodity edge inference silicon. Pricing stratifies across radiation-tolerant, automotive-qualified, and consumer-tier performance levels, with FDA and FAA certification tiers commanding substantial premiums. Cost compression in consumer-grade event-based processors is intensifying because foundry-scale incumbents leverage captive fabrication capacity. Industrial automation integrators exhibit highest price sensitivity; Pentagon R&D contractors show least sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Memristive crossbar array fabrication rests on specialty CMOS facilities concentrated in Taiwan and South Korea, with packaging operations increasingly migrating to EU-based facilities for REACH compliance. Critical inputs include TaOx and HfO2 resistive RAM materials, photoresist chemicals, and rare-earth elements for radiation-hardened substrates. Single-source vulnerability in memristor foundry concentration exposes supply chains to geopolitical disruption. Distribution runs through direct foundry relationships and co-development agreements, displacing standard semiconductor distribution for defense primes and automotive Tier-1s.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in neuromorphic computing hinges on the shift from retrofit compliance engineering to certifiable-by-design architectures that capture premium pricing in regulated verticals.
For Market Incumbents: Cement foundry-scale leverage through captive radiation-hardened fabrication lines in the United States, insulating against memristor foundry concentration risk. Deepen backward integration into rare-earth sourcing documentation to satisfy ECHA material traceability mandates. Prioritize compiler ecosystem investments that collapse skill barriers for conventional embedded engineers, defending against open-source framework commoditization. For New Entrants and Emerging Players: Cloud-based SNN training platforms offer the lowest-friction route to developer adoption without foundry capital requirements. Agricultural drone applications in India and smart grid edge intelligence represent penetrable white-space segments with less entrenched incumbent relationships. Target academic partnership channels in Boston and Tsukuba research clusters for technology validation before commercial procurement engagement. For Investors and Strategic Acquirers: Roll-up economics work for mixed-signal neuromorphic IP licensors because automotive qualification timelines demand fault-tolerant architectures that bridge research-to-product gaps. Over a multi-year horizon, consolidation around event-based processor architectures and memristive controller integration will separate viable platforms from stranded tooling investments. Watch NMPA procurement standard evolution in China as the critical inflection signal for cross-border architectural scale.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened Foundry Investment | Captures Pentagon R&D contract flows for satellite-borne adaptive learning systems. |
| SNN Compiler Ecosystem Expansion | Collapses skill barriers for embedded engineers beyond neuroscience specialists. |
| EU-Based Packaging Facility Establishment | Satisfies ECHA material traceability for healthcare and robotics supply chains. |
| Event Camera-Spiking Processor Integration | Addresses uncontracted demand from German Tier-1 automotive suppliers. |
| Academic Partnership Migration | Bridges neuroscience expertise and embedded engineering in Boston and Tsukuba clusters. |
Research Methodology
Direct dialogue with neuromorphic hardware architects, embedded systems procurement leads at defense primes, FDA regulatory affairs specialists, and automotive Tier-1 platform engineers grounded qualitative findings. Secondary validation drew from Pentagon R&D contract disclosures, ECHA REACH registration databases, FAA airworthiness certification filings, and SEC 10-K semiconductor segment reports. Bottom-up shipment modeling and top-down addressable market sizing were triangulated against foundry capacity announcements and academic framework migration timelines.
Bottom-up volume estimates aggregated across hardware, software, and services segments, with technology splits between analog, digital, hybrid, and biologically inspired architectures. Application segmentation modeled robotics, image recognition, natural language processing, and autonomous vehicle deployment patterns. End-user splits captured aerospace, healthcare, finance, and telecommunications procurement frameworks. CAGRs were derived from regression analysis against semiconductor capital expenditure cycles and regulatory compliance timeline compression.
The model assumes a particular technology adoption path; alternative pathways for memristive crossbar yield improvement or quantized transformer efficiency gains would alter the outlook. Forecasts reflect assumptions about FAA certification parallelism resolution and EU AI Act implementation consistency across member states. A small set of triggers—NMPA procurement standard finalization, India PLI scheme disbursement velocity, and memristor foundry geographic diversification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market