
 Global Analog Integrated Circuit (IC) Market | 2026-2036
Global Analog Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Analog Integrated Circuit (IC) Market Foresight
The EU Green Deal is pivoting automotive OEM procurement toward energy-efficient power management chips. Texas Instruments leverages its 300-millimeter analog wafer fabrication in Richardson to sustain cost leadership in voltage regulators. Analog Devices Inc. anchors its position through high-precision data converters for industrial automation and aerospace signal chains.
Analog integrated circuits process continuous electrical signals through transistor arrays fabricated on silicon substrates, with operating parameters spanning microvolt input offsets to megahertz bandwidth thresholds. These devices execute amplification, regulation, conversion, and sensing functions that bridge physical phenomena with digital processing systems. Operational amplifiers and voltage regulators command the largest revenue pools within product type segments, while data converters capture the fastest expansion as automotive lidar and medical imaging systems multiply channel counts. CMOS technology dominates volume production, though BiCMOS variants command premium positioning where mixed-signal precision justifies higher process complexity.
REACH chemical restrictions and RoHS substance limits constrain packaging material choices and solder compositions across European supply chains, while EPA energy efficiency standards under the IRA framework shape power supply specifications for US-bound industrial equipment. FDA electromagnetic compatibility requirements for medical devices further tighten noise and isolation parameters in precision analog designs. Stakeholders must monitor how dual carbon goals in China and the EU AI Act's edge-computing mandates redirect R&D budgets toward low-power sensor interfaces and adaptive power architectures.
Market Dynamics
Automotive electrification is compressing design cycles for precision voltage regulators as OEMs cascade tier-one requirements through semiconductor supply chains. Tier-one suppliers now demand simultaneous engineering support across multiple voltage domains.
Growth Catalysts
- EU Green Deal procurement mandates:European automotive OEMs now embed energy-efficiency specifications directly into supplier qualification scorecards, accelerating demand for low-quiescent-current regulators.
- Industrial automation sensor densification:Factory floors in Germany and China are multiplying analog channel counts per machine, pulling high-precision data converters into motion-control and predictive maintenance architectures.
- 300-millimeter wafer migration:Richardson and Dresden fabrication clusters are expanding die-per-wafer economics for standard analog products, compressing cost curves for voltage references and operational amplifiers.
Market Restraints
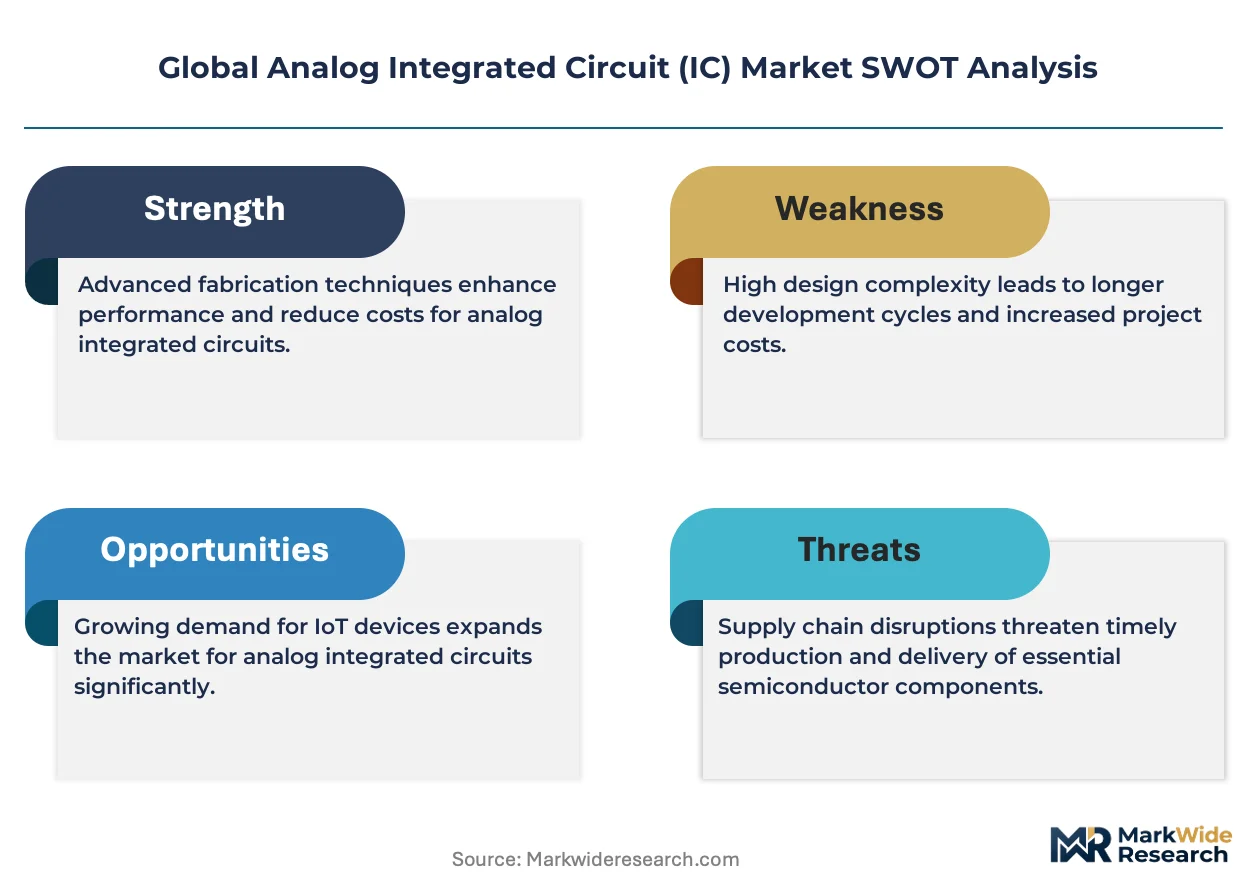
- Silicon substrate cost volatility:Polished wafer supply concentrates among Japanese and German suppliers, exposing margin structures to spot-price swings in 200mm and 300mm diameters.
- BiCMOS process complexity premiums:Mixed-signal designs requiring bipolar-CMOS integration face 40-60% die cost penalties versus pure CMOS, constraining adoption in cost-sensitive consumer segments.
- REACH substance restrictions:ECHA chemical limitations on lead-frame plating materials and mold compounds force qualification cycles that extend time-to-revenue for new package families.
Strategic Opportunities
- India domestic fabrication incentives:PLI scheme subsidies for semiconductor manufacturing are attracting analog foundry investments in Gujarat and Karnataka, creating captive supply options for industrial and automotive grade devices.
- Medical imaging channel expansion:MRI and CT manufacturers are unbundling analog front-end modules from system integrators, opening direct component procurement relationships with converter and amplifier specialists.
- Edge AI sensor fusion:Convergence of analog sensor interfaces with digital inference engines is creating demand for adaptive power architectures that dynamically scale precision versus consumption.
Industry Challenges
- Mixed-signal design talent scarcity:Experienced analog layout engineers capable of managing noise isolation in dense digital environments command premium compensation, constraining R&D scaling.
- Automotive AEC-Q100 certification timelines:Extended qualification protocols for temperature-grade devices delay revenue recognition by 18-24 months from tape-out.
- Legacy system integration friction:Industrial equipment with 15-20 year service lives requires voltage-level translation and signal conditioning that complicates drop-in replacement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Analog Integrated Circuit (IC) Market |
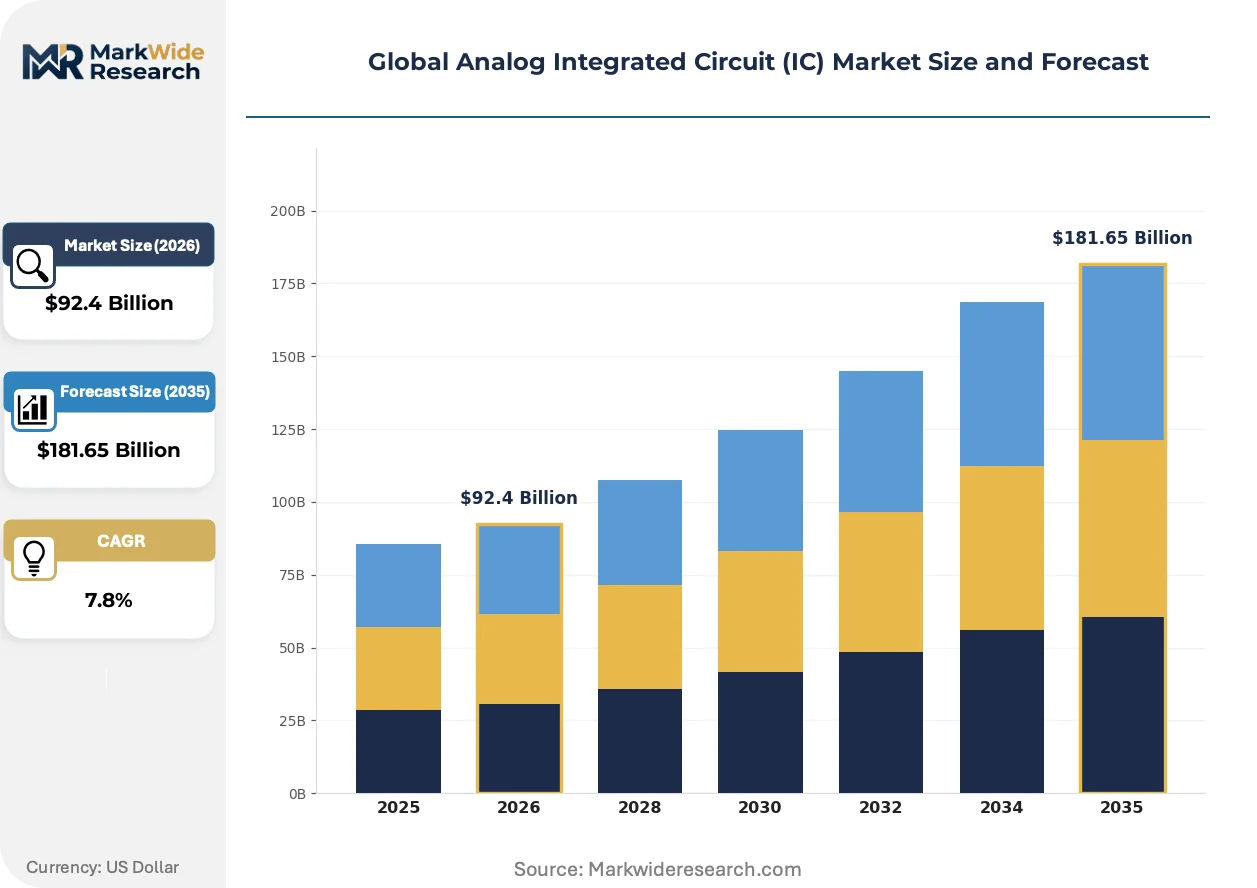
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $181.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Data Converters, Sensors, Interface ICs Technology: Bipolar, CMOS, BiCMOS, MOSFET, GaAs Application: Consumer Electronics, Telecommunication Equipment, Industrial Automation, Aerospace & Defense, Renewable Energy End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, System Integrators |
| Companies Covered | Texas Instruments, Analog Devices Inc., Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, Microchip Technology, ON Semiconductor, Renesas Electronics Corporation, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Analog Integrated Circuit (IC) Market Shifts & Advancements
Silicon carbide power stages are forcing analog control loops to operate at higher switching frequencies and tighter tolerances. This pressure is reshaping how feedback networks and gate drivers co-evolve with wide-bandgap semiconductors.
Monolithic integration of gate drivers with protection logic is consolidating discrete component counts in motor-drive and power-supply subassemblies. Automotive traction inverters and server power supplies are adopting these compact solutions to shrink board area and reduce parasitic inductance. The technology is consolidating second-source strategies as proprietary IP blocks become embedded in application-specific standard products.
EPA emissions standards under the IRA framework are mandating efficiency thresholds for industrial motor systems that cascade into power-supply specifications. Variable-frequency drive manufacturers must now document standby power consumption and load-transient response. This regulatory pressure is concentrating procurement on vendors with validated reference designs that pre-certify subsystem compliance.
Direct procurement from semiconductor vendors is displacing traditional distribution for high-volume automotive and industrial accounts. Tier-one suppliers in Germany and China are establishing vendor-managed inventory programs that bypass regional distributors. This channel compression is most visible in voltage regulator and data converter categories where specification continuity outweighs local technical support.
Global Analog Integrated Circuit (IC) Market Segmentation
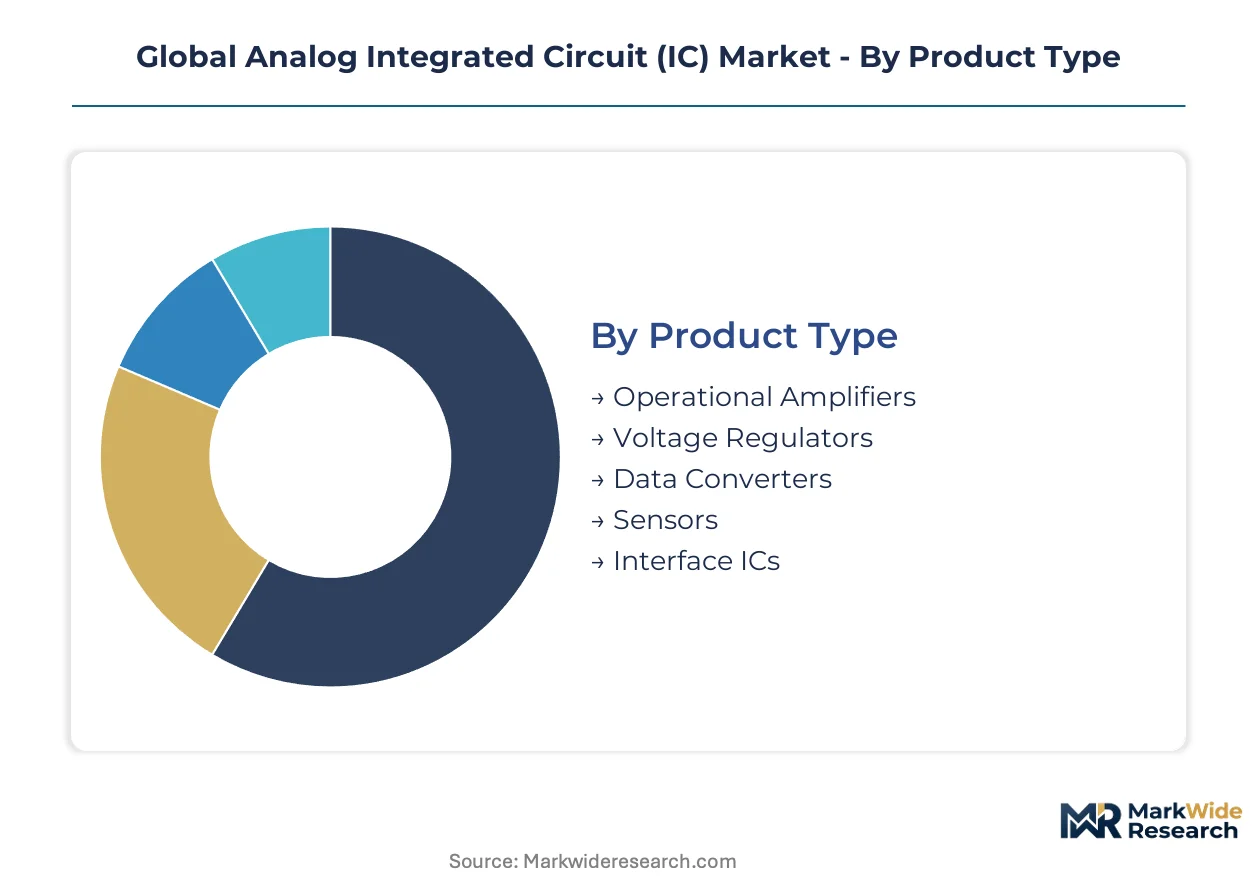
Analog IC segmentation reveals how fabrication economics and end-use specifications fragment procurement patterns. Voltage regulators and data converters command premium positioning where precision requirements justify process complexity premiums.
Product Type:
Supply concentration for precision analog devices clusters around voltage regulation and signal conversion functions, with fabrication scale determining cost positioning across each segment.
- Operational Amplifiers:These devices amplify differential input signals with microvolt offset precision across megahertz bandwidth ranges. German industrial automation OEMs and Chinese automotive tier-one suppliers drive procurement volumes for motion control and sensor conditioning applications.
- Voltage Regulators:Linear and switching architectures manage power delivery with tight load-transient response specifications. EU Green Deal efficiency mandates and EPA energy standards under the IRA framework concentrate demand in automotive electrification and industrial motor systems.
- Data Converters:ADC and DAC architectures bridge physical and digital domains. Expanding most quickly as automotive lidar and medical imaging multiply channel counts per system.
- Sensors:Signal conditioning interfaces for temperature, pressure, and position transducers.
- Interface ICs:Level translators and protocol bridges managing voltage domain mismatches in mixed-signal systems.
Today's leader: Voltage Regulators. Tomorrow's challenger: Data Converters.
Technology:
Process selection trades off precision against die cost, with bipolar-CMOS integration commanding premiums where mixed-signal performance justifies complexity.
- CMOS:Dominates volume production for standard analog functions with scalable geometry and mature yield curves. Richardson and Dresden fabrication clusters exploit 300-millimeter wafer economics for operational amplifiers and voltage references serving consumer and industrial accounts.
- BiCMOS:Integrates bipolar precision with CMOS density for high-performance data converters and precision references. Die cost penalties of 40-60% versus pure CMOS constrain adoption to aerospace, medical, and automotive signal chains where specification margins outweigh price sensitivity.
- Bipolar:Legacy process for high-voltage and high-current applications with established reliability records.
- MOSFET:Power-specific implementations for switching regulators and gate driver integration.
- GaAs:Niche radio-frequency and high-frequency signal processing with limited analog crossover.
CMOS captures current volume leadership. BiCMOS gains share fastest as automotive and medical specifications tighten.
Application:
End-use diversification spreads analog IC consumption across equipment types with diverging qualification timelines and specification stringency.
- Consumer Electronics:Smartphones, wearables, and home appliances drive high-volume, cost-optimized demand for standard voltage regulators and audio amplifiers. Chinese OEM procurement concentrates on CMOS-based solutions with compressed design cycles.
- Industrial Automation:Factory floors in Germany and China multiply analog channel counts per machine for motion control and predictive maintenance. REACH substance restrictions and RoHS compliance constrain packaging material choices across European supply chains.
- Telecommunication Equipment:Base stations and optical transport systems require precision timing and power management.
- Aerospace & Defense:Extended temperature ranges and radiation tolerance specifications mandate qualified process flows with 18-24 month certification timelines.
- Renewable Energy:Solar inverters and wind turbine controls demand robust power stage management.
Industrial Automation leads procurement value. Renewable Energy presents the steepest expansion trajectory as grid-scale installations multiply.
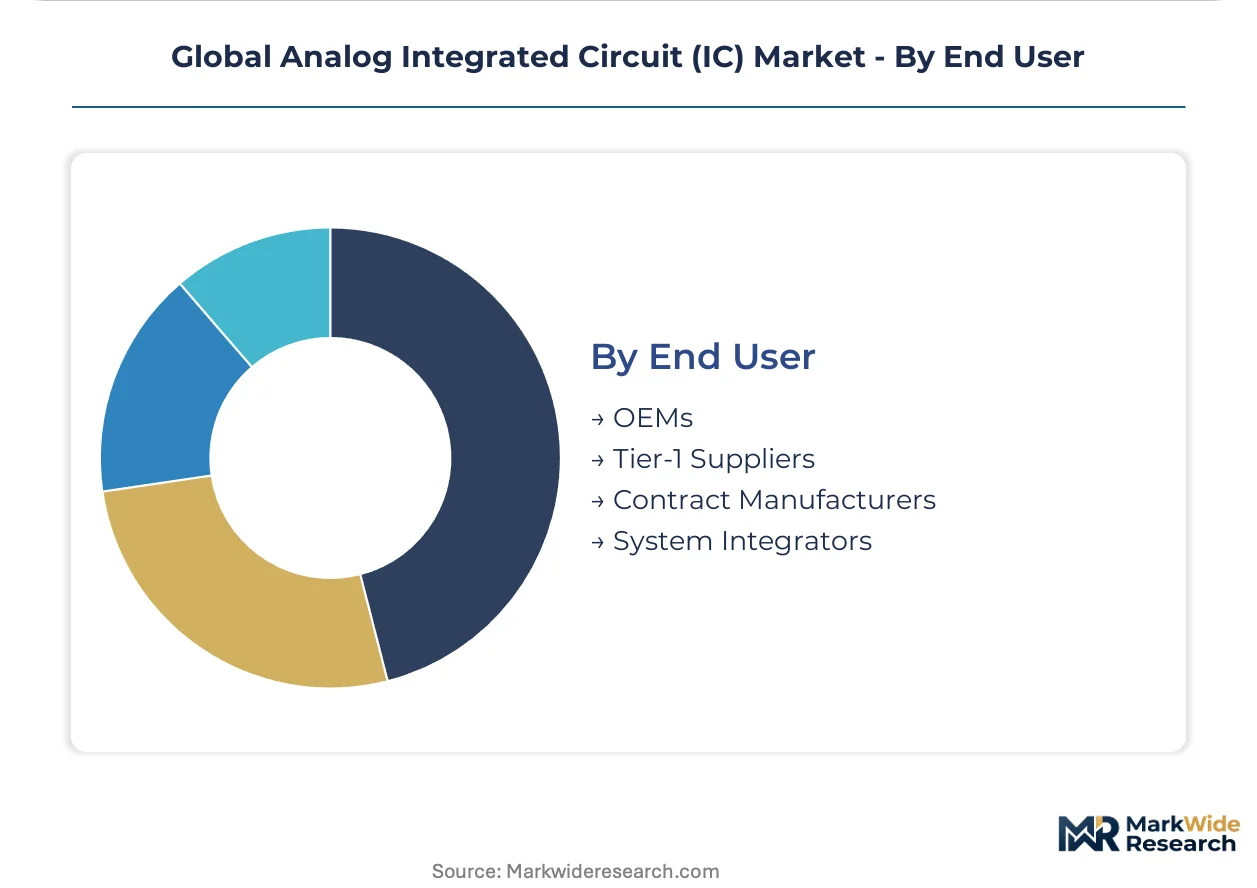
End User:
Channel structure varies by procurement scale and technical support requirements, with direct vendor relationships displacing traditional distribution for qualified accounts.
- OEMs:Automotive and industrial equipment manufacturers specify analog subsystems directly, embedding energy-efficiency requirements into supplier scorecards. German and Chinese OEMs establish vendor-managed inventory programs that bypass regional distributors for voltage regulators and data converters.
- Tier-1 Suppliers:Subsystem integrators cascade OEM specifications through semiconductor supply chains with simultaneous engineering support demands across multiple voltage domains.
- Contract Manufacturers:Electronics manufacturing services providers procure standard analog components at volume scale.
- System Integrators:Industrial automation and building control specialists assemble multi-vendor solutions with legacy system integration requirements.
OEMs dominate specification authority. Tier-1 Suppliers are consolidating procurement influence through design-in partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analog IC design talent clusters in Richardson, Dresden, and Shanghai anchor regional production networks. Foundry investments concentrate where government incentives intersect with established semiconductor ecosystems.
United States
Automotive electrification and aerospace programs drive precision analog demand across Michigan and Texas manufacturing corridors. EPA energy efficiency standards under the IRA framework mandate stricter power management specifications for industrial motor systems. Richardson's 300-millimeter fabrication cluster expands die-per-wafer economics for voltage regulators serving domestic automotive OEMs.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg multiply analog channel counts for predictive maintenance architectures. REACH chemical restrictions and RoHS substance limits constrain packaging material choices across European supply chains. Dresden's fabrication ecosystem anchors BiCMOS production for high-precision data converters serving automotive lidar manufacturers.
China
Domestic semiconductor fabrication capacity expansion targets automotive and consumer electronics analog demand. Dual carbon goals redirect R&D budgets toward low-power sensor interfaces and adaptive power architectures. Yangtze River Delta clusters in Shanghai and Suzhou concentrate CMOS foundry investments for standard voltage regulators.
India
PLI scheme subsidies for semiconductor manufacturing attract analog foundry investments in Gujarat and Karnataka. Central Electricity Authority efficiency mandates shape power supply specifications for industrial equipment procurement. Bengaluru's design ecosystem develops captive supply options for automotive-grade voltage regulators and sensor interfaces.
Japan
Automotive tier-one suppliers in Aichi and Kanagawa prefectures cascade precision voltage regulation requirements through semiconductor supply chains. METI industrial policy supports domestic fabrication capacity for mixed-signal devices. Kyushu's semiconductor materials cluster supplies polished wafers to analog foundries across East Asia.
Global Analog Integrated Circuit (IC) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across fragmented procurement channels. IDM fabs with captive 300-millimeter capacity command cost leadership in standard voltage regulators and operational amplifiers. Fabless specialists occupy premium positioning in high-precision data converters where BiCMOS process complexity justifies die cost penalties. Strategic moves concentrate on backward integration into wafer supply and geographic diversification of packaging operations.
Within the integrated device manufacturer tier, Texas Instruments and Analog Devices Inc. exemplify scale-driven cost structures versus precision-focused specialization. Infineon Technologies AG occupies a position bridging automotive qualification depth with industrial automation breadth. These three anchors demonstrate how Richardson-based fabrication, high-precision signal chain expertise, and Munich-anchored automotive heritage represent divergent competitive vectors in analog IC supply.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| Microchip Technology |
| ON Semiconductor |
| Renesas Electronics Corporation |
| Qualcomm |
| Others |
Supply & Pricing Matrix
Polished silicon wafer costs cascade through three pricing tiers as Japanese and German substrate suppliers transmit spot-price volatility to Richardson and Dresden fabrication clusters serving automotive and industrial buyers.
Pricing Analysis
Component-plus-reference-design bundling separates premium BiCMOS data converters from standard CMOS voltage regulators and economy-grade operational amplifiers. Price differentiation hinges on AEC-Q100 automotive certification grade and 300-millimeter wafer scale. Cost compression in standard analog tiers is intensifying because Chinese foundry expansion under dual carbon mandates adds CMOS capacity. Contract manufacturers exhibit highest price sensitivity; aerospace OEMs accept 40-60% die cost premiums for precision specifications.
Supply Chain Analysis
Direct-to-OEM channels handle automotive and industrial hyperscale demand, displacing regional distributors for voltage regulators and data converters. Raw material flows draw from Japanese and German polished wafer suppliers, Kyushu semiconductor materials clusters, and Texas-based 300-millimeter fabrication. Single-source vulnerability concentrates in 200mm and 300mm substrate supply. Distribution runs through vendor-managed inventory programs anchored by German and Chinese tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into procurement pull-through, with EU Green Deal efficiency mandates and EPA IRA standards embedding analog specifications directly into automotive and industrial OEM scorecards.
For Market Incumbents: Extend 300-millimeter fabrication scale in Richardson and Dresden to defend cost leadership against Chinese foundry expansion under dual carbon subsidies. Deepen backward integration into polished wafer supply to mitigate Japanese and German substrate concentration. Accelerate AEC-Q100 qualification pipelines to capture automotive electrification demand before 18-24 month certification timelines delay revenue recognition.
For New Entrants and Emerging Players: Enter via India's PLI-subsidized fabrication incentives in Gujarat and Karnataka, targeting captive supply relationships for automotive-grade voltage regulators. Medical imaging channel expansion offers white-space as MRI and CT manufacturers unbundle analog front-end modules from system integrators. Pursue direct procurement partnerships with German industrial automation OEMs multiplying analog channel counts for predictive maintenance architectures.
For Investors and Strategic Acquirers: Consolidation pressure builds where BiCMOS process complexity premiums constrain fabless specialists to narrow aerospace and medical niches. Long-term viability favors asset-light designers with proprietary IP blocks embedded in application-specific standard products. Watch edge AI sensor fusion demand as the inflection signal where adaptive power architectures dynamically scale precision versus consumption.
| Strategic Initiative | Industry Significance |
|---|---|
| 300-Millimeter Wafer Migration | Richardson and Dresden clusters compress cost curves for standard voltage regulators. |
| Backward Integration into Substrate Supply | Captive polished wafer sourcing mitigates Japanese and German supply concentration. |
| AEC-Q100 Certification Acceleration | Automotive qualification depth secures electrification procurement from tier-one suppliers. |
| BiCMOS Process Investment | Mixed-signal precision captures medical imaging and aerospace specification premiums. |
| Direct OEM Procurement Partnerships | Vendor-managed inventory programs bypass distributors for high-volume automotive accounts. |
Research Methodology
Multiple input streams — semiconductor fabrication executives, tier-one automotive procurement leads, industrial automation R&D directors, and analog design specialists — were reconciled against secondary validation from SEC 10-K filings, EIA energy efficiency databases, EU Green Deal implementation reports, and automotive production registries. Bottom-up die-per-wafer economics and top-down OEM specification demand were triangulated to anchor volume and value estimates.
Data-stream reconciliation across product type, technology process, application vertical, and end-user channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated EPA IRA energy efficiency mandate compliance timelines and REACH substance restriction qualification cycle impacts on time-to-revenue.
The model holds under stable regulatory enforcement and continued automotive electrification capex; deviation in subsidy program continuity or substrate supply disruption would shift trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Energy Metering IC Chip Market