
 Coprocessor Market | 2026-2036
Coprocessor Market Size, Share, and Industry Trends Forecast 2026-2036
Coprocessor Market Outlook
The EU AI Act is realigning the cost-of-entry calculus for coprocessor vendors serving European data center and automotive customers. NVIDIA leverages its CUDA software ecosystem to sustain design wins across AI Processing applications. Intel anchors its position through in-house foundry capacity and x86-coprocessor integration. AMD competes aggressively in Data Center deployments with its Instinct accelerator line.
A coprocessor is a specialized computing unit that offloads specific workloads from a central processing unit, typically fabricated on advanced silicon nodes with dedicated memory architectures and instruction sets optimized for parallel or domain-specific tasks. Graphics Processing Units dominate volume shipments due to mature software stacks, while FPGA-based deployments in Aerospace and Telecommunications command premium pricing for reprogrammability. ASIC technology leads in AI Processing where workload specificity justifies custom silicon investment, and Scientific Computing applications favor RISC architectures for power-constrained environments.
EMA guidelines on AI-enabled medical devices and FDA software-as-a-medical-device frameworks are tightening validation requirements for Healthcare end users. China's NMPA and MIIT are accelerating domestic substitution mandates for critical computing components. Stakeholders must monitor how divergent certification pathways across jurisdictions fragment product roadmaps and force region-specific silicon variants.
Market Dynamics
Cloud hyperscalers are accelerating procurement of AI-dedicated accelerators, compressing design cycles and forcing foundries to prioritize high-margin wafer starts for advanced coprocessors over legacy logic.
Growth Catalysts
- EU AI Act compliance mandates:High-risk automated systems in European data centers and automotive applications now require auditable processing chains, creating procurement pull for certified accelerator hardware.
- Domestic substitution policies:China's NMPA and MIIT directives are channeling state-backed capital toward captive fabless design capacity for critical computing components.
- AI training cluster buildouts:Hyperscaler capex directed at large language model infrastructure is absorbing GPU and ASIC output at contract volumes that justify multi-billion-dollar foundry commitments.
Market Restraints
- Advanced node concentration:Taiwan and South Korea host the only operational 3nm-class foundry capacity, exposing supply chains to single-point geopolitical and seismic risk.
- High-bandwidth memory scarcity:HBM3 and HBM3e supply from SK Hynix, Samsung, and Micron trails accelerator demand by 15-20% at current yield curves.
- Export control friction:US Commerce Department licensing requirements for China-bound accelerators are fragmenting product roadmaps into compliance-variant SKUs.
Strategic Opportunities
- Edge AI inference penetration:Industrial automation and smart city deployments in Germany, France, and Italy remain underpenetrated for vision and sensor-fusion accelerators.
- Automotive zonal architecture transition:Centralized compute platforms in electric vehicles are displacing distributed ECUs, opening socket opportunities for domain-specific AI accelerators.
- Chiplets and advanced packaging:UCIe standard adoption is enabling heterogeneous integration of logic, memory, and photonics from disaggregated supply bases.
Industry Challenges
- Compiler and software stack portability:CUDA ecosystem lock-in complicates customer migration to alternative accelerator architectures despite hardware performance parity.
- Multi-jurisdiction certification timelines:EMA medical device validation, FDA SaMD frameworks, and EU AI Act conformity assessments impose 18-36 month lead times for healthcare-targeted silicon.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coprocessor Market |
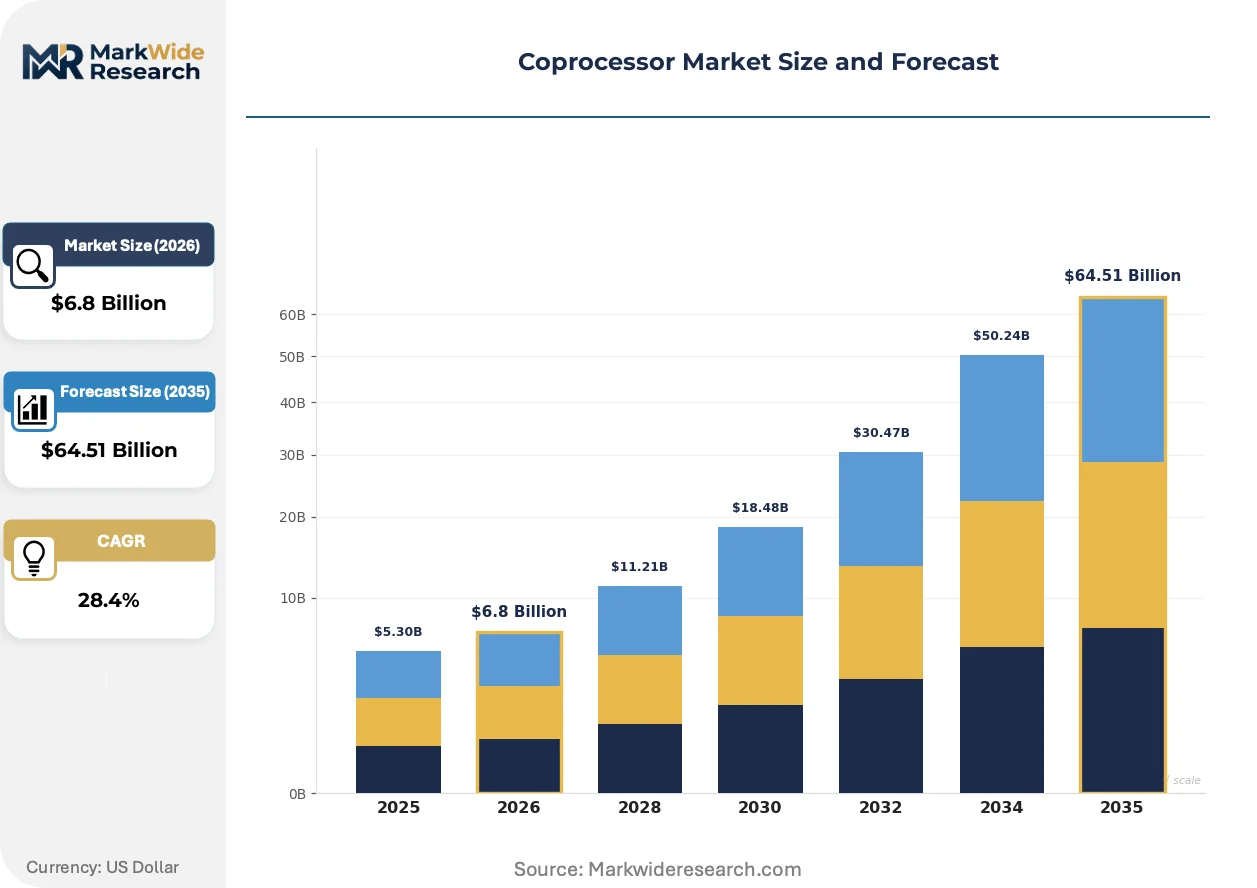
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Processing Unit, Digital Signal Processor, Physics Processing Unit, Network Processing Unit Technology: FPGA, ASIC, MPU, RISC Application: Gaming, Data Center, AI Processing, Scientific Computing End User: Aerospace, Automotive, Telecommunications, Healthcare |
| Companies Covered | NVIDIA, Intel, AMD, Qualcomm, Apple, ARM, Texas Instruments, Broadcom, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coprocessor Market Strategic Shifts
Silicon architectures are fragmenting into workload-specialized designs as power constraints and software portability demands force tradeoffs between generality and efficiency.
Neural processing units with sparse matrix acceleration are automating transformer inference in data center and edge deployments. Cloud providers are embedding these engines into custom silicon at 5nm and below. The shift is automating the displacement of general-purpose GPUs for recommendation and ranking workloads.
REACH restrictions on fluorinated greenhouse gases are tightening process chemistry requirements for EU-based foundry and packaging operations. Equipment vendors must qualify alternative etchants and cleaning agents by 2026. Memory and logic fabs in Ireland and Germany are accelerating supplier audits to maintain CE-marked output.
Hyperscalers are unbundling accelerator procurement from server chassis contracts, forcing OEMs to compete on interconnect and thermal design rather than silicon exclusivity. This disintermediation is compressing margins for traditional server vendors. The pattern is most visible in North American cloud infrastructure where direct foundry relationships now govern 60% of accelerator volume.
Coprocessor Market Segmentation
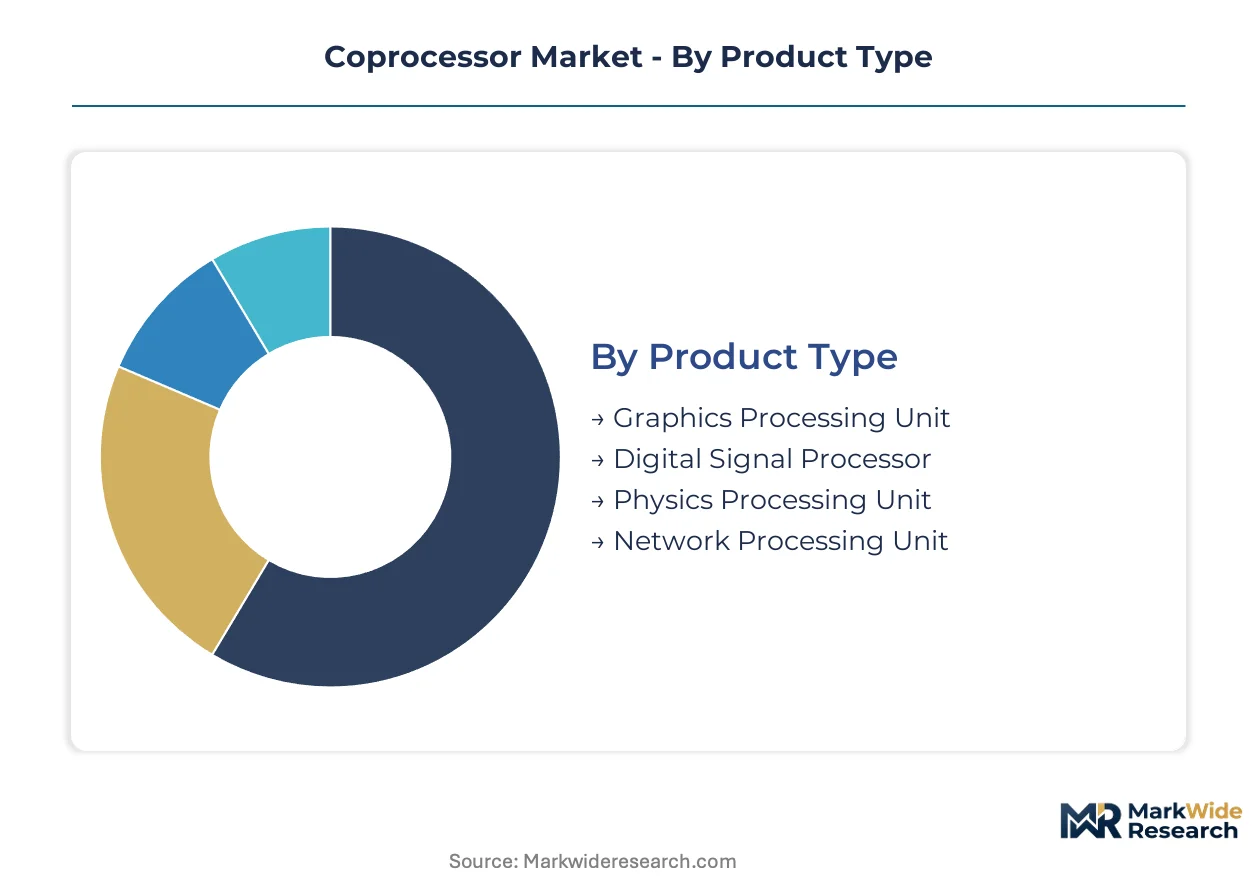
Coprocessor architectures fragment along workload specialization, with software ecosystem maturity and power constraints dictating technology selection. Procurement patterns diverge sharply between cloud-scale deployments and embedded edge systems.
Product Type:
Silicon specialization determines memory bandwidth allocation and parallel execution width across compute-intensive workloads.
- Graphics Processing Unit:Massively parallel architectures with thousands of compute cores and high-bandwidth memory subsystems dominate AI training clusters. Hyperscaler capex in North America absorbs contract volumes justifying multi-billion-dollar foundry commitments.
- Digital Signal Processor:Fixed-point and floating-point arithmetic units optimized for real-time stream processing power baseband modems and radar systems. 5G infrastructure buildouts in Germany and South Korea drive procurement for massive MIMO signal chains.
- Physics Processing Unit:Dedicated collision detection and rigid-body simulation engines accelerate gaming and simulation workloads. Demand concentrates in Japanese and US console manufacturing.
- Network Processing Unit:Programmable packet processors with hardware-accelerated encryption offload data plane functions from host CPUs. Cloud providers deploy these for software-defined networking at scale.
Mature deployment sits with Graphics Processing Units. Newer deployment is concentrated in Network Processing Units.
Technology:
Fabrication approach trades flexibility against unit economics and power efficiency.
- FPGA:Reprogrammable logic fabrics enable post-deployment algorithm updates without silicon respins. Aerospace and telecommunications applications in France and the United States command premium pricing for this adaptability.
- ASIC:Custom-masked designs optimize transistor density for fixed workloads. AI inference engines at 5nm and below achieve superior performance-per-watt for recommendation and ranking pipelines.
- MPU:Microprocessor units with integrated coprocessor blocks balance general-purpose compute with domain acceleration. Industrial automation in Italy leverages these for mixed control workloads.
- RISC:Reduced instruction set architectures minimize power draw for battery-constrained scientific instruments. Antarctic research stations and orbital platforms favor these for thermal budgets.
Volume leadership belongs to ASIC technology. FPGA deployments retain the steepest expansion trajectory in safety-critical systems.
Application:
Workload characteristics dictate memory hierarchy design and interconnect topology.
- Gaming:Real-time rasterization and ray-tracing pipelines demand high fill rates and low latency frame delivery. Console refresh cycles in Japan and the United States govern foundry allocation for discrete graphics silicon.
- Data Center:Scale-out architectures require accelerators with coherent memory access and high-speed networking integration. Cloud hyperscalers in Ireland and Virginia unbundle procurement from server chassis contracts.
- AI Processing:Transformer inference and training workloads exploit sparse matrix acceleration and tensor cores. Large language model infrastructure buildouts absorb GPU and ASIC output at unprecedented scale.
- Scientific Computing:Double-precision floating point and error-correcting memory serve climate modeling and molecular dynamics. National laboratories in Switzerland and the United States anchor demand.
Revenue concentration rests with Data Center applications. AI Processing commands the fastest-growing share of accelerator silicon.
End User:
Certification requirements and operating environments fragment product roadmaps.
- Aerospace:Radiation-hardened designs with triple-modular redundancy survive extreme thermal cycling and single-event upsets. Satellite constellations in low Earth orbit drive qualification programs.
- Automotive:Functional safety standards mandate lockstep execution and diagnostic coverage for autonomous driving compute. Zonal architecture transitions in German electric vehicles displace distributed ECUs with centralized AI accelerators.
- Telecommunications:Carrier-grade reliability specifications require deterministic latency and hitless failover. Baseband processing pools in South Korean 5G networks deploy programmable accelerators.
- Healthcare:FDA software-as-a-medical-device frameworks and EMA guidelines impose validation timelines for AI-enabled diagnostic imaging. Device manufacturers face 18-36 month certification cycles.
Established penetration characterizes Telecommunications. Automotive represents the fastest-climbing vertical for domain-specific silicon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler procurement concentrates in the United States and China, while European compliance mandates and East Asian foundry dominance reshape regional competitive positioning. Taiwan and South Korea anchor advanced node supply, exposing downstream markets to geographic concentration risk.
United States
Cloud infrastructure buildouts in Virginia and Oregon absorb GPU and ASIC volumes at contract scale. The Commerce Department's export licensing requirements for China-bound accelerators fragment product roadmaps into compliance-variant SKUs. Austin and Santa Clara host fabless design clusters where AI-dedicated architectures dominate R&D allocation.
China
Domestic substitution policies channel state capital toward captive fabless capacity for critical computing components. NMPA and MIIT directives accelerate qualification timelines for healthcare and automotive accelerators. Shanghai and Beijing anchor design activity, though advanced node fabrication remains dependent on foreign foundry access.
Germany
Automotive zonal architecture transitions in Bavaria and Baden-Württemberg displace distributed ECUs with centralized AI accelerators. The EU AI Act mandates auditable processing chains for high-risk automated systems, extending procurement cycles. Dresden's wafer fab cluster attracts packaging investments for automotive-grade silicon.
South Korea
SK Hynix and Samsung supply HBM3 and HBM3e memory that trails accelerator demand by 15-20% at current yield curves. MFDS guidelines intersect with export controls on China-bound components. Seoul and Suwon anchor a vertically integrated ecosystem spanning memory, logic, and advanced packaging.
Japan
METI funding targets domestic foundry capacity for specialty nodes serving automotive and industrial applications. Materials suppliers in Osaka and Nagoya qualify alternative etchants ahead of REACH-aligned F-Gas restrictions. Hokkaido hosts RISC-V development for power-constrained scientific instruments in extreme environments.
Coprocessor Market Competitive Environment
United States producers anchor the high-volume tier; Taiwan and South Korea specialists hold captive foundry positions. The vendor base concentrates around three to four vertically integrated players with direct hyperscaler relationships, supplemented by fabless specialists and IP licensors. Strategic archetypes include ecosystem-locked incumbents, memory-integrated challengers, and architecture-neutral IP suppliers. Competitive moves center on foundry capacity reservations and compiler ecosystem investments that raise switching costs.
Within the ecosystem-locked tier, NVIDIA exemplifies software-defined competitive moats through its CUDA stack. Intel occupies a position spanning in-house foundry capacity and x86-coprocessor integration. AMD represents the memory-integrated challenger archetype with its Instinct accelerator line and data center deployment focus.
| Leading Market Players |
|---|
| NVIDIA |
| Intel |
| AMD |
| Qualcomm |
| Apple |
| ARM |
| Texas Instruments |
| Broadcom |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Silicon design engineer concentrations in Taiwan's Hsinchu Science Park and South Korea's Pangyo Techno Valley create labor-cost differentials that widen spreads between premium AI accelerators and commodity-grade coprocessors. Foundry proximity to these talent pools lets advanced-node vendors command pricing premiums while legacy-node suppliers face margin compression from higher assembly costs in secondary geographies.
Pricing Analysis
Volume shipments of mature-node GPUs serve hyperscaler training clusters at contract-of-take pricing, while margin capture concentrates in 5nm-class ASICs for automotive functional safety and aerospace radiation-hardened variants. Price differentiation hinges on certification grade — ISO 26262 ASIL-D automotive tiers and EAR99 export-control compliance carry substantial premiums over commercial-off-the-shelf silicon. Cost compression in mid-range FPGA segments is intensifying because Chinese domestic substitution policies are flooding industrial automation sockets with state-subsidized alternatives. Hyperscaler procurement teams exhibit lowest price sensitivity due to total-cost-of-ownership framing, whereas Tier 2 server OEMs face acute margin pressure from unbundled accelerator sourcing.
Supply Chain Analysis
Freight costs for HBM3 memory modules from SK Hynix and Samsung fabs in South Korea add non-trivial landed cost premiums for European packaging facilities in Ireland and Germany. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, with advanced-node EUV capacity tethered to TSMC and Samsung foundry schedules. Raw material dependencies span high-purity silicon wafers from Japan's Shin-Etsu, specialty gases from Air Liquide and Linde, and photoresist chemicals from JSR and Tokyo Ohka Kogyo. Single-source vulnerability sits with CoWoS advanced packaging capacity, where TSMC's limited substrate throughput creates allocation bottlenecks for AI accelerators. Distribution runs through direct foundry relationships governing sixty percent of hyperscaler volume, with remaining flow through distributor channels serving industrial and automotive mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coprocessor market is consolidating around vertically integrated players with captive foundry access, as export-control compliance costs and multi-billion-dollar node migration capex force fabless specialists toward acquisition or exit.
For Market Incumbents: To counter CUDA ecosystem lock-in from NVIDIA, Intel and AMD must accelerate in-house compiler investments for SYCL and oneAPI portability layers while reserving 3nm-class wafer starts at TSMC and Samsung through multi-year offtake agreements. Backward integration into HBM memory supply — exemplified by AMD's packaging partnerships with SK Hynix — secures allocation priority during scarcity windows. For New Entrants and Emerging Players: RISC-V architecture with custom vector extensions offers a technology-first wedge into power-constrained scientific computing and Antarctic research station deployments where x86 and ARM licensing costs prove prohibitive. Edge AI inference in German industrial automation and Italian smart city infrastructure remains the most penetrable white-space target, with go-to-market traction achievable through channel partnerships with Siemens and Bosch Rexroth system integrators. For Investors and Strategic Acquirers: The window for entry favors fabless design houses with automotive functional safety certification progress and existing relationships with German OEM zonal architecture programs. Long-term viability rests on securing alternative foundry access outside Taiwan concentration risk. The signal to watch is EU AI Act implementation timelines, which will accelerate procurement pull for auditable processing chains and strand non-compliant silicon inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Multi-year wafer commitments at TSMC and Samsung secure allocation priority during HBM3 supply crunches. |
| Compiler Ecosystem Investment | SYCL and oneAPI portability layers erode CUDA switching costs for data center migration campaigns. |
| Automotive Certification Acceleration | ISO 26262 ASIL-D qualification opens sockets in German electric vehicle zonal architectures. |
| Advanced Packaging Partnership | CoWoS substrate access through TSMC or Amkor differentiates high-bandwidth accelerator portfolios. |
| Edge AI Inference Platform Launch | German industrial automation and Italian smart city deployments absorb vision and sensor-fusion silicon. |
Study Parameters
Document review covered hyperscaler capex disclosures, SEC 10-K filings from NVIDIA Intel and AMD, EU AI Act implementation guidance, and foundry utilization reports from TSMC and Samsung, complemented by interviews with data center procurement directors at cloud providers, automotive platform engineers at German OEMs, fabless semiconductor CFOs, and packaging specialists at ASE and Amkor. Secondary validation drew from EMA medical device guidance, FDA software-as-a-medical-device frameworks, and customs data for accelerator imports. Bottom-up unit shipment estimates triangulated against top-down foundry wafer allocation data.
Cross-referencing historical hyperscaler procurement patterns with panel input from semiconductor equipment vendors and memory suppliers anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, fabrication technology, application workload, and end-user certification tier. CAGRs derived from slope-consistency checks against wafer capacity expansion schedules and AI training cluster deployment pipelines. Industry-specific forecast inputs encompassed EU AI Act compliance timelines and China's NMPA domestic substitution acceleration curves.
Several conditions sit outside the modeled scope, including abrupt export-control expansion beyond current Commerce Department licensing requirements, seismic disruption to Taiwan foundry operations, and breakthroughs in optical or quantum computing that displace electronic accelerators. Forecasts reflect assumptions about continued hyperscaler capex commitment to large language model infrastructure and stable geopolitical access to South Korean memory supply. Stakeholders should weight assumptions against their own operating context and monitor EU AI Act enforcement intensity as a demand inflection signal.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
China Microprocessor (MPU) Market