
 Embedded Non-Volatile Memory Market | 2026-2036
Embedded Non-Volatile Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Non-Volatile Memory Market Analysis
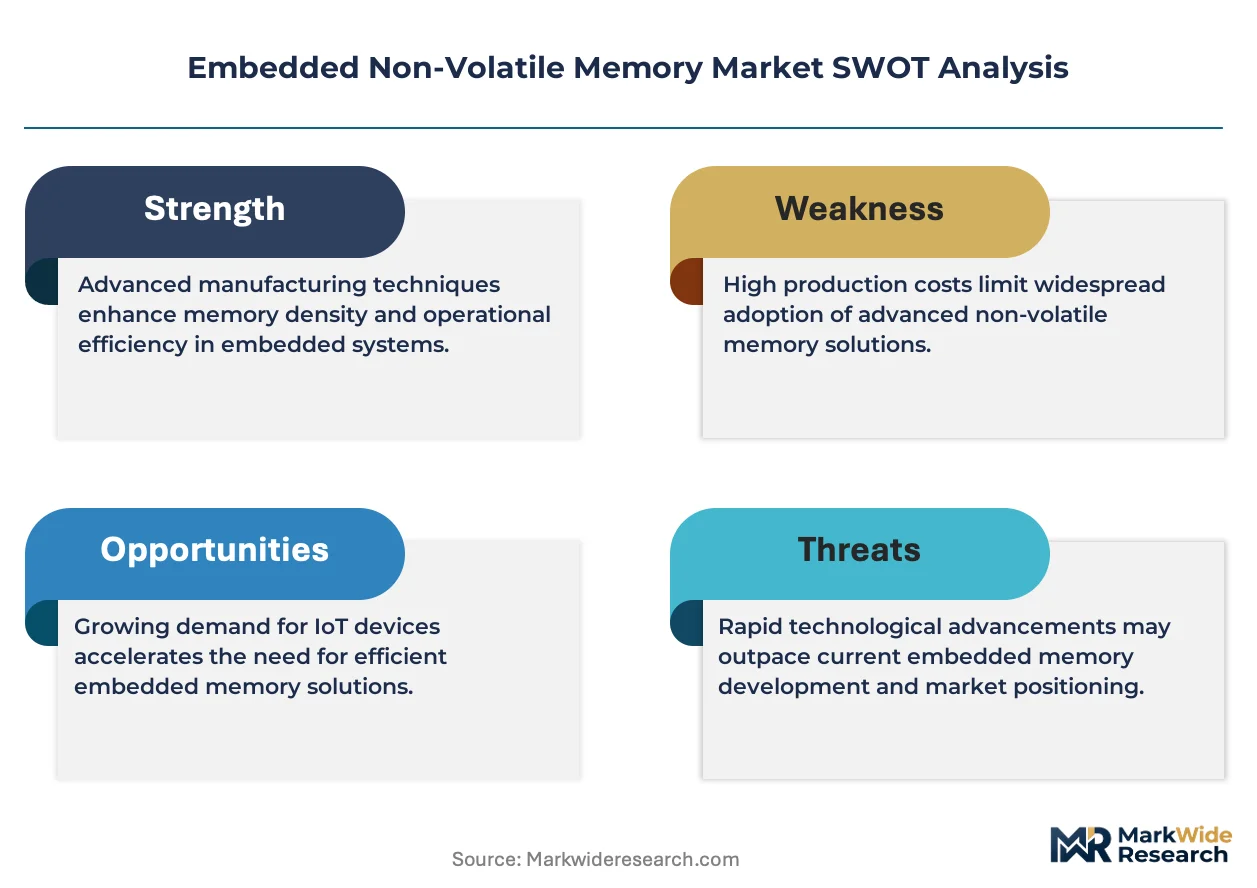
The foundry-to-fabless capability gap is reorganizing competitive hierarchy in embedded NVM fabrication. Samsung Electronics Co. Ltd leverages captive wafer capacity to anchor supply security for automotive-grade flash. TSMC sustains process leadership at advanced nodes where MRAM integration demands precision lithography. Infineon Technologies specializes in automotive-qualified embedded NVM with AEC-Q100 compliance, occupying a defensible niche against commodity memory suppliers.
Embedded non-volatile memory retains stored data without continuous power, typically fabricated at process nodes between 40nm and 130nm using floating-gate or charge-trap architectures for code storage and parameter retention in microcontroller systems. Flash dominates unit shipments across consumer electronics and telecommunications applications, while MRAM gains traction in industrial automation where write endurance exceeds one trillion cycles. EEPROM retains margin strength in low-density configurations below 512Kb where design-in longevity offsets higher per-bit cost. Spintronics-based technologies attract R&D concentration from foundries seeking differentiation beyond planar NAND scaling limits.
REACH restrictions on per- and polyfluoroalkyl substances constrain fluorinated precursor availability for atomic layer deposition in European-bound production, while EU F-Gas Regulation phases down greenhouse gas-intensive etching chemistries used in 3D NAND stack formation. FDA cybersecurity guidance for connected medical devices indirectly elevates embedded NVM requirements for secure boot and firmware integrity in diagnostic equipment sold into the United States. Stakeholders must weigh geographic compliance cost against process node roadmap commitments when siting new captive or merchant NVM capacity.
Market Dynamics
Automotive ECU consolidation is forcing embedded NVM suppliers to reconcile AEC-Q100 qualification timelines with compressed design cycles, while foundry capacity allocation for mature nodes tightens against competing analog and power semiconductor demand.
Growth Catalysts
- Automotive ECU Integration:Centralized vehicle architectures require embedded flash for firmware storage across powertrain, ADAS, and body control modules. Tier-1 suppliers in Germany and Japan are expanding qualification programs for 40nm-90nm embedded NVM.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon etching chemistries is accelerating process chemistry innovation for charge-trap memory fabrication. European-bound production lines are retooling atomic layer deposition systems.
- MRAM Endurance Thresholds:Spin-transfer torque architectures exceeding one trillion write cycles are penetrating industrial automation controllers. Factory automation OEMs in South Korea are qualifying MRAM for PLC replacement cycles.
Market Restraints
- Fluorinated Precursor Constraints:REACH restrictions on per- and polyfluoroalkyl substances limit atomic layer deposition precursor availability for European-bound wafer starts. Memory foundries face reformulation costs or supply quota rationing.
- Mature Node Capacity Squeeze:40nm-130nm foundry capacity concentrates among three merchant suppliers. Fabless embedded NVM designers face allocation priority conflicts with power management IC and display driver demand.
- MRAM Density Ceiling:Spintronics-based cells occupy larger die area than floating-gate equivalents at comparable density nodes. Cost-per-bit economics constrain MRAM to high-endurance, low-density applications below 256Mb.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and test are attracting embedded NVM packaging investment. Domestic microcontroller demand from white goods and automotive Tier-2 suppliers is rising.
- FDA Cybersecurity Guidance:Connected diagnostic equipment sold into the United States requires secure boot architectures with tamper-resistant embedded NVM. Medical device OEMs are qualifying new suppliers for firmware integrity solutions.
- Chalcogenide Phase-Change Convergence:Integration of PCRAM with CMOS logic at 28nm and below offers embedded storage for AI inference accelerators. Foundry R&D programs in Taiwan and the United States are co-developing process modules.
Industry Challenges
- AEC-Q100 Qualification Timeline Compression:Automotive-grade embedded NVM requires 12-18 month validation cycles for temperature grade 1 (-40°C to 125°C). Design wins are locking two years ahead of volume production, straining R&D resource planning.
- Legacy EEPROM Design-In Persistence:Industrial equipment with 15-20 year service life creates procurement fragmentation. Buyers resist migrating to newer NVM technologies despite superior endurance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Non-Volatile Memory Market |
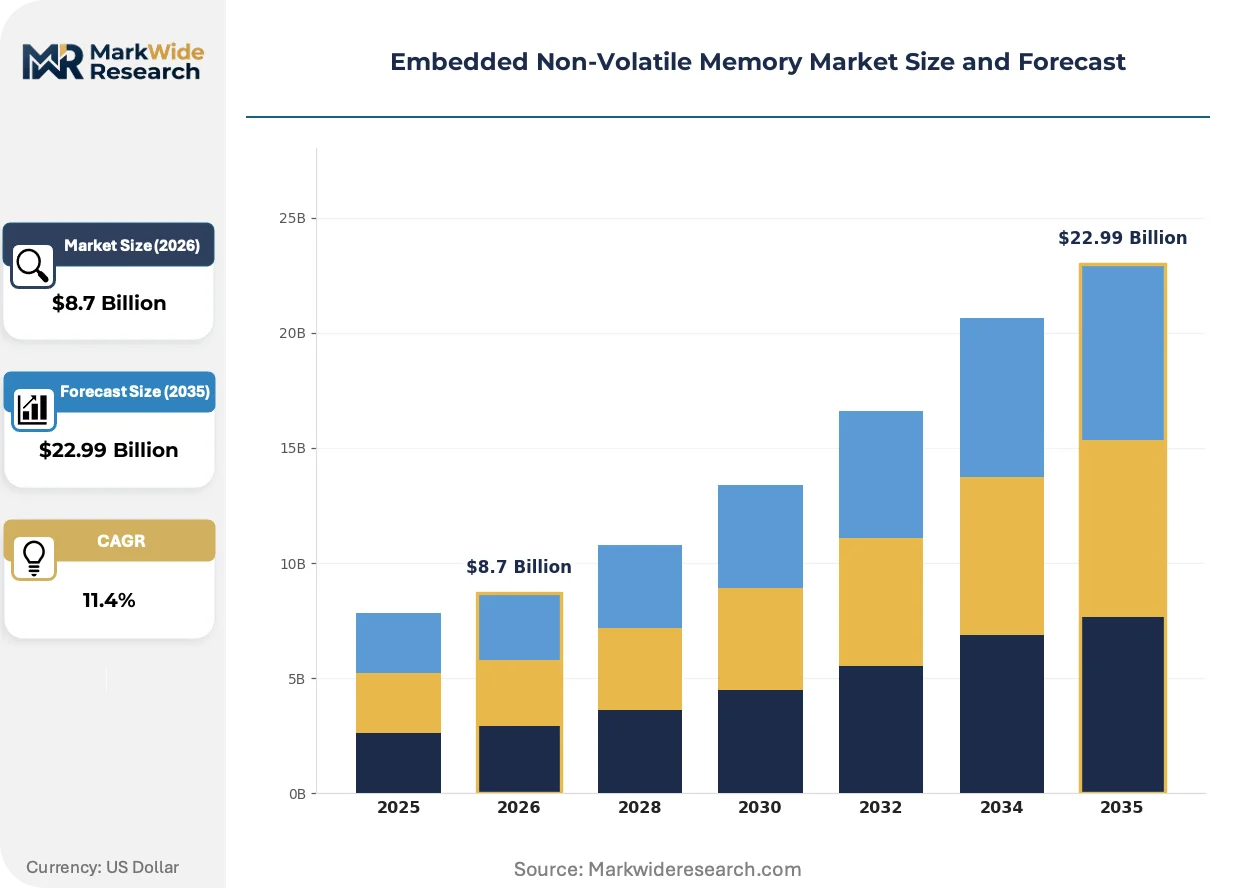
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEPROM, Flash, MRAM, FeRAM Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications End User: OEMs, Retailers, Distributors, System Integrators Technology: 3D NAND, 2D NAND, NOR, Spintronics |
| Companies Covered | Samsung Electronics Co. Ltd, Micron Technology, Inc., TSMC, SK Hynix, Toshiba Electronic Devices & Storage Corporation, Western Digital Technologies, Inc., Rohm Co. Ltd, Infineon Technologies, Crossbar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Non-Volatile Memory Market Emerging Trajectories
Process-node bifurcation is splitting embedded NVM development between automotive-qualified mature nodes and advanced-node MRAM integration for AI accelerators, with regulatory chemistry constraints adding a third vector of technical divergence.
MRAM is fragmenting the embedded storage landscape by offering non-volatile retention with SRAM-compatible speed. Automotive SoC designers are sampling 22nm MRAM macros for gateway controllers and zone ECUs. The technology is fragmenting traditional flash-dominated sockets across powertrain and chassis safety domains where write endurance requirements exceed ten million cycles.
EU F-Gas Regulation is forcing etching chemistry substitution in 3D NAND and embedded flash stack formation. Memory foundries serving European automotive customers are qualifying fluorine-free plasma etch processes for high-aspect-ratio charge-trap layers. South Korean and Japanese equipment suppliers are shipping modified chamber configurations to EU-bound production lines.
Certification-driven supplier selection is compressing procurement cycles for automotive-grade embedded NVM. Tier-1 ECU manufacturers are pre-qualifying dual-source NVM macros to mitigate AEC-Q100 audit risk. This pattern is most visible in German automotive supply chains, where Volkswagen Group and BMW procurement specifications now mandate second-source validation before design-in approval.
Embedded Non-Volatile Memory Market Segmentation
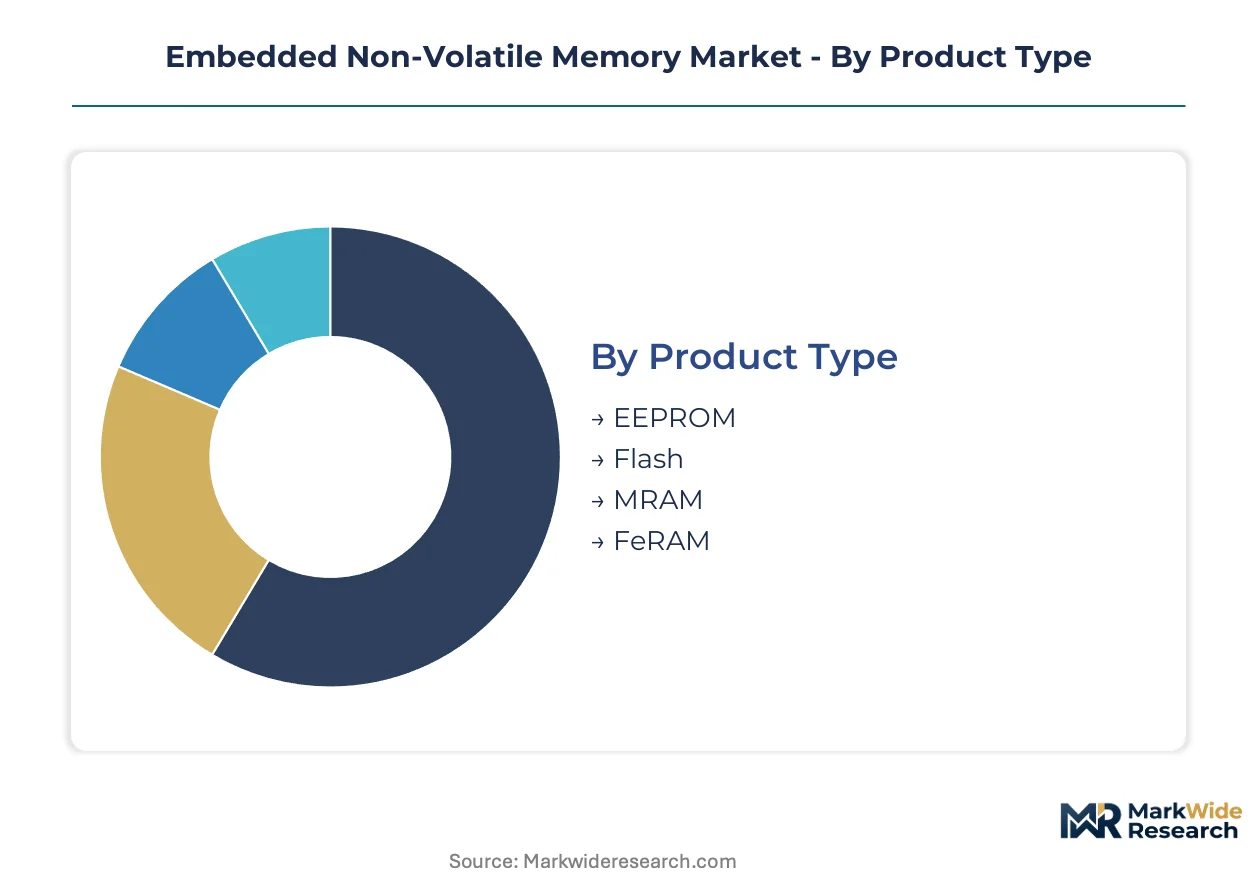
Embedded NVM procurement splits across incompatible technical requirements. Automotive buyers prioritize temperature-grade endurance while consumer OEMs optimize for die-size cost efficiency. These divergent specifications fragment supplier portfolios and foundry capacity allocation.
Product Type:
Flash faces substitution pressure from MRAM in high-cycle industrial sockets where endurance specifications exceed floating-gate physical limits.
- Flash:Floating-gate and charge-trap architectures dominate microcontroller code storage at 40nm-130nm nodes. Automotive ECU consolidation in Germany and Japan concentrates demand for AEC-Q100 qualified embedded flash macros.
- MRAM:Spin-transfer torque cells deliver SRAM-compatible speed with non-volatile retention. Factory automation OEMs in South Korea are qualifying MRAM for PLC applications exceeding one trillion write cycles.
- EEPROM:Retains margin strength in sub-512Kb configurations where design-in longevity offsets higher per-bit cost against flash alternatives.
- FeRAM:Ferroelectric capacitors serve niche medical and RFID applications requiring low-power write operations with instant non-volatile capture.
Flash anchors the volume base while MRAM gains share at the steepest rate.
Application:
Automotive qualification timelines stretch 12-18 months, creating the highest barrier to supplier switching among all demand verticals.
- Automotive:Centralized vehicle architectures require embedded NVM across powertrain, ADAS, and body control modules. Tier-1 suppliers in Germany and Japan are expanding qualification programs for 40nm-90nm embedded solutions.
- Industrial Automation:PLC and motion controllers demand write endurance beyond ten million cycles. South Korean factory automation OEMs are migrating from battery-backed SRAM to MRAM for maintenance-free retention.
- Consumer Electronics:Smartphone and wearable OEMs prioritize die-size efficiency for firmware storage in Bluetooth and power management companion chips.
- Telecommunications:Baseband processors and RF transceivers employ embedded NVM for calibration parameter retention across temperature extremes.
Automotive commands the longest design-in cycles while industrial automation shows the most rapid technology substitution.
End User:
System integrators intermediate between component suppliers and fragmented industrial equipment builders with divergent specification requirements.
- OEMs:Automotive and consumer electronics original equipment manufacturers specify embedded NVM macros at the semiconductor design stage, locking supplier relationships two years ahead of volume production.
- System Integrators:Industrial automation specialists configure PLC and controller platforms with socketed or soldered-down NVM modules for end-customer customization.
- Distributors:Arrow Electronics and Avnet maintain inventory of standard-density EEPROM and flash for replacement markets and small-volume industrial builds.
- Retailers:Limited direct engagement; primarily serve hobbyist and prototyping demand for development kits and programmer hardware.
OEMs drive specification standards while distributors capture replacement volume in extended-lifecycle equipment.
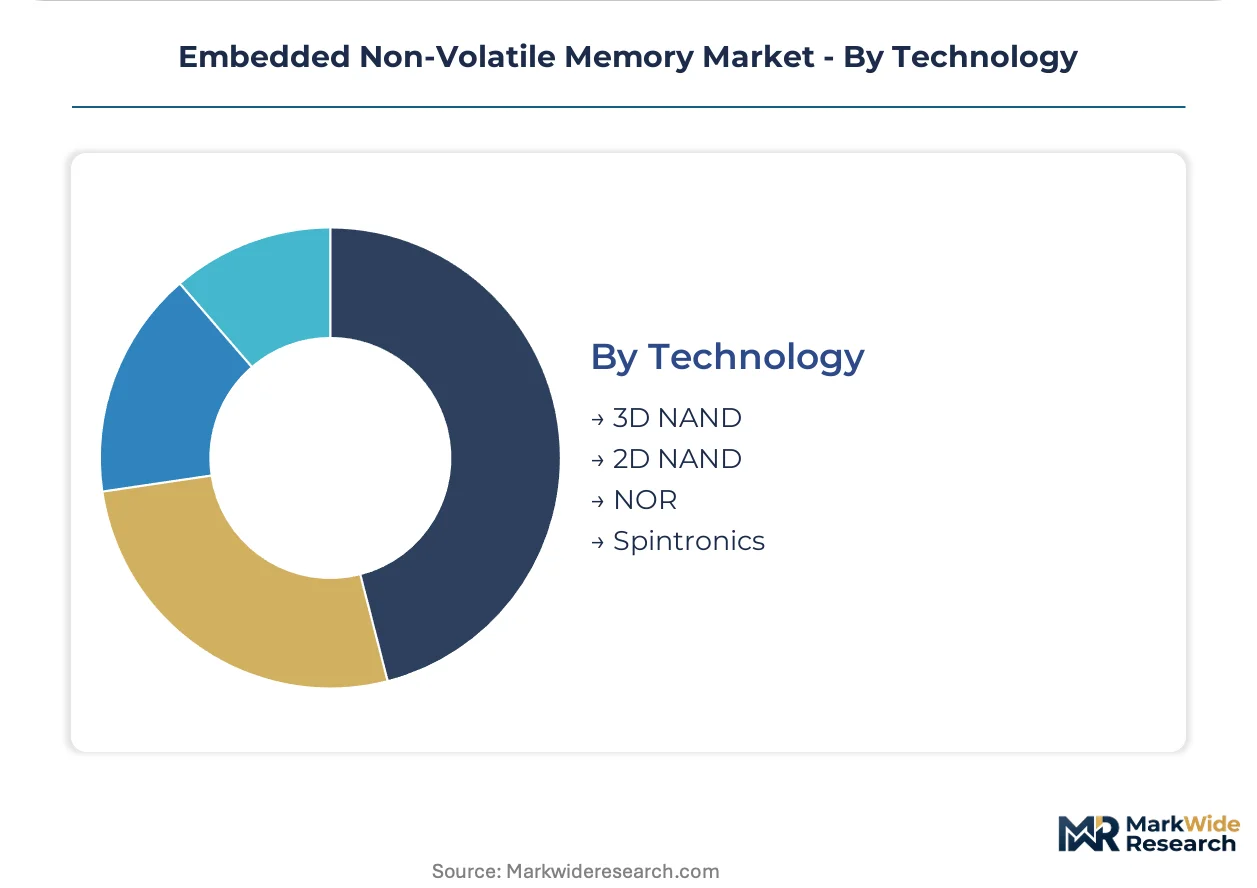
Technology:
3D NAND scaling economics have decoupled from embedded applications, creating architectural divergence between commodity storage and microcontroller-integrated solutions.
- NOR:Random-access read architecture enables direct code execution without shadow RAM. Automotive ECU designs in Germany specify parallel and serial NOR for boot loader and firmware storage.
- Spintronics:Magnetic tunnel junction devices integrate with CMOS logic at 22nm and below for AI accelerator local weight storage. Foundry R&D programs in Taiwan and the United States are co-developing process modules.
- 2D NAND:Charge-trap cells at 40nm-60nm nodes serve cost-sensitive consumer microcontroller applications with moderate endurance requirements.
- 3D NAND:Vertical stacking architectures remain confined to discrete storage products; embedded integration is precluded by process incompatibility with logic CMOS.
NOR retains the broadest embedded design-in base while spintronics climbs the fastest on AI accelerator integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes embedded NVM primarily for captive semiconductor manufacturing, while Germany and Japan drive automotive qualification demand. The United States concentrates on AI accelerator integration. China expands domestic microcontroller production. India attracts packaging investment under production-linked incentives.
South Korea
Samsung Electronics and SK Hynix anchor captive demand for embedded flash in automotive and consumer microcontrollers. The MFDS regulates medical device components indirectly affecting diagnostic equipment NVM requirements. The Seoul-Pyeongtaek semiconductor corridor hosts advanced foundry capacity for 40nm-90nm embedded memory production.
Germany
Volkswagen Group and BMW procurement specifications mandate AEC-Q100 qualified embedded NVM for centralized ECU architectures. The KBA enforces automotive cybersecurity standards elevating secure boot memory requirements. Bavaria's automotive Tier-1 supplier cluster around Munich and Ingolstadt drives qualification program expansion for 40nm embedded flash macros.
United States
AI accelerator designers at 22nm and below integrate MRAM for local weight storage in inference chips. The FDA cybersecurity guidance for connected medical devices mandates tamper-resistant embedded NVM for firmware integrity. Foundry R&D programs in California and Arizona co-develop spintronics process modules with logic CMOS integration.
Japan
Toshiba and Rohm specialize in industrial-grade embedded NVM for factory automation controllers requiring ten million-plus write cycles. METI's semiconductor strategy supports domestic production of automotive-qualified memory at mature nodes. The Nagoya-Tokyo industrial belt concentrates PLC and motion controller OEM demand for high-endurance MRAM migration.
India
Domestic microcontroller demand from white goods and automotive Tier-2 suppliers rises for firmware storage applications. The PLI scheme for semiconductor assembly and test attracts embedded NVM packaging investment. Gujarat and Karnataka host emerging packaging facilities serving regional electronics manufacturing clusters.
Embedded Non-Volatile Memory Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in embedded NVM fabrication. Captive foundry operators leverage wafer capacity security against merchant foundry process leadership at advanced nodes. Three archetypes dominate: IDMs with automotive qualification depth, pure-play foundries with lithography precision, and fabless designers with application-specific IP. Competitive moves concentrate on AEC-Q100 pre-qualification partnerships and fluorine-free process chemistry certification for EU-bound production.
Within the integrated device manufacturer tier, Samsung Electronics Co. Ltd and Infineon Technologies exemplify divergent strategic positions. Samsung represents captive supply security through in-house wafer capacity for automotive-grade flash. Infineon occupies a defensible niche in AEC-Q100 compliance specialization against commodity memory suppliers. Among foundry-based competitors, TSMC anchors advanced-node MRAM integration capabilities where precision lithography demands exceed IDM process roadmaps.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| Micron Technology, Inc. |
| TSMC |
| SK Hynix |
| Toshiba Electronic Devices & Storage Corporation |
| Western Digital Technologies, Inc. |
| Rohm Co. Ltd |
| Infineon Technologies |
| Crossbar Inc. |
| Others |
Supply Flow & Price Mechanics
Wafer-scale economies at captive foundries in South Korea and Taiwan compress unit costs for automotive-grade embedded flash while simultaneously hardening price floors for fabless competitors lacking comparable capacity utilization. This scale asymmetry concentrates margin capture among integrated device manufacturers and forces merchant suppliers to differentiate through certification premiums rather than cost parity.
Pricing Analysis
After-sales revenue from long-term firmware update contracts and field-replacement programs drives lifetime value for automotive embedded NVM suppliers. Pricing stratifies across AEC-Q100 Grade 0, Grade 1, and industrial-temperature tiers, with certification level commanding the steepest premium over die-size cost. Cost compression in consumer-grade flash is intensifying because foundry capacity allocation prioritizes automotive and industrial sockets. Consumer electronics OEMs exhibit highest price sensitivity, while German automotive Tier-1 suppliers prioritize supply security over per-unit cost.
Supply Chain Analysis
Inventory lead times for fluorinated atomic layer deposition precursors have extended following REACH restrictions on per- and polyfluoroalkyl substances. Supply concentrates in South Korea, Taiwan, and Japan for wafer fabrication, with Germany and the United States hosting automotive qualification and co-development activity. Raw material dependencies include high-purity silicon wafers, specialized etching gases, and rare-earth elements for spintronics magnetic tunnel junctions. Single-source vulnerability in fluorine-free precursor chemistry poses structural risk for EU-bound production lines. Distribution runs through direct foundry relationships for high-volume automotive contracts and specialized distributors for industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of AEC-Q100 qualified process capacity at mature nodes concentrates competitive advantage among incumbents with captive automotive certification pipelines. This capability gap limits new entrant acceleration and rewards early investment in qualification infrastructure.
For Market Incumbents: Secure dual-source validation partnerships with German and Japanese Tier-1 ECU manufacturers before design-in windows close two years ahead of volume production. Add captive capacity at 40nm-90nm nodes in South Korea or Taiwan to offset foundry allocation conflicts with power management IC demand. MRAM substitution in industrial automation represents the primary technology threat requiring defensive flash endurance roadmaps. For New Entrants and Emerging Players: AEC-Q100 fast-track programs through accredited test houses in Bavaria and Nagoya offer qualification acceleration for fabless designers lacking incumbent automotive relationships. Target India's domestic microcontroller market under PLI scheme incentives, where white goods and automotive Tier-2 demand outpaces local embedded NVM supply. Pursue FDA cybersecurity guidance compliance for connected diagnostic equipment as a go-to-market angle bypassing saturated automotive sockets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among embedded NVM suppliers with decade-long industrial design-in longevity and firmware update service contracts. Long-term viability over the next decade hinges on process node roadmap alignment with automotive ECU consolidation trends. Acquisition targets should display AEC-Q100 pre-qualification status and fluorine-free process chemistry certification for EU-bound production. Watch for inflection when South Korean factory automation OEMs complete MRAM qualification for PLC replacement cycles at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Process Chemistry Certification | EU F-Gas Regulation compliance unlocks automotive supply contracts bound for European OEMs. |
| AEC-Q100 Pre-Qualification Partnership | German Tier-1 procurement specifications mandate second-source validation before design-in approval. |
| MRAM-Logic CMOS Co-Development | Taiwanese and US foundry R&D programs target AI accelerator local weight storage at 22nm. |
| India Packaging Facility Investment | PLI scheme incentives attract embedded NVM assembly and test capacity for regional microcontroller demand. |
| Secure Boot Architecture Integration | FDA cybersecurity guidance elevates tamper-resistant embedded NVM requirements for US diagnostic equipment. |
Methodological Framework
Cross-validation between primary interviews with automotive platform engineers, foundry process integration specialists, and industrial automation procurement managers anchors the qualitative findings. Secondary sources include SEC semiconductor filings, customs wafer trade data, AEC component qualification databases, and EU regulatory chemistry restriction notices. Bottom-up segment sizing triangulates against top-down foundry capacity allocation estimates from equipment supplier disclosures.
Sensitivity analysis around mature node capacity utilization rates and automotive ECU consolidation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include memory technology type, application vertical, process node tier, and geographic regulatory cluster. CAGRs derive from wafer start projections and content-per-vehicle trajectories for centralized vehicle architectures. Industry-specific inputs capture MRAM endurance qualification progress and fluorinated precursor supply quota rationing effects.
The analysis sits within stated boundaries; outcomes outside sustained automotive semiconductor demand or accelerated REACH chemistry substitution would require recalibration. Forecasts reflect documented assumptions about foundry capacity expansion and regulatory phase-down schedules. Technology substitution risk from MRAM and PCRAM convergence, alongside geopolitical disruption to South Korean wafer supply, constitute primary revision factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Japan DRAM Market
Memory Chips
Automotive Memory Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
DDR SDRAM Market
Memory Chips
Memory Module Market
Memory Chips
MRAM Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Mobile DRAM Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Smartphone RAM Market
Memory Chips
Japan Flash Memory Market
Memory Chips
eMMC Master Control Chip Market