
 Global Ureteral Stent Market | 2026-2036
Global Ureteral Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ureteral Stent Market Foresight
Biocompatibility-grade polymer specifications is unwinding competitive positioning across the ureteral stent landscape. Boston Scientific Corporation leverages its polymer science capabilities to sustain premium positioning in hydrogel-coated platforms. Cook Medical LLC anchors its presence through specialized urological portfolios with deep procedural integration. Olympus Corporation differentiates via endoscopic ecosystem control that bundles stent placement with imaging systems.
A ureteral stent is a thin, hollow tube inserted into the ureter to restore or maintain urine flow from the kidney to the bladder, typically manufactured from polymers such as polyurethane or silicone with diameters ranging from 4.7 Fr to 8 Fr and lengths from 12 cm to 30 cm depending on patient anatomy. Double-J stents retain the largest installed base due to their universal compatibility with standard cystoscopic placement, while hydrogel-coated variants command margin premiums through reduced encrustation and patient discomfort. Metal stents occupy a narrow but structurally important niche in malignant obstruction cases where tissue ingrowth resistance proves critical.
FDA 510(k) clearance pathways govern US market entry for polymer stents, while the EU MDR demands expanded clinical evidence for implantable devices including biocompatibility testing under ISO 10993 standards. Japan's PMDA maintains distinct material qualification requirements that shape regional product configurations. Stakeholders must monitor how evolving antimicrobial coating claims trigger new regulatory evidentiary thresholds across FDA, EMA, and PMDA jurisdictions.
Market Dynamics
Biocompatibility documentation burdens under EU MDR are compressing vendor margins while accelerating polymer specification differentiation among implantable device manufacturers.
Growth Catalysts
- Minimally invasive procedure preference:Urology departments in hospital systems are expanding stent placement volumes as laparoscopic and endoscopic techniques replace open surgical interventions for stone disease management.
- ISO 10993 biocompatibility frameworks:Standardized testing protocols for polymer-based implants are creating regulatory clarity that accelerates product development cycles for hydrogel-coated platforms.
- Japan:Aging demographics and rising stone disease prevalence are sustaining procedural growth in tertiary care centers across the archipelago.
Market Restraints
- Polymer raw material concentration:Medical-grade polyurethane and silicone supply chains concentrate among a limited cohort of specialty chemical producers in Germany and the United States.
- EU MDR clinical evidence expansion:The regulation demands expanded biocompatibility documentation for implantable devices, extending time-to-market and inflating regulatory compliance costs.
- Metal stent substitution ceiling:Polymer platforms face structural limitations in malignant obstruction cases where tissue ingrowth resistance proves critical.
Strategic Opportunities
- Antimicrobial coating claims:Evidentiary thresholds for antimicrobial efficacy across FDA, EMA, and PMDA jurisdictions create first-mover advantage for coating technology specialists.
- India:Underpenetrated urological service infrastructure in secondary cities presents volume expansion potential for standard double-J stent configurations.
- Endoscopic ecosystem bundling:Convergence of stent placement devices with imaging and lithotripsy systems enables procedural workflow capture in integrated surgical suites.
Industry Challenges
- Polymer science talent scarcity:Formulation chemistry expertise for hydrogel coating development concentrates among a narrow pool of specialists with medical device commercialization experience.
- 510(k) predicate device navigation:FDA clearance pathways require careful predicate selection to avoid de novo classification, compressing product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ureteral Stent Market |
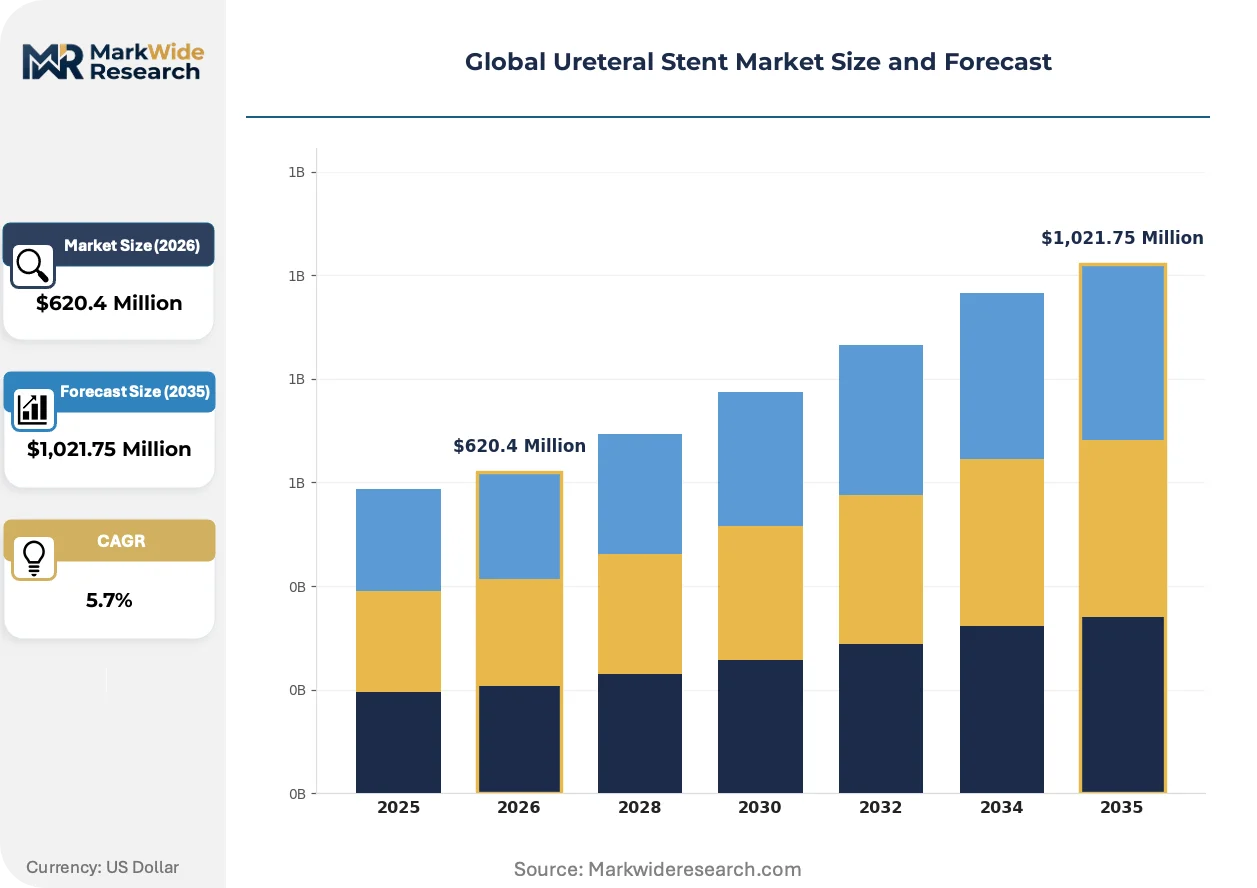
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $1,021.75 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-J Stents, Percutaneous Stents, Resonance Stents, Hydrogel-coated Stents, Metal Stents Application: Urinary Tract Obstruction, Ureteral Strictures, Kidney Stones Management, Postoperative Drainage, Tumor-Related Obstruction End User: Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Medical Research Institutes, Urology Departments Material: Polyurethane, Silicone, Polyethylene, Cobalt-Chromium Alloy, Polymer Composite |
| Companies Covered | B. Braun Melsungen AG, Becton, Dickinson and Company, Boston Scientific Corporation, Merit Medical Systems, Inc., Olympus Corporation, Coloplast A/S, Teleflex Incorporated, Allium Medical Solutions Ltd., Cook Medical LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ureteral Stent Market Shifts & Advancements
Active coating technologies and procedural integration strategies are restructuring how ureteral stent value is captured across manufacturer, provider, and payer relationships.
Hydrogel-coated polymer formulations are supplanting bare polyurethane stents in premium hospital accounts. Academic medical centers in the United States and Western Europe are adopting coated platforms at accelerating pace to reduce encrustation-related complications and emergency department revisits. This technology migration is compressing margin structures for commodity stent producers while elevating polymer science capabilities to primary competitive differentiator status.
EU MDR biocompatibility documentation requirements are tightening evidentiary standards for implantable polymer devices. Manufacturers must now submit expanded clinical data packages and ISO 10993 testing matrices that were previously unnecessary under the Medical Device Directive. Small and mid-cap stent specialists without dedicated regulatory affairs infrastructure are outsourcing compliance functions or exiting the European market entirely.
Hospital procurement departments are consolidating stent purchasing through integrated delivery network contracts that bundle urological consumables across multiple procedure categories. Group purchasing organizations are displacing individual hospital negotiations in the United States, while NHS Supply Chain centralization performs analogous concentration in the United Kingdom. This channel shift is most visible in high-volume stone disease corridors where procedural standardization enables volume-based pricing agreements.
Global Ureteral Stent Market Segmentation
Ureteral stent procurement patterns diverge sharply across clinical settings and material specifications. Manufacturers must align polymer science capabilities with end-user workflow requirements to capture value across fragmented hospital and ambulatory channels.
Product Type:
Double-J and hydrogel-coated platforms dominate domestic hospital procurement in the United States and Western Europe, while metal stent demand concentrates in tertiary oncology centers across Japan and Germany.
- Double-J Stents:These polyurethane or silicone tubes with coiled retention ends at both extremities constitute the universal standard for routine stone disease management. Demand concentrates in high-volume urology departments across the United States, where standardized cystoscopic placement protocols minimize operator training burden and inventory complexity.
- Hydrogel-coated Stents:Polymer formulations with hydrophilic surface layers reduce encrustation rates and patient discomfort during dwell periods. Academic medical centers in Germany and the United Kingdom are migrating toward coated platforms to lower emergency department revisit rates and justify premium reimbursement.
- Metal Stents:Cobalt-chromium or nitinol constructs resist tissue ingrowth in malignant obstruction cases. Tertiary oncology centers in Japan and Switzerland deploy these for extended indwelling periods where polymer degradation risks exceed tolerance.
- Percutaneous Stents:Larger-caliber tubes inserted via nephrostomy access support antegrade drainage when retrograde cystoscopic placement fails. Interventional radiology departments in France and the United States maintain specialized inventories.
- Resonance Stents:Metallic mesh designs with radial force optimization occupy narrow indications for complex stricture anatomy. Limited adoption concentrates in specialized reconstructive urology centers.
Double-J stents hold the largest share; momentum sits with hydrogel-coated platforms.
Application:
Cost tier stratification separates commodity stone management from premium oncologic interventions, with reimbursement intensity tracking clinical complexity.
- Kidney Stones Management:Elective stent placement following ureteroscopic lithotripsy or as temporizing therapy for obstructing calculi. High procedural volumes in ambulatory surgical centers across the United States sustain economies of scale for standard polymer platforms.
- Tumor-Related Obstruction:Malignant extrinsic compression from gynecologic, colorectal, or urologic neoplasms demands stent durability exceeding polymer capabilities. University hospitals in Switzerland and the Netherlands deploy metal constructs with extended dwell protocols.
- Urinary Tract Obstruction:Benign prostatic hyperplasia, pregnancy, or congenital anomalies drive retrograde drainage requirements. Community hospitals in India and Brazil manage these cases with cost-optimized double-J configurations.
- Ureteral Strictures:Iatrogenic or inflammatory narrowing necessitates graduated dilation with sequential stent exchanges. Reconstructive urology specialists in Italy and South Korea maintain dedicated stricture management protocols.
- Postoperative Drainage:Temporary diversion following ureteral reimplantation, pyeloplasty, or trauma repair. Tertiary centers in Canada and Australia standardize dwell duration protocols to minimize stent-related morbidity.
Kidney stones management commands the greatest volume; tumor-related obstruction claims the steepest expansion trajectory as oncologic stenting protocols mature.
End User:
Customer type fragmentation creates channel conflict between integrated delivery networks and independent specialty practices.
- Urology Departments:Hospital-based divisions with dedicated endoscopic suites and fellowship-trained faculty. United States academic medical centers drive technology adoption for coated platforms through value-based care contracts.
- Ambulatory Surgical Centers:Freestanding facilities performing same-day ureteroscopy and stent placement. Medicare reimbursement shifts in the United States are accelerating case migration to this lower-cost setting.
- Specialty Clinics:Independent urology practices with office-based cystoscopy capabilities. Germany's outpatient reimbursement framework supports substantial stent placement volume outside hospital walls.
- Diagnostic Laboratories:Limited direct stent utilization; occasional participation in retrieval and analysis of encrusted specimens for metabolic stone workup.
- Medical Research Institutes:Academic centers conducting coating technology trials and comparative effectiveness studies. University hospitals in Sweden and Denmark contribute disproportionately to clinical evidence generation.
Urology departments retain the largest share; ambulatory surgical centers are climbing the fastest as site-of-service economics reshape procedural distribution.
Material:
Supply concentration among German and American specialty chemical producers dictates regional material availability and formulation customization.
- Polyurethane:Segmental durometer variations enable proximal stiffness for pushability with distal flexibility for patient comfort. Medical-grade suppliers in Germany and the United States control specification certification for implantable grades.
- Silicone:Lower tissue reactivity and reduced encrustation propensity support long-dwell applications. Japanese PMDA material qualification requirements create distinct regional formulation standards.
- Polyethylene:Cost-optimized alternative for emerging market price sensitivity. Indian and Brazilian manufacturers specify lower-durometer grades for domestic production.
- Cobalt-Chromium Alloy:Radial strength and fatigue resistance for permanent or semi-permanent malignant obstruction management. Swiss and German metallurgical specialists dominate precision tube drawing capabilities.
- Polymer Composite:Experimental formulations incorporating drug-elution or biodegradability. Early clinical investigation concentrates in Netherlands and Belgian university hospitals.
Polyurethane holds the largest share; polymer composite formulations are gaining share fastest through active coating integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ureteral stent trade flows reflect a pronounced import dependency in emerging markets alongside concentrated polymer supply from German and American chemical producers. Export volumes track procedural sophistication, with premium-coated platforms flowing toward academic medical centers in high-income economies.
United States
Aging demographics and stone disease prevalence sustain procedural growth across tertiary care centers. FDA 510(k) clearance pathways govern market entry for polymer stents, with antimicrobial coating claims triggering elevated evidentiary requirements. Boston Scientific Corporation anchors polymer science capabilities in Massachusetts, while Medicare reimbursement shifts accelerate case migration to ambulatory surgical centers in Florida and Texas.
Germany
EU MDR biocompatibility documentation demands compress vendor margins while accelerating regulatory specialization. EMA oversight of implantable devices requires expanded ISO 10993 testing matrices that were unnecessary under prior directives. Cook Medical LLC maintains deep procedural integration from its Bavarian operational footprint, supplying coated platforms to university hospitals across Baden-Württemberg and North Rhine-Westphalia.
Japan
PMDA material qualification requirements create distinct regional formulation standards for silicone-based platforms. Aging populations in Tokyo and Osaka metropolitan areas drive sustained stent placement volumes in tertiary oncology centers. Olympus Corporation bundles stent placement with endoscopic imaging systems, capturing procedural workflow in Kansai region integrated surgical suites.
India
Underpenetrated urological service infrastructure in secondary cities presents volume expansion potential for standard double-J configurations. CDSCO regulates implantable polymer devices through centralized licensing frameworks that lengthen import approval timelines. Domestic manufacturers in Maharashtra and Gujarat specify lower-durometer polyethylene grades for cost-optimized production targeting community hospitals.
Switzerland
Swissmedic oversight maintains stringent biocompatibility standards for implantable devices that align with EU MDR convergence timelines. Tertiary oncology centers in Zurich and Geneva deploy metal stent constructs for malignant obstruction cases requiring extended indwelling periods. Precision metallurgical specialists in Basel control cobalt-chromium tube drawing capabilities for premium oncologic applications.
Global Ureteral Stent Market Competitive Landscape
Listed leaders compete with private specialists across polymer science capabilities and regulatory infrastructure. The vendor base stratifies between scale-driven multinationals with integrated coating laboratories and mid-cap specialists outsourcing biocompatibility documentation. Three archetypes dominate: diversified medtech conglomerates with urological portfolios, endoscopic ecosystem integrators bundling imaging with consumables, and regional polymer specialists serving price-sensitive emerging markets. Competitive moves concentrate on M&A for coating technology access and strategic partnerships with academic medical centers for clinical evidence generation.
Within the diversified medtech tier, B. Braun Melsungen AG and Becton, Dickinson and Company exemplify scale-driven players with broad hospital system relationships. Among endoscopic ecosystem specialists, Olympus Corporation occupies a position integrating stent placement with imaging and lithotripsy systems. Cook Medical LLC represents the private specialist archetype with deep procedural integration in urological workflows.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Merit Medical Systems, Inc. |
| Olympus Corporation |
| Coloplast A/S |
| Teleflex Incorporated |
| Allium Medical Solutions Ltd. |
| Cook Medical LLC |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates both polymer supplier qualification and hospital procurement tiering, compressing margin structures for uncertified producers while elevating premium pricing power for coating-technology leaders. This regulatory threshold simultaneously restricts raw material sourcing pools and stratifies end-product pricing across academic medical centers and community hospitals.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers. Hydrogel-coated platforms command reimbursement premiums through reduced encrustation complications, while bare polyurethane configurations face cost compression from group purchasing organization consolidation. Academic medical centers in the United States exhibit lowest price sensitivity due to value-based care contracts; ambulatory surgical centers in Florida and Texas drive hardest bargain for commodity double-J stents.
Supply Chain Analysis
Germany and the United States anchor medical-grade polyurethane and silicone production for implantable device grades. Specialty chemical producers in Bavaria and Massachusetts control specification certification, with Japanese PMDA standards creating distinct regional formulation requirements. Single-source vulnerability concentrates in hydrogel coating precursor supply, with tariff exposure on Chinese-sourced active pharmaceutical ingredients for antimicrobial variants. Distribution runs through integrated delivery network contracts that bundle urological consumables across procedural categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscopic ecosystem convergence is restructuring value capture around procedural workflow control rather than discrete device transactions, with imaging-lithotripsy-stent bundling creating platform lock-in effects across integrated surgical suites.
For Market Incumbents: Fortify polymer science capabilities through captive coating laboratory investment or specialist acquisition to defend against hydrogel technology commoditization. Deepen vertical integration into medical-grade silicone supply chains to mitigate German and American chemical producer concentration risk. Secure long-term ISO 10993 testing partnerships to accelerate EU MDR compliance velocity relative to mid-cap competitors.
For New Entrants and Emerging Players: Antimicrobial coating evidentiary gaps in FDA and PMDA pathways present white-space opportunity for specialist coating technology developers. India's underpenetrated secondary city urological infrastructure offers most penetrable geography for cost-optimized polyethylene double-J configurations. Pursue hospital system partnership models that bundle stent supply with training and inventory management services.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogel coating manufacturing as cleanroom and analytical chemistry infrastructure requirements expand. Target acquisition archetype: mid-cap stent specialists with established EU MDR technical documentation and stranded regulatory assets. Monitor antimicrobial coating FDA submission volumes as inflection indicator for competitive intensity in premium segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Acquisition | Captures hydrogel formulation expertise that accelerates EU MDR biocompatibility dossier completion. |
| Hospital System Partnership | Locks in ambulatory surgical center volume through procedural workflow integration and training commitments. |
| Antimicrobial Coating FDA Submission | Establishes first-mover evidentiary position for infection-resistance claims in premium stent tiers. |
| Backward Integration into Polymer Supply | Reduces dependency on German and American specialty chemical producers for medical-grade silicone. |
| Reimbursement Strategy Development | Aligns stent dwell duration protocols with CMS value-based care metrics to justify coated platform premiums. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation repositories, and hospital procurement contract disclosures preceded structured interviews with urology department chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at polymer implant manufacturers. Secondary validation drew from ISO 10993 testing laboratory publications, academic medical center purchasing committee minutes, and trade flow customs records. Bottom-up procedural volume estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, application indication, end-user facility tier, and material specification informed analytical framework construction across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic healthcare expenditure trajectories. Modeled inputs incorporated stone disease epidemiology shifts, ambulatory surgical center case migration rates, and antimicrobial coating regulatory evidentiary thresholds.
Underlying assumptions cover stable EU MDR implementation timelines and sustained Medicare reimbursement for outpatient urological procedures, with deviation risk concentrated in antimicrobial coating claim rejections and polymer raw material supply disruptions. Recalibration cycles align with material shifts in regulatory evidentiary requirements and hospital procurement centralization momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Respiratory Devices Market
Medical Devices
Bariatric Beds Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Global Casting Devices Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Toe Fixation System Market