
 Global Emerging Mental Health Devices and Platforms Market | 2026-2036
Global Emerging Mental Health Devices and Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emerging Mental Health Devices and Platforms Market Foresight
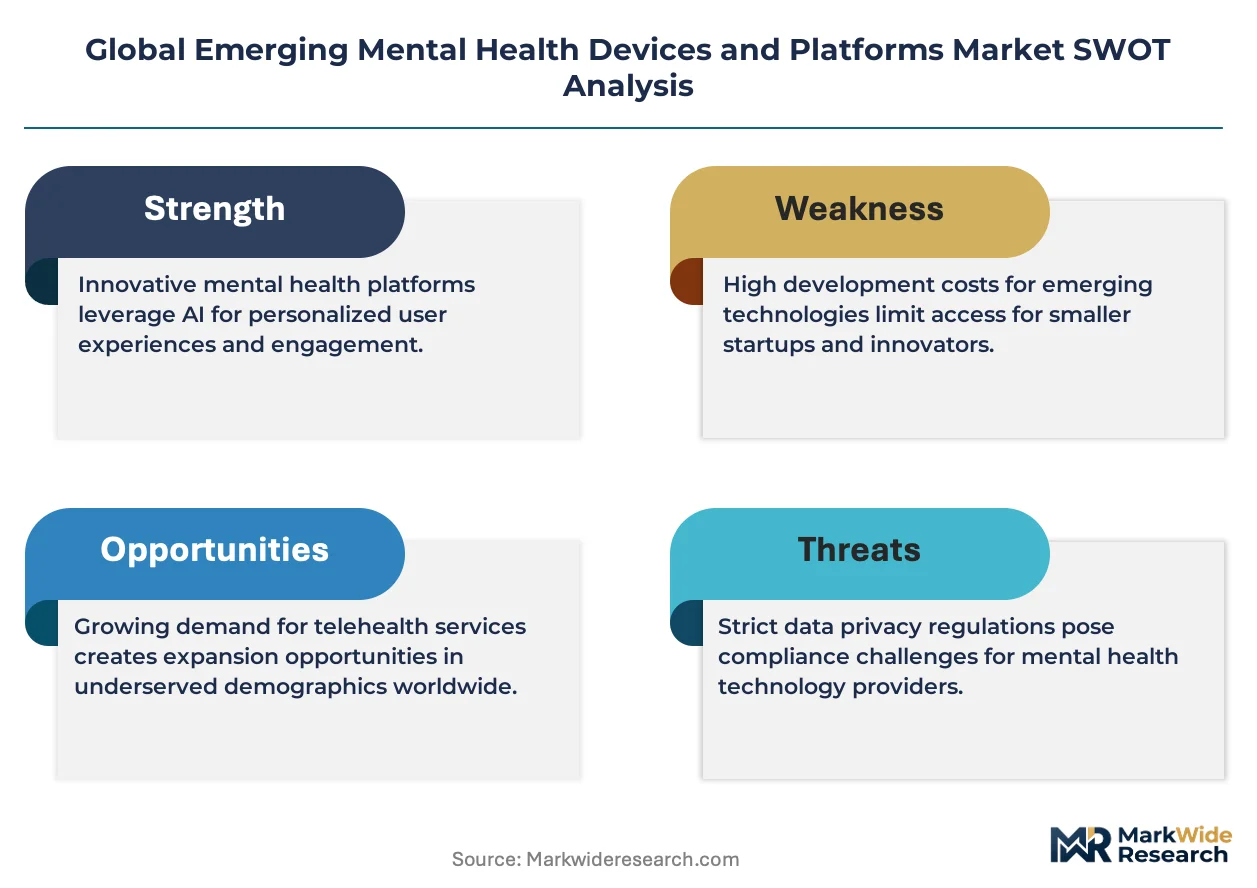
The FDA's software-as-a-medical-device framework is restructuring the cost-of-entry calculus for mental health technology developers. Pear Therapeutics navigates this terrain through prescription digital therapeutics that require clinical trial validation. Talkspace leverages its direct-to-consumer channel to sustain subscriber growth outside traditional reimbursement pathways. Calm anchors its position through employer partnerships that bypass regulatory complexity entirely.
Global Emerging Mental Health Devices and Platforms encompass sensor-integrated hardware and software systems that measure physiological markers such as heart rate variability, electroencephalography patterns, and sleep architecture to deliver personalized behavioral interventions. These systems serve clinical and subclinical populations seeking scalable alternatives to conventional psychotherapy delivery. Wearable monitors occupy the largest installed base among product types, while VR therapy devices represent the fastest-expanding category due to immersive exposure therapy applications. AI-enabled diagnostics command premium pricing through predictive risk stratification capabilities, whereas cloud-based platforms compete on deployment speed and interoperability.
The FDA, EMA, and WHO each impose distinct evidentiary standards on mental health technologies, with the FDA requiring randomized controlled trials for prescription claims while the WHO emphasizes accessibility metrics in low-resource settings. This regulatory fragmentation forces developers to architect modular compliance strategies that accommodate multiple jurisdiction requirements. Stakeholders must monitor evolving reimbursement codes for digital therapeutics, as payer acceptance will determine whether platform economics shift from direct consumer payment to institutional contracting.
Market Dynamics
Corporate wellness procurement is consolidating around platform-based mental health solutions, compressing vendor selection cycles and elevating interoperability requirements above standalone clinical efficacy claims.
Growth Catalysts
- Employer Mandate Expansion:United States employers now treat behavioral health benefits as standard compensation components, creating institutional procurement channels that bypass consumer adoption friction entirely.
- Prescription Digital Therapeutics Pathway:The FDA's evolving software-as-a-medical-device framework is legitimizing clinically validated interventions through reimbursement code expansion.
- Wearable Sensor Maturation:Photoplethysmography and accelerometer miniaturization is enabling continuous physiological monitoring at consumer price points.
Market Restraints
- Clinical Validation Burden:Randomized controlled trial requirements for prescription claims impose development timelines that exclude capital-constrained entrants.
- Data Localization Requirements:The EU's GDPR and emerging national privacy frameworks fragment cloud infrastructure strategies, raising compliance costs for platform operators.
- Substitution by Generic Mindfulness Apps:Free or low-cost meditation applications capture subclinical demand, compressing pricing power for condition-specific therapeutic platforms.
Strategic Opportunities
- VR Exposure Therapy:Immersive hardware combined with cognitive behavioral protocols is penetrating anxiety and PTSD treatment where traditional exposure methods face patient resistance.
- Japan's Aging Demographics:METI initiatives targeting elderly mental health monitoring create demand for passive sensing systems that reduce caregiver burden.
- AI-Enabled Risk Stratification:Predictive algorithms applied to electronic health records are opening preventive intervention markets prior to acute episode onset.
Industry Challenges
- Interoperability Standards Gap:Absence of universal data exchange protocols between wearable devices, electronic health records, and platform dashboards forces expensive custom integration work.
- Behavioral Health Credentialing:Shortage of licensed practitioners qualified to oversee digital therapeutic delivery is constraining platform scale-up in regulated jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emerging Mental Health Devices and Platforms Market |
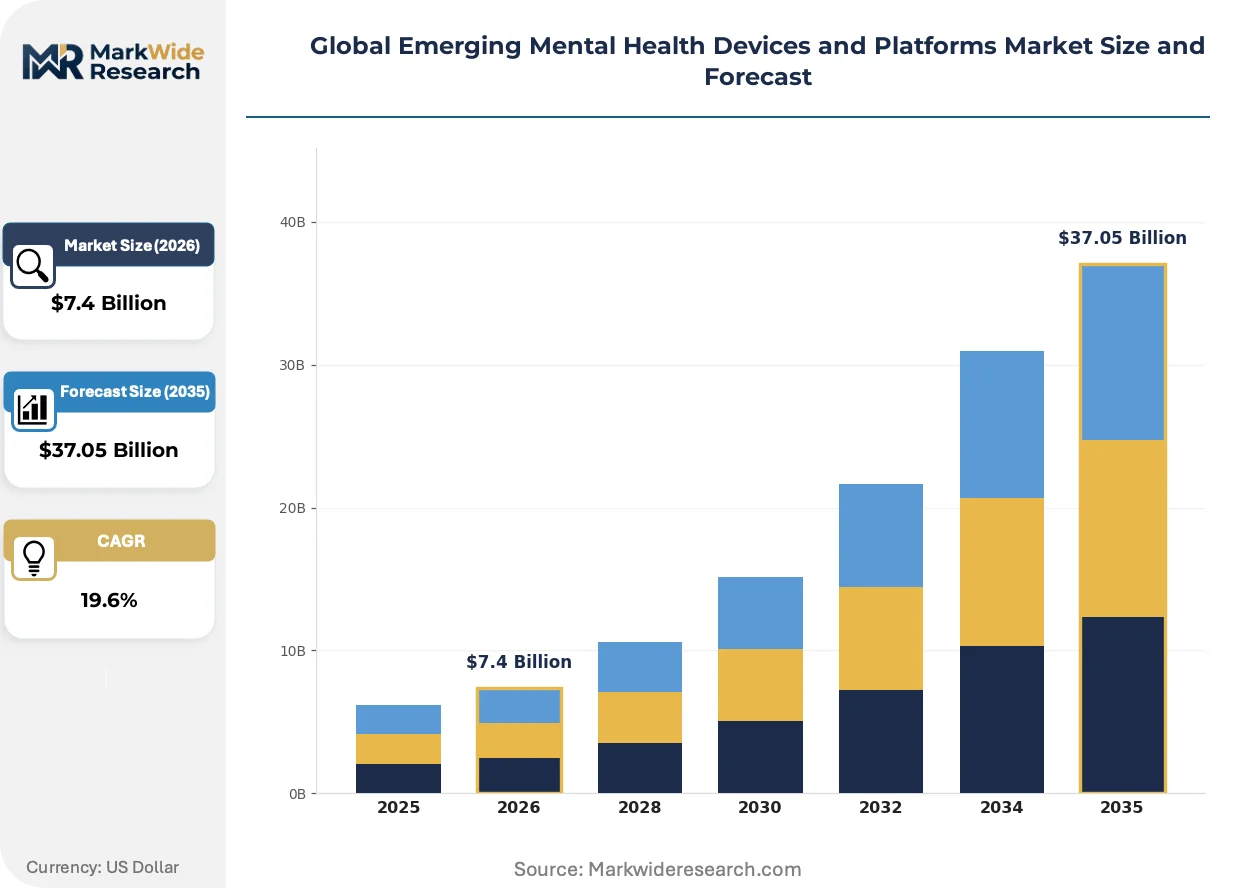
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $37.05 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurofeedback Systems, Wearable Monitors, VR Therapy Devices, Mobile Applications Technology: AI-Enabled Diagnostics, Cloud-Based Platforms, Biofeedback Sensors, Cognitive Behavioral Algorithms Application: Stress Management, Anxiety Treatment, Depression Monitoring, Sleep Disorder Therapy End User: Psychologists, Teletherapy Providers, Rehabilitation Centers, Corporate Wellness Programs |
| Companies Covered | Headspace Inc., Talkspace, Electromedical Products International, Inc., Happify Health, Calm, Lyra Health, Inc., Ginger, Pear Therapeutics, Inc., AbleTo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emerging Mental Health Devices and Platforms Market Shifts & Advancements
Sensor miniaturization and algorithmic personalization are converging to displace episodic clinical assessment with continuous, ambient mental health monitoring embedded in consumer electronics.
Edge computing architectures are decentralizing physiological data processing from cloud servers to wearable devices and smartphones. Consumer electronics manufacturers are embedding dedicated neural processing units at accelerating cadence. This shift is compressing latency for real-time biofeedback interventions while reducing platform operators' infrastructure costs and exposure to data sovereignty restrictions.
The FDA's Breakthrough Devices Program is accelerating review timelines for digital therapeutics targeting serious conditions. Developers are restructuring clinical trial designs to capture real-world evidence through platform usage data. Prescription digital therapeutic categories are attracting venture funding that direct-to-consumer wellness applications cannot match.
Self-insured employers are unbundling mental health benefits from traditional health plans and contracting directly with platform providers. Human resources departments are consolidating vendor relationships around integrated employee assistance and chronic condition management offerings. This concentration is visible most acutely in the United States, where large employers command sufficient scale to negotiate outcome-based pricing arrangements.
Global Emerging Mental Health Devices and Platforms Market Segmentation
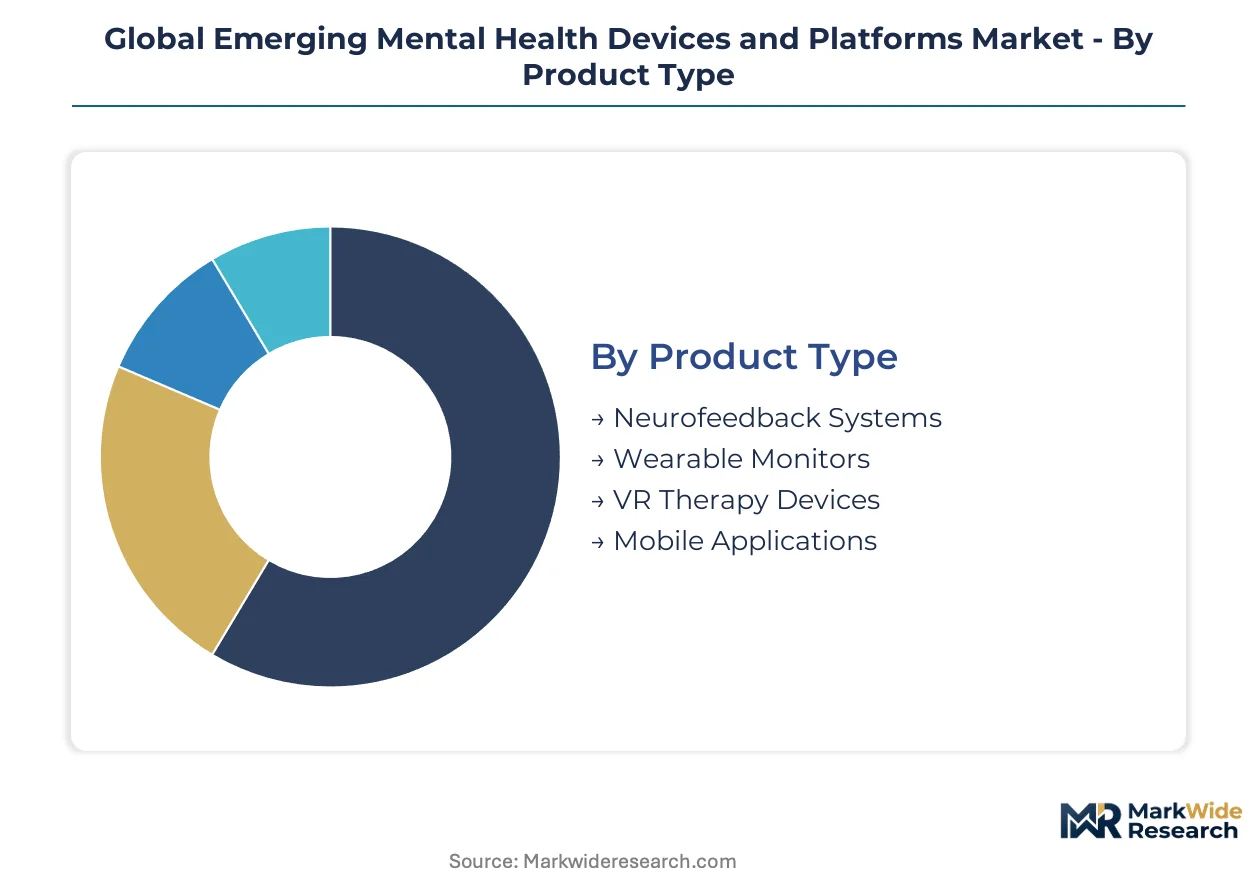
Segmentation in mental health technology reveals divergent commercial logics across hardware, software, and service delivery models. Each dimension carries distinct regulatory burdens, pricing power, and scalability constraints that reshape competitive boundaries.
Product Type:
Supply concentration in hardware manufacturing favors vertically integrated producers of sensor arrays and display systems, while software platforms fragment across specialized development shops.
- Neurofeedback Systems:Electroencephalography-based training platforms requiring clinical-grade amplifiers and real-time signal processing hardware. Demand concentrates in United States rehabilitation centers where FDA 510(k) clearance supports insurance reimbursement, though capital intensity limits entrant proliferation.
- Wearable Monitors:Photoplethysmography and accelerometer-embedded wristbands and rings enabling continuous heart rate variability tracking. United States corporate wellness programs drive procurement volume, with employers favoring devices that integrate with existing benefits administration systems.
- VR Therapy Devices:Head-mounted displays paired with exposure therapy software protocols.
- Mobile Applications:Smartphone-delivered interventions spanning meditation, mood tracking, and cognitive behavioral exercises.
Today's leader: Wearable Monitors. Tomorrow's challenger: VR Therapy Devices.
Technology:
Cost tier stratification separates premium-priced predictive diagnostics from commoditized cloud infrastructure, with middleware algorithms occupying contested middle ground.
- AI-Enabled Diagnostics:Machine learning models applied to voice biomarkers, facial expression analysis, and electronic health record patterns for risk stratification. United States academic medical centers and payers command premium pricing for predictive capabilities that reduce hospitalization rates.
- Cloud-Based Platforms:Scalable software-as-a-service architectures hosting therapy content, patient portals, and clinician dashboards. Teletherapy providers in the United States and Germany absorb deployment costs through per-seat licensing models that favor multi-tenant efficiency.
- Biofeedback Sensors:Peripheral hardware capturing galvanic skin response, blood oxygen saturation, and temperature variation.
- Cognitive Behavioral Algorithms:Structured intervention protocols encoded as adaptive digital programs.
AI-Enabled Diagnostics command margin premiums. Cloud-Based Platforms scale fastest.
Application:
Volume distribution tracks prevalence and reimbursement generosity, with anxiety and depression commanding largest addressable populations while sleep disorders attract consumer-direct payment.
- Stress Management:Subclinical interventions targeting workplace burnout and lifestyle optimization through mindfulness and relaxation protocols. United States employer-sponsored programs represent the dominant procurement channel, bypassing medical necessity documentation requirements.
- Anxiety Treatment:Condition-specific platforms incorporating exposure hierarchies, cognitive restructuring, and pharmacotherapy adjuncts. United States and United Kingdom health systems reimburse clinically validated digital therapeutics, concentrating demand among FDA and NICE-approved offerings.
- Depression Monitoring:Longitudinal symptom tracking and intervention adjustment for major depressive disorder.
- Sleep Disorder Therapy:Circadian rhythm alignment and insomnia-specific cognitive behavioral protocols.
Anxiety Treatment captures institutional budgets. Stress Management scales through direct-to-consumer channels.
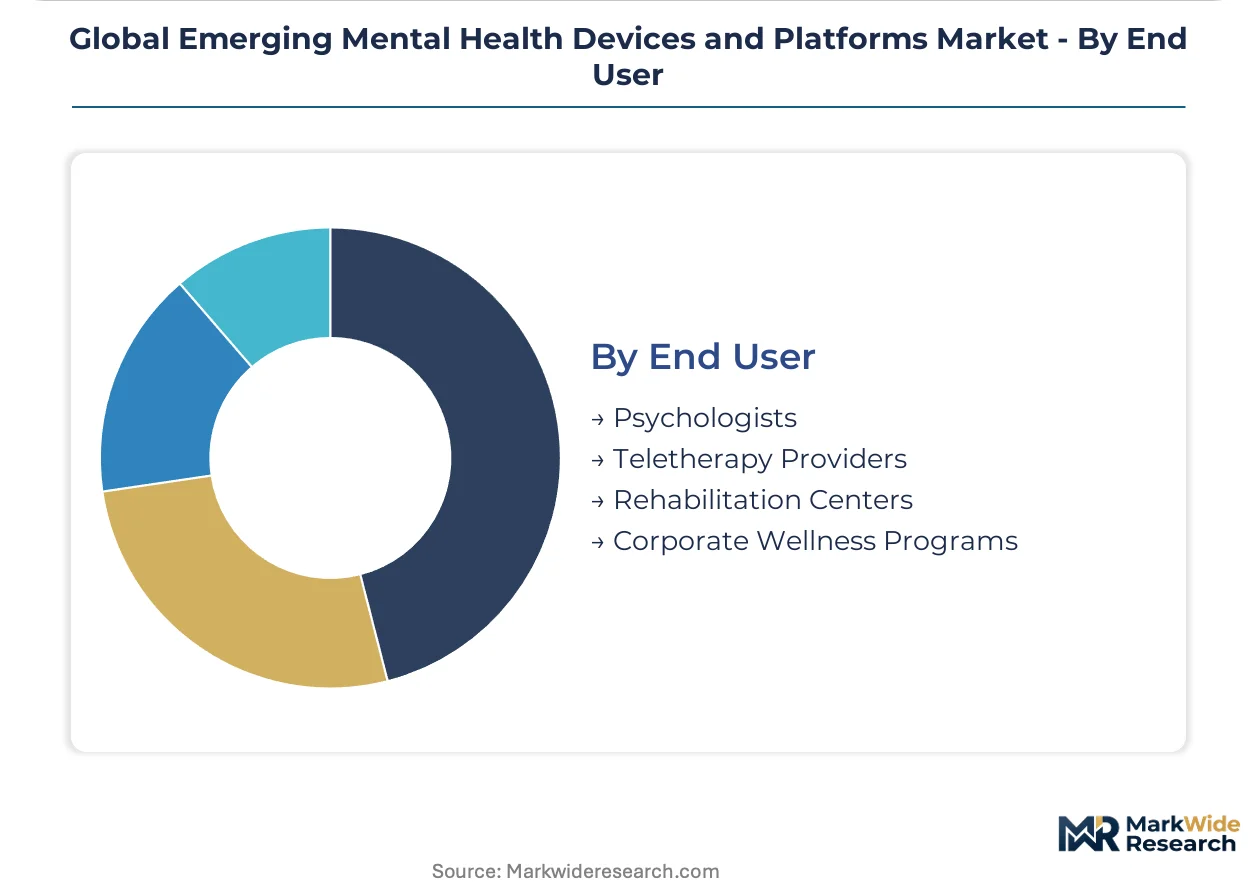
End User:
Customer type determines regulatory exposure and contract structure, with licensed practitioners facing credentialing requirements that corporate buyers circumvent.
- Psychologists:Licensed practitioners integrating digital tools into face-to-face or telehealth practice, requiring HIPAA-compliant platforms with clinical workflow integration. United States state licensing boards impose supervision requirements that constrain platform selection to established vendors.
- Teletherapy Providers:Scalable virtual care organizations purchasing enterprise licenses for therapist-guided digital interventions. United States-based platforms dominate procurement through network effects and payer contracting relationships.
- Rehabilitation Centers:Inpatient and outpatient facilities deploying hardware-intensive neurofeedback and biofeedback systems.
- Corporate Wellness Programs:Human resources departments procuring population-level mental health benefits for employee assistance and resilience training.
Corporate Wellness Programs drive volume aggregation. Teletherapy Providers demand clinical validation depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mental health technology industry traces its commercial origins to United States employer-sponsored wellness programs and FDA-regulated prescription digital therapeutics, with early platform development concentrated in Silicon Valley and Boston healthcare corridors before spreading to European and Asian markets.
United States
Corporate wellness procurement and prescription digital therapeutics reimbursement dominate demand generation. The FDA's software-as-a-medical-device framework and Breakthrough Devices Program structure regulatory pathways for clinical validation. The San Francisco Bay Area and Greater Boston anchor platform development clusters, with venture capital concentration supporting Pear Therapeutics and Talkspace headquarters operations.
Germany
Statutory health insurance reimbursement for digital health applications and industrial mental health programs drive institutional procurement. The BfArM's DiGA fast-track approval process accelerates market access for validated interventions. Berlin and Munich host teletherapy platform development centers, with corporate wellness integration expanding through Mittelstand employer networks.
United Kingdom
NHS Digital and NICE technology appraisals shape reimbursement decisions for mental health platforms. The MHRA's evolving guidance on software medical devices parallels FDA frameworks with accelerated access pathways. London concentrates teletherapy provider headquarters and health technology venture capital, while Manchester hosts NHS innovation testbeds for platform deployment.
Japan
METI initiatives targeting elderly mental health monitoring and workplace stress reduction create demand for passive sensing systems. The PMDA's regulatory harmonization with FDA standards facilitates cross-border platform development. Tokyo and Osaka anchor corporate wellness procurement decisions, with Kanagawa Prefecture hosting pilot programs for AI-enabled diagnostic integration.
Australia
Medicare reimbursement expansion for telehealth mental health services and rural healthcare access programs drive platform adoption. The TGA's software medical device framework requires clinical evidence proportionate to risk classification. Sydney and Melbourne concentrate digital health startup ecosystems, with Queensland hosting regional deployment programs for remote patient monitoring.
Global Emerging Mental Health Devices and Platforms Market Competitive Landscape
The competitive structure tilts toward platform-based service providers over hardware manufacturers, with corporate wellness procurement concentrating contract volumes among integrated solution vendors. Three archetypes dominate: prescription digital therapeutic developers pursuing FDA validation, direct-to-consumer wellness applications scaling through employer channels, and teletherapy platforms combining human clinicians with digital tools. Consolidation pressure manifests through strategic partnerships between sensor manufacturers and platform operators, alongside geographic expansion into reimbursement-favorable jurisdictions.
Among United States-based platform developers, Headspace Inc. and Talkspace exemplify divergent strategic positioning within employer-sponsored distribution channels, while Pear Therapeutics, Inc. occupies the prescription digital therapeutic archetype requiring clinical trial investment. Calm and Lyra Health, Inc. anchor the corporate wellness procurement tier through direct contracting relationships with human resources departments. These entities represent the competitive spectrum from consumer-scaled meditation applications to clinically validated therapeutic interventions.
| Leading Market Players |
|---|
| Headspace Inc. |
| Talkspace |
| Electromedical Products International, Inc. |
| Happify Health |
| Calm |
| Lyra Health, Inc. |
| Ginger |
| Pear Therapeutics, Inc. |
| AbleTo, Inc. |
| Others |
Supply & Pricing Matrix
ISO 13485 certification for medical device quality management gates qualified supply relationships and premium-tier pricing access in mental health hardware manufacturing. Developers lacking this certification face exclusion from institutional procurement channels in the United States and Germany, compressing their addressable market to direct-to-consumer segments with lower price realization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by clinical validation depth and integration complexity. Premium tiers command subscription rates supported by FDA 510(k) clearance and EMA DiGA approval, while standard tiers compete on employer wellness program fit and economy tiers face commoditization from generic mindfulness applications. Price differentiation separates prescription digital therapeutics requiring randomized trial investment from wellness applications scaling through volume. Pricing pressure stems from employer procurement consolidation around integrated platform vendors. Corporate wellness programs exhibit lowest price sensitivity due to outcome-based contracting, whereas individual consumers in direct-to-consumer channels demonstrate highest elasticity.
Supply Chain Analysis
Photoplethysmography sensor arrays rest on Taiwanese semiconductor foundries and South Korean display manufacturers for VR headset components. Cloud infrastructure draws from hyperscale data centers concentrated in the United States, Ireland, and Singapore. Raw material dependencies include lithium-ion cells for wearable power management, rare earth elements for EEG amplifier precision, and specialized polymers for biocompatible device housings. Supply chain risk centers on single-source vulnerability for clinical-grade EEG amplifier chips from United States and German specialty electronics producers. Distribution runs through direct enterprise sales teams for institutional contracts and app store platforms for consumer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as employer-sponsored behavioral health benefits harden from optional perk to standard compensation component across United States enterprises. The institutional procurement channel creates predictable recurring revenue streams that consumer-direct models cannot replicate.
For Market Incumbents: To counter margin compression from employer procurement consolidation, deepen clinical validation moats through FDA Breakthrough Devices Program submissions and expand platform interoperability to capture multi-vendor integration contracts. Backward integration into sensor manufacturing reduces dependency on Taiwanese photoplethysmography module suppliers.
For New Entrants and Emerging Players: Employer benefits consultants represent the most penetrable channel partner type for bypassing entrenched vendor relationships. Target Japan's elderly mental health monitoring segment where METI subsidies reduce customer acquisition costs and passive sensing requirements align with capital-constrained development. White-space exists in AI-enabled risk stratification for payers seeking hospitalization reduction.
For Investors and Strategic Acquirers: Roll-up economics work for teletherapy platforms combining human clinicians with digital tools because employer procurement favors integrated solutions over point products. Five-to-ten year viability hinges on reimbursement code expansion for prescription digital therapeutics. Acquisition targets should demonstrate FDA engagement timelines and existing employer pilot contracts. Watch FDA software-as-a-medical-device guidance updates as the inflection signal for platform economics shifting from consumer payment to institutional contracting.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Submission | Accelerated review timelines compress competitive entry windows for serious condition targets. |
| Employer Direct Contracting | Bypasses traditional health plan intermediaries to capture outcome-based pricing premiums. |
| Sensor Manufacturer Partnership | Secures photoplethysmography supply continuity for wearable monitor production scaling. |
| EMA DiGA Fast-Track Pursuit | Unlocks statutory reimbursement in Germany's concentrated employer insurance market. |
| VR Exposure Protocol Development | Penetrates anxiety and PTSD segments where immersive delivery overcomes patient resistance. |
Research Methodology
Direct dialogue with digital health platform executives, FDA regulatory consultants, employer benefits directors, and clinical trial principal investigators grounded the qualitative foundation. Secondary validation drew from FDA 510(k) and De Novo submission databases, EMA DiGA approval registries, CMS Medicare telehealth reimbursement bulletins, and corporate wellness program RFP documentation. Bottom-up platform revenue modeling triangulated against top-down employer spending estimates.
Segment-level demand outputs across product type, technology, application, and end-user dimensions were generated through the analytical framework. Deployment model differentiation between prescription digital therapeutics and direct-to-consumer wellness applications shaped regional adoption pattern modeling. CAGRs were derived from employer benefit penetration curves and reimbursement code expansion timelines. Forecast inputs incorporated the FDA's evolving software-as-a-medical-device framework and METI elderly mental health initiative funding allocations.
Revisions become necessary when FDA software-as-a-medical-device guidance shifts materially, employer procurement consolidation accelerates beyond modeled thresholds, or data localization requirements fragment cloud infrastructure strategies more severely than baseline assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Clot Management Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Biological Microscope Market
Medical Devices
Global Angioplasty Balloons Market