
 Portable Cardiology Ultrasound Systems Market | 2026-2036
Portable Cardiology Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Cardiology Ultrasound Systems Market Analytics
Emergency medical services is bifurcating demand away from traditional hospital-based procurement as pre-hospital cardiac assessment protocols expand. GE Healthcare leverages its deep installed base in cart-based systems to defend institutional accounts, while FUJIFILM SonoSite specializes in ruggedized handheld form factors built for austere environments. Philips sustains technology leadership in integrated telehealth workflows that connect field deployments to cardiology reading centers.
Portable cardiology ultrasound systems are compact echocardiography devices typically weighing under eight pounds, employing phased-array transducers operating at 2-8 MHz to generate real-time cardiac images for structural and functional assessment outside conventional catheterization laboratories. Handheld devices now capture the fastest-growing margin pool as semiconductor miniaturization and AI-assisted image interpretation reduce operator-dependence; tablet-based systems occupy the clinical sweet spot for hospitalist and internal medicine workflows where diagnostic confidence must balance portability against screen resolution. Doppler ultrasound technology dominates procedure volume, though contrast-enhanced imaging is deepening penetration into perfusion assessment where wall-motion scoring demands higher fidelity.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are lengthening market entry for new entrants while elevating quality benchmarks that favor established manufacturers with regulatory infrastructure. The country's national pharmaceutical regulator and notified body capacity constraints in Europe are creating parallel bottlenecks that stakeholders must navigate through early engagement and predicate device strategies. Buyers should monitor how AI-enabled autonomous measurement tools reshape purchasing criteria before committing to multi-year fleet refresh cycles.
Market Dynamics
AI-assisted image interpretation is compressing operator training requirements while simultaneously elevating diagnostic accuracy benchmarks, fundamentally restructuring how hospitals evaluate capital deployment for point-of-care cardiac imaging.
Growth Catalysts
- Hospital-at-Home Expansion:CMS reimbursement codes for acute care at home programs in the United States are creating institutional demand for bedside-capable echocardiography that travels with patients.
- EU MDR Streamlining:Consolidated technical documentation pathways under the Medical Device Regulation are reducing redundant conformity assessments for manufacturers with established quality systems.
- Phased-Array Miniaturization:Semiconductor fabrication advances enabling 2-8 MHz transducer arrays in sub-pound form factors are unlocking pre-hospital cardiac assessment protocols.
Market Restraints
- Notified Body Bottlenecks:European Union MDR designation capacity constraints are extending CE marking timelines by 12-18 months for new market entrants lacking predicate device histories.
- Neodymium Supply Concentration:Rare earth magnet dependency for high-field transducer motors creates vulnerability to export restriction policies in processing-dominant jurisdictions.
- CT Angiography Substitution:Coronary CT angiography with fractional flow reserve computation is capturing intermediate-risk chest pain triage cases previously routed to stress echocardiography.
Strategic Opportunities
- Rural Health Network Gaps:Federally Qualified Health Centers in the United States are deploying handheld systems to bridge cardiology specialist access deserts without on-site sonographer staffing.
- AI-Autonomous Measurements:Machine learning algorithms capable of automated ejection fraction calculation and strain analysis are reducing interpretation dependency on cardiologist availability.
- Direct-to-Consumer Channels:Subscription-based device access models for concierge medicine practices are emerging as alternatives to capital purchase cycles.
Industry Challenges
- Sonographer Training Compression:Accelerated certification pathways for point-of-care ultrasound are producing operators with limited structural heart disease recognition capabilities.
- Legacy PACS Integration:Hospital information system interoperability requirements are forcing middleware development that delays deployment timelines and inflates implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Cardiology Ultrasound Systems Market |
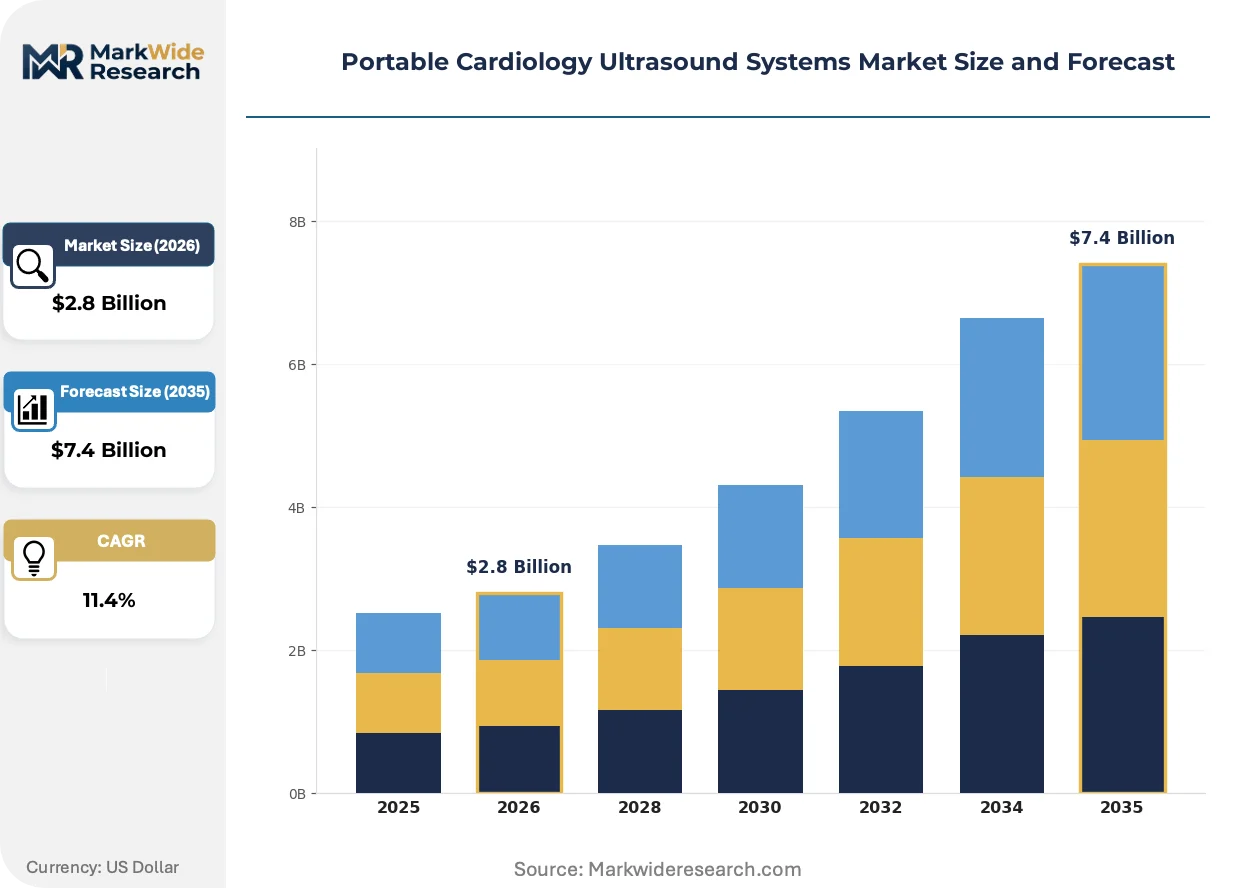
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Tablet-Based Systems, Cart-Based Systems, Point-Of-Care Solutions Technology: Doppler Ultrasound, 2D Imaging, 3D Imaging, Contrast-Enhanced Imaging End User: Hospitals, Clinics, Home Care, Emergency Medical Services Application: Cardiac Monitoring, Diagnostics, Research, Telehealth Services |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers AG, Canon Medical Systems, Mindray Medical International Limited, Samsung Medison Co., Ltd., FUJIFILM SonoSite, Inc., Esaote SpA, Konica Minolta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Cardiology Ultrasound Systems Market Evolving Landscape
Semiconductor miniaturization and edge-computing architectures are collapsing the functional gap between handheld probes and cart-based systems, redrawing competitive boundaries across acute care settings.
Cloud-native ultrasound architectures are fragmenting the traditional hardware-software bundling model. These platforms separate image acquisition from processing and storage, enabling software-defined feature upgrades without device replacement. Emergency departments and mobile intensive care units are adopting subscription-tiered functionality that scales with clinical acuity. This architecture is fragmenting vendor lock-in patterns that historically protected installed-base revenues.
FDA 510(k) clearance pathways for AI-enabled autonomous measurement tools are tightening predicate device requirements for algorithm training datasets. The agency's evolving guidance on machine learning-based device modifications is forcing manufacturers to pre-specify modification protocols rather than seeking iterative clearances. Cardiology reading centers and academic medical centers in the United States are prioritizing vendors with established algorithm change control plans.
Hospital procurement committees are unbundling service contracts from device acquisition, separating preventive maintenance from software support and clinical training. Third-party service organizations and independent sonography educator networks are capturing margin pools previously retained by original equipment manufacturers. This unbundling is most advanced in United States health systems with centralized capital equipment standardization committees.
Portable Cardiology Ultrasound Systems Market Segmentation
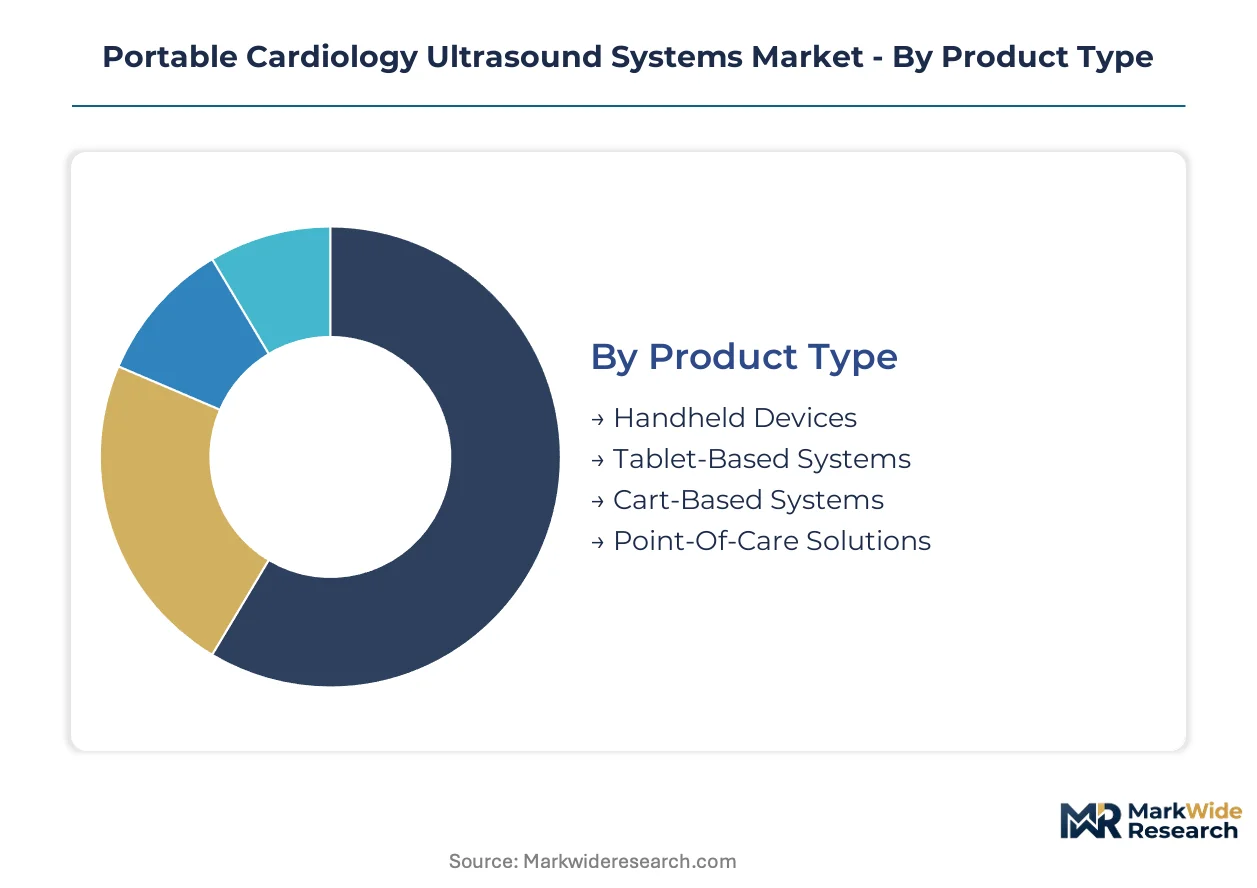
Portable cardiology ultrasound systems fragment across four intersecting dimensions that determine procurement patterns and margin capture. Product form factor and technology modality define hardware economics, while end-user setting and clinical application dictate software licensing and service attach rates.
Product Type:
Margin pools concentrate in the transition zone between handheld portability and cart-based diagnostic confidence, where semiconductor miniaturization meets clinical workflow integration.
- Handheld Devices:Sub-pound form factors integrating phased-array transducers at 2-8 MHz with AI-assisted image interpretation. Demand clusters in United States emergency medical services and rural clinic networks where sonographer staffing is scarce and field cardiac assessment protocols are expanding.
- Tablet-Based Systems:Mid-weight platforms balancing screen resolution against mobility for hospitalist and internal medicine workflows. These systems capture the clinical sweet spot where diagnostic confidence requirements moderate pure portability priorities.
- Cart-Based Systems:Full-featured echocardiography with advanced Doppler capabilities and contrast-enhanced imaging support. Institutional accounts in United States academic medical centers defend these deployments for complex structural heart disease assessment.
- Point-Of-Care Solutions:Workflow-optimized packages bundling device, software, and training for specific clinical settings. Federally Qualified Health Centers deploy these to bridge cardiology specialist access deserts.
Cart-based systems hold installed capacity. Handheld devices are rotating up the share rankings.
Technology:
Technology selection tracks the fidelity gradient from functional assessment to perfusion imaging, with reimbursement codes and regulatory clearance pathways shaping adoption velocity.
- Doppler Ultrasound:Dominates procedure volume through velocity-based flow assessment for valvular function and pressure gradient estimation. Hospital-at-home programs in the United States specify Doppler-capable systems for CMS-reimbursed acute care delivery.
- 2D Imaging:Structural assessment backbone using phased-array sector scanning for chamber quantification and wall-motion analysis. Emergency departments prioritize 2D systems for rapid triage of chest pain presentations.
- 3D Imaging:Volumetric reconstruction enabling en-face valve visualization and automated chamber quantification. Academic medical centers with interventional cardiology programs drive demand for procedural planning applications.
- Contrast-Enhanced Imaging:Microbubble perfusion assessment for endocardial border delineation and wall-motion scoring in technically difficult patients. FDA 510(k) clearance timelines for contrast-specific software modules extend deployment schedules.
Doppler ultrasound anchors current procedure volume. Contrast-enhanced imaging is climbing the fastest as perfusion assessment protocols penetrate community practice.
End User:
Customer type determines capital deployment models, with institutional procurement separating from subscription-based access arrangements in ambulatory and pre-hospital settings.
- Hospitals:Multi-departmental deployments spanning emergency, critical care, and cardiology units with PACS integration requirements. United States health systems with centralized standardization committees unbundle service contracts from device acquisition.
- Clinics:Federally Qualified Health Centers and rural health networks deploying handheld systems without on-site sonographer staffing. AI-autonomous measurement tools reduce interpretation dependency on distant cardiologist availability.
- Home Care:Hospital-at-home programs requiring bedside-capable echocardiography that travels with patients. CMS reimbursement codes for acute care at home create institutional demand pull.
- Emergency Medical Services:Pre-hospital cardiac assessment protocols driving ruggedized handheld adoption. Field deployments connect through integrated telehealth workflows to cardiology reading centers.
Hospitals retain fleet refresh authority. Emergency medical services is gaining share fastest as pre-hospital protocols expand.
Application:
Application focus determines software licensing tiers and algorithm training requirements, with autonomous measurement capabilities reshaping purchasing criteria.
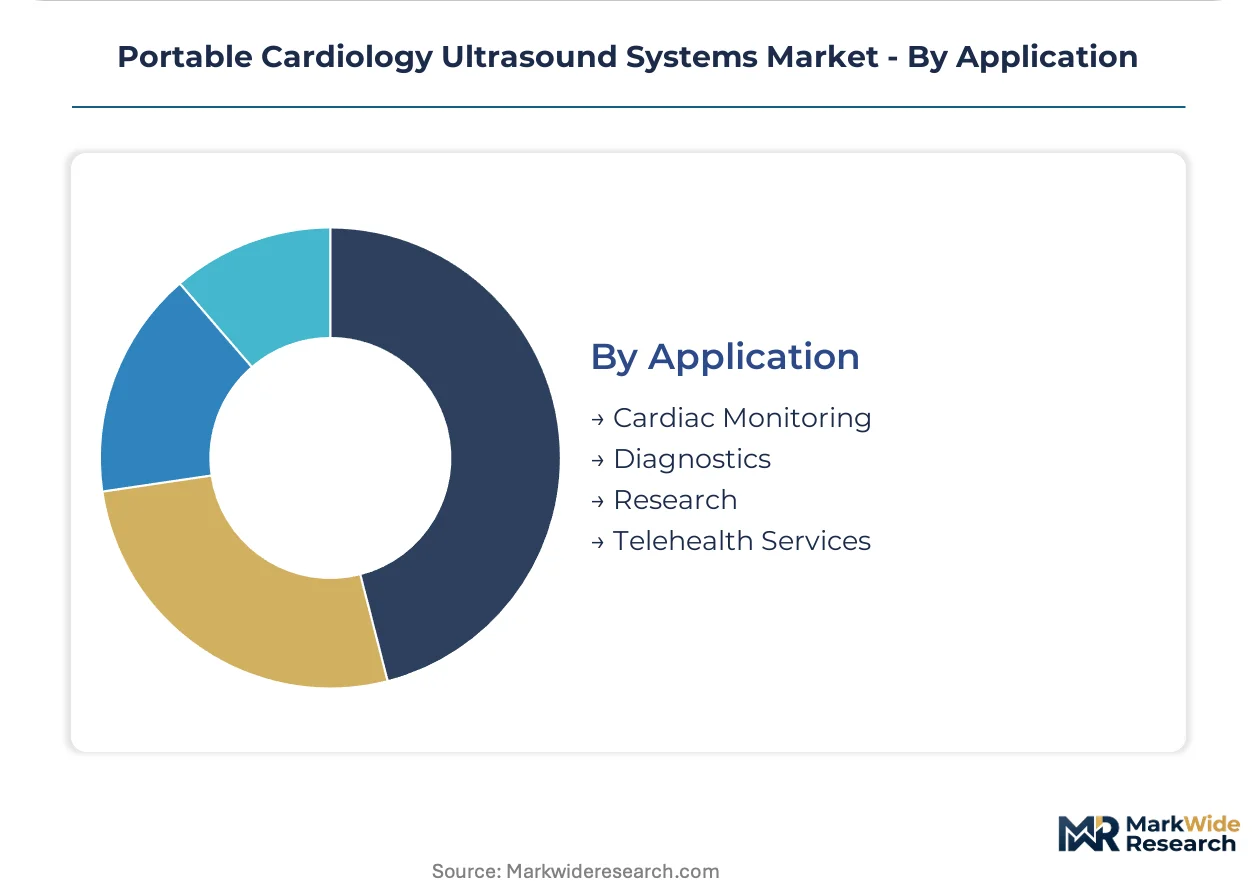
- Cardiac Monitoring:Serial functional assessment for heart failure management and post-interventional surveillance. Home care programs in the United States deploy portable systems for longitudinal patient tracking.
- Diagnostics:Structural and functional characterization for chest pain triage and murmur evaluation. Emergency departments balance throughput demands against diagnostic confidence requirements.
- Research:Strain imaging and advanced quantification for clinical trial endpoints and algorithm development. Academic medical centers prioritize vendors with established algorithm change control plans.
- Telehealth Services:Cloud-native architectures separating image acquisition from processing and storage. Subscription-tiered functionality scales with clinical acuity in mobile intensive care units.
Diagnostics commands current deployment volume. Telehealth services represents the steepest expansion trajectory as cloud-native architectures fragment traditional hardware-software bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export phased-array transducer components to United States health systems, while South Korean semiconductor fabricators supply miniaturized processing chips for handheld device assembly.
United States
Hospital-at-home programs and rural clinic networks drive procurement of bedside-capable echocardiography systems. FDA 510(k) clearance pathways for AI-enabled autonomous measurement tools are tightening predicate device requirements for algorithm training datasets. The Mayo Clinic in Rochester anchors clinical validation studies for cloud-native ultrasound architectures.
Germany
Industrial demand concentrates in precision transducer manufacturing for export markets. EU MDR technical documentation requirements under notified body supervision are extending CE marking timelines for new market entrants. The Baden-Württemberg medical technology corridor around Stuttgart hosts specialized suppliers for high-frequency phased-array components.
China
Domestic health system modernization and county-level hospital upgrades expand point-of-care cardiac imaging deployment. NMPA regulatory pathways for AI-assisted diagnostic software are converging with international standards through harmonization initiatives. The Yangtze River Delta manufacturing cluster around Shanghai produces miniaturized semiconductor assemblies for handheld ultrasound probes.
Japan
Aging demographics and home-based cardiac monitoring protocols stimulate demand for portable echocardiography in ambulatory settings. PMDA consultation procedures for software-as-a-medical-device are clarifying approval pathways for cloud-native platforms. The Kansai region around Osaka maintains concentrated expertise in diagnostic imaging component fabrication.
India
Federally Qualified Health Center equivalents and tier-two city hospitals adopt handheld systems to bridge cardiology specialist access gaps. CDSCO medical device rules are aligning with IMDRF guidelines for software-enabled diagnostics. The Karnataka medical device park near Bangalore attracts assembly operations for export-oriented portable ultrasound manufacturing.
Portable Cardiology Ultrasound Systems Market Competitive Landscape
Listed leaders compete with private specialists across regulatory infrastructure and installed-base defense dimensions. The vendor base consolidates around three tiers: diversified health technology conglomerates with deep regulatory affairs capabilities, mid-scale imaging specialists with focused cardiology portfolios, and emerging handheld-native challengers leveraging semiconductor partnerships. Strategic archetypes include cart-based system incumbents defending institutional accounts, ruggedized handheld pure-plays targeting pre-hospital deployments, and cloud-native platform builders unbundling hardware-software integration. Dominant competitive moves encompass AI algorithm licensing agreements and vertical integration into transducer semiconductor fabrication.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify archetypes with established regulatory infrastructure and deep installed bases in institutional cardiology departments. Siemens Healthineers AG occupies a position bridging cart-based diagnostic confidence with emerging portable form factors. FUJIFILM SonoSite, Inc. represents the ruggedized handheld specialization vector, with its corporate structure reflecting focused investment in austere-environment deployment protocols.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Canon Medical Systems |
| Mindray Medical International Limited |
| Samsung Medison Co., Ltd. |
| FUJIFILM SonoSite, Inc. |
| Esaote SpA |
| Konica Minolta Inc. |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways and EU MDR technical documentation requirements simultaneously gate supplier qualification and stratify price tiers across portable cardiology ultrasound systems, compressing margins for non-compliant manufacturers while amplifying premium capture for established players with regulatory infrastructure.
Pricing Analysis
Current-generation handheld devices with AI-assisted interpretation command substantial premiums over prior-generation tablet-based systems and economy-tier cart-based platforms without autonomous measurement capabilities. Pricing stratifies across premium, standard, and economy tiers based on algorithm training dataset sophistication and FDA clearance tier for AI-enabled features. Cost compression in the economy handheld segment is intensifying because semiconductor miniaturization has democratized basic phased-array functionality. Federally Qualified Health Centers exhibit the highest price sensitivity, while academic medical centers with interventional cardiology programs demonstrate the lowest.
Supply Chain Analysis
Inbound logistics costs from South Korean semiconductor fabricators to United States device assemblers fluctuate with container availability on the Busan-Los Angeles trade lane, compressing margin buffers for handheld-native challengers without volume-contracted freight rates. Supply concentrates in South Korea for miniaturized processing chips, Germany for precision phased-array transducer components, and China for final device assembly. Raw material dependencies encompass neodymium rare earth magnets for transducer motors, silicon wafers for ASIC fabrication, and specialized polymers for probe housing. Single-source vulnerability in neodymium processing creates exposure to export restriction policies. Distribution runs through hospital GPO contracts, regional medical device distributors, and emerging direct-to-subscription channels for concierge medicine practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
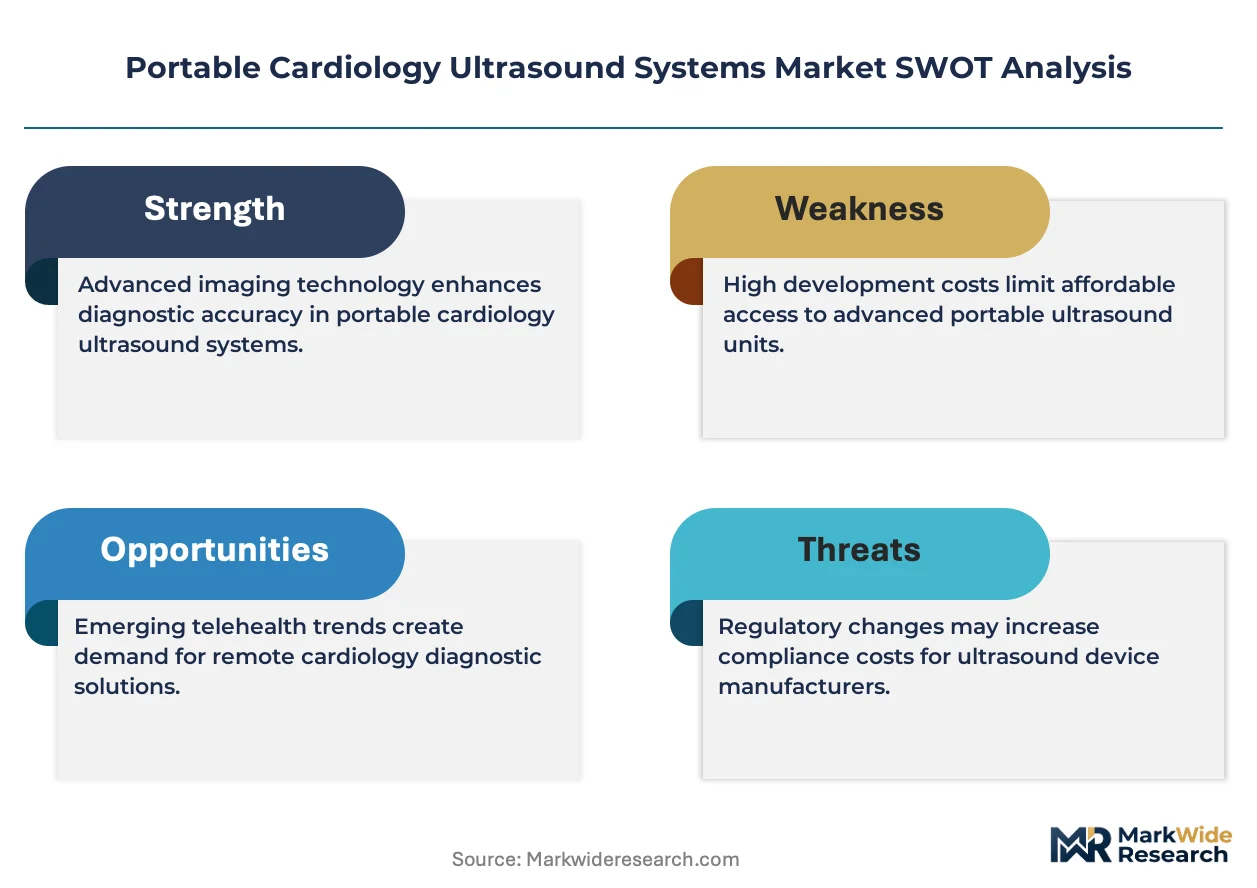
Scarcity in AI algorithm training datasets with cardiologist-validated annotations constrains how quickly new entrants can achieve diagnostic accuracy parity, entrenching incumbents with established clinical validation partnerships and forcing acquisition premiums for algorithm-native startups.
For Market Incumbents: Secure exclusive data-sharing agreements with academic medical centers to maintain algorithm training dataset advantages against handheld-native challengers. Capture backward integration into transducer semiconductor fabrication to insulate margin structures from rare earth magnet price volatility. Defend institutional accounts by unbundling service contracts before third-party service organizations capture maintenance margin pools. For New Entrants and Emerging Players: Differentiate on cloud-native architectures that separate image acquisition from processing, enabling subscription-tiered functionality without hardware replacement cycles. Target Federally Qualified Health Centers in United States rural access deserts where AI-autonomous measurements reduce dependency on distant cardiologist interpretation. Pursue direct-to-consumer channels through concierge medicine subscription models as an alternative to capital purchase cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates seeking to divest non-core imaging portfolios amid portfolio rationalization pressures. Long-term viability hinges on regulatory infrastructure depth and installed-base defense capabilities rather than pure technology differentiation. Monitor FDA algorithm change control plan submissions as an inflection indicator for which vendors can sustain iterative AI improvement without clearance delays.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing Agreement | Accelerates autonomous measurement capabilities for handheld device manufacturers lacking in-house cardiologist validation networks. |
| CE Marking Pathway Investment | Reduces EU MDR timeline exposure for new entrants through early notified body engagement and predicate device strategies. |
| Hospital System Partnership | Locks in fleet refresh cycles through integrated telehealth workflows connecting field deployments to cardiology reading centers. |
| Software Companion Development | Enables cloud-native feature upgrades without hardware replacement, fragmenting traditional vendor lock-in patterns. |
| Reimbursement Strategy | Aligns device specifications with CMS hospital-at-home program requirements for acute care delivery reimbursement codes. |
Research Methodology
The analysis maps handheld devices, tablet-based systems, cart-based platforms, and point-of-care solution bundles, each validated through cardiologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary interviews with device manufacturers and emergency medical services operators combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement code releases, and hospital procurement contract records. Bottom-up unit deployment estimates and top-down market sizing triangulate across stakeholder perspectives.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product form factor, technology modality, end-user setting, and clinical application dimensions alongside AI-enabled feature tier as an industry-specific segmentation axis. CAGRs were derived from procedure volume growth trajectories and capital equipment replacement cycle compression. Forecast inputs incorporated semiconductor miniaturization curves and regulatory clearance timeline elasticity.
Material uncertainties — notified body capacity constraints, rare earth export restrictions, and CT angiography substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about algorithm regulatory pathway stability and reimbursement code durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Germany Mammography Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market