
 Image-Based Cytometer Market | 2026-2036
Image-Based Cytometer Market Size, Share, and Industry Trends Forecast 2026-2036
Image-Based Cytometer Market Outlook
Deep learning integration into fluorescence imaging workflows is tilting instrument architecture toward GPU-accelerated processing and real-time morphometric analysis. Thermo Fisher Scientific leverages its ion and electron microscopy heritage to extend software ecosystems into cytometry data pipelines. Danaher Corporation anchors its position through Beckman Coulter Life Sciences' installed base and service infrastructure. Bio-Rad Laboratories specializes in droplet-based microfluidic imaging platforms for single-cell applications.
An image-based cytometer combines optical microscopy with automated image capture and computational analysis to quantify cellular morphology, protein expression, and functional states at single-cell resolution; systems typically operate at 10x to 60x magnification with sub-micron resolution and throughput rates exceeding 1,000 cells per second in high-content screening configurations. Fluorescence imaging dominates current installations due to multiplexing capacity for immunophenotyping, while multispectral imaging represents the fastest-expanding technology segment as spectral unmixing algorithms reduce spectral overlap artifacts. Among end users, pharmaceutical companies command the largest revenue share through outsourced toxicology and target validation contracts, whereas research institutions sustain the highest unit growth driven by NIH and ERC grant cycles.
FDA 21 CFR Part 11 compliance requirements shape software validation protocols for clinical cytometry deployments, while EMA's ICH Q2(R1) guidelines drive analytical method transfer standards across European contract research organizations. ISO 13485 certification serves as a gating factor for manufacturers supplying diagnostic laboratories in regulated markets. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled image analysis algorithms, as predicate device pathways for deep-learning cytometry modules remain under active agency review.
Market Dynamics
Deep learning architectures are compressing image analysis timelines from hours to minutes, forcing instrument manufacturers to restructure hardware-software bundles around GPU-accelerated inference engines rather than traditional CPU-bound processing pipelines.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records compliance mandates drive pharmaceutical companies toward validated cytometry software platforms with audit trails and electronic signatures, expanding the addressable base for regulated deployments.
- High-content screening workflows:Contract research organizations in the United States and Germany integrate image-based cytometers into automated compound profiling pipelines, accelerating toxicology and target validation throughput.
- Spectral unmixing algorithms:Multispectral imaging systems reduce fluorophore crosstalk artifacts, enabling 8-plex and 12-plex panels that displace sequential staining protocols in immuno-oncology research.
Market Restraints
- CMOS sensor supply concentration:Japanese and Taiwanese semiconductor fabricators control high-sensitivity image sensor supply, exposing instrument manufacturers to allocation risk during foundry capacity crunches.
- Laser source cost structure:Solid-state lasers and LED engines represent 15-22% of bill-of-materials costs, with rare-earth phosphor pricing volatility compressing gross margins at the mid-tier instrument segment.
- ISO 13485 certification timelines:Diagnostic laboratory deployments require 18-24 month quality management system validation cycles, delaying revenue recognition for manufacturers entering clinical markets.
Strategic Opportunities
- China biopharma clusters:Shanghai and Suzhou life science parks expand domestic R&D spending, creating procurement windows for localized instrument platforms with Mandarin-language software interfaces.
- AI-enabled algorithm modules:Predicate device pathways for deep-learning cytometry analysis remain under FDA active review, offering first-mover advantage to manufacturers submitting 510(k) packages with validated training datasets.
- Single-cell multi-omics convergence:Integration of image-based cytometry with droplet microfluidics and mass spectrometry creates unified workflows for simultaneous transcriptomic and proteomic profiling at cellular resolution.
Industry Challenges
- Computational pathology skill scarcity:Bioimage informatics expertise remains concentrated in academic medical centers, constraining commercial deployment of advanced morphometric analysis tools in contract research settings.
- Legacy LIMS integration friction:Pre-2015 laboratory information management systems lack API architectures for real-time image data ingestion, forcing middleware development costs onto instrument vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image-Based Cytometer Market |
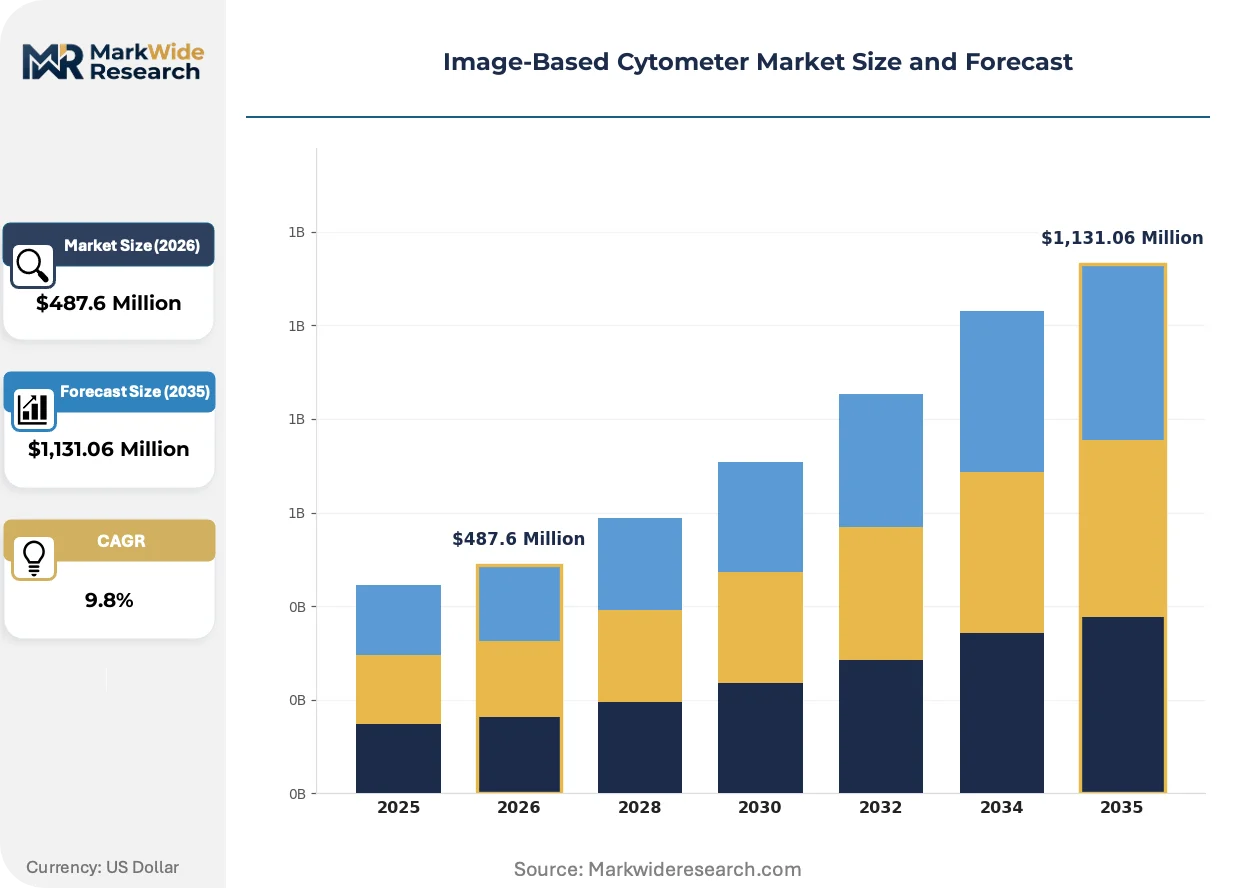
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometer, Image Cytometer, Automated Cytometer, Benchtop Cytometer End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Biotechnology Firms Technology: Fluorescence Imaging, Brightfield Imaging, Confocal Imaging, Multispectral Imaging Application: Cellular Analysis, Cancer Research, Stem Cell Research, Drug Discovery |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Sysmex Corporation, Becton Dickinson, PerkinElmer, Cytek Biosciences, Yokogawa Electric Corporation, Bio-Rad Laboratories, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image-Based Cytometer Market Strategic Shifts
Instrument architectures are pivoting from hardware-centric specifications to software-defined analysis capabilities, with computational performance replacing optical resolution as the primary competitive differentiator in procurement evaluations.
Confocal spinning-disk microscopy is digitizing fluorescence imaging workflows through parallelized multi-point scanning and camera-based detection. Pharmaceutical toxicology groups in Germany and the United States deploy these systems for sub-cellular organelle tracking at 100+ frames per second. The technology is digitizing throughput benchmarks that previously required dedicated flow cytometry channels, collapsing the functional boundary between imaging and flow-based platforms.
EMA's ICH Q2(R1) analytical method transfer guidelines tighten cross-laboratory validation requirements for cell-based potency assays. European contract research organizations now demand instrument qualification packages with documented measurement uncertainty budgets and intermediate precision studies. High-content screening service providers respond by embedding metrology-grade calibration workflows into standard operating procedures, extending deployment timelines but reducing regulatory audit risk.
Service unbundling is fragmenting traditional instrument-plus-support contracts. Academic core facilities in the United States increasingly procure hardware through capital grants while purchasing image analysis software and cloud storage through separate SaaS subscriptions. This purchasing pattern shifts vendor revenue toward recurring software licenses and consumption-based compute credits, compressing upfront instrument margins while extending customer lifetime value horizons.
Image-Based Cytometer Market Segmentation
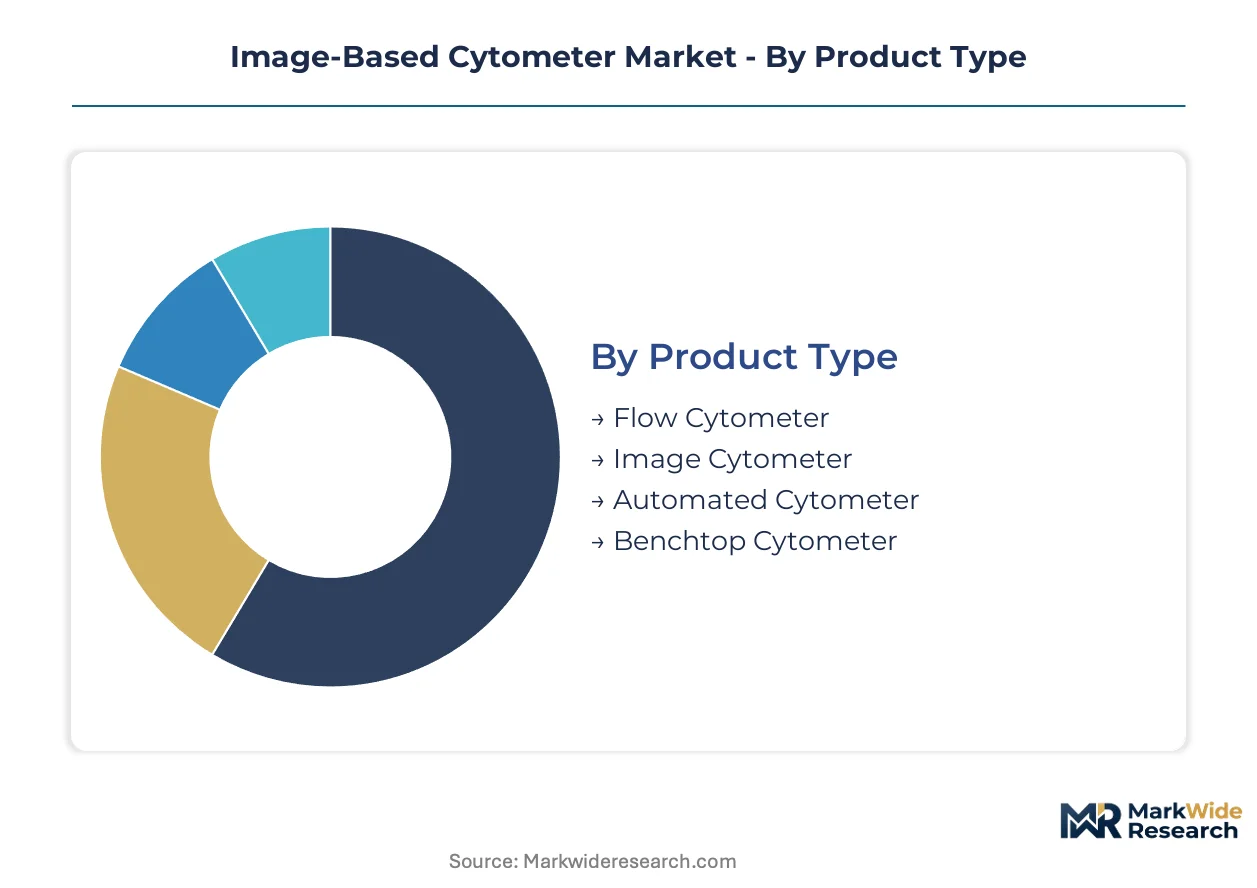
Segmentation in image-based cytometry reveals divergent service intensity and margin profiles across hardware categories and user environments. Procurement patterns vary sharply between regulated clinical deployments and grant-funded academic installations, shaping vendor go-to-market architectures.
Product Type:
After-sales service intensity escalates with system complexity, as field service engineers must calibrate optical paths and validate software modules across multi-year support contracts.
- Image Cytometer:Combines high-resolution microscopy with automated image analysis for single-cell morphometric quantification. Pharmaceutical toxicology groups in Germany deploy these systems for compound safety profiling, driving demand for 24/7 uptime guarantees and rapid replacement part logistics.
- Flow Cytometer:Fluidics-based cell sorting with integrated imaging modules for image-in-flow applications. Academic core facilities in the United States prioritize these hybrid platforms for immunophenotyping workflows, constrained by NIH capital equipment depreciation cycles and shared-instrument scheduling protocols.
- Automated Cytometer:Robotic sample handling with walk-away operation for high-throughput screening.
- Benchtop Cytometer:Compact footprint systems for space-constrained laboratories with basic imaging capabilities.
Image cytometers hold the largest share; momentum sits with automated cytometers.
End User:
Cost tier stratification separates enterprise-grade deployments from entry-level configurations, with diagnostic laboratories absorbing premium pricing for regulatory-compliant software bundles.
- Pharmaceutical Companies:Enterprise procurement of multi-instrument fleets with centralized data management and LIMS integration. Outsourced toxicology contracts in the United States and Germany require validated 21 CFR Part 11 software stacks, extending sales cycles but securing multi-year service revenue.
- Research Institutions:Grant-dependent acquisition through NIH and ERC funding windows with heavy reliance on shared core facility models. Principal investigators prioritize open-file formats and third-party analysis software compatibility over vendor-locked ecosystems.
- Clinical Laboratories:ISO 13485-certified installations for diagnostic workflows with stringent quality control protocols.
- Biotechnology Firms:Venture-backed startups favoring flexible leasing arrangements and cloud-based analysis subscriptions.
Pharmaceutical companies command the revenue concentration; biotechnology firms are climbing the fastest.
Technology:
Volume throughput requirements differentiate spectral architectures from conventional fluorescence, with multiplexing depth directly correlating to per-sample reagent economics.
- Fluorescence Imaging:Broadband excitation with filter-based emission detection for 4-6 color immunophenotyping panels. Installed base concentration in the United States reflects decades of protocol standardization, though spectral overlap limitations constrain panel expansion.
- Multispectral Imaging:Continuous wavelength capture with algorithmic unmixing for 8-12 fluorophore resolution. Immuno-oncology research in Germany and China adopts these systems for complex tumor microenvironment profiling, displacing sequential staining protocols.
- Brightfield Imaging:Label-free morphological assessment for basic cell counting and viability applications.
- Confocal Imaging:Optical sectioning with pinhole aperture for sub-cellular resolution in 3D cultures.
Fluorescence imaging retains the dominant installed base; multispectral imaging shows the steepest expansion trajectory.
Application:
Customer maturity varies across therapeutic domains, with oncology workflows demanding higher analytical rigor than stem cell quality control applications.
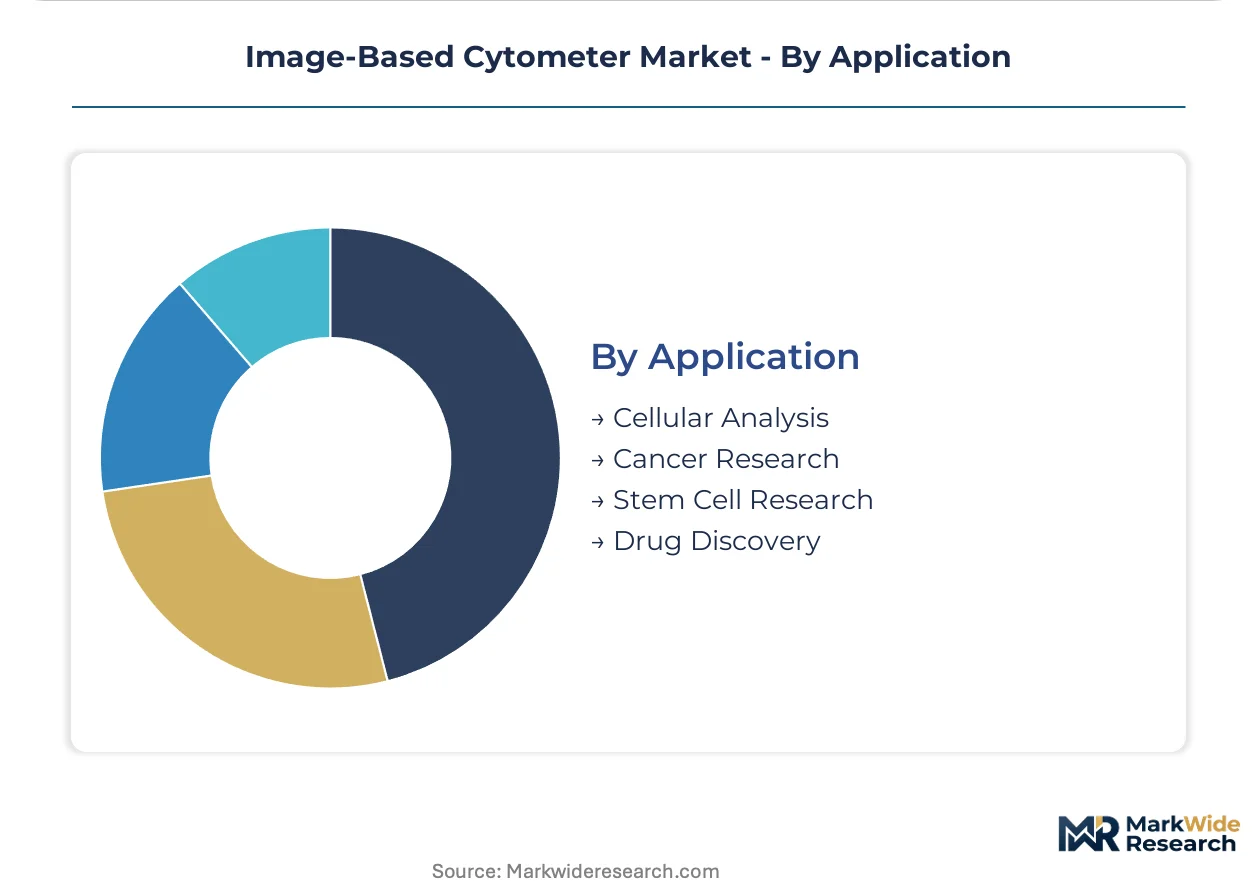
- Drug Discovery:High-content screening for compound mechanism-of-action and toxicity prediction. Contract research organizations in the United States integrate image-based cytometers into automated profiling pipelines, requiring instrument qualification packages with documented measurement uncertainty budgets.
- Cancer Research:Tumor heterogeneity analysis and immune cell infiltration quantification. Research institutions in Germany leverage spectral unmixing for multiplexed biomarker panels in precision oncology studies.
- Cellular Analysis:Routine phenotyping and proliferation assays for general biology research.
- Stem Cell Research:Pluripotency marker verification and differentiation tracking for regenerative medicine.
Drug discovery captures the largest revenue pool; cancer research is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German instrument manufacturers export image-based cytometry platforms to contract research organizations across the United States and China, establishing a transatlantic-Pacific trade corridor that channels precision optical engineering into high-content screening workflows.
United States
NIH grant cycles and outsourced pharmaceutical toxicology contracts drive procurement volumes. FDA 21 CFR Part 11 compliance mandates shape software validation requirements for regulated deployments. The Greater Boston biotech cluster and San Diego life science corridor concentrate multi-instrument fleet installations with centralized data management infrastructure.
Germany
EMA ICH Q2(R1) guidelines tighten analytical method transfer standards for cell-based potency assays. Federal research funding through the Deutsche Forschungsgemeinschaft sustains academic core facility procurement. The Rhine-Main biopharma corridor around Frankfurt and Heidelberg anchors high-content screening service provider density.
China
Domestic biopharma R&D spending expansion in Shanghai and Suzhou life science parks creates localized procurement windows. NMPA regulatory pathways for innovative medical devices influence instrument qualification timelines. The Yangtze River Delta cluster concentrates venture-backed biotechnology firm formation and instrument leasing demand.
Japan
PMDA quality management system requirements extend validation timelines for diagnostic laboratory deployments. METI industrial technology grants support academic imaging core facility modernization. The Kanto region around Tokyo maintains the highest concentration of shared cytometry platforms with open-file format compatibility requirements.
United Kingdom
ERC funding windows and MRC capital equipment schemes sustain research institution acquisition cycles. MHRA guidance on cell-based assay validation aligns with EMA standards for cross-border method transfer. The Cambridge-Oxford-London golden triangle concentrates spectral imaging adoption for immuno-oncology research.
Image-Based Cytometer Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base exhibits moderate concentration, with diversified life science conglomerates anchoring enterprise procurement channels while specialized cytometry firms penetrate grant-funded academic segments. Three archetypes dominate: full-platform integrators with service infrastructure, component-specialist innovators with software-defined differentiation, and regional fabricators with localized support networks. Competitive moves center on strategic partnerships for AI-enabled algorithm validation and geographic expansion through distributor qualification in China.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify full-platform integrators with extensive installed bases and service logistics networks. Bio-Rad Laboratories occupies a specialist position within droplet-based microfluidic imaging architectures. These three entities represent distinct competitive vectors—optical systems heritage, life sciences instrumentation breadth, and single-cell workflow specialization—that collectively define the market's structural segmentation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Sysmex Corporation |
| Becton Dickinson |
| PerkinElmer |
| Cytek Biosciences |
| Yokogawa Electric Corporation |
| Bio-Rad Laboratories |
| Sartorius AG |
| Others |
Value Chain & Pricing Dynamics
Taipei and Hsinchu semiconductor corridors anchor CMOS sensor fabrication capacity, with foundry allocation crunches during peak demand cycles transmitting directly into instrument OEM pricing power and extended lead time premiums for high-sensitivity imaging modules.
Pricing Analysis
Cost-plus contracts with rare-earth phosphor indexation govern laser source procurement between Japanese component suppliers and mid-tier instrument manufacturers. Pricing stratifies across FDA-validated premium tiers, ISO-certified standard configurations, and grant-funded economy systems lacking 21 CFR Part 11 software bundles. Cost compression in the economy segment intensifies as academic core facilities shift toward capital-grant hardware procurement paired with separate SaaS analysis subscriptions. Biotechnology startups exhibit highest price sensitivity, while pharmaceutical toxicology groups absorb premium pricing for validated multi-instrument fleets with centralized LIMS integration.
Supply Chain Analysis
High-sensitivity image sensors draw from Taiwanese and Japanese semiconductor fabricators, solid-state laser engines rest on Japanese and German optical component houses, and precision motion stages feed from Swiss and German mechatronics specialists. Single-source vulnerability concentrates in sCMOS sensor supply where two foundry groups control advanced back-illuminated architectures. Distribution runs through direct enterprise sales teams for pharmaceutical fleet deployments, regional distributors for academic core facilities, and cloud-platform marketplaces for software analysis modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Image-based cytometry sits in early-cycle expansion as deep learning integration creates replacement demand for GPU-accelerated instruments across installed bases predating real-time morphometric capabilities.
For Market Incumbents: Build switching-cost moats through embedded AI algorithm validation workflows that lock pharmaceutical customers into recurring software license structures. Deepen field service engineer density in the Boston and San Diego biotech corridors to defend against emerging cloud-native cytometry platforms. Prioritize ISO 13485 certification investment for diagnostic laboratory segments before NMPA regulatory pathways mature in China. For New Entrants and Emerging Players: Establish a beachhead in Mandarin-language software interfaces for Shanghai and Suzhou life science parks where domestic biopharma R&D spending outpaces localized instrument platform availability. Target biotechnology firm segments with flexible leasing arrangements and consumption-based compute credit models that circumvent capital equipment depreciation cycle constraints. Lead with droplet microfluidic imaging specialization to differentiate from established fluorescence imaging installed bases. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-specialist innovators with software-defined differentiation over full-platform integrators facing SaaS unbundling pressure. Long-term viability hinges on AI-enabled algorithm module revenue streams displacing hardware-centric valuation multiples. Watch FDA 510(k) submission volumes for deep-learning cytometry modules as inflection indicator for first-mover regulatory capture.| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Accelerated Platform Launch | Thermo Fisher Scientific and Danaher Corporation compete on inference speed benchmarks for high-content screening workflows. |
| AI Algorithm Validation Partnership | FDA predicate device pathway submissions require documented training datasets from pharmaceutical toxicology collaborators. |
| China Localization Program | Mandarin software interfaces and NMPA qualification timelines determine procurement wins in Shanghai life science parks. |
| Service Unbundling Transition | Academic core facilities increasingly separate hardware capital grants from SaaS analysis subscriptions. |
| Spectral Imaging Module Expansion | Cytek Biosciences and Yokogawa Electric Corporation extend 12-plex panel capabilities for immuno-oncology research. |
Study Parameters
A standing panel of pharmaceutical toxicology directors, academic core facility managers, biomedical imaging specialists, and regulatory affairs leads provided ongoing calibration against secondary validation from FDA 510(k) filings, EMA ICH Q2(R1) guidance documents, NIH grant award databases, and instrument vendor SEC disclosures. Bottom-up triangulation across procurement cycle interviews with contract research organizations in the United States and Germany converged with top-down analysis of biopharma R&D capital expenditure trends.
Scenario-bracketing framed demand projections across the analysis window, modeling technology adoption curves for fluorescence versus multispectral imaging architectures, end-user segmentation across pharmaceutical companies and research institutions, and geographic regulatory cluster differentiation. CAGRs derived from instrument shipment data, software license renewal rates, and service contract attach rates. Forecast inputs incorporated deep learning integration timelines and NMPA regulatory pathway maturation in China.
Stress conditions across CMOS sensor foundry allocation, rare-earth phosphor pricing volatility, and FDA AI-enabled device guidance evolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about GPU cost curves and pharmaceutical outsourcing contract growth. Cross-checking against NIH capital equipment depreciation schedules and Deutsche Forschungsgemeinschaft funding windows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Implant Handpiece Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Power Smart Bed Market
Medical Devices
Medical Device Coating Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
North America Electroencephalography Devices Market