
 North America Ultrasound Devices Market | 2026-2036
North America Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ultrasound Devices Market Analytics
Aftermarket service revenue is narrowing as manufacturers shift toward software-subscription models bundled with hardware refresh cycles. GE Healthcare leverages its installed base of radiology suites to sustain recurring revenue streams across US health systems. Koninklijke Philips N.V. anchors its North American position through deep integration of AI-assisted image reconstruction into diagnostic workflows. Siemens Healthineers competes by controlling the premium segment with advanced elastography capabilities for liver and breast imaging.
North America ultrasound devices employ piezoelectric transducers operating at frequencies from two to fifteen megahertz, generating real-time anatomical images through pulse-echo acoustic principles for non-invasive diagnostic and interventional guidance. Diagnostic ultrasound systems dominate capital expenditure budgets across hospitals, while portable ultrasound units represent the fastest-expanding product category as emergency departments and rural clinics prioritize bedside mobility. Software-based technology architectures command expanding margin pools as vendors replace dedicated hardware processors with cloud-connected computational platforms.
FDA premarket notification requirements under 510(k) pathways govern device safety and efficacy, while the EPA regulates disposal of transducer gel and electronic waste from decommissioned systems across US healthcare facilities. The IRA's hospital infrastructure incentives indirectly shape procurement timelines for imaging equipment modernization. Stakeholders must monitor evolving reimbursement codes for point-of-care ultrasound applications as CMS adjusts physician fee schedules affecting adoption economics.
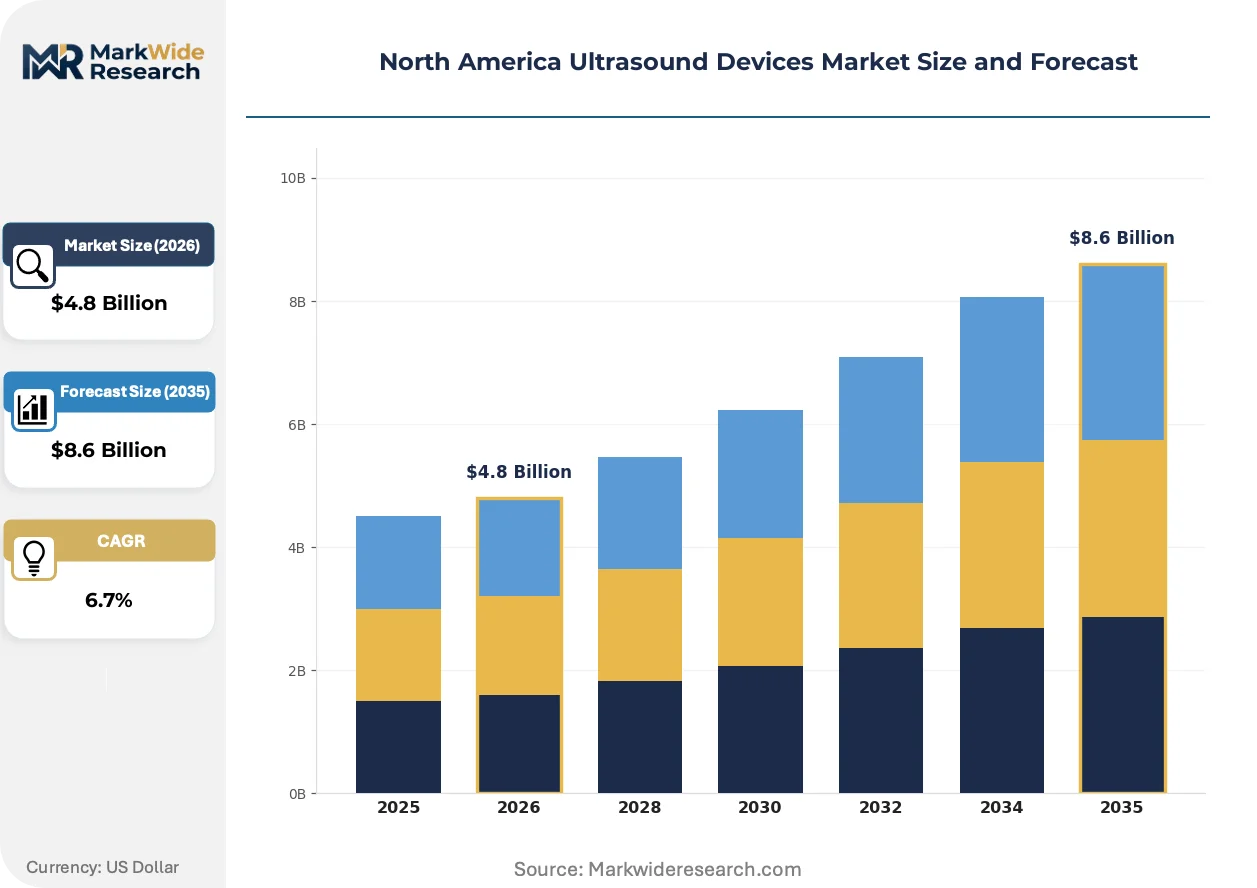
Market Dynamics
Software-subscription bundling is restructuring revenue capture across North American ultrasound vendors, compressing traditional hardware margins while expanding recurring income streams through cloud-connected diagnostic platforms.
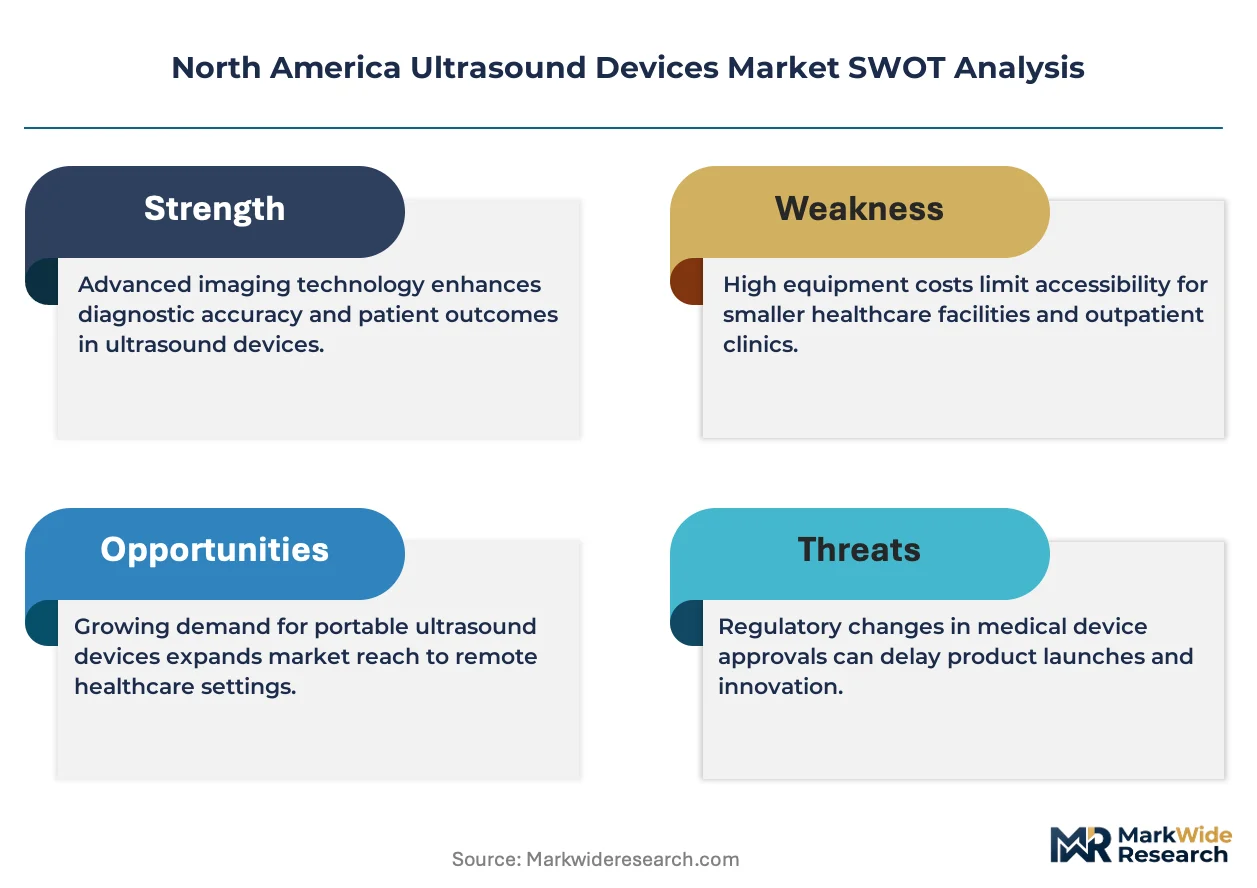
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification processes for AI-enhanced imaging software are shortening product development cycles and accelerating commercialization timelines for diagnostic algorithms.
- Ambulatory Surgical Center Expansion:Point-of-care imaging adoption is intensifying across United States outpatient facilities as procedural volume migrates from inpatient settings.
- Cloud-Connected Computational Platforms:Vendors are replacing dedicated hardware processors with software-based architectures, unlocking margin expansion through remote updates and predictive maintenance capabilities.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Transducer manufacturing depends on specialized ceramic supply chains concentrated in East Asian material processing facilities, exposing procurement to geopolitical friction.
- EPA Electronic Waste Disposal Mandates:Decommissioned ultrasound systems and transducer gel disposal trigger hazardous waste compliance costs that inflate total cost of ownership for US healthcare facilities.
- Portable Device Reimbursement Compression:CMS physician fee schedule adjustments for point-of-care applications create pricing pressure that constrains margin realization on handheld units.
Strategic Opportunities
- IRA Hospital Infrastructure Incentives:Federal modernization funding is creating procurement windows for imaging equipment refresh cycles across US health systems.
- Emergency Department Bedside Mobility:Underserved rural clinics and urban trauma centers present expansion vectors for portable ultrasound deployment.
- AI-Assisted Image Reconstruction Convergence:Integration of machine learning algorithms with real-time acoustic processing is opening diagnostic accuracy gaps that premium vendors can monetize.
Industry Challenges
- Sonographer Workforce Pipeline Constraints:Specialized training program capacity limitations are restricting operational scaling for high-volume imaging departments.
- Legacy PACS Integration Complexity:Cloud-native ultrasound platforms face interoperability friction with entrenched hospital picture archiving systems, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ultrasound Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, 3D Ultrasound, Portable Ultrasound Technology: Analog, Digital, Hybrid, Software-based End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Application: Obstetrics, Cardiology, Urology, Musculoskeletal |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Mindray Medical International Ltd., Hitachi Medical Corporation, Esaote S.p.A., Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ultrasound Devices Market Evolving Landscape
Artificial intelligence is embedding into diagnostic workflows at the point of image acquisition, shifting value capture from hardware performance specifications to software-enabled clinical decision support.
AI-enhanced diagnostic software is digitizing real-time anatomical interpretation by automating lesion detection and measurement protocols. Emergency departments and cardiology suites across the US Northeast are deploying these tools to reduce interpretation latency. The technology is digitizing traditional radiologist workflow steps, compressing time-to-diagnosis metrics while expanding addressable clinical settings.
FDA premarket notification requirements under 510(k) pathways are evolving to accommodate software-as-medical-device submissions, creating regulatory precedent for iterative algorithm updates without full hardware revalidation. This framework is accelerating vendor release cycles for image reconstruction improvements. Cardiology application segments are responding by prioritizing vendors with established AI clearance portfolios.
Subscription-based service contracts are displacing traditional capital procurement and break-fix maintenance arrangements across US hospital systems. Purchasing committees now evaluate total cost of ownership over five-to-seven year horizons rather than upfront equipment expenditure. This behavioral shift is most pronounced in Midwest hospital corridors where consolidated health systems wield centralized procurement authority.
North America Ultrasound Devices Market Segmentation
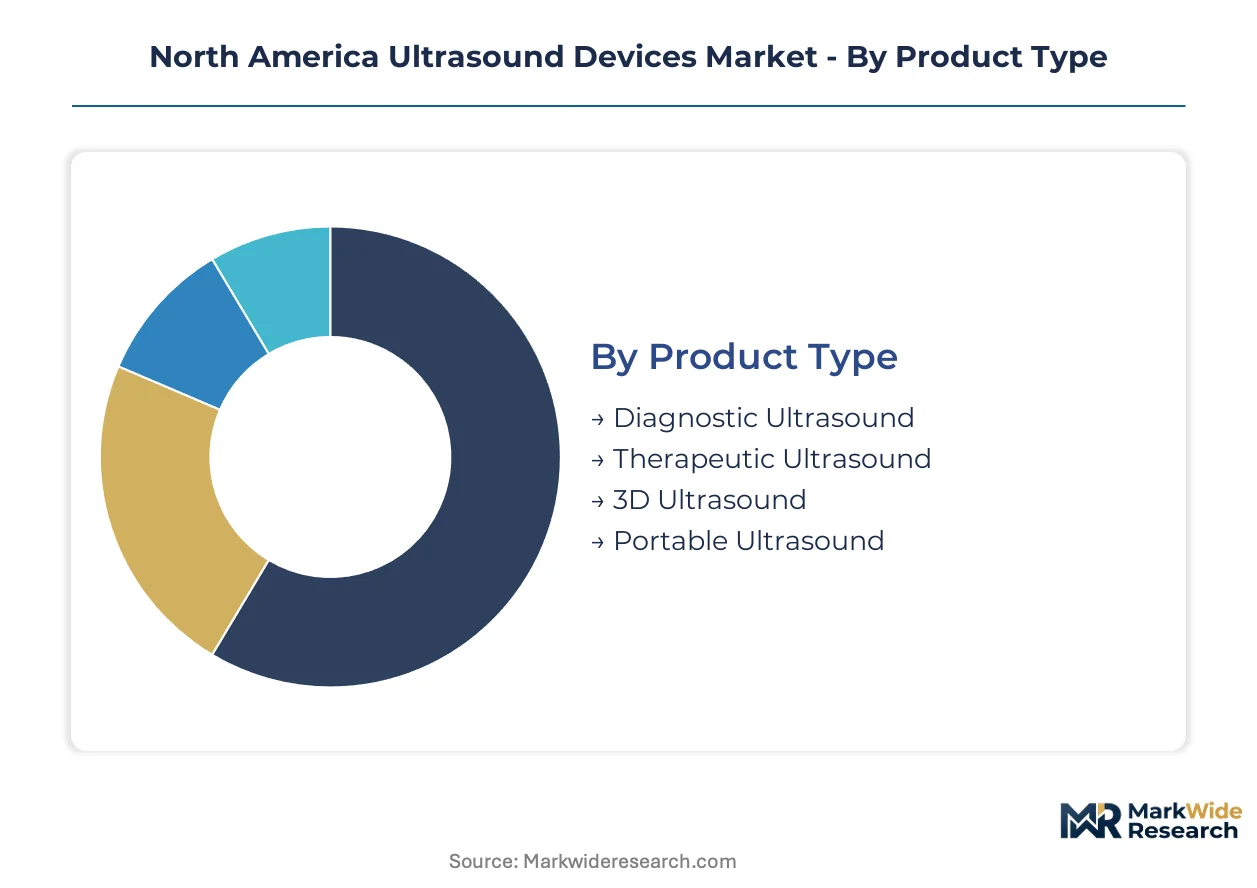
Ultrasound device segmentation reveals how procurement priorities diverge across care settings and clinical workflows. Understanding these divides allows vendors to align hardware specifications, software architectures, and service models with distinct buyer economics.
Product Type:
Cost tiers separate capital-intensive fixed installations from mobility-optimized units, with reimbursement codes and infrastructure requirements determining viable price points.
- Diagnostic Ultrasound:Cart-based systems with multi-frequency transducer arrays and dedicated hardware processors anchor radiology department capital budgets. US hospital systems in the Midwest and Northeast corridors prioritize these units for high-volume cardiac and abdominal imaging workflows.
- Portable Ultrasound:Handheld and laptop-configured devices with battery-powered operation and wireless connectivity are penetrating emergency departments and rural clinics. CMS reimbursement compression for point-of-care applications constrains margin realization despite volume expansion.
- Therapeutic Ultrasound:Phonophoresis and thermal ablation systems target physical therapy and interventional oncology applications.
- 3D Ultrasound:Volume rendering systems with matrix array transducers enable fetal anomaly screening and procedural planning.
Diagnostic ultrasound commands the established base. The steepest expansion runs through portable ultrasound.
Technology:
Architecture maturity determines margin structure, with software-defined platforms capturing recurring revenue through cloud-connected update cycles.
- Digital:Fully digitized beamformers with FPGA-based processing and software-defined image reconstruction dominate new system deployments. US health systems consolidating procurement authority favor these platforms for remote diagnostic support and predictive maintenance capabilities.
- Software-based:Cloud-native computational architectures replace dedicated hardware processors with edge-to-cloud processing pipelines. FDA 510(k) pathway evolution for software-as-medical-device submissions accelerates iterative algorithm deployment without full hardware revalidation.
- Analog:Legacy beamformer designs with discrete component processing persist in cost-constrained refurbishment markets.
- Hybrid:Mixed-signal architectures bridge analog front-ends with digital back-end processing for transitional upgrade paths.
Digital platforms anchor current procurement. The steepest climb is occurring in software-based architectures.
End User:
Customer scale and purchasing authority reshape vendor go-to-market economics, with consolidated health systems extracting volume concessions unavailable to fragmented buyers.
- Hospitals:Integrated delivery networks with centralized capital committees negotiate multi-year enterprise agreements spanning radiology, cardiology, and emergency department deployments. IRA infrastructure incentives are accelerating refresh cycles across US health systems.
- Clinics:Outpatient facilities and ambulatory surgical centers are migrating imaging volume from inpatient settings. Point-of-care adoption intensifies as procedural economics favor same-day discharge protocols.
- Diagnostic Centers:Independent imaging facilities with specialized service lines and direct consumer access models.
- Research Institutions:Academic medical centers with NIH-funded translational imaging programs and protocol development mandates.
Hospitals retain the volume concentration. The fastest share gains are appearing in clinics.
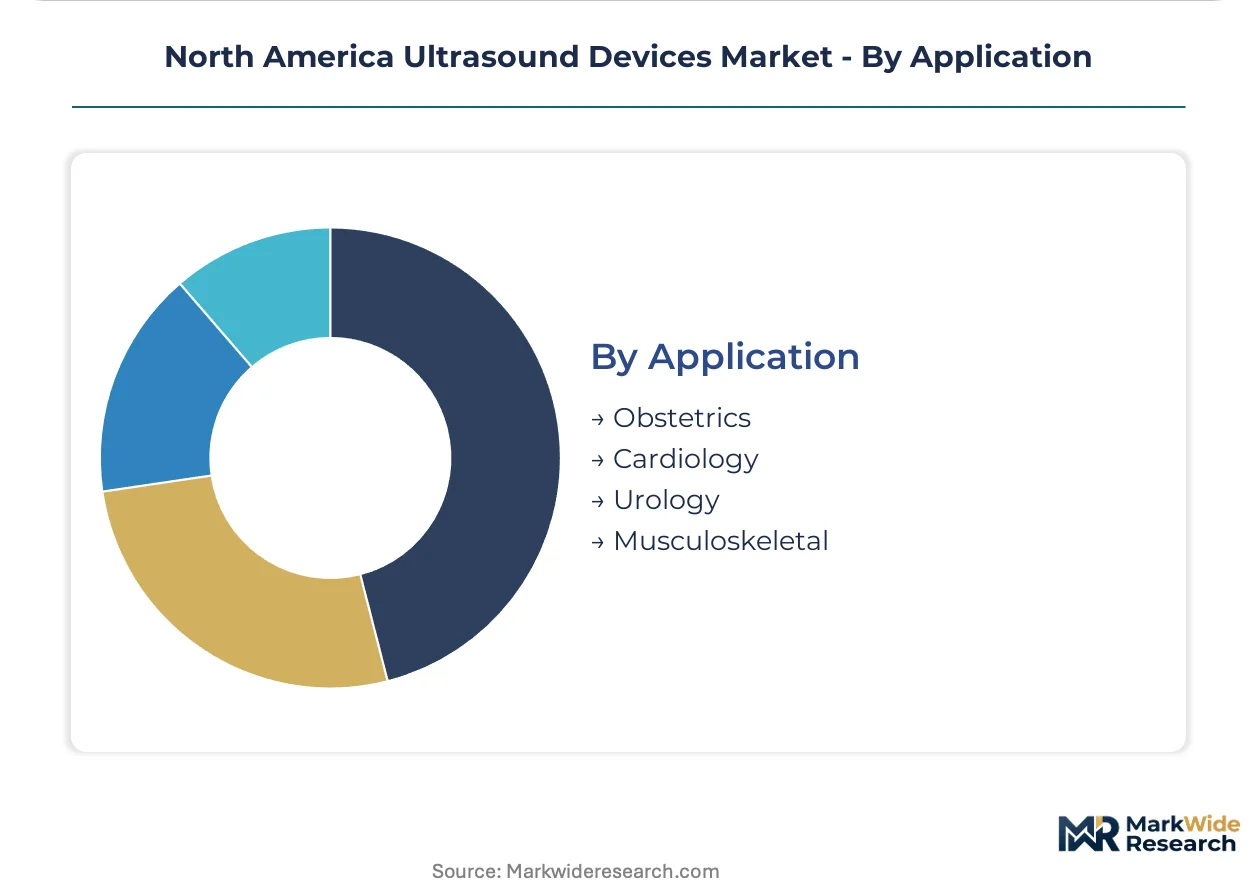
Application:
Clinical specificity dictates transducer configuration, software module requirements, and reimbursement pathway complexity.
- Cardiology:Echocardiography systems with phased array transducers and spectral Doppler capabilities command premium pricing. AI-assisted image reconstruction is opening diagnostic accuracy gaps that vendors monetize through subscription-tier software licensing.
- Obstetrics:Fetal imaging protocols with biometric measurement automation and 3D/4D rendering packages. Sonographer workforce pipeline constraints restrict operational scaling for high-volume maternal-fetal medicine departments.
- Urology:Transrectal and transabdominal imaging for prostate assessment and renal function evaluation.
- Musculoskeletal:High-frequency linear array systems for tendon, ligament, and joint surface imaging in sports medicine and rheumatology practices.
Cardiology anchors premium revenue pools. Obstetrics is climbing fastest on AI-enabled workflow compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the North American ultrasound market. Canadian buyers prioritize total cost of ownership, while US health systems absorb premium pricing for AI-enabled platforms. Mexican procurement concentrates on refurbished systems and mid-tier portable units.
United States
US hospital systems drive premium-tier demand for AI-assisted echocardiography and elastography systems. FDA 510(k) pathway acceleration compresses commercialization timelines for software-as-medical-device submissions. The Northeast and Midwest hospital corridors anchor high-volume cardiac imaging deployments across integrated delivery networks.
Canada
Canadian provincial health authorities emphasize cost containment through centralized procurement and extended equipment lifecycles. Health Canada regulates device licensing through the Medical Devices Bureau, with alignment to FDA standards easing cross-border vendor entry. Ontario and Quebec health systems lead adoption of portable ultrasound for rural and remote clinic networks.
Mexico
Mexican healthcare facilities prioritize accessible imaging through refurbished diagnostic systems and handheld portable units. COFEPRIS medical device registration requirements govern importation and commercialization timelines for foreign manufacturers. Mexico City and Monterrey metropolitan areas concentrate private hospital investment in radiology infrastructure modernization.
North America Ultrasound Devices Market Competitive Landscape
Full-line imaging conglomerates and specialized ultrasound pure-plays split the North American market. Consolidation around three dominant strategic archetypes defines competitive positioning: diversified medical technology conglomerates with radiology suite integration, dedicated diagnostic imaging specialists with workflow-embedded AI, and emerging Asian manufacturers competing on portable device cost structures. M&A activity targets AI software capabilities, while strategic partnerships with cloud infrastructure providers accelerate platform transitions.
Among diversified conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify the installed-base leverage archetype, anchoring recurring revenue through software-subscription bundling. Siemens Healthineers occupies a position within the premium-tier specialist segment. These three entities represent the dominant competitive anchors shaping procurement committee evaluations across US health systems.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Mindray Medical International Ltd. |
| Hitachi Medical Corporation |
| Esaote S.p.A. |
| Hologic Inc. |
| Others |
Value Network & Pricing Analysis
Tariff exposure on East Asian ceramic substrates determines both the spread between premium cart-based systems and economy portable units and the geographic configuration of transducer assembly networks. Procurement committees at US health systems now weight total landed cost against FDA clearance timelines when selecting between domestic final-assembly and offshore component sourcing strategies.
Pricing Analysis
Software-subscription tiers now drive lifetime value capture, with vendors bundling predictive maintenance and AI module updates into recurring contracts that exceed original hardware margins over five-to-seven year horizons. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled echocardiography platforms from digital beamformer workhorses and refurbished analog systems. Cost compression in the portable segment intensifies because CMS reimbursement compression for point-of-care applications constrains pricing power. Rural clinics and ambulatory surgical centers exhibit highest price sensitivity, while integrated delivery networks in the Midwest corridor absorb premium positioning for cardiology suites.
Supply Chain Analysis
Piezoelectric ceramic feedstock draws from Japan, South Korea, and China's specialized material processing facilities, with PZT formulations and single-crystal PMN-PT substrates anchoring transducer performance tiers. Assembly of FPGA-based beamformers rests on Taiwanese semiconductor foundries, while final system integration concentrates in US and Mexican manufacturing corridors. Single-source vulnerability in ceramic substrate supply exposes procurement timelines to geopolitical friction and export licensing delays. Distribution runs through manufacturer-direct enterprise contracts for hospital systems, with regional distributors serving fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care imaging modalities threaten diagnostic ultrasound's procedural monopoly, forcing incumbents to defend installed-base relationships through software-embedded switching costs and workflow integration depth.
For Market Incumbents: Insulate recurring revenue streams by deepening AI-assisted image reconstruction subscriptions within existing radiology suite deployments. Pursue backward integration into transducer ceramic supply through offtake agreements with Japanese material processors to secure PZT substrate allocation. Defend against handheld portable entrants by embedding cloud-native platforms into entrenched PACS infrastructure, raising interoperability barriers for challengers. For New Entrants and Emerging Players: Build out emergency department bedside mobility offerings targeting rural clinic networks and urban trauma centers underserved by capital-intensive cart-based vendors. The most penetrable white-space sits in ambulatory surgical center point-of-care adoption, where procedural volume migration from inpatient settings creates procurement windows. Pursue FDA 510(k) clearance for AI-enhanced diagnostic software as the primary go-to-market angle, leveraging streamlined regulatory pathways to compress commercialization timelines against hardware-centric incumbents. For Investors and Strategic Acquirers: Cloud-native ultrasound software specialists with established FDA clearance portfolios represent the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on recurring revenue mix and health system purchasing committee relationships rather than hardware shipment volumes. Monitor CMS physician fee schedule adjustments for point-of-care reimbursement codes as the critical inflection signal for portable segment margin expansion or compression. Cross-checking against hospital procurement database trends is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Diagnostic Software Development | FDA 510(k) pathway acceleration enables iterative algorithm deployment without hardware revalidation cycles. |
| Cloud-Native Platform Migration | Software-defined architectures unlock remote diagnostic support and predictive maintenance revenue streams across US health systems. |
| Transducer Supply Security | Long-term ceramic substrate agreements with East Asian material processors mitigate geopolitical procurement risk. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks anchor multi-year refresh cycles and subscription bundling. |
| Point-of-Care Reimbursement Strategy | CMS physician fee schedule engagement shapes adoption economics for portable ultrasound in ambulatory settings. |
Research Methodology
The analysis maps diagnostic ultrasound systems, portable units, and therapeutic platforms, each validated through hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and sonography department heads. Primary intelligence combines with secondary validation from FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement records, and EPA hazardous waste disposal compliance filings. Bottom-up shipment estimates triangulate against top-down health system capital expenditure surveys to anchor volume projections.
The forecast framework holds FDA regulatory timelines, IRA infrastructure incentive disbursement patterns, and sonographer workforce graduation rates within observed trajectories while varying AI adoption curves and cloud platform penetration assumptions across the projection horizon. Segmentation dimensions span product type, technology architecture, end-user scale, and clinical application with regional regulatory cluster overlays. CAGRs derive from logistic diffusion modeling of software-subscription adoption against hardware replacement cycles, with inputs from health system IT modernization budgets and ambulatory surgical center formation rates.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by emerging Asian portable manufacturers or accelerated AI diagnostic software convergence by technology entrants would shift outcomes beyond modeled ranges. Cross-checking against hospital capital expenditure tracking databases and health system earnings call commentary is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Korea ECG Market
Medical Devices
Global Concussion Market
Medical Devices
Cyberknife Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
EEG Electrodes Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Morcellators Market
Medical Devices
Catheter Coatings Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market