
 Next Generation Optical Biometry Devices Market | 2026-2036
Next Generation Optical Biometry Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Optical Biometry Devices Market Foresight
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between established manufacturers and emerging entrants. Carl Zeiss leverages its vertically integrated optics manufacturing to sustain premium positioning in wavefront-enabled biometry systems. Nidek anchors its presence across Asia-Pacific through localized service networks and Scheimpflug-based anterior segment analysis. Haag-Streit competes on precision engineering heritage, dominating manual and automated keratometry integration within surgical workflows.
Next generation optical biometry devices employ low-coherence interferometry or partial coherence interferometry to measure axial length, corneal curvature, and anterior chamber depth with sub-micron precision for intraocular lens power calculation. The technology enables preoperative planning that reduces refractive prediction errors below 0.25 diopters in cataract surgery. Measuring instruments and imagers command the largest revenue pools due to replacement cycles tied to excimer laser suite upgrades, while optical coherence tomography biometry represents the fastest-expanding technology segment as surgeons adopt depth-resolved tissue visualization. Cataract surgery applications absorb the majority of installed base depreciation, though glaucoma diagnosis is gaining share through multi-modal device platforms that consolidate anterior and posterior segment assessment.
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures govern market access timelines and clinical evidence requirements for optical biometry devices in the United States and Europe. Japan's PMDA enforces Japan Medical Device Nomenclature standards that complicate registration for foreign manufacturers lacking domestic quality system audits. Stakeholders must monitor evolving reimbursement coding for optical biometry as separate from bundled cataract surgery payments across Medicare, NHS England, and Japan's MHLW fee schedules.
Market Dynamics
Swept-source optical coherence tomography biometry is fragmenting the installed base of partial coherence interferometry systems across metropolitan hospital networks in the United States, China, and India, compressing replacement cycles and forcing manufacturers to defend service revenue through software lock-in strategies.
Growth Catalysts
- EU MDR Conformity Assessment:Stricter premarket approval pathways in Germany are accelerating clinic-level upgrades to ISO 13485-certified swept-source platforms that satisfy notified body clinical evidence requirements.
- Cataract Surgery Volume Concentration:Metropolitan hospital networks in India and China are consolidating ophthalmology services, creating procurement pools large enough to justify premium biometry system investments.
- Axial Length Precision Standards:Sub-micron measurement protocols for intraocular lens power calculation are decommissioning first-generation optical biometers in Japan's PMDA-regulated facilities.
Market Restraints
- Supercontinuum Laser Source Concentration:Swept-source engine manufacturing concentrates among Japanese and German photonics suppliers, exposing device makers to input cost volatility and allocation risk.
- Japan Medical Device Nomenclature Friction:PMDA's classification standards complicate registration for foreign manufacturers lacking domestic quality system audits, extending market access timelines.
- Excimer Laser Suite Tethering:Biometry system procurement remains captive to refractive surgery platform replacement cycles, decoupling device demand from standalone clinical utility.
Strategic Opportunities
- Glaucoma Multi-Modal Convergence:Anterior segment analysis integration with posterior segment swept-source imaging is opening diagnostic workflows beyond cataract surgery in academic medical centers.
- India's PLI Scheme Alignment:Medical device manufacturing incentives are attracting component localization investments that could reshape Asia-Pacific supply chain configuration for optical subassemblies.
- Tele-ophthalmology Screening Channels:Mobile diagnostic units equipped with portable biometry modules are penetrating rural catchment areas previously excluded from surgical planning services.
Industry Challenges
- FDA 510(k) Clinical Evidence Burden:Substantial equivalence determinations for next-generation algorithms require predicate device matching that delays software-enabled feature releases.
- ISO 13485 Audit Backlogs:Notified body capacity constraints are extending certification timelines for emerging manufacturers seeking European market access.
- Legacy Keratometry Integration:Surgical workflow dependencies on manual and automated keratometry systems create interoperability friction during biometer upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Optical Biometry Devices Market |
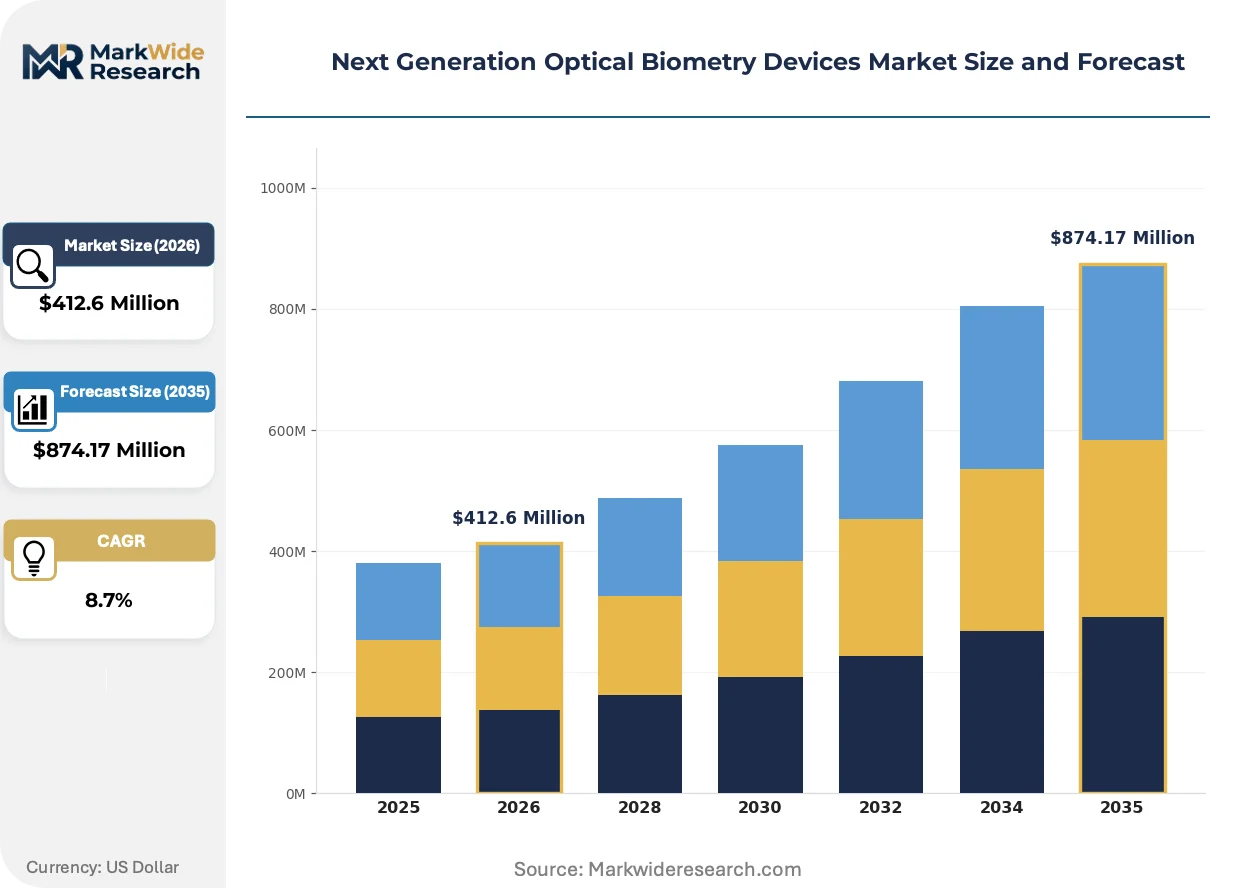
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Refractive Devices, Measuring Instruments, Imagers, Analyzers End User: Hospitals, Clinics, Optical Centers, Research Labs Technology: Wavefront Aberrometry, Optical Coherence Tomography, Scheimpflug Imaging, Ultrasound Biometry Application: Cataract Surgery, Glaucoma Diagnosis, Vision Correction, Eyewear Prescription |
| Companies Covered | Carl Zeiss, Nidek, Haag-Streit, Ziemer Ophthalmic Systems, Topcon, Optovue, Tomey GmbH, Movu, OCULUS Optikgeräte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Optical Biometry Devices Market Shifts & Advancements
Optical biometry is undergoing platform-level reconstruction as measurement modalities converge with diagnostic imaging and regulatory frameworks force clinical evidence upgrades. Three forces are compressing competitive position.
Artificial intelligence-enabled intraocular lens power calculation is decomposing the historical dominance of regression-based formulas in premium cataract surgery planning. Academic medical centers in Germany and Japan are piloting machine learning-trained prediction models that reduce refractive error variance. This capability is compressing differentiation among biometer hardware manufacturers and shifting value capture toward proprietary software ecosystems.
EU MDR's enhanced clinical evidence requirements for Class IIa medical devices are extending conformity assessment timelines for optical biometry systems seeking European market access. Notified bodies are demanding prospective validation studies that predicate devices under the Medical Devices Directive avoided. Manufacturers with legacy ISO 13485 certifications are accelerating post-market surveillance infrastructure investments to satisfy periodic safety update report obligations.
After-sales service unbundling is disrupting traditional capital equipment purchasing in United States outpatient surgery centers. Buyers are separating hardware acquisition from maintenance contracts and software subscriptions, forcing manufacturers to defend recurring revenue through predictive uptime guarantees rather than captive service lock-in. This pattern is most visible in ophthalmology clinic chains negotiating multi-site fleet deployments across Texas and Florida metropolitan corridors.
Next Generation Optical Biometry Devices Market Segmentation
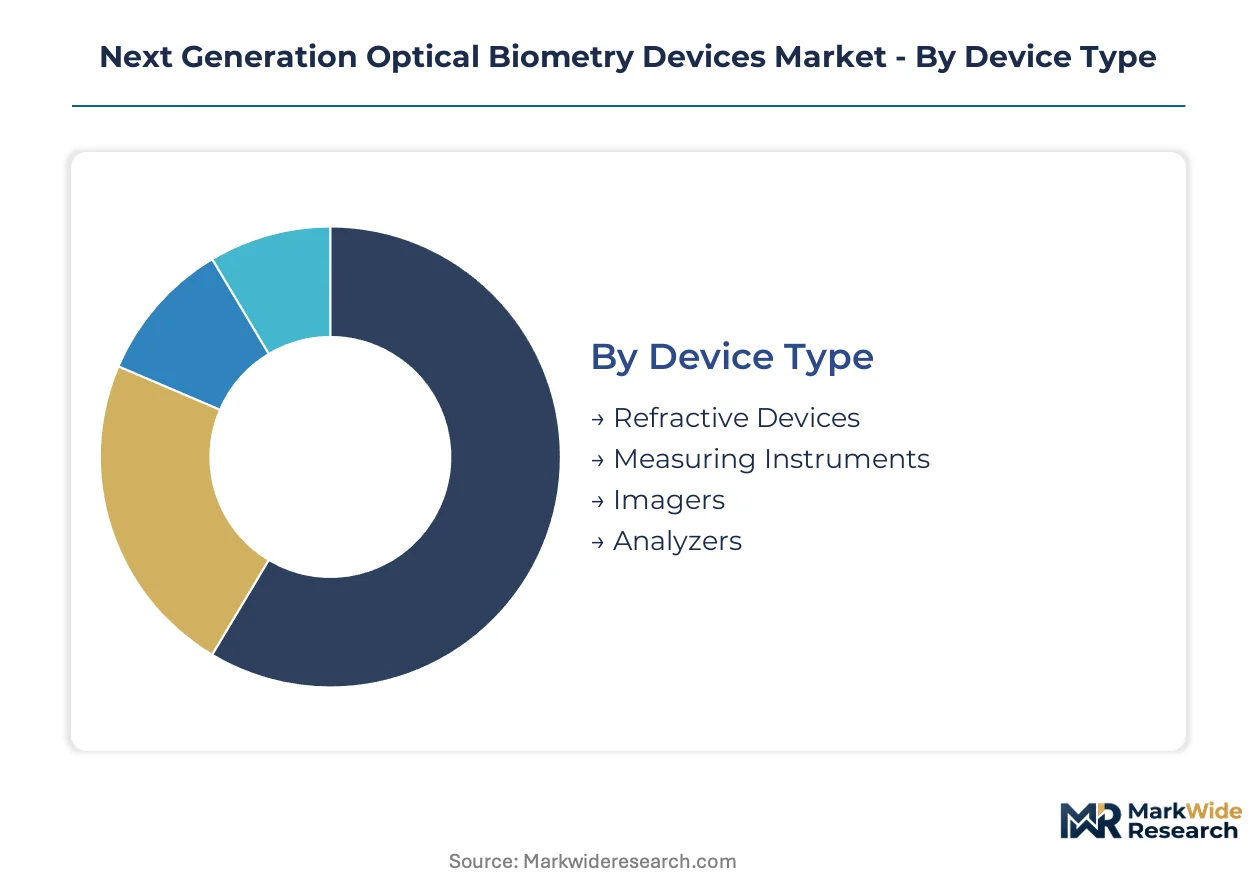
Optical biometry device purchasing concentrates around surgical workflow integration and reimbursement bundling patterns. Segmentation reveals how technology modality and clinical setting determine procurement specifications and replacement cycles across metropolitan hospital networks.
Device Type:
Domestic production of imagers and analyzers clusters in Germany and Japan for EU MDR and PMDA-certified supply chains, while refractive devices and measuring instruments flow through multinational assembly networks serving United States and China demand centers.
- Measuring Instruments:Low-coherence interferometry systems deliver sub-micron axial length precision for intraocular lens power calculation. Procurement concentrates in United States metropolitan hospital networks where excimer laser suite upgrades drive synchronized replacement cycles.
- Imagers:Depth-resolved tissue visualization platforms integrate swept-source optical coherence tomography engines. Demand accelerates across ophthalmology clinics in Germany and Japan pursuing stricter notified body clinical evidence requirements under EU MDR and PMDA pathways.
- Refractive Devices:Wavefront-enabled systems dominate premium cataract surgery planning in academic medical centers.
- Analyzers:Scheimpflug-based anterior segment analysis tools anchor corneal diagnostic workflows in Asia-Pacific service networks.
Measuring instruments command the established base. The steepest expansion runs through imagers.
End User:
Cost tier stratification separates capital-intensive hospital procurement from outpatient clinic leasing arrangements and research laboratory grant-funded acquisitions.
- Hospitals:Metropolitan networks in India and China consolidate ophthalmology services into procurement pools justifying premium biometry system investments. Multi-modal platform deployment satisfies bundled cataract surgery reimbursement coding across Medicare, NHS England, and Japan MHLW fee schedules.
- Clinics:Ophthalmology clinics in Germany upgrade to swept-source platforms meeting EU MDR conformity assessment timelines. After-sales service unbundling disrupts traditional capital equipment purchasing in United States outpatient surgery centers separating hardware acquisition from maintenance contracts.
- Optical Centers:Eyewear prescription workflows drive compact footprint device demand with simplified operator training protocols.
- Research Labs:Academic medical centers in Germany and Japan pilot artificial intelligence-enabled intraocular lens power calculation models.
Hospitals absorb the majority of installed base depreciation. Clinics are climbing the fastest as surgical volume migrates to outpatient settings.
Technology:
Volume concentration favors optical coherence tomography biometry as surgeons adopt depth-resolved visualization, while wavefront aberrrometry retains premium positioning in refractive surgery planning.
- Optical Coherence Tomography:Swept-source engines enable simultaneous anterior and posterior segment assessment. Adoption concentrates across metropolitan hospital networks in United States, China, and India where multi-modal diagnostic platforms consolidate glaucoma and cataract workflows.
- Wavefront Aberrometry:High-order aberration measurement guides custom excimer laser ablation profiles. Demand localizes in premium cataract surgery centers pursuing refractive prediction errors below 0.25 diopters.
- Scheimpflug Imaging:Rotating camera systems capture corneal topography and anterior chamber depth for toric intraocular lens planning.
- Ultrasound Biometry:Immersion and contact modes serve dense cataract cases where optical methods fail.
Optical coherence tomography commands the established base. The steepest expansion runs through wavefront aberrometry as artificial intelligence-enabled calculation models reduce refractive error variance.
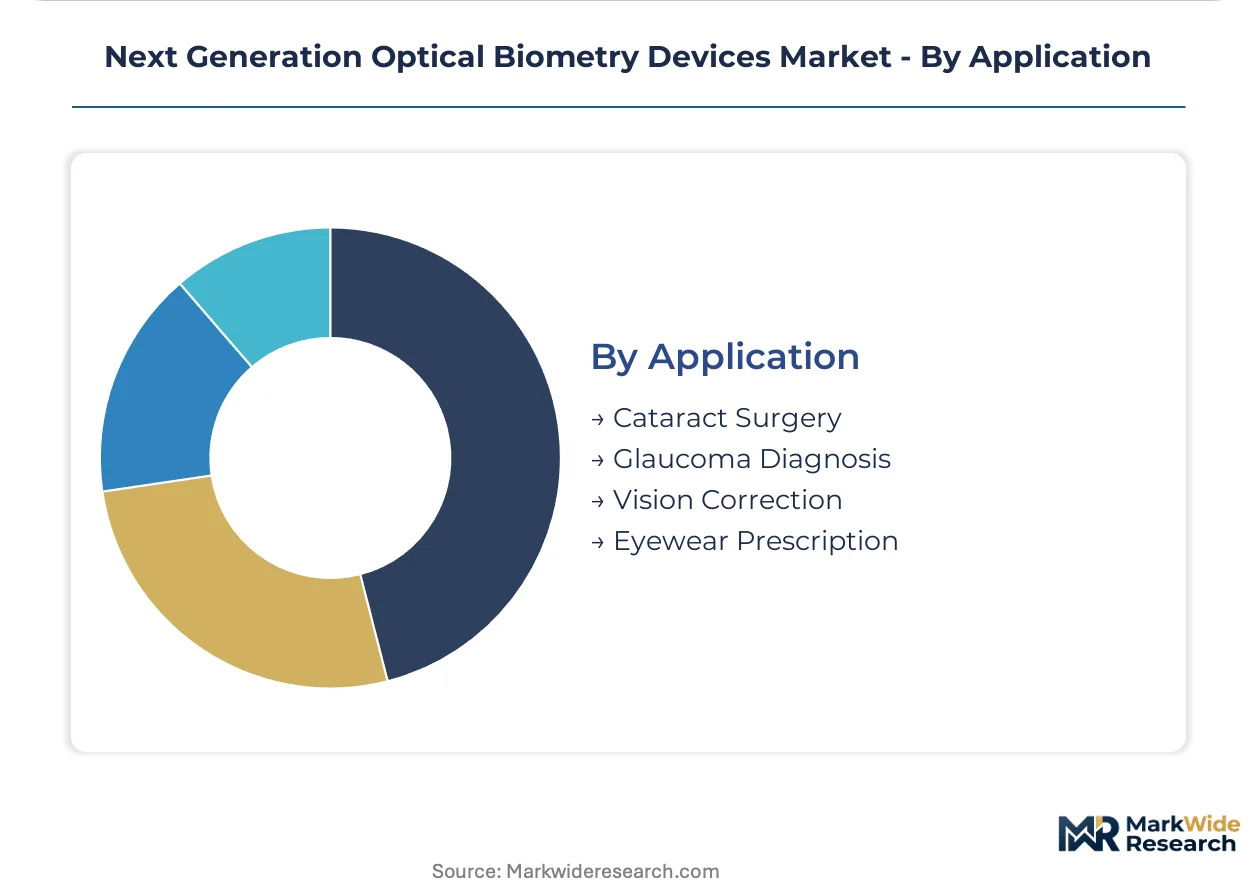
Application:
Customer type differentiation separates surgical planning reimbursement from diagnostic screening fee schedules and vision correction consumer payments.
- Cataract Surgery:Preoperative axial length, corneal curvature, and anterior chamber depth measurement enables intraocular lens power calculation. Application absorbs majority of installed base depreciation across United States, China, and India metropolitan networks.
- Glaucoma Diagnosis:Multi-modal device platforms consolidate anterior and posterior segment assessment. Academic medical centers in Germany and Japan integrate swept-source imaging with tele-ophthalmology screening channels penetrating rural catchment areas.
- Vision Correction:Refractive surgery planning drives wavefront-enabled biometry system specifications.
- Eyewear Prescription:Automated refraction and keratometry support optical center workflow efficiency.
Cataract surgery commands the established base. Glaucoma diagnosis is gaining share fastest through platform convergence strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device manufacturing incentives and stricter notified body requirements are redrawing procurement patterns across major ophthalmology markets. National reimbursement frameworks and premarket approval pathways now determine upgrade cycles for biometry systems in metropolitan hospital networks.
United States
Metropolitan hospital networks in Texas and Florida concentrate cataract surgery volumes that justify premium biometry system investments. FDA 510(k) clearance pathways govern software-enabled feature releases for next-generation algorithms. Outpatient surgery centers across the Southeast and Southwest are unbundling after-sales service from hardware acquisition.
Germany
Ophthalmology clinics in Bavaria and North Rhine-Westphalia are accelerating upgrades to swept-source platforms that satisfy EU MDR conformity assessment timelines. ISO 13485 certification requirements are bifurcating the competitive landscape between established manufacturers and emerging entrants. The Stuttgart and Munich metropolitan corridors anchor precision optics manufacturing clusters serving domestic and export demand.
Japan
PMDA premarket approval pathways enforce Japan Medical Device Nomenclature standards that complicate registration for foreign manufacturers. Sub-micron measurement protocols for intraocular lens power calculation are decommissioning first-generation optical biometers in Kanto and Kansai region facilities. Tokyo and Osaka academic medical centers pilot artificial intelligence-enabled calculation models.
China
Metropolitan hospital networks in Beijing and Shanghai are consolidating ophthalmology services into procurement pools large enough to justify multi-modal platform investments. NMPA registration standards for Class II medical devices shape market access timelines for imported biometry systems. The Yangtze River Delta manufacturing corridor is attracting component localization investments under medical device manufacturing incentives.
India
Cataract surgery volume concentration across Maharashtra and Tamil Nadu is creating procurement pools for premium biometry system investments. CDSCO medical device registration requirements and state-level healthcare infrastructure programs shape distribution patterns. The Delhi-NCR and Bengaluru clusters are emerging as service hubs for Asia-Pacific ophthalmology equipment deployment.
Next Generation Optical Biometry Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The market structure concentrates around precision optics heritage and vertically integrated manufacturing capabilities. Three archetypes dominate: diversified medical technology conglomerates, specialized ophthalmology equipment manufacturers, and precision engineering firms with surgical workflow integration. M&A activity targets software-enabled diagnostic platforms, while strategic partnerships secure swept-source engine supply from Japanese and German photonics suppliers.
Within the diversified conglomerate tier, Carl Zeiss AG exemplifies vertically integrated optics manufacturing that sustains premium positioning. Among specialized ophthalmology equipment manufacturers, Nidek Co., Ltd. and Haag-Streit Holding AG occupy positions anchored by localized service networks and precision engineering heritage respectively. These three entities represent distinct competitive vectors: captive supply chain control, Asia-Pacific geographic density, and surgical workflow integration.
| Leading Market Players |
|---|
| Carl Zeiss |
| Nidek |
| Haag-Streit |
| Ziemer Ophthalmic Systems |
| Topcon |
| Optovue |
| Tomey GmbH |
| Movu |
| OCULUS Optikgeräte GmbH |
| Others |
Supply & Pricing Matrix
Ninety-day component lead times for swept-source laser engines concentrate pricing power among German and Japanese photonics suppliers, compressing margins for device assemblers while ISO 13485 certification premiums widen spreads between established and emerging manufacturers. This inventory-to-certification nexus forces buyers into long-term offtake commitments or spot-market exposure.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-certified systems and uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance status, EU MDR conformity, and after-sales bundling. Cost compression in economy tiers intensifies as outpatient surgery centers unbundle service contracts from hardware acquisition. Price-sensitive buyers cluster in India's state-level procurement pools, while least-sensitive demand concentrates in United States academic medical centers pursuing AI-enabled calculation platforms.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for optical subassemblies sourced from Japanese and German photonics clusters. Swept-source engine manufacturing concentrates in Japan, Germany, and the United States, drawing from supercontinuum laser sources, precision optics, and scan mirror assemblies. Single-source vulnerability runs through Japanese swept-source engine suppliers exposed to allocation risk. Distribution runs through authorized service networks anchored in metropolitan hospital procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 13485-certified swept-source engineering talent concentrates competitive advantage among manufacturers with vertically integrated optics heritage, forcing latecomers into costly certification timelines or partnership dependency.
For Market Incumbents: Consolidate service revenue through predictive uptime guarantees rather than captive lock-in strategies as United States outpatient surgery centers unbundle maintenance contracts. Deepen backward integration into supercontinuum laser source manufacturing to reduce exposure to Japanese supplier allocation risk. Prioritize EU MDR post-market surveillance infrastructure investments to satisfy periodic safety update report obligations ahead of emerging entrant certification completion. For New Entrants and Emerging Players: FDA 510(k) substantial equivalence fast-tracks offer the most penetrable pathway for algorithm-enabled software features bypassing predicate device matching delays. Target India's PLI scheme-aligned component localization clusters to establish Asia-Pacific service hub presence before multinational incumbents consolidate supply chain investments. Deploy tele-ophthalmology screening channel partnerships as primary go-to-market angle for rural catchment area penetration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core ophthalmology equipment divisions amid platform convergence pressures. Five-to-ten year viability favors specialized manufacturers with captive swept-source engine supply relationships over pure-play software entrants. Watch FDA 510(k) clearance velocity for AI-enabled intraocular lens calculation algorithms as inflection indicator for software value capture shifting from hardware manufacturers to proprietary ecosystem providers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Acceleration | Notified body clinical evidence requirements compress upgrade cycles across German ophthalmology clinic networks. |
| Swept-Source Engine Backward Integration | Captive supercontinuum laser manufacturing reduces allocation risk exposure from Japanese photonics suppliers. |
| AI-Enabled IOL Calculation Platform Launch | Machine learning-trained prediction models shift value capture from hardware to proprietary software ecosystems. |
| Tele-Ophthalmology Channel Partnership | Mobile diagnostic units penetrate rural catchment areas previously excluded from surgical planning services. |
| Service Contract Unbundling Response | Predictive uptime guarantees defend recurring revenue as United States outpatient surgery centers separate hardware from maintenance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, PMDA registration databases, and hospital procurement records. Interviews with cataract surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers inform demand-side validation. Bottom-up installed base modeling triangulates against top-down reimbursement coding analysis across Medicare, NHS England, and Japan MHLW fee schedules.
Segmentation dimensions modeled include device type, end-user facility tier, technology modality, and application workflow across the projection horizon. CAGRs derive from replacement cycle analysis tied to excimer laser suite upgrades and regulatory-driven decommissioning of first-generation biometers. Forecast inputs incorporate PMDA nomenclature friction coefficients and EU MDR conformity assessment timeline distributions.
Decision-makers should treat outputs as directional under assumptions of sustained cataract surgery volume concentration in metropolitan networks and stable swept-source engine supply allocation; material deviation would warrant model refresh. Specific risk factors include Japan Medical Device Nomenclature reclassification, supercontinuum laser source supply disruption, and reimbursement unbundling acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Medical Coatings Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Collateral Ligament Stabilizer System Market