
 Heel and Elbow Suspension Market | 2026-2036
Heel and Elbow Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Heel and Elbow Suspension Market Foresight
ISO 13485 certification cycles for medical device quality management is unwinding competitive access, forcing smaller manufacturers to either upgrade facilities or exit the market. Stryker Corporation leverages its orthopedic device ecosystem to bundle suspension products with surgical hardware. Medline Industries, Inc. anchors distribution through its acute-care supply contracts across North American hospital networks. Mölnlycke Health Care AB differentiates through silicone-foam composite technologies that reduce shear forces on at-risk tissue.
Heel and elbow suspension systems are pressure-redistribution medical devices engineered to elevate and cradle the calcaneus or olecranon process, typically employing viscoelastic polymers or gel-filled chambers that maintain microclimate control below 28°C surface temperature to prevent pressure injury formation. Orthotic Devices command the largest revenue share within product type segments due to standardized reimbursement codes, while Custom Fit Solutions utilizing 3D Printing technology represent the fastest-expanding margin pool as digital scanning replaces plaster casting in orthotic fabrication. Sports Medicine applications are gaining share among end users as athletic trainers adopt prophylactic suspension protocols for high-impact contact sports.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) CE marking pathways are elevating clinical evidence thresholds for new heel and elbow suspension entrants, compressing the addressable vendor base to firms with dedicated regulatory affairs capacity. ISO 10993 biocompatibility testing standards further constrain material selection, favoring suppliers with in-house polymer chemistry expertise over contract manufacturers. Stakeholders must monitor evolving pressure injury prevention protocols from the National Pressure Injury Advisory Panel and European Pressure Ulcer Advisory Panel as clinical guideline shifts directly alter device specification requirements in hospital tenders.
Market Dynamics
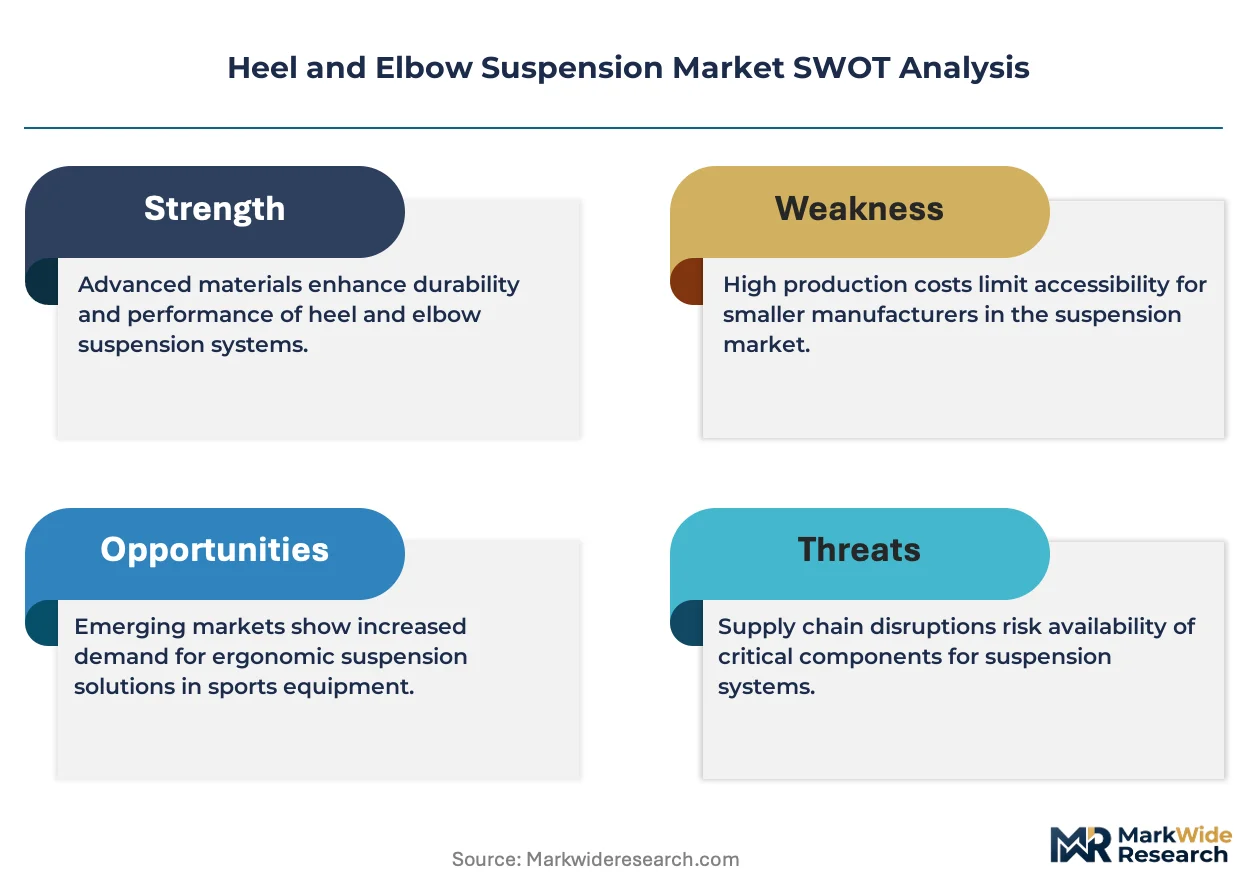
ISO 13485 certification cycles are compressing competitive access for heel and elbow suspension manufacturers, forcing facility upgrades or market exits while favoring incumbents with dedicated quality management infrastructure.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States are expanding chronic wound prevention spending in acute care settings, driving procurement of pressure-redistribution devices.
- FDA 510(k) Pathway:Tightening documentation requirements for Class II medical devices are elevating barriers to entry, protecting incumbent market positions.
- Silicone-Foam Composites:Advanced polymer technologies that reduce shear forces on at-risk tissue are differentiating premium product lines and commanding tender preference.
Market Restraints
- Biocompatibility Testing Costs:ISO 10993 standards constrain material selection, favoring suppliers with in-house polymer chemistry expertise over contract manufacturers.
- Regulatory Friction:EU MDR CE marking pathways are elevating clinical evidence thresholds, compressing the addressable vendor base to firms with dedicated regulatory affairs capacity.
- Substitution Threat:Low-cost foam positioning alternatives in long-term care facilities limit pricing power for engineered suspension systems in budget-constrained settings.
Strategic Opportunities
- 3D Printing Convergence:Digital scanning technologies replacing plaster casting in orthotic fabrication are opening margin expansion in custom-fit solutions.
- Sports Medicine Pivot:Athletic trainers in contact sports are adopting prophylactic suspension protocols, creating new end-use verticals beyond traditional post-operative care.
- Guideline-Driven Demand:National Pressure Injury Advisory Panel protocol updates directly alter device specifications in hospital tenders, creating first-mover advantages for specification-compliant suppliers.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Firms struggle to hire specialists capable of navigating simultaneous FDA 510(k) and EU MDR submission requirements.
- Legacy System Integration:Digital scanning workflows face friction integrating with established electronic health record systems in acute hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heel and Elbow Suspension Market |
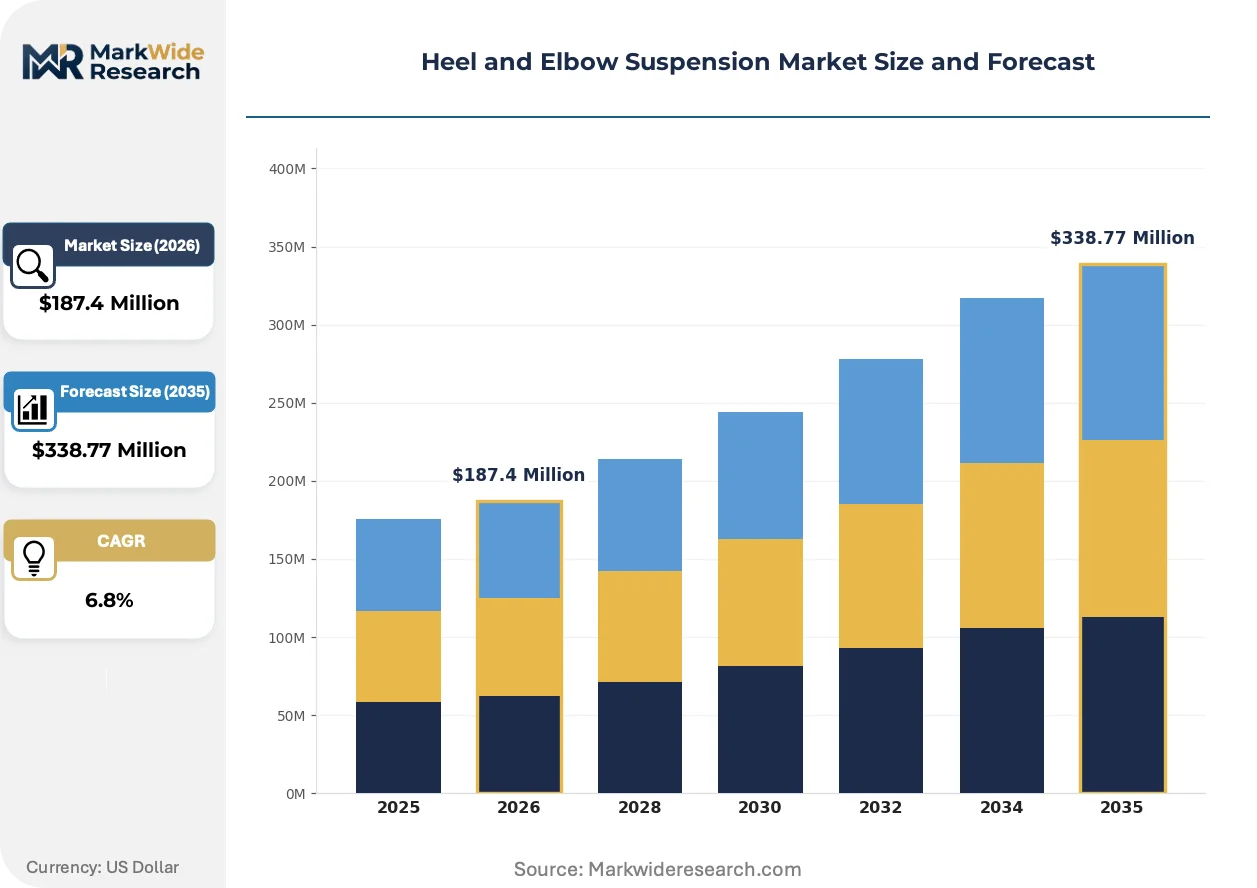
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Devices, Suspension Systems, Bracing Solutions, Padding Materials End User: Patients, Healthcare Professionals, Rehabilitation Centers, Sports Teams Technology: 3D Printing, Smart Materials, Traditional Manufacturing, Custom Fit Solutions Application: Sports Medicine, Post-Operative Care, Chronic Pain Management, Mobility Assistance |
| Companies Covered | Span-America Medical Systems, Inc., DeRoyal Industries, Inc., Stryker Corporation, Invacare Corporation, Mölnlycke Health Care AB, Medline Industries, Inc., EHOB, Inc., Smith & Nephew plc, AliMed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heel and Elbow Suspension Market Shifts & Advancements
Digital fabrication methods are displacing traditional casting workflows across heel and elbow suspension manufacturing, while regulatory harmonization pressures and shifting procurement authority reshape competitive positioning.
Sensor-embedded suspension systems are miniaturizing pressure monitoring capabilities into wearable form factors. Post-operative care units in acute hospitals are piloting these devices for real-time tissue perfusion tracking. The technology is miniaturizing hardware requirements and compressing device footprints to meet single-patient-use specifications.
EU MDR CE marking pathways are extending clinical evidence requirements for Class IIa medical devices. Manufacturers must now submit post-market surveillance data that previously satisfied FDA 510(k) pathways alone. Orthotic device segments face the steepest compliance cost escalation as notified body capacity constrains approval timelines.
Hospital procurement departments are consolidating supplier relationships through acute-care supply contract bundling. Group purchasing organizations are displacing direct manufacturer relationships for mid-tier suspension products. This concentration is most visible in North American health system networks where standardized reimbursement codes drive commoditization pressure.
Heel and Elbow Suspension Market Segmentation
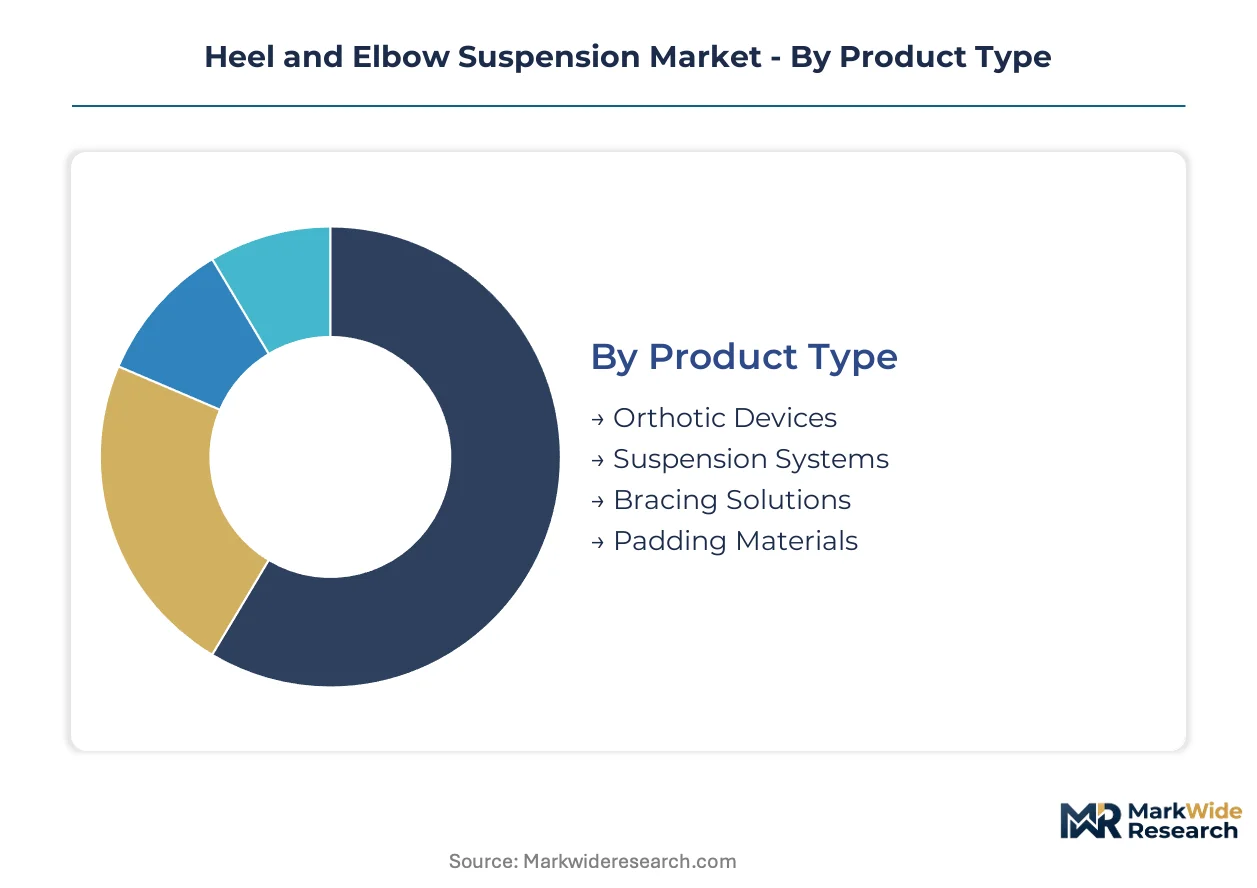
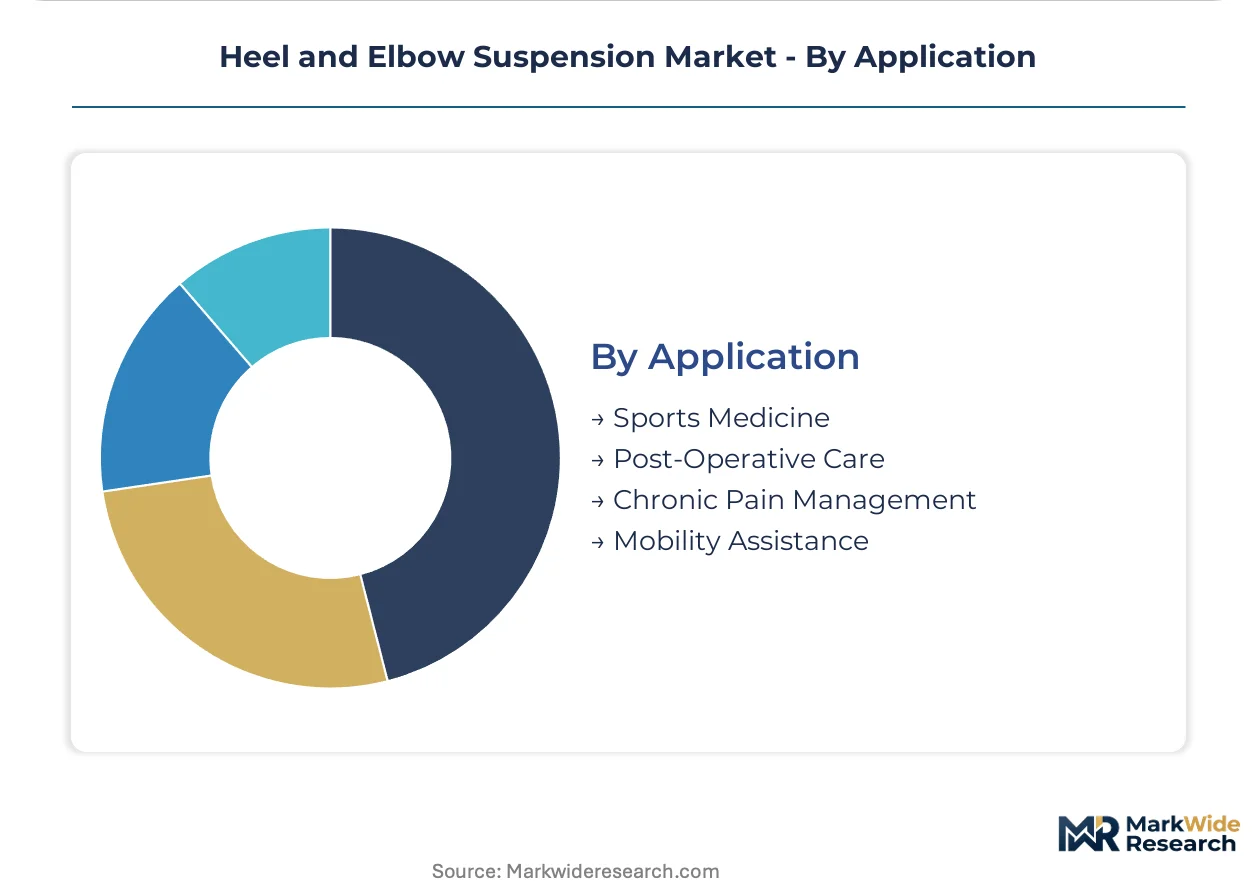
Segmentation in heel and elbow suspension markets reveals how reimbursement pathways, fabrication technologies, and end-use environments fragment demand. Procurement authority concentrates differently across acute hospitals, outpatient clinics, and athletic settings, shaping margin structures and competitive access.
Product Type:
Substitution pressure from low-cost foam positioning alternatives weighs most heavily on commodity segments, while premium engineered systems defend share through clinical evidence requirements.
- Orthotic Devices:Standardized prefabricated systems utilizing viscoelastic polymers and gel-filled chambers for pressure redistribution. Demand concentrates in United States acute care hospitals where Medicare reimbursement codes drive procurement standardization and volume contracting.
- Suspension Systems:Elevated cradle mechanisms engineered to maintain calcaneus or olecranon clearance with microclimate control below 28°C surface temperature. Germany and Japan are expanding procurement of these devices for chronic wound prevention in aging patient populations.
- Bracing Solutions:Structural support frameworks combining suspension with immobilization for post-operative protocols.
- Padding Materials:Disposable and reusable cushioning components subject to commodity pricing pressure in long-term care settings.
Orthotic Devices anchors the volume base while Suspension Systems gains share at the steepest rate.
End User:
Cost tier fragmentation separates institutional purchasers with dedicated wound care budgets from individual consumers facing out-of-pocket constraints.
- Healthcare Professionals:Hospital-based wound care specialists and orthopedic surgeons specifying devices for post-operative protocols. United States health system networks are consolidating supplier relationships through group purchasing organization contracts that displace direct manufacturer relationships.
- Rehabilitation Centers:Outpatient facilities managing chronic pressure injury prevention and mobility restoration. Japan's expanding geriatric rehabilitation infrastructure is driving procurement of sensor-embedded systems for real-time tissue perfusion monitoring.
- Patients:Individual consumers accessing devices through retail or durable medical equipment channels.
- Sports Teams:Athletic trainers in contact sports adopting prophylactic suspension protocols for injury prevention.
Healthcare Professionals commands the largest procurement volume while Sports Teams demonstrates the most rapid adoption trajectory.
Technology:
Supply concentration among polymer chemistry specialists favors segments requiring ISO 10993 biocompatibility certification.
- 3D Printing:Digital fabrication workflows replacing plaster casting in custom orthotic production. Germany's medical device manufacturing clusters are investing in scanning-to-print infrastructure for patient-specific suspension geometry.
- Smart Materials:Sensor-embedded polymers enabling real-time pressure and temperature monitoring. United States acute care pilots are validating these systems for post-operative tissue perfusion tracking.
- Traditional Manufacturing:Injection-molded and thermoformed components serving cost-sensitive procurement segments.
- Custom Fit Solutions:Patient-matched devices fabricated from digital scans, expanding margin pools as digital workflows displace manual casting.
Traditional Manufacturing retains the installed base while 3D Printing climbs the fastest toward commercial scale.
Application:
Maturity gradients separate established reimbursement pathways from emerging self-pay categories.
- Post-Operative Care:Acute hospital protocols for surgical recovery and pressure injury prevention. United States Medicare diagnosis-related group reimbursement sustains volume demand for standardized suspension systems.
- Sports Medicine:Prophylactic and therapeutic applications in athletic settings. Professional and collegiate sports programs in Germany and Japan are formalizing equipment standards for contact sport protection.
- Chronic Pain Management:Long-term positioning solutions for neuropathic and musculoskeletal conditions.
- Mobility Assistance:Devices supporting ambulatory function in elderly and disabled populations.
Post-Operative Care generates the revenue foundation while Sports Medicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in acute-care networks concentrate demand for suspension devices, with aging demographics and reimbursement pathways shaping geographic purchasing patterns. The United States, Germany, and Japan anchor volume procurement through established Medicare and statutory health insurance frameworks.
United States
Medicare diagnosis-related group reimbursement sustains standardized procurement of orthotic suspension systems across acute hospital networks. FDA 510(k) premarket notification requirements for Class II medical devices elevate documentation thresholds for new market entrants. The Minneapolis-St. Paul corridor hosts medical device manufacturing clusters where sensor-embedded suspension technologies undergo clinical validation.
Germany
Statutory health insurance expansion for chronic wound prevention drives procurement of elevated cradle mechanisms with microclimate control capabilities. EU MDR CE marking pathways extend clinical evidence requirements for Class IIa devices, compressing approval timelines. The Baden-Württemberg medical technology cluster advances digital scanning-to-print infrastructure for patient-specific orthotic fabrication.
Japan
Geriatric rehabilitation infrastructure expansion propels demand for real-time tissue perfusion monitoring systems in post-operative protocols. PMDA regulatory harmonization with ISO 13485 quality management standards constrains market access for uncertified manufacturers. The Kansai region around Osaka anchors polymer chemistry expertise for silicone-foam composite production.
United Kingdom
NHS procurement consolidation through group purchasing organizations standardizes tender specifications for pressure-redistribution devices. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific approval pathways. The Cambridge-Oxford-London golden triangle concentrates orthotic research partnerships between university hospitals and medical device developers.
Australia
TGA therapeutic goods registration requirements for medical devices align with ISO 10993 biocompatibility testing standards, favoring suppliers with established polymer chemistry capabilities. Aged care quality standards mandate pressure injury prevention protocols in residential facilities. The Melbourne biomedical precinct hosts clinical trials validating sensor-embedded suspension systems for tissue perfusion monitoring.
Heel and Elbow Suspension Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with dedicated wound care divisions, creating tiered competitive access where regulatory affairs capacity separates sustainable participants from contract manufacturers. Orthopedic ecosystem bundling and acute-care supply contract anchoring represent the dominant competitive moves, with silicone-foam composite differentiation commanding tender preference in premium procurement segments.
Among diversified medical technology conglomerates, Stryker Corporation and Smith & Nephew plc occupy positions where orthopedic device ecosystems enable bundled suspension product offerings. Medline Industries, Inc. exemplifies the supply contract anchoring archetype through North American hospital network relationships. Mölnlycke Health Care AB represents silicone-foam composite specialization within the premium technology tier.
| Leading Market Players |
|---|
| Span-America Medical Systems, Inc. |
| DeRoyal Industries, Inc. |
| Stryker Corporation |
| Invacare Corporation |
| Mölnlycke Health Care AB |
| Medline Industries, Inc. |
| EHOB, Inc. |
| Smith & Nephew plc |
| AliMed, Inc. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day polymer resin lead times in silicone-foam composite sourcing compress inventory buffers for suspension device manufacturers, concentrating pricing power among German and Japanese suppliers with captive polymer chemistry capabilities while forcing contract manufacturers toward cost-plus arrangements indexed to petrochemical feedstock indices.
Pricing Analysis
Cost-plus contracts with ethylene and silicone feedstock indexation dominate procurement agreements between suspension device OEMs and polymer suppliers. Three-tier pricing structure across premium ISO 13485-certified, standard FDA 510(k)-cleared, and economy non-certified levels separates reimbursement-eligible hospital tenders from budget-constrained long-term care purchases. Pricing pressure stems from group purchasing organization consolidation in United States health systems, which commoditizes mid-tier orthotic segments. Long-term care facilities exhibit highest price sensitivity due to out-of-pocket procurement constraints, while acute hospital networks prioritize clinical evidence over unit cost.
Supply Chain Analysis
Germany and Japan anchor silicone-foam composite production for premium suspension systems, while the United States concentrates injection-molded polymer component manufacturing. Supply chains draw from medical-grade silicone elastomers, viscoelastic polyurethane foams, and sensor-embedded smart polymers as critical inputs. Single-source vulnerability concentrates in specialized biocompatible adhesive suppliers certified to ISO 10993 standards. Distribution runs through group purchasing organization contracts in North American acute care networks, direct manufacturer relationships in German statutory health insurance procurement, and durable medical equipment retail channels for patient-direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in custom-fit digital fabrication, as 3D printing adoption among orthopedic clinics creates service-layer niches underserved by standardized prefabricated device incumbents.
For Market Incumbents: Secure ISO 13485 certification renewal cycles ahead of EU MDR enforcement to defend hospital tender eligibility against emerging contract manufacturers lacking dedicated quality infrastructure. Deepen backward integration into silicone-foam polymer chemistry to protect margin pools from petrochemical feedstock volatility and substitution threats from low-cost foam positioning alternatives. For New Entrants and Emerging Players: Sports medicine digital scanning services represent the most penetrable white-space target, as athletic trainers in contact sports seek prophylactic suspension protocols beyond traditional post-operative care reimbursement pathways. Target rehabilitation center direct relationships bypassing group purchasing organization consolidation, leveraging 3D printing workflow integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-anchored defensive play because aging population chronic wound prevention spending in Japan, Germany, and the United States sustains procurement volume regardless of macroeconomic cyclicality. Acquisition focus should center on mid-tier manufacturers with EU MDR transition readiness and established silicone-foam composite expertise. Signal to monitor: National Pressure Injury Advisory Panel guideline updates that would force device specification changes and first-mover certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market access for Class II suspension devices in United States acute care networks. |
| CE Marking Pathway under EU MDR | Extends clinical evidence requirements, compressing vendor base to firms with regulatory affairs capacity. |
| Hospital System Partnership | Secures group purchasing organization contract anchoring against commodity substitution pressure. |
| Software Companion Development | Enables sensor-embedded suspension systems for real-time tissue perfusion monitoring in post-operative protocols. |
| Reimbursement Strategy | Aligns device specifications with Medicare diagnosis-related group codes and statutory health insurance frameworks. |
Research Methodology
Initial hypotheses were tested against primary input from wound care clinicians, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers, and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR CE marking registries, hospital procurement contract archives, and CMS Medicare reimbursement code filings. Bottom-up demand modeling across acute care, rehabilitation, and sports medicine end-use segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Variance decomposition across product type, technology platform, end-user environment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume elasticities to reimbursement pathway expansion, aging demographic penetration curves, and digital fabrication adoption rates. Industry-specific forecast inputs incorporated silicone-foam composite material cost trajectories and notified body approval timeline constraints under EU MDR.
Forecasts assume regulatory continuity in FDA 510(k) Class II pathways and EU MDR CE marking frameworks; material policy shifts in biocompatibility testing standards or pressure injury prevention protocol mandates would require re-modeling. Specific risks include ISO 13485 certification cycle disruptions, group purchasing organization contract consolidation acceleration, and sensor-embedded device cybersecurity regulatory expansion. Recalibration cycles align with material shifts in National Pressure Injury Advisory Panel guideline updates and statutory health insurance reimbursement expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Deflectable Catheters Market
Medical Devices
North America Medical Devices Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Lactation Massager Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Surgical Incision Closure Devices Market