
 Batteries for Skin Patches Market | 2026-2036
Batteries for Skin Patches Market Size, Share, and Industry Trends Forecast 2026-2036
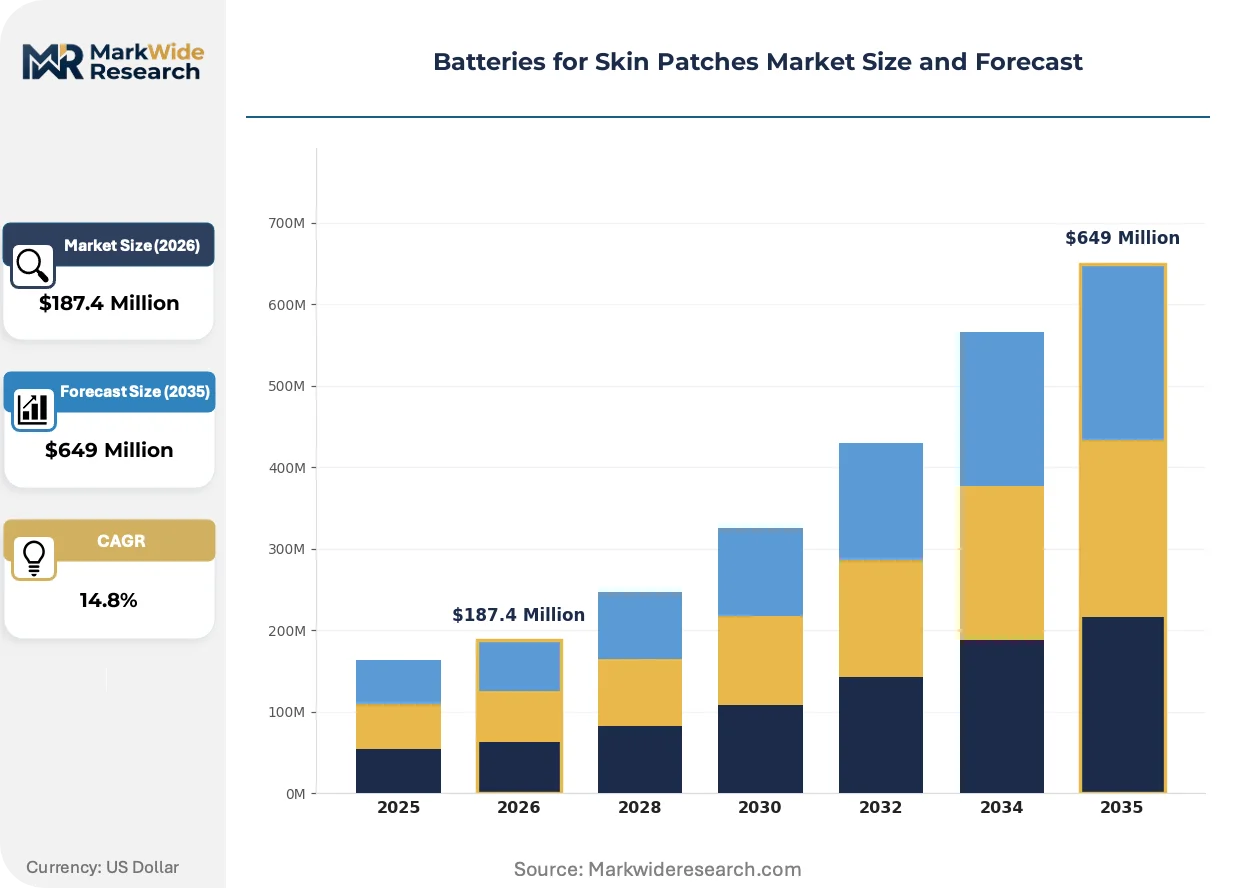
Batteries for Skin Patches Market Outlook
Medical-grade energy density is bifurcating the competitive landscape into performance-certified suppliers and commodity cell assemblers. Panasonic Corporation leverages its thin-film lithium expertise to sustain premium positioning in diagnostic patch applications. LG Energy Solution anchors volume supply through scalable roll-to-roll manufacturing for wearable device manufacturers. Blue Spark Technologies differentiates via proprietary printed battery architectures that occupy niche therapeutic delivery segments.
Batteries for skin patches are electrochemical power sources engineered below two millimeters thickness, typically employing zinc-air chemistry or solid-state lithium constructions to deliver stable voltage across flexing substrates for biosignal acquisition or controlled pharmaceutical release. Non-rechargeable zinc-air configurations lead unit economics in disposable monitoring applications where shelf-life stability governs procurement decisions, while rechargeable thin-film lithium ion systems capture margin pools in multi-day therapeutic patches requiring cyclability. Flexible form factors now outpace rigid micro-cells in new design-ins as dermatological conformity becomes a non-negotiable wearable device specification.
FDA 21 CFR Part 820 quality system regulations and IEC 60601-1 third-edition electrical safety standards govern electrochemical biocompatibility and isolation requirements for skin-contact power systems, compelling manufacturers to maintain dual jurisdiction compliance documentation. The EU Medical Device Regulation's classification escalation for active drug-delivery wearables is extending conformity assessment burdens to battery subsystem suppliers. Stakeholders must monitor whether emerging solid-state electrolyte formulations can satisfy both energy density targets and evolving thermal runaway test protocols without redesigning form factor roadmaps.
Market Dynamics
Continuous glucose monitor manufacturers are consolidating procurement around ultra-thin flexible zinc-air cells, compressing supplier margins while elevating electrochemical certification requirements for dermatological power systems.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system regulations for powered wearable medical devices are tightening electrochemical safety thresholds, forcing upgrade cycles in diagnostic patch battery specifications.
- Zinc-air chemistry:Disposable monitoring applications favor non-rechargeable configurations where shelf-life stability governs hospital procurement decisions and unit economics.
- German industrial clusters:Fraunhofer institutes in Stuttgart and Berlin drive prototype-to-production transitions for flexible cell manufacturing.
Market Restraints
- Lithium raw material volatility:Thin-film lithium ion systems face input cost pressure from cathode active material supply concentration in East Asian processing hubs.
- EU MDR classification escalation:Active drug-delivery wearables now trigger extended conformity assessment burdens that delay battery subsystem supplier qualification.
- Rigid micro-cell substitution:Legacy coin cell architectures retain cost advantage in price-sensitive wellness tracker segments.
Strategic Opportunities
- Solid-state electrolyte convergence:Emerging ceramic-polymer hybrid formulations promise simultaneous energy density gains and thermal runaway suppression.
- Multi-day therapeutic patches:Rechargeable thin-film lithium ion systems capture margin pools in cyclical pharmaceutical delivery applications.
- Roll-to-roll manufacturing scale:Korean and Japanese equipment vendors are enabling kilometer-length flexible cell production.
Industry Challenges
- IEC 60601-1 third-edition compliance:Electrical isolation documentation for skin-contact power systems requires dual jurisdiction testing protocols that extend development timelines.
- Biocompatibility certification backlog:ISO 10993 cytotoxicity and sensitization studies for novel electrolyte formulations face laboratory capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batteries for Skin Patches Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $649 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Rechargeable, Non-rechargeable, Lithium Ion, Zinc Air Form Factor: Flexible, Rigid, Ultra-thin, Micro End User: Healthcare Providers, Patients, Research Institutions, Wearable Device Manufacturers Application: Monitoring, Drug Delivery, Diagnostics, Therapeutic |
| Companies Covered | Maxell, Murata Manufacturing, Panasonic Corporation, LG Energy Solution, Blue Spark Technologies, Medtronic, Dexcom, Abbott, Nemaura Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batteries for Skin Patches Market Strategic Shifts
Flexible form factors are now non-negotiable in wearable device specifications, compressing design-in windows for rigid alternatives while elevating dermatological conformity as a procurement filter.
Solid-state lithium constructions are displacing conventional liquid electrolyte thin-film cells in premium diagnostic patch applications. Continuous glucose monitor manufacturers in North America and Western Europe are accelerating design qualification cycles for these architectures. The shift is compressing margin pools for commodity zinc-air assemblers while rewarding suppliers with in-house solid-state deposition capabilities.
EU MDR Article 10 technical documentation requirements are extending conformity assessment scope to battery subsystem suppliers for active implantable wearables. German notified bodies are interpreting electrochemical biocompatibility more stringently than pre-2021 medical device directives. This regulatory friction is diverting R&D expenditure toward ISO 13485-certified production lines in Ireland and Switzerland.
Hospital procurement departments are unbundling battery supply from finished patch device contracts, creating direct sourcing relationships with certified cell manufacturers. This channel disintermediation is visible in German and Dutch healthcare systems where group purchasing organizations negotiate cell specifications separately from device OEMs. Tier-1 suppliers respond by building dedicated medical sales functions with regulatory affairs support.
Batteries for Skin Patches Market Segmentation
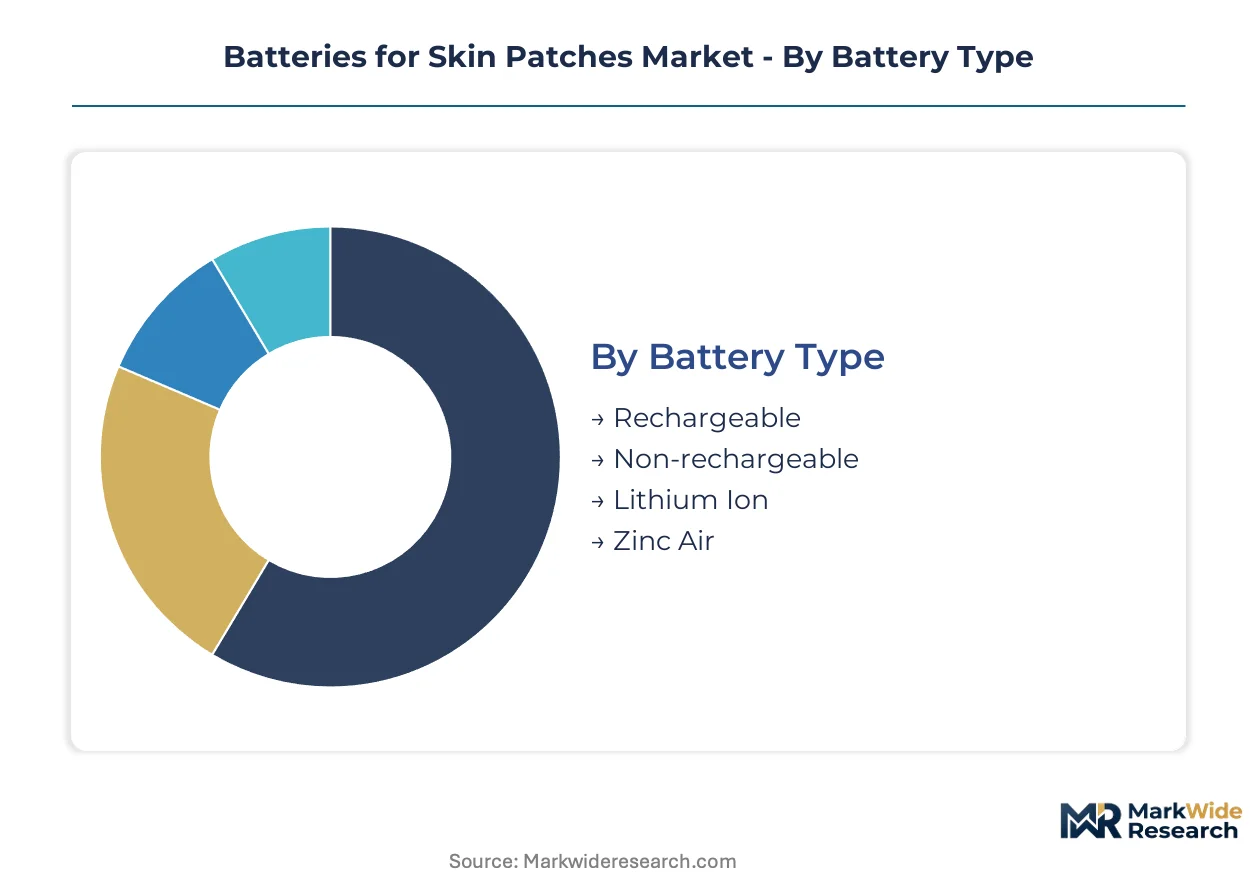
Electrochemical specifications for skin-contact power systems diverge sharply across use cases. Procurement patterns in this market track regulatory certification tiers rather than commodity pricing, making segment boundaries unusually rigid.
Battery Type:
Domestic production clusters in Germany and Japan anchor non-rechargeable supply, while Korean manufacturers dominate export flows of rechargeable thin-film architectures.
- Non-rechargeable:Zinc-air chemistry dominates disposable glucose monitoring patches where shelf-life stability exceeds fifteen years. Hospital procurement departments in Germany and the Netherlands consolidate volume tenders around certified zinc-air suppliers to simplify inventory management.
- Rechargeable:Thin-film lithium ion constructions enable multi-day therapeutic patches requiring fifty-plus charge cycles. Korean roll-to-roll manufacturing lines supply North American and Western European device OEMs with kilometer-length flexible cell reels.
- Lithium Ion:Solid-state electrolyte variants are displacing liquid electrolyte predecessors in premium diagnostic applications.
- Zinc Air:Printed architectures from Fraunhofer-licensed producers occupy niche pharmaceutical delivery segments.
Non-rechargeable configurations command the established base. The steepest expansion runs through rechargeable solid-state architectures.
Form Factor:
Cost tiers separate premium ultra-thin deposition capabilities from commodity rigid cell stamping operations concentrated in East Asian contract manufacturers.
- Ultra-thin:Sub-two-millimeter constructions employing ceramic-polymer hybrid electrolytes satisfy FDA electrochemical safety thresholds for continuous wear. German industrial clusters in Stuttgart prototype these architectures for export to North American glucose monitor manufacturers.
- Flexible:Roll-to-roll processed cells conform to skin topography without signal degradation during motion. Korean equipment vendors supply deposition lines enabling volume scale for wearable device manufacturers.
- Rigid:Legacy coin cell formats retain cost advantage in price-sensitive wellness tracker segments.
- Micro:Stamped metal enclosures dominate disposable diagnostic applications with sub-24-hour operational requirements.
Flexible form factors command the established base. Ultra-thin solid-state constructions are climbing the fastest.
End User:
Customer type determines certification burden intensity, with healthcare providers imposing ISO 13485 requirements that research institutions frequently bypass.
- Healthcare Providers:German and Dutch group purchasing organizations unbundle battery procurement from finished device contracts, negotiating cell specifications directly with certified manufacturers. FDA 21 CFR Part 820 quality system documentation is mandatory for hospital admission.
- Wearable Device Manufacturers:Continuous glucose monitor producers consolidate procurement around ultra-thin flexible cells, compressing supplier margins while elevating electrochemical certification requirements.
- Patients:Direct-to-consumer therapeutic patches drive demand for intuitive recharging interfaces and extended cycle life.
- Research Institutions:Prototype-to-production transitions at Fraunhofer institutes generate early demand for novel solid-state formulations before commercial scale-up.
Healthcare providers command the established base. Wearable device manufacturers are gaining share fastest.
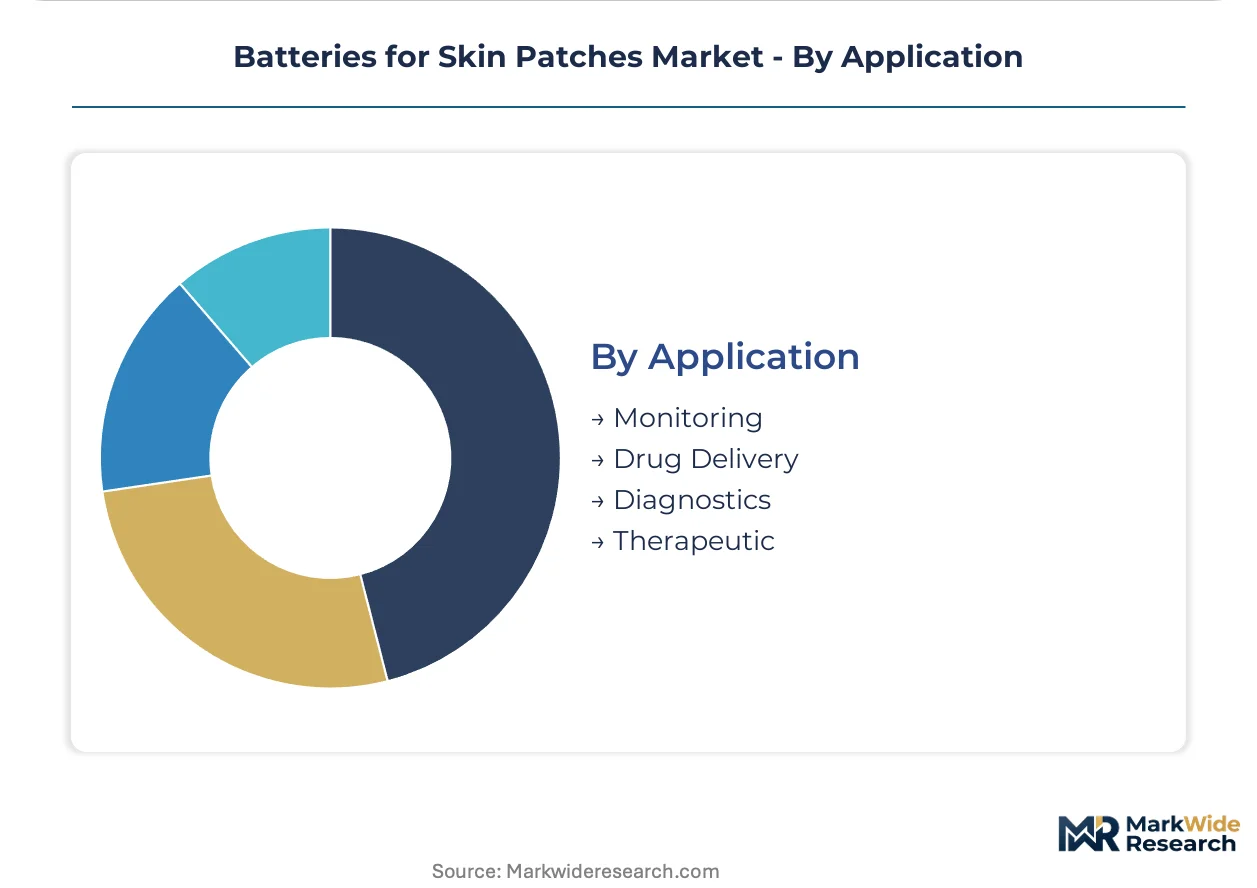
Application:
Maturity gradients separate decades-established monitoring applications from emerging therapeutic delivery formats requiring novel biocompatibility certification pathways.
- Monitoring:Continuous glucose tracking applications specify zinc-air cells with stable voltage output across temperature and humidity ranges. FDA guidance on powered wearable medical devices tightens electrochemical safety thresholds specifically for glucose monitor integrations.
- Drug Delivery:Active pharmaceutical release patches require precise current control for iontophoretic or electroosmotic mechanisms. EU MDR classification escalation extends conformity assessment burdens to battery subsystem suppliers in this category.
- Diagnostics:Single-use biosignal acquisition patches prioritize shelf-life stability over cycle durability.
- Therapeutic:Transcutaneous electrical nerve stimulation and similar modalities demand higher instantaneous current delivery than monitoring applications.
Monitoring applications command the established base. Drug delivery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement in the Netherlands shows the highest price elasticity, squeezing commodity zinc-air margins, while German hospital systems absorb premium solid-state premiums with minimal volume reduction.
United States
Continuous glucose monitor manufacturers consolidate procurement around ultra-thin flexible cells from Korean and Japanese suppliers. FDA 21 CFR Part 820 quality system regulations tighten electrochemical safety thresholds specifically for powered wearable medical devices. Greater Boston hosts Dexcom and Abbott R&D facilities driving solid-state qualification cycles.
Germany
Fraunhofer institutes in Stuttgart and Berlin generate early demand for novel solid-state formulations before commercial scale-up. EU MDR classification escalation for active drug-delivery wearables extends conformity assessment burdens to battery subsystem suppliers. Industrial clusters in Baden-Württemberg prototype ceramic-polymer hybrid electrolytes for export to North American device OEMs.
South Korea
Roll-to-roll manufacturing lines supply kilometer-length flexible cell reels to Western wearable device manufacturers. The national industrial policy under METI-equivalent frameworks prioritizes advanced battery export capacity. Seoul Capital Area equipment vendors enable volume scale for thin-film lithium ion deposition systems.
Japan
Thin-film lithium expertise sustains premium positioning in diagnostic patch applications through PMDA-certified production facilities. JIS standards for medical electrical equipment align with IEC 60601-1 third-edition electrical safety protocols. Kansai region manufacturers anchor non-rechargeable supply for disposable monitoring applications.
Switzerland
ISO 13485-certified production lines in Ireland and Switzerland capture R&D expenditure diverted from German regulatory friction. Swissmedic interprets electrochemical biocompatibility requirements for active implantable wearables. Zurich-area notified bodies specialize in battery subsystem technical documentation for EU MDR Article 10 compliance.
Batteries for Skin Patches Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Thin-film deposition specialists command premium positioning through solid-state electrolyte capabilities, while roll-to-roll manufacturers anchor volume economics. Three archetypes dominate: certified medical-grade suppliers, scalable flexible cell producers, and niche printed battery architects. Competitive moves concentrate on strategic partnerships for regulatory certification and capacity expansion for kilometer-length production lines.
Within the certified medical-grade tier, Panasonic Corporation and LG Energy Solution exemplify divergent scale-positioning strategies. Blue Spark Technologies occupies a position among niche printed battery specialists serving therapeutic delivery segments. Japanese and Korean entities anchor the technology-intensive vector, while Fraunhofer-licensed producers represent the European prototype-to-production transition archetype.
| Leading Market Players |
|---|
| Maxell |
| Murata Manufacturing |
| Panasonic Corporation |
| LG Energy Solution |
| Blue Spark Technologies |
| Medtronic |
| Dexcom |
| Abbott |
| Nemaura Medical |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Korean roll-to-roll manufacturers and North American glucose monitor OEMs lock in cathode active material supply access while freezing price visibility across multi-year procurement windows, insulating contract holders from lithium raw material volatility that spot-market buyers absorb immediately.
Pricing Analysis
FDA 21 CFR Part 820 dictates the pricing tier structure across the medical-grade battery segment. Three-tier pricing stratifies across ISO 13485-certified premium suppliers, standard-tier roll-to-roll manufacturers, and economy zinc-air assemblers. Price differentiation hinges on electrochemical certification grade and volume scale commitments from hospital group purchasing organizations. Cost compression in the commodity zinc-air tier is intensifying because Dutch and German procurement departments unbundle cell specifications from finished device contracts. Healthcare providers in the Netherlands exhibit the highest price sensitivity, while German hospital systems absorb solid-state premiums with minimal volume reduction.
Supply Chain Analysis
Port congestion on Busan-to-Los Angeles trade lanes elevates inbound logistics costs for Korean flexible cell exports destined for Dexcom and Abbott facilities in Greater Boston. Supply concentrates in South Korea, Japan, and Germany, with cathode active material processing anchored in East Asian hubs. The chain draws from lithium carbonate, ceramic-polymer electrolyte precursors, and thin-film deposition equipment. Single-source vulnerability in solid-state electrolyte precursor supply creates structural risk. Distribution runs through direct OEM relationships and hospital group purchasing organization channels, bypassing traditional device manufacturer intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte convergence represents a high-growth disruption, with ceramic-polymer hybrid formulations satisfying both FDA electrochemical safety thresholds and thermal runaway suppression requirements that liquid electrolyte predecessors cannot meet.
For Market Incumbents: Secure ISO 13485-certified production capacity in Switzerland and Ireland before EU MDR Article 10 technical documentation requirements harden battery subsystem supplier qualification timelines. Backward integration into cathode active material processing mitigates lithium raw material volatility that compresses margins on thin-film lithium ion contracts. Capacity reservation agreements with Korean equipment vendors lock in roll-to-roll deposition line access before order backlogs extend to thirty-six months. For New Entrants and Emerging Players: Lead with printed zinc-air architectures in pharmaceutical delivery segments where Fraunhofer licensing creates prototype-to-production pathways without competing against Panasonic's thin-film lithium expertise head-on. Target research institution procurement at Stuttgart and Berlin Fraunhofer institutes before commercial scale-up demands capital-intensive roll-to-roll infrastructure. Position through direct GPO relationships in Dutch healthcare systems that unbundle battery procurement from device OEM contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among solid-state electrolyte specialists serving multi-day therapeutic patch applications requiring fifty-plus charge cycles. Long-term viability over the five-to-ten year window favors suppliers with in-house deposition capabilities rather than contract assemblers exposed to zinc-air commodity margin erosion. Acquisition targets should demonstrate PMDA or FDA quality system certification. The signal to watch is EU MDR notified body capacity constraints extending battery subsystem qualification timelines beyond eighteen months.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Swissmedic and German notified body alignment accelerates EU MDR Article 10 compliance for active implantable wearables. |
| Roll-to-Roll Capacity Expansion | Seoul Capital Area equipment vendors enable kilometer-length flexible cell production for Western glucose monitor OEMs. |
| Solid-State Electrolyte R&D Partnership | Fraunhofer institute licensing bridges ceramic-polymer hybrid formulations from prototype to commercial deposition. |
| Direct GPO Channel Development | Dutch and German hospital purchasing organizations now negotiate cell specifications separately from device contracts. |
| Backward Integration into Cathode Materials | Captive supply of lithium carbonate reduces exposure to East Asian processing hub concentration. |
Study Parameters
Cross-validation between primary interviews with wearable device procurement directors, biomedical engineers at continuous glucose monitor manufacturers, and hospital GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and Fraunhofer institute patent disclosures. Bottom-up demand modeling triangulates against top-down electrolyte chemistry production capacity estimates.
Sensitivity analysis across zinc-air shelf-life stability assumptions and solid-state electrolyte yield rates frames the forecast envelope. Segmentation dimensions include battery type, form factor, end user archetype, and application category, with cyclability requirements and dermatological conformity specifications as cross-cutting variables. CAGRs derive from installed base expansion in continuous glucose monitoring and therapeutic patch adoption curves, with Korean and Japanese export flow data informing regional supply-side constraints.
Underlying assumptions cover FDA guidance stability on powered wearable medical devices and EU MDR notified body capacity availability, with deviation risk concentrated in lithium raw material supply disruptions and solid-state electrolyte thermal runaway test protocol revisions. Practitioners should keep alternative scenarios live as EU MDR classification interpretations for active drug-delivery wearables evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Pelvic Electro-Stimulators Market