
 Bone Conduction Hearing Devices Market | 2026-2036
Bone Conduction Hearing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Conduction Hearing Devices Market Intelligence
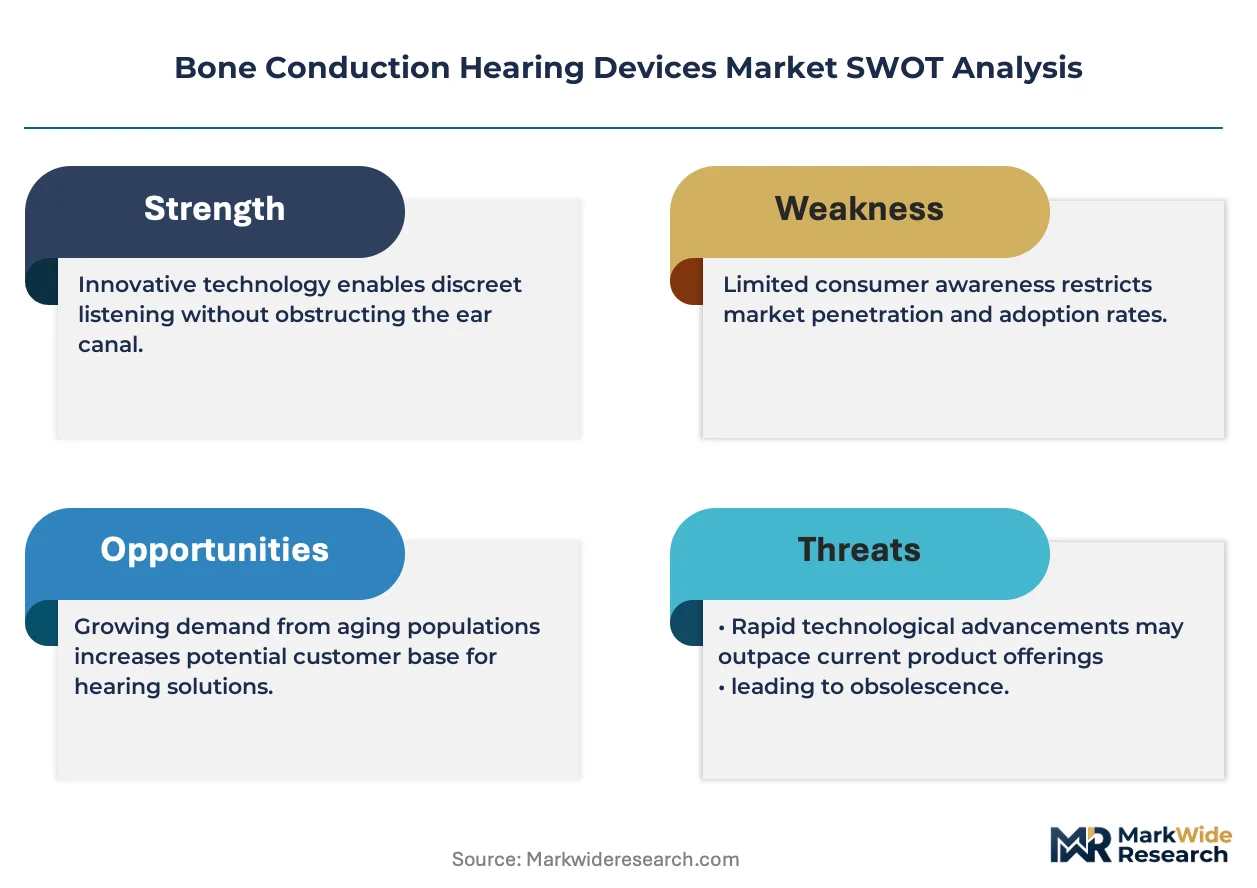
MEMS miniaturization is rewriting how bone conduction transducers integrate into wearable form factors, shrinking driver size while preserving mechanical efficiency across the 250-4000 Hz speech band. Sonova leverages its audiology clinic network to sustain premium positioning in behind-the-ear configurations. Cochlear Limited anchors the implantable segment through deep expertise in osseointegrated fixture design. Demant competes across multiple technology tiers, from piezoelectric headbands to capacitive communication aids.
Bone conduction hearing devices transmit acoustic signals directly to the cochlea via mechanical vibration of the temporal bone, bypassing compromised middle-ear structures that obstruct air-conduction pathways. Titanium abutment fixtures and percutaneous screws typically achieve 45-55 dB functional gain in mixed hearing loss cases, with implantable systems requiring 3-6 months osseointegration before activation. The implantable product category commands the deepest margin pools given surgical workflow complexity and long-term service revenue. Piezoelectric technology leads unit economics in sports and recreation applications where waterproofing and shock resistance outweigh audiometric fidelity requirements. Military field demand gravitates toward electromagnetic architectures that resist electromagnetic interference in combat communication networks.
FDA 510(k) clearance pathways govern US market entry for non-implantable bone conduction systems, while EU MDR Class IIa certification now demands expanded clinical evidence for implantable devices sold in Germany, France, and Italy. Japan's PMDA maintains distinct technical standards for bone-anchored hearing aids that delay multinational product harmonization by 12-18 months relative to Western timelines. Stakeholders must monitor how WHO hearing care integration targets reshape national reimbursement catalogs and whether China's NMPA accelerates local manufacturing approvals for domestic piezoelectric suppliers.
Market Dynamics
MEMS miniaturization is compressing transducer dimensions while preserving mechanical efficiency across the speech band, forcing incumbents to redesign fixture architectures and abandon legacy electromagnetic assemblies that dominated the prior decade.
Growth Catalysts
- EU MDR Class IIa pathway:Expanded clinical evidence requirements for implantable devices in Germany, France, and Italy have paradoxically strengthened reimbursement credibility, accelerating clinic adoption.
- Piezoelectric waterproofing:Sports and recreation end-uses now specify piezoelectric transducers for shock resistance and submersion tolerance, opening volume channels beyond medical audiology.
- Japan METI clusters:Metropolitan hearing aid centers in Tokyo and Osaka leverage government-supported innovation infrastructure to compress product validation timelines.
Market Restraints
- Titanium input volatility:Percutaneous abutment fixtures rely on surgical-grade titanium supply concentrated in a limited supplier base, exposing margin structures to raw material price swings.
- PMDA harmonization lag:Japan's distinct technical standards for bone-anchored systems create 12-18 month delays versus Western clearance timelines, fragmenting multinational product roadmaps.
- Air-conduction substitution:Advances in open-ear acoustic designs threaten non-implantable bone conduction positioning in mild-to-moderate hearing loss segments.
Strategic Opportunities
- Pediatric audiology expansion:German reimbursement solidification under EU MDR creates template pathways for pediatric clinic networks in France and Italy.
- Military electromagnetic demand:Combat communication networks specify interference-resistant architectures, opening specialized procurement channels with distinct performance specifications.
- Osseointegration service revenue:Three-to-six month activation protocols for implantable systems create recurring calibration and maintenance revenue streams.
Industry Challenges
- Audiological fitting specialization:Bone conduction device programming requires distinct competencies from conventional air-conduction fitting, constraining clinic capacity expansion.
- EU MDR technical documentation:Implantable device manufacturers face expanded clinical evidence compilation timelines that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Conduction Hearing Devices Market |
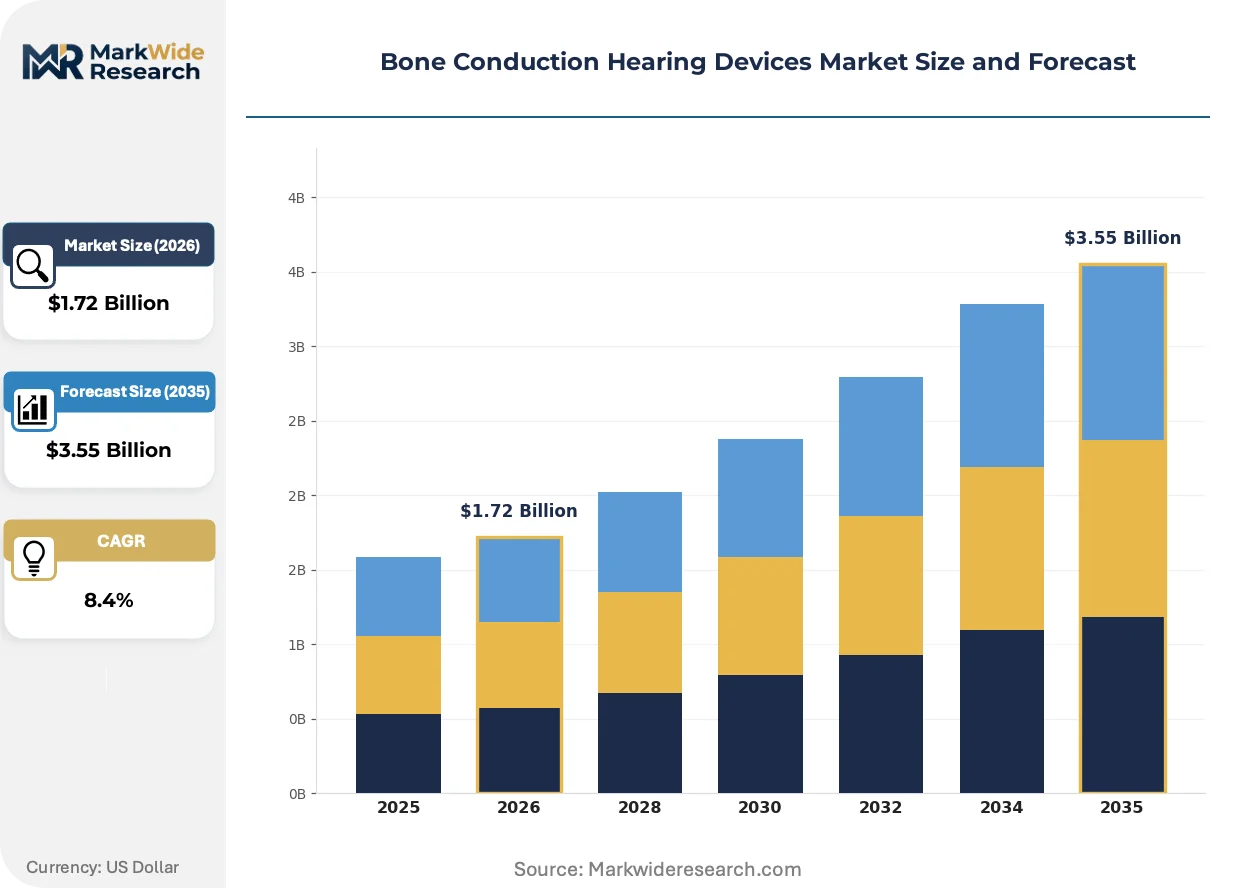
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.55 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headband, Implantable, Eyeglasses, Behind-the-Ear Technology: Piezoelectric, Electromagnetic, Microelectromechanical Systems, Capacitive Application: Hearing Loss Compensation, Communication Aid, Military Field, Sports & Recreation End User: Audiology Clinics, Hearing Aid Centers, Sports Professionals, Military Personnel |
| Companies Covered | Sonova, Demant, Cochlear Limited, Natus Medical, Medtronic, Oticon Medical, Starkey, Best Hearing Solutions, MED-EL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Conduction Hearing Devices Market Strategic Shifts & Innovations
Digital signal processing architectures are displacing analog amplification chains across both implantable and wearable bone conduction systems, compressing device footprints while enabling adaptive frequency response tuning.
Capacitive transducer arrays are digitizing how acoustic energy couples to the temporal bone, replacing electromagnetic voice-coil assemblies with solid-state vibration engines. Behind-the-ear configuration manufacturers in Germany and Japan are adopting these arrays fastest, with pediatric clinics specifying the technology for reduced feedback artifacts. The shift is digitizing supply chain priorities toward semiconductor fabrication partnerships and away from precision mechanical machining.
EU MDR Class IIa certification now demands expanded clinical evidence for implantable devices, elevating documentation burdens for osseointegrated fixture manufacturers. Surgical workflow complexity has deepened as notified bodies require longitudinal outcome data before market authorization. Implantable product categories face the steepest compliance cost inflation, with German and Italian manufacturers absorbing the largest regulatory overhead.
Hospital purchasing consortia in Japan are consolidating procurement authority for bone-anchored systems, displacing individual clinic autonomy with centralized tender processes. Metropolitan hearing aid centers in Tokyo and Osaka now negotiate volume contracts through regional health authority frameworks. This concentration is most visible in Japan's Kanto and Kansai regions, where aging demographics amplify purchasing leverage.
Bone Conduction Hearing Devices Market Segmentation
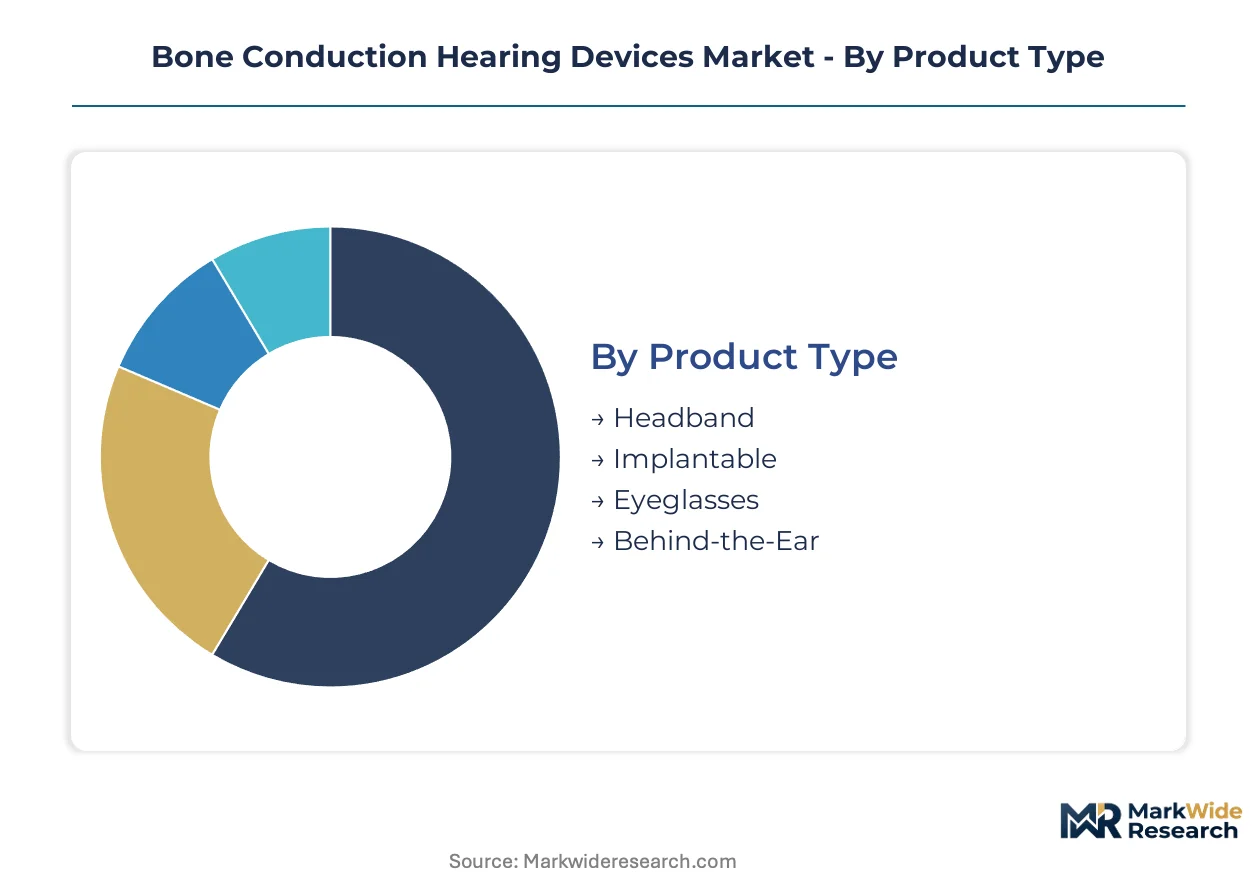
Segmentation in bone conduction hearing devices reveals how technical architecture, user environment, and clinical workflow shape procurement decisions. Manufacturers must align transducer physics with specific anatomical constraints and use-case durability requirements.
Product Type:
The use-case spectrum spans from non-invasive wearable formats to surgically integrated systems, each demanding distinct fixture engineering and activation protocols.
- Headband:External compression frames position transducers against the temporal bone through adjustable spring tension. Demand concentrates in sports retail channels across Germany and Japan where waterproof piezoelectric variants serve cyclists and swimmers who require situational awareness.
- Implantable:Titanium abutment fixtures achieve osseointegration with the skull over three-to-six months, delivering 45-55 dB functional gain for mixed hearing loss. German pediatric audiology clinics now drive adoption as EU MDR reimbursement pathways solidify, though surgical workflow complexity elevates service revenue dependency.
- Eyeglasses:Temple-integrated transducers merge vision correction with hearing assistance through bone conduction coupling. Japanese optical retail chains in Tokyo and Osaka specify these for aging consumers seeking discreet dual-function devices.
- Behind-the-Ear:Miniaturized transducer housings clip posterior to the pinna, preserving open-ear acoustic awareness. Sonova's audiology clinic network sustains premium positioning in this configuration across European metropolitan markets.
The dominant share belongs to Implantable systems, while Headband formats are closing the gap fastest through sports and recreation channels.
Technology:
Cost tiers separate legacy electromagnetic assemblies from solid-state architectures that command semiconductor fabrication partnerships.
- Piezoelectric:Ceramic transducers convert electrical signals to mechanical vibration through crystalline deformation, achieving IP68 waterproofing and shock resistance. Sports and recreation end-uses in Japan and Germany now specify this technology exclusively for submersion tolerance.
- Electromagnetic:Voice-coil assemblies drive magnetic armatures against the temporal bone, historically dominating medical audiology for linear frequency response. Military procurement in combat communication networks retains this architecture for electromagnetic interference resilience.
- Microelectromechanical Systems:MEMS miniaturization compresses transducer dimensions while preserving mechanical efficiency across the 250-4000 Hz speech band. Japanese METI-supported innovation clusters in Tokyo accelerate validation timelines for these solid-state engines.
- Capacitive:Electrostatic transducer arrays digitize acoustic coupling through variable capacitance plates, eliminating moving parts. Pediatric clinics in Germany specify this technology for reduced feedback artifacts in behind-the-ear configurations.
Piezoelectric technology commands the volume leadership position, though MEMS architectures are climbing the fastest as fixture redesigns abandon legacy electromagnetic assemblies.
Application:
Customer type determines performance thresholds, with medical audiology demanding audiometric fidelity and tactical users prioritizing environmental resilience.
- Hearing Loss Compensation:Clinical applications target conductive and mixed hearing loss through calibrated vibration delivery. German audiology clinics under EU MDR frameworks now anchor demand for implantable systems with longitudinal outcome documentation.
- Communication Aid:Occupational voice transmission for logistics and manufacturing workers leverages bone conduction to preserve ambient awareness. Japanese hearing aid centers in Osaka specify these for warehouse and construction environments.
- Military Field:Combat communication networks demand interference-resistant architectures that function through helmet integration. Electromagnetic transducer specifications dominate this procurement channel for electromagnetic pulse resilience.
- Sports & Recreation:Waterproof and shock-resistant configurations serve cyclists, swimmers, and runners requiring open-ear situational awareness. German sports retail channels and Japanese metropolitan fitness centers drive volume for piezoelectric headband formats.
Hearing Loss Compensation retains the deepest margin pools, while Sports & Recreation is gaining share fastest through waterproofing specifications that bypass clinical distribution constraints.
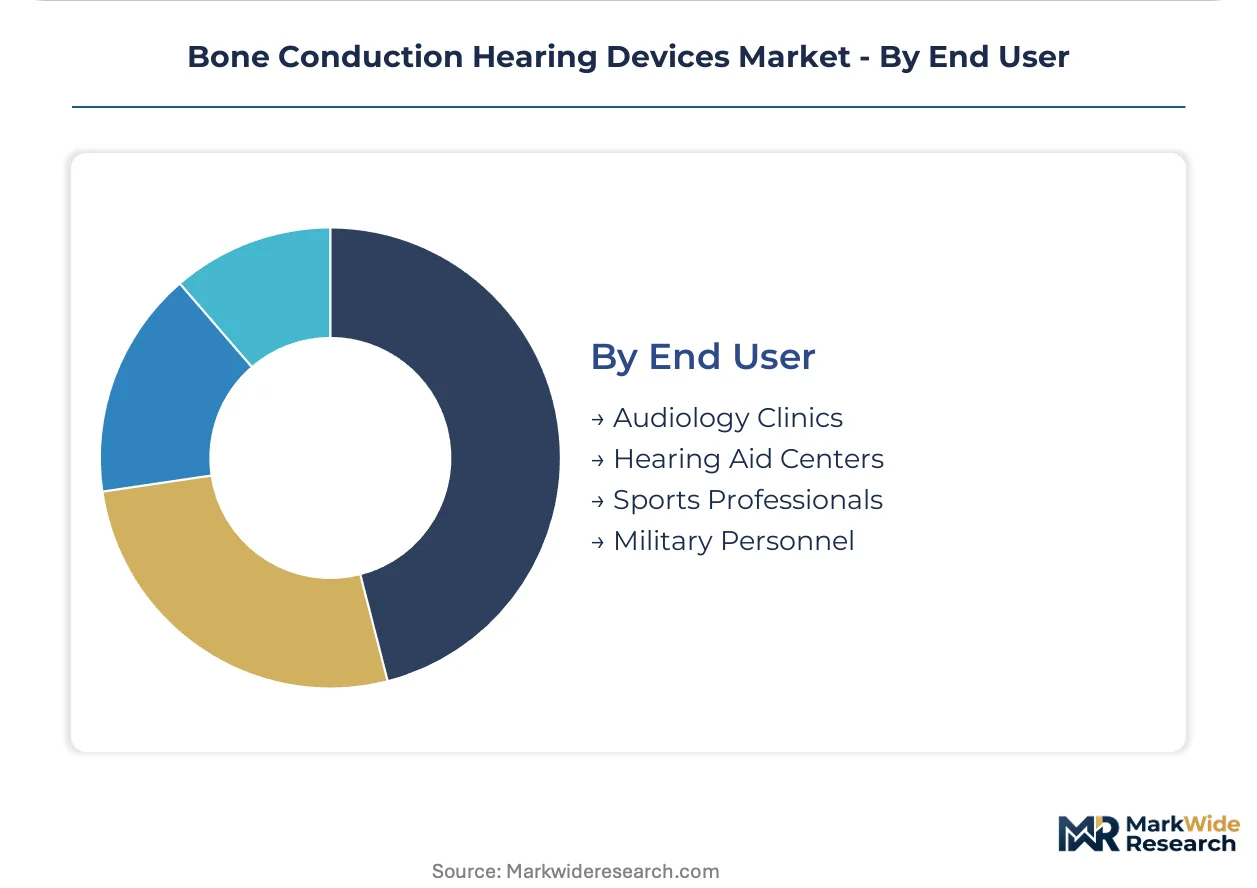
End User:
Procurement authority concentrates differently across clinical, retail, and institutional channels, shaping pricing negotiation dynamics.
- Audiology Clinics:German pediatric networks now drive implantable system adoption as EU MDR reimbursement solidifies, requiring specialized fitting competencies distinct from air-conduction protocols.
- Hearing Aid Centers:Metropolitan retail chains in Tokyo and Osaka leverage METI-supported infrastructure to compress product validation timelines for capacitive and MEMS architectures.
- Sports Professionals:Endurance athletes and aquatic competitors in Japan and Germany specify piezoelectric waterproof formats through direct retail and specialty cycling channels.
- Military Personnel:Defense procurement authorities in combat communication networks specify electromagnetic architectures with distinct electromagnetic interference performance envelopes.
Audiology Clinics control the premium tier, while Hearing Aid Centers are expanding most quickly through retail consolidation in Japanese metropolitan regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export implantable bone conduction systems to Japanese audiology networks, while Swiss component suppliers feed assembly operations across the EU and Asia-Pacific.
United States
Pediatric audiology networks and veterans' health facilities drive implantable system procurement. FDA 510(k) clearance pathways govern market entry for non-implantable configurations, with recent guidance emphasizing biocompatibility documentation for titanium abutment fixtures. Minneapolis and Boston medical device clusters concentrate surgical training programs for osseointegrated fixture placement.
Germany
Pediatric audiology clinics now anchor European demand as EU MDR Class IIa reimbursement pathways solidify. BfArM and notified body oversight demands expanded clinical evidence for implantable devices, compressing product launch timelines for manufacturers. Berlin and Munich metropolitan regions concentrate audiology clinic networks that validate MEMS miniaturization prototypes.
Japan
Metropolitan hearing aid centers in Tokyo and Osaka leverage METI-supported innovation infrastructure to compress validation timelines for solid-state transducer architectures. PMDA maintains distinct technical standards for bone-anchored systems that delay multinational product harmonization. Kanto and Kansai regions concentrate procurement authority through hospital purchasing consortia.
China
Domestic piezoelectric component suppliers expand manufacturing capacity for sports and recreation headband formats. NMPA regulatory pathways for bone conduction hearing aids remain under development, with local standards diverging from ISO benchmarks. Shenzhen and Dongguan electronics clusters drive cost compression in ceramic transducer fabrication.
Switzerland
Precision machining suppliers concentrate surgical-grade titanium fixture production for implantable system manufacturers. Swissmedic oversight aligns with EU MDR requirements, streamlining parallel market authorization across German and Italian entry points. Basel and Zurich medtech corridors anchor component supply relationships with German audiology device assemblers.
Bone Conduction Hearing Devices Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct technology tiers. The vendor base stratifies between audiology clinic network owners, implantable surgical system specialists, and sports-format component suppliers. Three archetypes dominate: integrated hearing healthcare conglomerates with clinic ownership, pure-play implantable fixture designers, and piezoelectric transducer component specialists. Competitive moves concentrate on MEMS fabrication partnerships and EU MDR clinical evidence compilation.
Within the integrated healthcare tier, Sonova and Demant occupy positions spanning clinic network control through multi-technology product portfolios. Cochlear Limited exemplifies the implantable-specialist archetype with concentrated expertise in osseointegrated fixture engineering. These three entities represent distinct strategic postures: clinic-channel leverage, surgical workflow integration, and transducer physics specialization respectively.
| Leading Market Players |
|---|
| Sonova |
| Demant |
| Cochlear Limited |
| Natus Medical |
| Medtronic |
| Oticon Medical |
| Starkey |
| Best Hearing Solutions |
| MED-EL |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese ceramic transducer fabrication is compressing component costs while elevating pricing power for German and Swiss fixture integrators who control EU MDR-certified surgical workflows. This utilization asymmetry rewards backward integration into titanium abutment machining and semiconductor MEMS partnerships.
Pricing Analysis
Prior-generation electromagnetic voice-coil assemblies now trade at steep discounts to MEMS-based and capacitive transducer arrays, while next-generation solid-state architectures command premium positioning through reduced feedback artifacts. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in piezoelectric headband formats is intensifying because Chinese suppliers are expanding ceramic fabrication capacity. Sports and recreation end-users exhibit highest price sensitivity, while German pediatric audiology clinics show lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Contract manufacturing capacity for MEMS die fabrication concentrates with Taiwanese foundries and select Japanese METI-supported clusters, while Swiss precision machinists retain surgical-grade titanium fixture production. Raw material dependencies center on surgical-grade titanium from Swiss and German suppliers, piezoelectric ceramics from Chinese and Japanese sources, and semiconductor wafers from South Korean and Taiwanese fabrication networks. Single-source vulnerability in titanium abutment supply exposes margin structures to raw material price volatility. Distribution runs through audiology clinic networks in Germany, hospital purchasing consortia in Japan, and sports retail channels across both markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bone conduction hearing devices are approaching a platform-economics inflection where MEMS transducer standardization enables interoperable fixture architectures across manufacturer ecosystems.
For Market Incumbents: Pre-empt air-conduction substitution threats by accelerating MEMS fabrication partnerships and securing exclusive clinic network contracts in German pediatric audiology. Backward integration into titanium abutment machining defends margin pools against raw material volatility. EU MDR clinical evidence compilation timelines compress product launch windows and favor incumbents with established notified body relationships. For New Entrants and Emerging Players: Pursue white-space opportunities in Japanese metropolitan hearing aid centers where METI-supported infrastructure compresses validation timelines for capacitive and MEMS architectures. Sports and recreation piezoelectric headband formats offer the most penetrable entry point due to lower regulatory barriers and direct retail distribution. Go-to-market positioning should emphasize IP68 waterproofing specifications for aquatic and cycling applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among implantable system manufacturers with three-to-six month osseointegration service protocols. Long-term viability over the next decade hinges on regulatory navigation capabilities and semiconductor fabrication partnerships. Acquisition targets should display EU MDR certification progress and established German clinic network relationships. The signal to monitor is PMDA harmonization progress, as accelerated alignment with Western standards would unlock Japanese market expansion for multinational players.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Partnership | Taiwanese foundry alliances compress transducer dimensions while preserving speech-band efficiency for wearable formats. |
| EU MDR Clinical Evidence Compilation | German notified body relationships accelerate implantable device authorization timelines under expanded Class IIa requirements. |
| Pediatric Audiology Network Expansion | Clinic ownership in Berlin and Munich metropolitan regions secures premium positioning for behind-the-ear configurations. |
| Piezoelectric Waterproofing Certification | IP68-rated headband formats unlock sports retail channels in Japanese metropolitan fitness centers and German cycling markets. |
| Titanium Abutment Backward Integration | Swiss precision machining partnerships reduce exposure to surgical-grade titanium supply concentration and price volatility. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with audiology clinic directors, biomedical engineers, hospital purchasing committee members, and MEMS fabrication specialists; and secondary validation through FDA 510(k) filings, EU MDR notified body documentation, PMDA technical standards, hospital procurement databases, and GPO contract records. Bottom-up unit shipment estimates across product type, technology, and application segments were triangulated against top-down market sizing derived from reimbursement pathway analysis and audiology clinic network expansion data.
Forecast inputs considered MEMS miniaturization adoption curves, EU MDR implementation timelines, PMDA harmonization progress, and titanium supply dynamics across the analysis window. Segmentation dimensions modeled include product type, transducer technology, clinical versus non-clinical application, and procurement channel authority. CAGRs were derived from regression analysis of historical adoption patterns and forward projection of reimbursement expansion scenarios. Industry-specific forecast inputs incorporated osseointegration service revenue attachment rates and METI cluster validation acceleration effects.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement budgets, titanium commodity pricing, or semiconductor fabrication capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and clinic network expansion rates. Quarterly review of EU MDR notified body clearance volumes, PMDA submission queues, and MEMS foundry capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market