
 New Born Eye Imaging Systems Market | 2026-2036
New Born Eye Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
New Born Eye Imaging Systems Market Foresight
The gap between premium and commodity tiers is expanding in concrete terms. Carl Zeiss Meditec AG leverages its optical heritage to dominate high-resolution fundus camera segments. Natus Medical anchors its position through dedicated neonatal care distribution channels. Remidio Innovative Solutions differentiates via portable, smartphone-connected screening devices aimed at cost-sensitive clinics.
New born eye imaging systems comprise specialized ophthalmic diagnostic equipment engineered for non-invasive visualization of infant retinal structures, typically operating at wavelengths between 400-1000 nanometers with fixation-free capture protocols designed for uncooperative pediatric subjects. These systems serve the primary commercial purpose of enabling early detection of retinopathy of prematurity, congenital cataracts, and optic nerve anomalies before irreversible vision loss occurs. Fundus cameras and optical coherence tomography devices currently command the deepest margin pools, while automated screening technology represents the fastest-expanding segment as hospitals seek to reduce specialist-dependent workflow bottlenecks. Digital imaging platforms sustain broader installed bases, though infrared imaging is gaining traction for through-media visualization in dense vitreous hemorrhage cases.
FDA premarket notification requirements and the EU Medical Device Regulation shape demand by mandating pediatric-specific safety and efficacy validation, which elevates barriers for new entrants while reinforcing incumbents with established clinical data packages. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety frameworks further constrain product design choices, particularly for devices contacting periocular infant skin. Stakeholders must monitor how reimbursement policy evolution for remote screening services reshapes capital equipment purchasing cycles versus disposable-per-test models.
Market Dynamics
Automated screening platforms are compressing specialist-dependent workflows in neonatal ophthalmology, forcing equipment vendors to reconfigure hardware-software bundles around nurse-operable protocols rather than physician-directed capture.
Growth Catalysts
- EU MDR pediatric validation mandates:Stricter premarket clinical requirements for infant-contact devices are filtering out marginal competitors and concentrating procurement among established suppliers with ISO 10993 biocompatibility documentation.
- Telemedicine reimbursement expansion:Remote diagnostic coding recognition in US Medicaid programs is accelerating capital deployment toward connected imaging platforms in rural birthing centers.
- Retinopathy of prematurity screening protocols:German university hospitals are embedding fundus photography into standard neonatal intensive care discharge checklists, creating institutional demand pull.
Market Restraints
- Specialized optical component supply:German and Japanese precision lens manufacturers control upstream sourcing for high-resolution objectives, exposing assemblers to single-source fragility.
- FDA 510(k) pediatric device pathway:Expanded clinical evidence requirements for devices contacting periocular infant tissue are extending time-to-market by 18-24 months for novel form factors.
- Disposable-per-test economic models:Capital-constrained clinics in lower-tier markets face pressure from single-use camera sheath and disinfectant cartridge recurring costs.
Strategic Opportunities
- Smartphone-connected portable platforms:Cost-sensitive outpatient clinics in India and Southeast Asia represent underpenetrated demand for handheld devices bypassing traditional fundus camera infrastructure.
- Infrared through-media imaging:Dense vitreous hemorrhage visualization capabilities are opening pediatric trauma and abusive head injury assessment applications beyond standard neonatal screening.
- US IRA preventive care incentives:Pediatric vision screening quality metrics tied to hospital reimbursement are creating procurement preference for automated, audit-trail-compliant systems.
Industry Challenges
- Pediatric ophthalmology technician training:Nurse-operable device interfaces require competency programs that most neonatal intensive care units lack internal capacity to deliver.
- Legacy PACS integration:Newborn-specific image formats and metadata standards clash with hospital-wide radiology archive protocols, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Born Eye Imaging Systems Market |
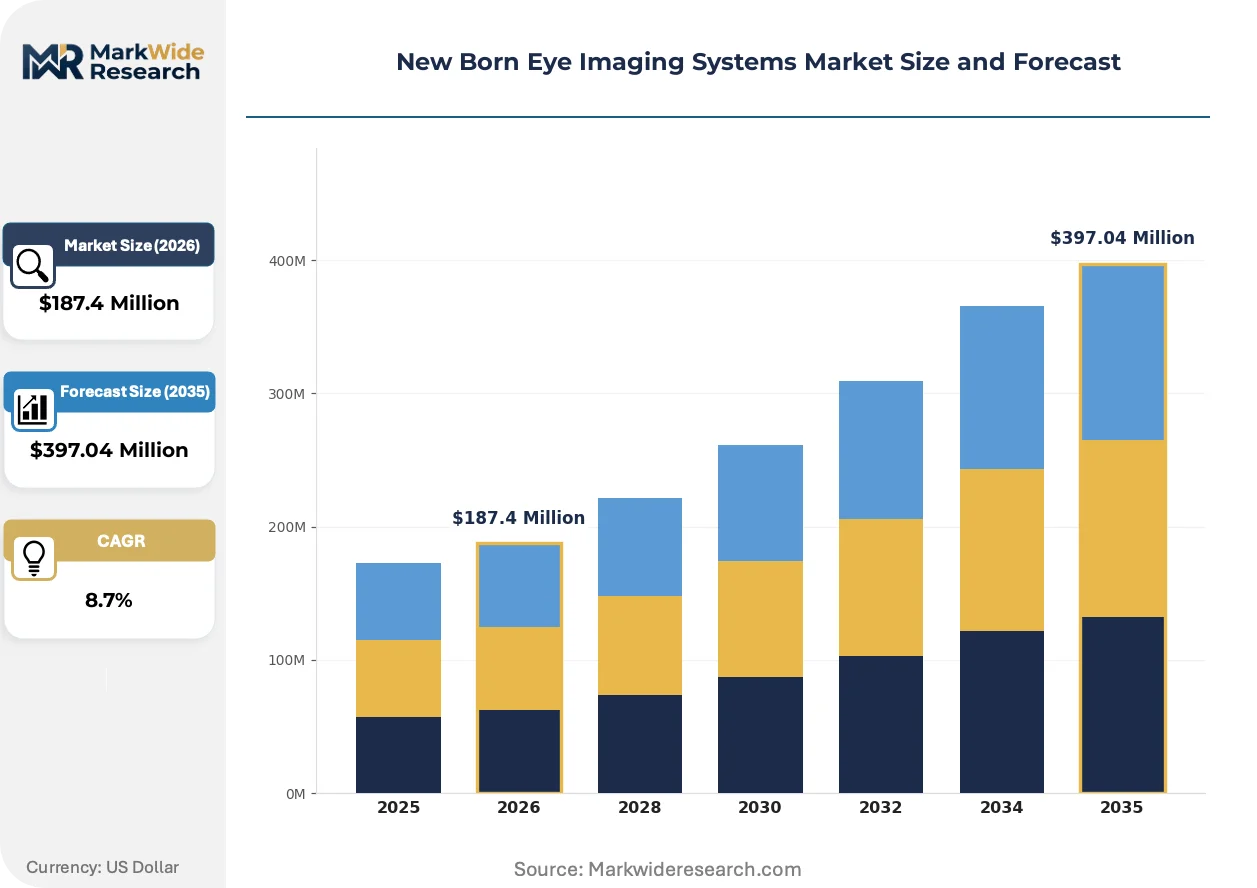
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fundus Cameras, Optical Coherence Tomography, Visual Field Analyzers, Retinal Imaging Systems End User: Pediatric Hospitals, Neonatal Clinics, Research Institutions, Ophthalmology Practices Technology: Digital Imaging, Infrared Imaging, Automated Screening, Fluorescence Imaging Application: Vision Screening, Disease Diagnosis, Research Studies, Follow-Up Care |
| Companies Covered | Visunex Medical Systems, D-EYE, Natus Medical, Carl Zeiss Meditec AG, Imagine Eyes, Remidio Innovative Solutions, Canon Medical Systems, Topcon Europe Medical, Allied Vision Technologies GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Born Eye Imaging Systems Market Shifts & Advancements
Workflow automation and point-of-care miniaturization are redrawing competitive boundaries between capital-intensive hospital systems and distributed screening networks.
Optical coherence tomography for infant retinal imaging is consolidating previously separate diagnostic steps into single-capture protocols. Level III neonatal intensive care units in the United States are replacing sequential fundus photography and specialist interpretation with nurse-operable OCT systems that generate structural measurements automatically. This compression is collapsing the traditional referral pipeline between community hospitals and academic medical centers.
The EU Medical Device Regulation's pediatric-specific post-market surveillance requirements are forcing manufacturers to maintain active implant registries for devices with extended infant contact. Companies must now fund multi-year follow-up studies as a condition of CE marking renewal. High-resolution fundus camera segments face the steepest compliance cost escalation due to their broader installed base and longer service lifecycles.
Hospital purchasing committees are unbundling after-sales service contracts from equipment leases and negotiating direct third-party maintenance agreements. This disintermediation is most visible in German university hospital networks, where centralized biomedical engineering departments now handle calibration and preventive maintenance internally. Vendors are responding with modular hardware designs that reduce proprietary technician dependency.
New Born Eye Imaging Systems Market Segmentation
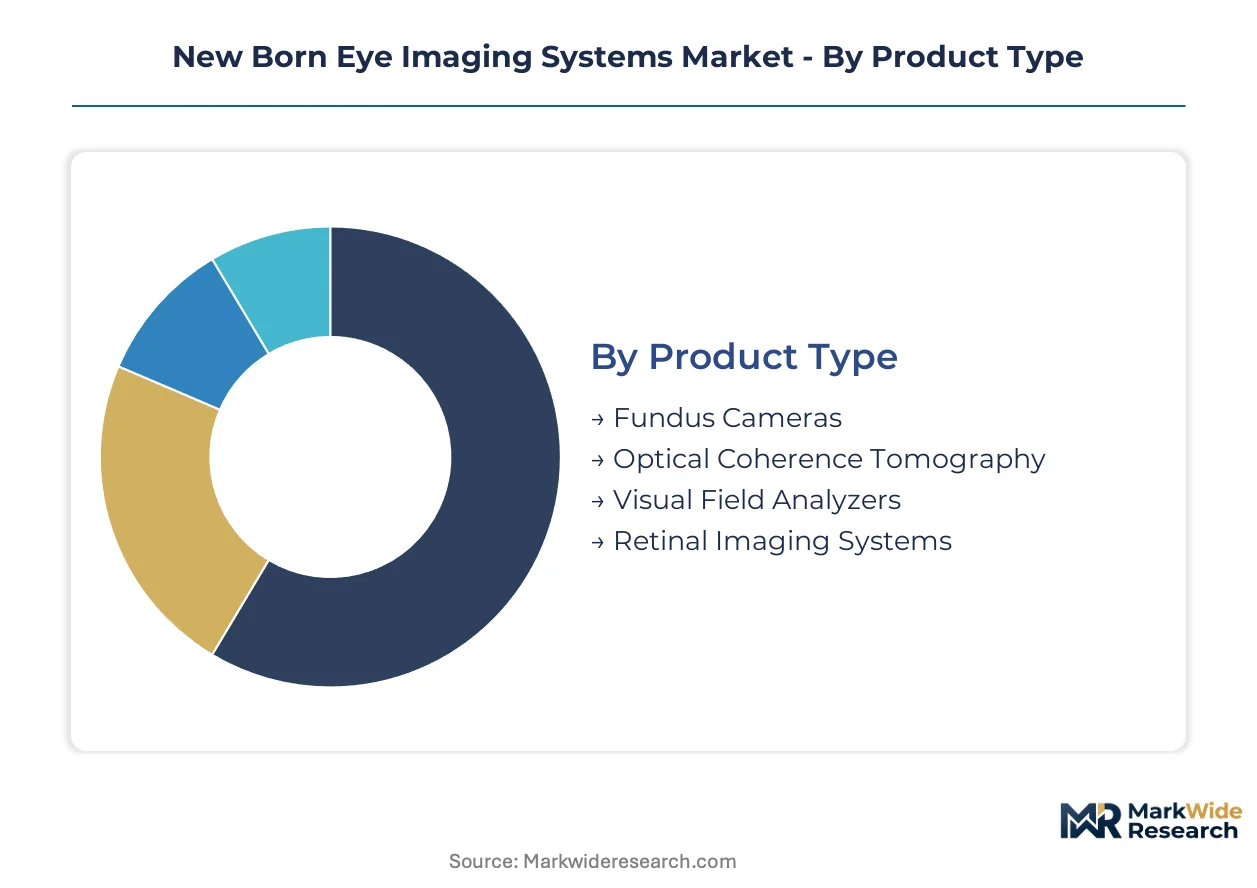
Segmentation in newborn eye imaging reveals how procurement priorities diverge between capital-intensive academic centers and distributed screening networks. Equipment vendors must align product configurations with distinct workflow constraints across NICU, outpatient, and research settings.
Product Type:
Purchase decisions in this category split between institutions prioritizing diagnostic depth versus those optimizing throughput volume.
- Fundus Cameras:These devices capture wide-field retinal images through pupil dilation at 30-50 degree angles, utilizing LED or xenon flash illumination. Pediatric hospitals in Germany embed these into standard NICU discharge protocols, driven by national ROP screening mandates and reimbursement alignment for automated image grading.
- Optical Coherence Tomography:Cross-sectional imaging systems achieve 3-8 micron axial resolution using low-coherence interferometry at 840nm or 1050nm wavelengths. Level III neonatal intensive care units in the United States are displacing sequential fundus photography with nurse-operable OCT platforms that collapse specialist-dependent workflows into single-capture protocols.
- Visual Field Analyzers:Automated perimetry systems adapted for infant fixation patterns through preferential looking protocols.
- Retinal Imaging Systems:Integrated platforms combining multiple modalities for comprehensive pediatric ophthalmic assessment.
Volume sits with fundus cameras; growth tilts toward optical coherence tomography.
End User:
Facility type determines capital allocation cycles, with academic medical centers favoring multi-modality suites while community settings prioritize portable, nurse-operable devices.
- Pediatric Hospitals:Comprehensive children's hospitals maintain centralized ophthalmology departments with dedicated imaging suites and fellowship-trained specialists. These institutions drive demand for research-grade spectral-domain OCT systems with angiography capabilities.
- Neonatal Clinics:Standalone NICU facilities and birthing centers require compact, automated screening devices operable by nursing staff without ophthalmology training. Medicaid reimbursement expansion for remote diagnostic coding in rural US centers is accelerating deployment of connected imaging platforms.
- Research Institutions:University laboratories and clinical trial networks procure devices with open software architectures for custom algorithm development.
- Ophthalmology Practices:Private pediatric subspecialty clinics balance equipment costs against procedure volume for ROP screening contracts.
Procurement concentrates at pediatric hospitals; expansion is strongest in neonatal clinics.
Technology:
Technical architecture choices reflect trade-offs between image fidelity, operational simplicity, and regulatory validation burden.
- Digital Imaging:CMOS and CCD sensor-based platforms with 12-16 megapixel resolution dominate installed bases. These systems sustain the broadest compatibility with hospital PACS infrastructure and telemedicine transmission protocols.
- Infrared Imaging:780-940nm wavelength systems enable through-media visualization in dense vitreous hemorrhage cases. Pediatric trauma centers are adopting these for abusive head injury assessment beyond standard neonatal screening applications.
- Automated Screening:AI-guided capture and diagnostic algorithms reduce operator dependency. EU MDR pediatric validation mandates are filtering marginal competitors from this segment, concentrating procurement among established suppliers with ISO 10993 biocompatibility documentation.
- Fluorescence Imaging:Intravenous fluorescein angiography adapted for infant dosing protocols in specialized academic settings.
Installed base favors digital imaging; capability expansion is fastest in automated screening.
Application:
Clinical use case determines device specification requirements, from rapid throughput screening to longitudinal disease monitoring.
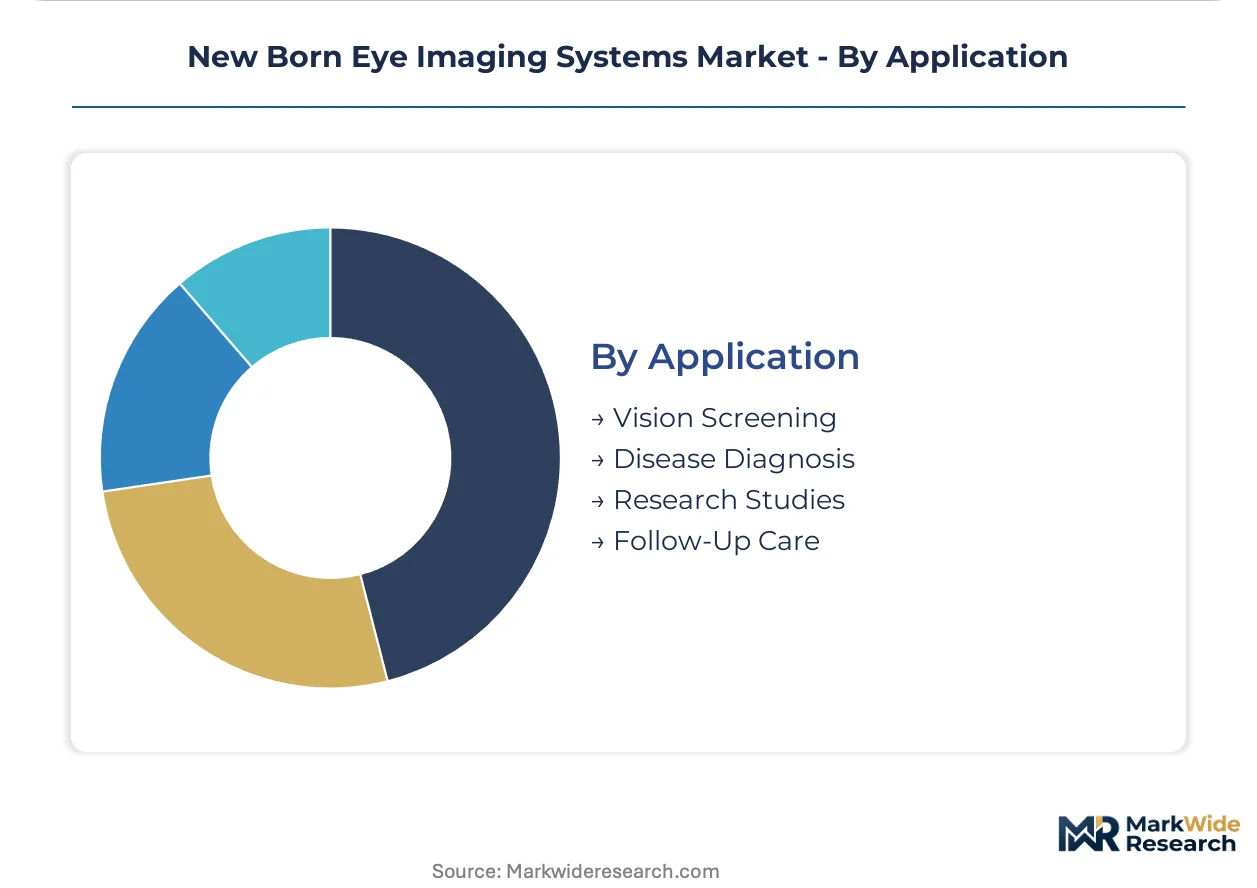
- Vision Screening:Protocol-driven detection of amblyopia risk factors and refractive errors in preverbal infants. US IRA preventive care incentives tying pediatric vision quality metrics to hospital reimbursement are creating procurement preference for audit-trail-compliant automated systems.
- Disease Diagnosis:Definitive characterization of retinopathy of prematurity stage, congenital cataracts, and optic nerve anomalies. German university hospitals are embedding fundus photography into standard NICU discharge checklists, institutionalizing demand for high-resolution diagnostic platforms.
- Research Studies:Longitudinal imaging protocols for natural history documentation and interventional trial endpoints.
- Follow-Up Care:Post-treatment monitoring for laser photocoagulation or anti-VEGF therapy response assessment.
Procedure volume clusters in vision screening; capability investment concentrates in disease diagnosis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg anchors European demand for newborn retinal imaging equipment, where university medical centers drive procurement of research-grade diagnostic platforms. German NICU networks embed fundus photography into standardized discharge protocols, creating institutional pull for automated screening systems. The United States, Japan, China, and India concentrate distinct competitive dynamics across regulatory and cost-sensitive segments.
United States
Level III neonatal intensive care units in Texas and California displace sequential fundus photography with nurse-operable OCT platforms that collapse specialist-dependent workflows. FDA 510(k) pathways for pediatric devices contacting periocular tissue now demand expanded clinical evidence, extending time-to-market for novel form factors. The Boston-Cambridge corridor concentrates telemedicine platform development for rural birthing center deployment.
Germany
University hospitals in Bavaria and North Rhine-Westphalia integrate retinal imaging into standard neonatal discharge checklists, institutionalizing demand for high-resolution diagnostic platforms. EU MDR pediatric validation mandates filter marginal competitors, concentrating procurement among suppliers with ISO 10993 biocompatibility documentation. The Heidelberg-Mannheim medical technology cluster sustains precision optics manufacturing for fundus camera objectives.
Japan
Pediatric ophthalmology departments in Tokyo and Osaka adopt spectral-domain OCT systems with angiography capabilities for research-grade diagnostic depth. PMDA premarket approval timelines for infant-contact devices align with global harmonization efforts, though domestic validation requirements retain distinctive elements. The Nagoya medical device corridor supplies specialized optical components to regional assemblers.
China
Provincial maternal and child health hospitals in Shanghai and Guangzhou expand automated screening deployment amid national ROP prevention program scale-up. NMPA regulatory pathways for pediatric ophthalmic devices increasingly reference international standards, reducing dual-validation burdens for imported platforms. The Suzhou medical technology zone incubates domestic fundus camera manufacturers targeting cost-sensitive county-level hospitals.
India
Outpatient clinics in Maharashtra and Karnataka represent underpenetrated demand for handheld smartphone-connected devices bypassing traditional fundus camera infrastructure. CDSCO import licensing requirements for Class C medical devices create compliance friction for non-domestic suppliers. The Hyderabad medical technology cluster develops low-cost screening platforms for district hospital deployment.
New Born Eye Imaging Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the newborn eye imaging landscape, with optical heritage conglomerates maintaining distinct manufacturing advantages over modular assemblers. The vendor base stratifies across three tiers: premium-tier suppliers with captive lens production, mid-tier systems integrators sourcing precision optics from German and Japanese specialists, and emerging portable platform developers leveraging smartphone computation. Strategic moves concentrate on unbundling after-sales service contracts from equipment leases and negotiating direct third-party maintenance agreements.
Within the premium-tier optical heritage segment, Carl Zeiss Meditec AG and Canon Medical Systems exemplify manufacturers with backward integration into precision objective production. Natus Medical occupies a position among dedicated neonatal care specialists with established distribution channel relationships. Remidio Innovative Solutions represents the portable platform archetype, anchoring cost-sensitive clinic demand through smartphone-connected form factors.
| Leading Market Players |
|---|
| Visunex Medical Systems |
| D-EYE |
| Natus Medical |
| Carl Zeiss Meditec AG |
| Imagine Eyes |
| Remidio Innovative Solutions |
| Canon Medical Systems |
| Topcon Europe Medical |
| Allied Vision Technologies GmbH |
| Others |
Supply & Pricing Matrix
Precision optics engineers concentrated in the Heidelberg-Mannheim corridor command wage premiums that propagate through three-tier pricing spreads, with German labor-cost differentials widening the gap between research-grade spectral-domain systems and nurse-operable screening platforms.
Pricing Analysis
Outcome-based pricing tied to diagnostic throughput per shift anchors equipment valuation in neonatal intensive care procurement. Three-tier pricing structure across premium, standard, and economy levels separates Carl Zeiss Meditec AG's research-grade OCT systems from Natus Medical's mid-tier NICU bundles and Remidio's smartphone-connected handhelds. Cost compression in the portable segment intensifies as Indian and Southeast Asian clinics demand sub-premium alternatives. Neonatal clinics in rural US markets exhibit highest price sensitivity; German university hospitals demonstrate lowest.
Supply Chain Analysis
Freight costs for precision optical components from Germany and Japan amplify landed equipment prices in North American and Asian markets. High-resolution fundus camera objectives draw from captive production at Carl Zeiss and Canon Medical, while mid-tier assemblers source from specialized German and Japanese lens manufacturers. Single-source vulnerability concentrates in 840nm and 1050nm superluminescent diode suppliers. Distribution runs through dedicated neonatal care distribution channels for hospital systems, with direct-to-clinic models emerging for portable platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around EU MDR pediatric validation mandates that filter marginal competitors lacking ISO 10993 biocompatibility documentation and multi-year follow-up study funding.
For Market Incumbents: Deploy backward integration into precision objective production to defend against mid-tier assemblers sourcing from shared German and Japanese optical suppliers. Capture channel control through modular hardware designs that reduce proprietary technician dependency, responding to German university hospital networks internalizing calibration and preventive maintenance. The disintermediation of after-sales service contracts threatens recurring revenue streams. For New Entrants and Emerging Players: US IRA preventive care incentives in pediatric vision screening quality metrics open a window for audit-trail-compliant automated systems targeting Medicaid-reimbursed rural birthing centers. Smartphone-connected portable platforms in Maharashtra and Karnataka outpatient clinics represent the most penetrable white-space, bypassing traditional fundus camera infrastructure entirely. Partner with Hyderabad medical technology cluster domestic manufacturers to navigate CDSCO import licensing friction. For Investors and Strategic Acquirers: Re-rating potential sits with portable platform developers given telemedicine reimbursement expansion and IRA preventive care incentive alignment. Long-term viability favors asset-light designers with smartphone computation leverage over capital-intensive spectral-domain OCT producers facing EU MDR post-market surveillance cost escalation. Watch FDA 510(k) pediatric pathway timeline compression as inflection signal for novel form factor entrants.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Pediatric Validation Pathway | CE marking renewal now requires multi-year infant follow-up studies, elevating compliance costs for fundus camera incumbents. |
| Hospital System Partnership | German university hospital networks internalizing biomedical engineering departments force vendors toward modular hardware designs. |
| Software Companion Development | AI-guided capture algorithms reduce operator dependency, enabling nurse-operable protocols that collapse specialist workflows. |
| Reimbursement Strategy | US Medicaid remote diagnostic coding recognition accelerates capital deployment toward connected imaging platforms in rural centers. |
| Geographic Manufacturing Footprint | Hyderabad cluster domestic production navigates CDSCO import licensing for cost-sensitive Indian district hospital deployment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with neonatal intensive care unit directors, biomedical engineering department heads, pediatric ophthalmology fellowship program directors, and GPO contracts managers. FDA 510(k) premarket notifications, EU MDR technical documentation, PMDA submissions, NMPA registration databases, and CDSCO import licensing records provided device-specific validation. Bottom-up equipment shipment analysis triangulated against top-down hospital procurement database aggregation.
Granularity-level modeling deployed product-type splits across fundus cameras, optical coherence tomography systems, visual field analyzers, and retinal imaging platforms; end-user segmentation across pediatric hospitals, neonatal clinics, research institutions, and ophthalmology practices; technology architecture across digital imaging, infrared imaging, automated screening, and fluorescence imaging; and application use cases across vision screening, disease diagnosis, research studies, and follow-up care. CAGRs derived from installed base evolution and replacement cycle analysis, incorporating ROP screening protocol adoption curves and telemedicine reimbursement policy trajectories.
The model assumes a particular technology adoption path; alternative pathways for AI-guided automated screening would alter the outlook if regulatory validation timelines compress or expand. Forecasts reflect assumptions about EU MDR enforcement consistency, FDA pediatric device pathway stability, and Medicaid remote diagnostic coding permanence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Handheld Dental X-Ray Systems Market