
 Prosthetic Liners Market | 2026-2036
Prosthetic Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Prosthetic Liners Market Analysis
The FDA's 510(k) clearance pathway is pivoting how manufacturers structure clinical evidence packages for silicone liner submissions. Össur leverages its Icelandic R&D campus to sustain polymer science leadership across transfemoral applications. Blatchford Group anchors British manufacturing heritage while competing in automated liner fabrication. Ottobock dominates Central European distribution through direct clinical partnerships with rehabilitation centers.
Prosthetic liners are elastomeric or textile interfaces worn between residual limb skin and prosthetic sockets, typically fabricated from medical-grade silicone, thermoplastic elastomers, or gel-infused fabrics with thickness ranging from 3mm to 9mm to manage shear stress and moisture. Their primary purpose is to distribute pressure uniformly, reduce skin breakdown, and enable stable suspension for lower-limb amputees during ambulation. Silicone formulations lead volume due to established reimbursement codes and clinical familiarity, while thermoplastic variants represent the fastest-expanding margin pool as temperature-adaptive polymers gain traction in pediatric and active-lifestyle segments. Fabric liners retain relevance in price-sensitive channels and markets with limited prosthetist access.
FDA, ISO 10328 structural testing standards, and Medicare's Local Coverage Determinations collectively shape product validation requirements and reimbursement access across the United States. The European Union's Medical Device Regulation imposes stricter clinical follow-up obligations on silicone liner manufacturers seeking CE marking, lengthening time-to-market but elevating barrier-to-entry for new entrants. Stakeholders must monitor evolving prosthetist training certification standards and value-based procurement pilots that increasingly bundle liner replacement schedules with socket fabrication contracts.
Market Dynamics
The prosthetic liners market pivots on reimbursement code consolidation and value-based procurement pilots that bundle liner replacement schedules with socket fabrication contracts, compressing standalone product margins while elevating service-integrated offerings.
Growth Catalysts
- Veterans Affairs Expansion:US Department of Veterans Affairs healthcare systems are broadening prosthetic coverage mandates for wounded service members, creating dedicated demand channels with predictable replacement cycles.
- ISO 10328 Standardization:Structural testing protocols for prosthetic limb components are harmonizing validation requirements across European markets, reducing redundant certification costs for silicone liner manufacturers.
- Temperature-Adaptive Polymers:Thermoplastic elastomer formulations with dynamic viscosity response are penetrating pediatric and high-activity amputee segments previously dominated by static silicone interfaces.
Market Restraints
- Medical-Grade Silicone Concentration:Raw material supply for high-purity silicone elastomers concentrates among a limited set of specialty chemical producers, exposing liner fabricators to input cost volatility and allocation risk.
- EU MDR Clinical Follow-Up Burden:The European Union's Medical Device Regulation imposes extended post-market surveillance obligations on silicone liner manufacturers, lengthening CE marking timelines and elevating compliance overhead.
- Fabric Liner Substitution:Textile-based interfaces retain significant share in price-sensitive channels and regions with limited prosthetist access, capping premium silicone penetration in emerging markets.
Strategic Opportunities
- Automated Fabrication Integration:Computer-numerical control and additive manufacturing convergence is enabling mass-customization of liner thickness gradients and regional stiffness variation at unit economics competitive with molded production.
- Medicare LCD Bundling Pilots:Local Coverage Determination experiments in select US jurisdictions are testing integrated reimbursement for liner-socket systems, rewarding manufacturers with clinical training and fitting service capabilities.
- Pediatric Growth Accommodation:Expandable liner architectures that adjust to residual limb volume changes without full replacement address the underserved juvenile amputee population where frequent refitting creates recurring revenue potential.
Industry Challenges
- Prosthetist Certification Bottleneck:Specialized fitting expertise for advanced silicone suspension systems remains concentrated among credentialed clinicians, limiting product uptake in markets with training infrastructure gaps.
- Legacy Socket Interface Compatibility:New liner materials and locking mechanisms require redesign of existing socket fabrication workflows, creating adoption friction among established prosthetic clinics with sunk equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prosthetic Liners Market |
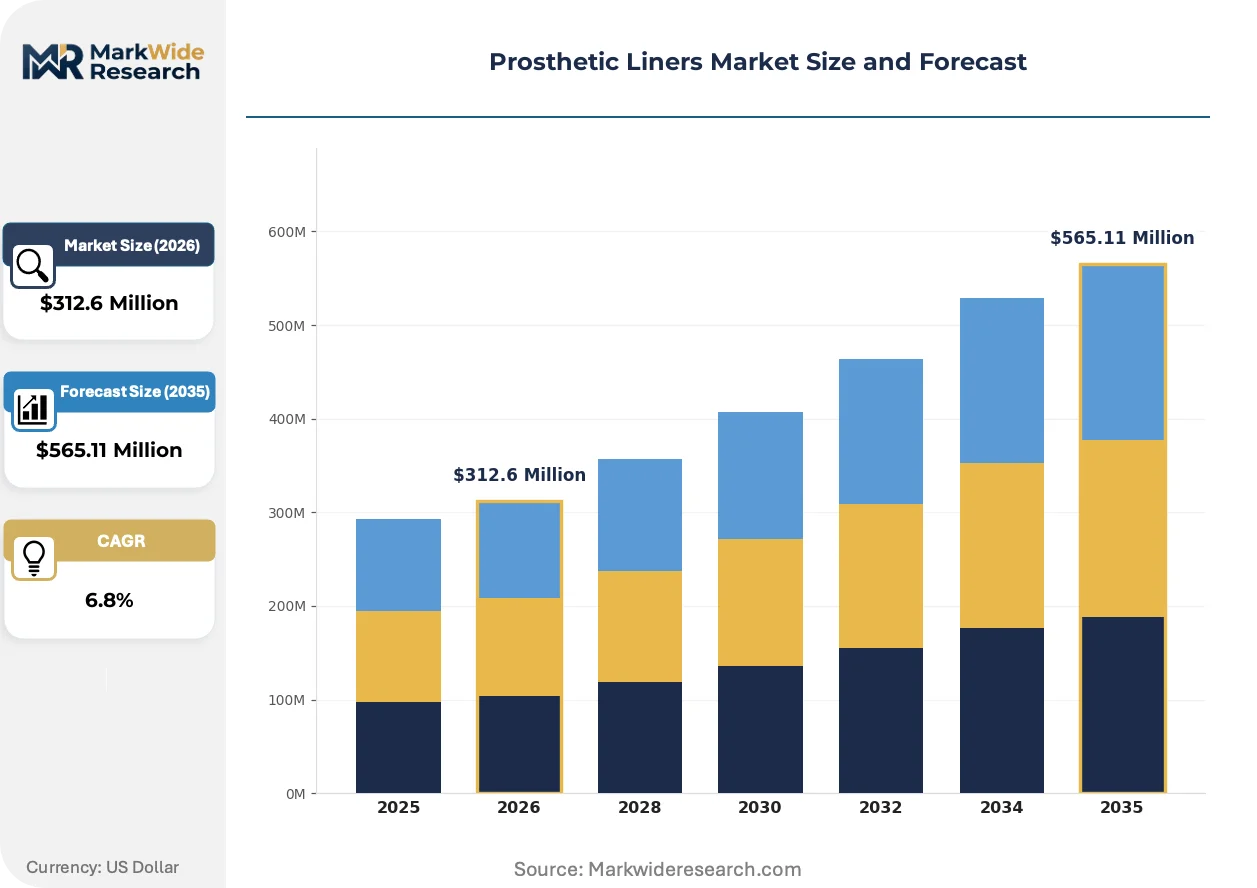
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Rubber, Fabric, Thermoplastic Application: Transfemoral, Transtibial, Symes, Above-knee End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Distribution Channel: Online Retailers, Medical Supply Stores, Direct Sales, Distributors |
| Companies Covered | Blatchford Group, ALPS South, Össur, Streifeneder ortho.production GmbH, Hanger, Ottobock, Fillauer, Knit-Rite, WillowWood Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prosthetic Liners Market Emerging Trajectories
Material science advances and regulatory harmonization are compressing product development cycles while elevating clinical evidence requirements for market access.
Shear-reduction gel matrices embedded within silicone substrates are converging with moisture-wicking textile laminates to create hybrid liners that address multiple skin integrity failure modes simultaneously. Active-lifestyle amputees and competitive athletes are adopting these interfaces at accelerating rates. This convergence is compressing the addressable market for single-function fabric liners while expanding premium pricing headroom for multifunctional products.
The FDA's 510(k) clearance pathway for silicone-based devices is streamlining premarket submission requirements through established predicate device referencing, reducing average review timelines for incremental formulation modifications. Manufacturers are restructuring clinical evidence packages to emphasize biocompatibility and durability testing over novel efficacy claims. Transfemoral applications benefit most from this regulatory efficiency given higher complication rates and corresponding predicate abundance.
Prosthetic clinics are consolidating purchasing decisions through group purchasing organizations and integrated delivery networks, displacing individual practitioner discretion in liner brand selection. Distributor relationships and volume rebate structures are replacing product performance as the primary vendor selection criterion. Germany and the United States exhibit this concentration most visibly, where rehabilitation center chains and veterans hospital networks command negotiating leverage over standalone manufacturers.
Prosthetic Liners Market Segmentation
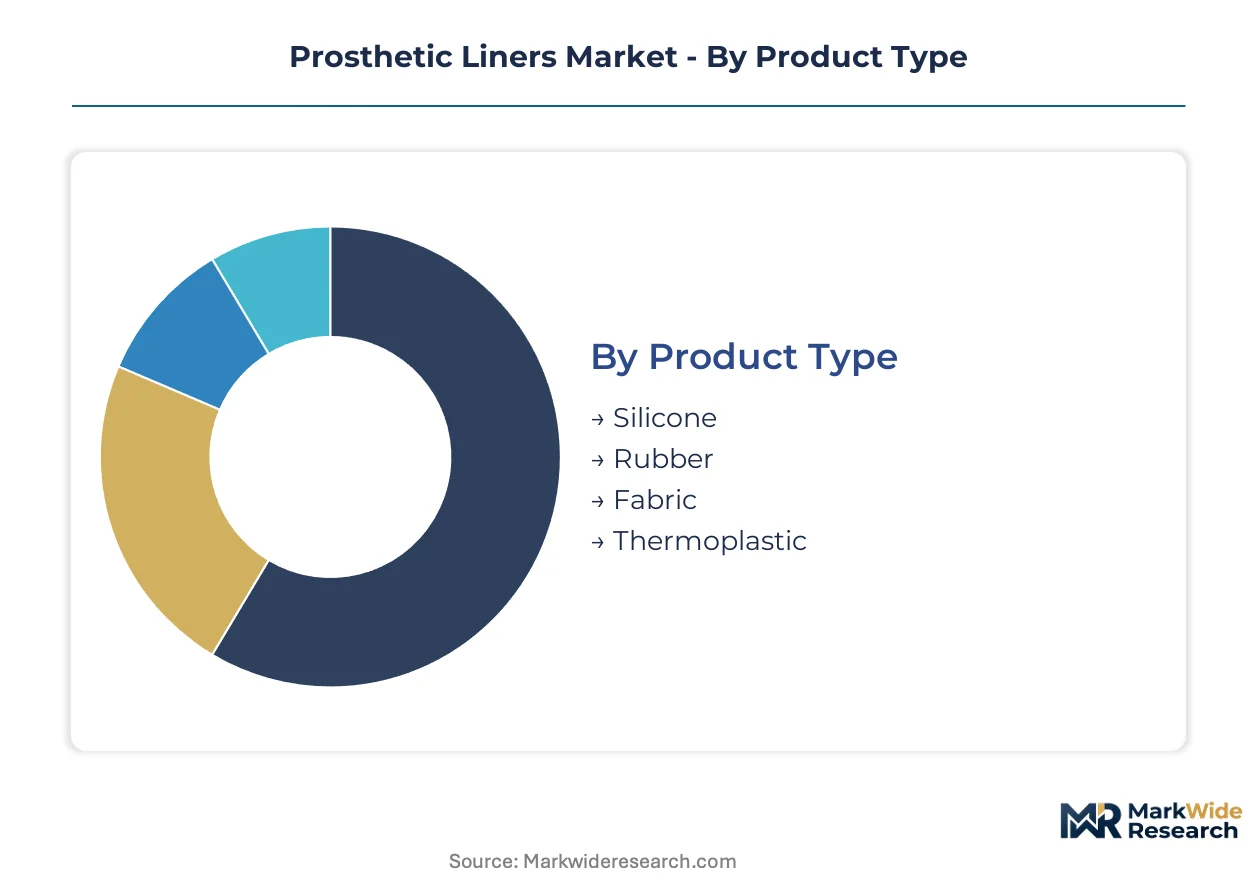
Segmentation in prosthetic liners reveals how replacement cycles, clinical settings, and procurement channels reshape manufacturer priorities. Upgrade timelines differ sharply between acute care and community-based fitting services.
Product Type:
Replacement frequency varies dramatically by liner material chemistry, with silicone users averaging shorter cycles due to wear-induced stiffness loss while thermoplastic alternatives extend service intervals through self-healing polymer properties.
- Silicone:Medical-grade elastomer formulations dominate volume through established Medicare reimbursement codes and prosthetist familiarity. Veterans Affairs facilities in the United States standardize on silicone for transfemoral fittings due to predictable shear stress management and moisture sealing.
- Thermoplastic:Temperature-responsive polymers adjust viscosity during ambulation, reducing skin breakdown in pediatric patients with fluctuating residual limb volume. German rehabilitation centers pilot these materials for adolescent amputees requiring frequent refitting without full liner replacement.
- Rubber:Neoprene and natural rubber variants serve price-sensitive institutional procurement in emerging markets with limited silicone supply chain access.
- Fabric:Textile-based interfaces with gel-infused laminates retain relevance for home care settings and regions with scarce certified prosthetist density.
Volume placements concentrate in silicone; the faster expansion belongs to thermoplastic.
Application:
Socket interface geometry dictates liner thickness gradients and suspension mechanism selection, with transfemoral fittings requiring more complex pressure distribution engineering than distal limb applications.
- Transfemoral:Above-knee amputations demand thicker liners (6-9mm) with ischial weight-bearing zones and advanced locking mechanisms. ISO 10328 structural testing requirements elevate validation costs for transfemoral-specific products.
- Transtibial:Below-knee applications represent the highest placement volume through simpler fabrication workflows and broader prosthetist training coverage. Medicare Local Coverage Determinations prioritize transtibial liner replacement schedules in bundled reimbursement pilots.
- Symes:Ankle disarticulation fittings require specialized distal padding to accommodate bulbous residual limb geometry without compromising suspension.
- Above-knee:Hip disarticulation and knee disarticulation segments command premium pricing for custom-fabricated liners with extended proximal sealing zones.
Transtibial captures the highest unit placements; above-knee applications are climbing the fastest on rising trauma-related amputation incidence.
End User:
Procurement authority is consolidating through integrated delivery networks and government healthcare systems, displacing individual clinician discretion in liner brand selection.
- Hospitals:Acute care settings manage initial post-amputation fitting and temporary liner provision during limb maturation. US Department of Veterans Affairs hospitals operate dedicated prosthetic procurement frameworks with centralized supplier qualification.
- Rehabilitation Centers:Specialized facilities in Germany coordinate long-term liner replacement through direct manufacturer partnerships and on-site fabrication laboratories.
- Home Care:Remote fitting services and mail-order liner replacement are expanding in rural US markets with prosthetist access deficits.
- Clinics:Independent prosthetic practices retain influence in custom silicone fabrication for complex residual limb presentations.
Rehabilitation centers dominate premium liner placements; home care channels are gaining share fastest on telehealth integration.
Distribution Channel:
Channel economics reflect inventory carrying costs, technical support requirements, and the degree of prosthetist involvement in product selection.
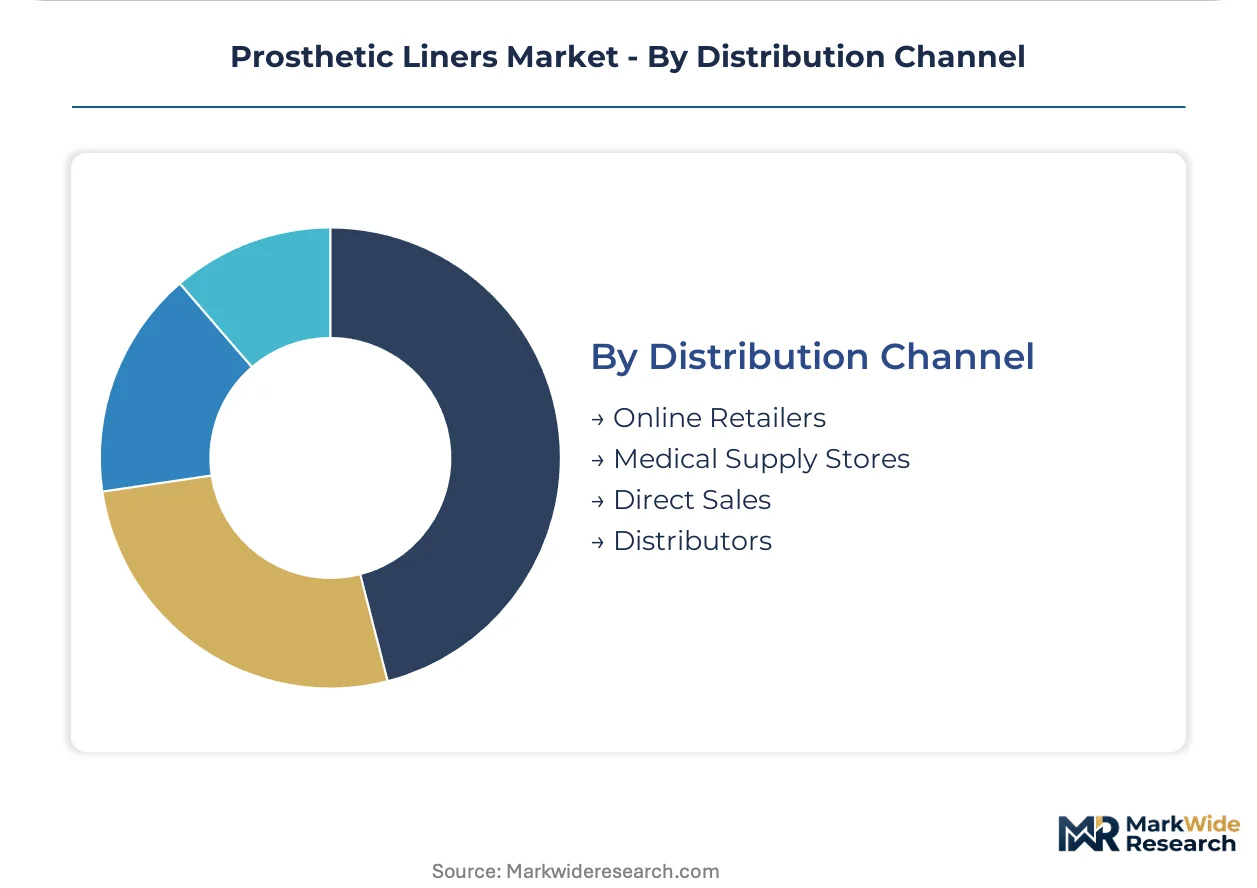
- Direct Sales:Manufacturers like Ottobock and Össur deploy clinical specialists to rehabilitation centers for fitting support and technical training. This channel captures the highest margin per unit through service bundling.
- Distributors:Regional medical device wholesalers aggregate demand from independent clinics and smaller hospital systems. German distributors maintain refrigerated storage for temperature-sensitive thermoplastic inventory.
- Medical Supply Stores:Retail channels serve cash-pay customers and replacement liner purchases outside insurance reimbursement cycles.
- Online Retailers:E-commerce penetration remains limited by fitting complexity, though standardized transtibial liners see growing direct-to-consumer volume in the United States.
Direct sales command the highest value per placement; online retailers are expanding most quickly in standardized product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for prosthetic liners concentrates in healthcare systems with established reimbursement frameworks and specialized rehabilitation infrastructure. Veterans Affairs hospitals in the United States and Germany's statutory health insurance networks anchor replacement volume. Regulatory pathways in these markets determine how quickly novel materials reach clinical adoption.
United States
The Department of Veterans Affairs operates dedicated prosthetic procurement frameworks with centralized supplier qualification and predictable replacement cycles for wounded service members. FDA's 510(k) clearance pathway streamlines premarket submissions for silicone-based devices through established predicate referencing. Minneapolis and San Antonio anchor regional fitting networks where rehabilitation centers coordinate long-term liner management with socket fabrication laboratories.
Germany
Statutory health insurance reimbursement codes standardize on silicone liners for transfemoral fittings, with Ottobock's headquarters in Duderstadt anchoring regional manufacturing and clinical training networks. The EU Medical Device Regulation imposes extended post-market surveillance obligations that lengthen CE marking timelines for new entrants. Bavaria and North Rhine-Westphalia concentrate rehabilitation center chains that command negotiating leverage through volume purchasing agreements.
United Kingdom
NHS England's specialized commissioning frameworks govern prosthetic provision for complex limb presentations, with Blatchford Group maintaining British manufacturing heritage alongside automated fabrication investments. MHRA convergence with EU MDR requirements elevates clinical evidence standards for market access. The Midlands and Greater London host integrated prosthetic service networks that bundle liner replacement with socket fabrication contracts.
Japan
PMDA's pharmaceutical and medical device agency maintains distinct approval pathways for silicone elastomer products, with thermoplastic alternatives gaining traction in pediatric segments through temperature-adaptive polymer formulations. METI's healthcare technology assessment frameworks influence reimbursement pricing for advanced suspension systems. The Kanto region around Tokyo concentrates prosthetist training institutions and university-affiliated rehabilitation hospitals.
France
ANSM's national health product safety agency oversees post-market surveillance for silicone liners distributed through hospital-based prosthetic services. HAS technology assessment determines reimbursement levels for premium suspension mechanisms versus standard fabric interfaces. The Île-de-France region anchors specialized limb fitting centers that serve as referral hubs for complex residual limb presentations from across the country.
Prosthetic Liners Market Vendor Landscape
German and Icelandic producers anchor the premium tier; British and American specialists hold mid-market positions through regional fabrication expertise. The vendor base organizes around three archetypes: integrated rehabilitation service providers, pure-play liner manufacturers, and diversified orthopedic conglomerates with prosthetic divisions. Competitive moves concentrate on automated fabrication integration and direct clinical partnership structures that displace distributor intermediaries.
Within the integrated service tier, Ottobock and Össur exemplify geographic anchoring strategies—Ottobock through its Duderstadt headquarters proximity to German rehabilitation networks, Össur through its Icelandic R&D campus sustaining polymer science leadership. Blatchford Group occupies a position representing British manufacturing heritage competing against automated fabrication convergence. Hanger sits within the American clinical services archetype, leveraging prosthetist employment density for captive liner placement volume. Streifeneder ortho.production GmbH represents specialized German fabrication expertise serving Central European distribution channels.
| Leading Market Players |
|---|
| Blatchford Group |
| ALPS South |
| Össur |
| Streifeneder ortho.production GmbH |
| Hanger |
| Ottobock |
| Fillauer |
| Knit-Rite |
| WillowWood Global |
| Others |
Supply Flow & Price Mechanics
Certified prosthetist concentrations in Germany and the United States drive labor-cost differentials that widen spreads between premium silicone and economy fabric tiers. These regional skill premiums translate directly into fitting-service bundling that separates high-margin direct sales from price-pressured distributor channels.
Pricing Analysis
Volume placements cluster in standard silicone formulations while thermoplastic variants capture expanding margins through temperature-adaptive performance premiums. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10328 certification grade, after-sales fitting support, and geographic delivery cost. Price erosion runs through rubber and fabric segments as Asian manufacturers penetrate institutional procurement in emerging markets. Veterans Affairs facilities exhibit lowest price sensitivity due to centralized supplier qualification, while independent clinics in rural markets face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade silicone elastomer feedstock concentrated among German and Japanese specialty chemical producers. Raw material procurement draws from high-purity silicone polymers, thermoplastic elastomer resins, and textile substrate laminates. Tariff exposure on Chinese-sourced gel-infused fabrics elevates input cost volatility for hybrid liner fabricators. Distribution runs through direct manufacturer clinical specialists to rehabilitation centers, bypassing traditional medical device wholesalers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prosthetic liners market sits in a technology-transition phase where thermoplastic elastomer formulations displace static silicone interfaces in pediatric and high-activity segments. Temperature-adaptive polymer chemistry is replacing legacy materials that lack dynamic viscosity response during ambulation.
For Market Incumbents: To counter automated fabrication convergence from British and German competitors, deepen captive supply of medical-grade silicone feedstock through backward integration into specialty chemical partnerships. Anchor capacity addition in Bavaria and North Rhine-Westphalia rehabilitation corridors to defend direct clinical channel control against distributor displacement. For New Entrants and Emerging Players: Group purchasing organizations in US integrated delivery networks represent the most penetrable channel archetype for thermoplastic liner introduction without prosthetist certification bottlenecks. Target Medicare LCD bundling pilots in select jurisdictions as the go-to-market angle for service-integrated offerings that bypass standalone product margin compression. For Investors and Strategic Acquirers: The window for entry favors mid-cap fabrication specialists with automated CNC and additive manufacturing capabilities over pure-play material suppliers. Acquisition target archetypes include German ortho.production specialists with CE marking infrastructure and established rehabilitation center relationships. Watch FDA 510(k) clearance velocity for thermoplastic predicates as the inflection indicator signaling regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical follow-up obligations lengthen timelines but elevate competitive barriers for new entrants. |
| Hospital System Partnership | US Veterans Affairs centralized procurement creates predictable replacement cycles with dedicated demand channels. |
| Reimbursement Strategy | Medicare LCD bundling pilots reward manufacturers with clinical training and socket fabrication service capabilities. |
| Software Companion Development | Remote fitting algorithms for home care channels address prosthetist access deficits in rural markets. |
| Automated Fabrication Investment | CNC and additive manufacturing convergence enables mass-customization at unit economics competitive with molded production. |
Methodological Framework
FDA 510(k) premarket notification databases, ISO 10328 structural testing registries, and CMS Medicare Local Coverage Determination archives formed the secondary backbone for this analysis. Primary interviews with prosthetist training directors, Veterans Affairs procurement officers, biomedical engineers at rehabilitation centers, and GPO contracts managers validated demand-side assumptions. Bottom-up placement volume estimates triangulated against top-down reimbursement code expenditure analysis across the analysis window.
Historical trendline analysis of silicone and thermoplastic liner replacement cycles informed growth trajectory modeling across product type, application, end user, and distribution channel segmentation dimensions. CAGRs were derived from fitted exponential growth curves applied to prosthetist placement density and statutory insurance reimbursement rate evolution. Forecast inputs incorporated EU MDR compliance cost trajectories and temperature-adaptive polymer adoption curves in pediatric segments.
Caveats apply where FDA regulatory pathway modifications or EU MDR post-market surveillance burden revisions could materially shift the outlook for new entrant viability. Forecasts reflect assumptions about prosthetist certification pipeline expansion and veterans healthcare budget allocation continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Cervical Spine System Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market