
 Urethral Stricture Market | 2026-2036
Urethral Stricture Market Size, Share, and Industry Trends Forecast 2026-2036
Urethral Stricture Market Outlook
The EU Medical Device Regulation is hardening clinical evidence requirements for implantable urological devices, compelling manufacturers to expand pre-market validation budgets. Boston Scientific Corporation leverages its endourology portfolio to sustain leadership in transurethral stent innovation. Cook Medical anchors its competitive position through specialized manufacturing of dilation systems for ambulatory settings.
Urethral stricture denotes a pathological narrowing of the urethral lumen caused by spongiofibrosis, typically resulting from trauma, infection, or iatrogenic injury, with strictures measuring less than 2 cm amenable to direct vision internal urethrotomy and longer segments requiring substitution urethroplasty with buccal mucosa grafts. Its primary purpose is to restore urinary flow and prevent downstream complications including recurrent urinary tract infections, bladder stones, and renal impairment. Urethral stents command the largest revenue share among product types due to recurring replacement cycles and premium pricing on drug-eluting variants, while minimal invasive delivery modes are expanding fastest as ambulatory surgical centers in Germany and the United States invest in same-day dilation protocols. Hospitals retain the deepest margin pools for complex urethroplasty procedures requiring inpatient stays and multidisciplinary care teams.
The FDA enforces biocompatibility testing under ISO 10993 for permanent implantable urethral devices, while the EU Medical Device Regulation mandates notified body oversight and post-market surveillance for all Class IIb and III urological implants. Japan's PMDA requires localized clinical trials for novel stent materials, creating staggered market entry timelines across OECD jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for outpatient urethrotomy versus inpatient urethroplasty as payers recalibrate episode-based payment models.
Market Dynamics
EU Medical Device Regulation hardening is compressing market entry timelines for implantable urological devices while ambulatory surgical centers in Germany and the United States accelerate same-day procedure adoption.
Growth Catalysts
- MDR Clinical Evidence Mandates:The EU Medical Device Regulation compels manufacturers to expand pre-market validation protocols, elevating barriers that favor established stent producers with deep clinical trial resources.
- Same-Day Dilation Protocols:Ambulatory surgical centers across the United States invest in minimal invasive delivery systems to capture episode-based reimbursement incentives from commercial payers.
- Drug-Eluting Stent Materials:Biocompatible polymer coatings that suppress spongiofibrosis recurrence are extending replacement cycles while commanding premium positioning in hospital procurement.
Market Restraints
- Biocompatibility Testing Costs:ISO 10993 validation requirements for permanent implants impose six-figure pre-market expenditure floors that exclude mid-tier manufacturers.
- Notified Body Bottlenecks:EU MDR designation delays for Class III urological devices stretch certification timelines to 18-24 months, freezing product pipelines.
- Substitution Urethroplasty Preference:High-volume academic medical centers increasingly bypass stenting for buccal mucosa graft procedures with superior long-term patency rates.
Strategic Opportunities
- Japanese PMDA Localization:Novel stent materials face staggered entry timelines requiring Japan-specific clinical trials, creating first-mover windows for compliant manufacturers.
- Outpatient Reimbursement Recalibration:Payers in Germany and the United States are testing episode-based models that favor same-day urethrotomy over inpatient urethroplasty.
- Digital Post-Market Surveillance:Connected stent monitoring systems align with EU MDR post-market clinical follow-up mandates while generating real-world evidence for payers.
Industry Challenges
- Multidisciplinary Care Coordination:Complex urethroplasty procedures require synchronized urology, reconstructive surgery, and anesthesia teams that strain staffing models.
- Stent Migration and Encrustation:Chronic complications with permanent metal mesh designs drive revision surgeries that erode manufacturer reputation and trigger liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urethral Stricture Market |
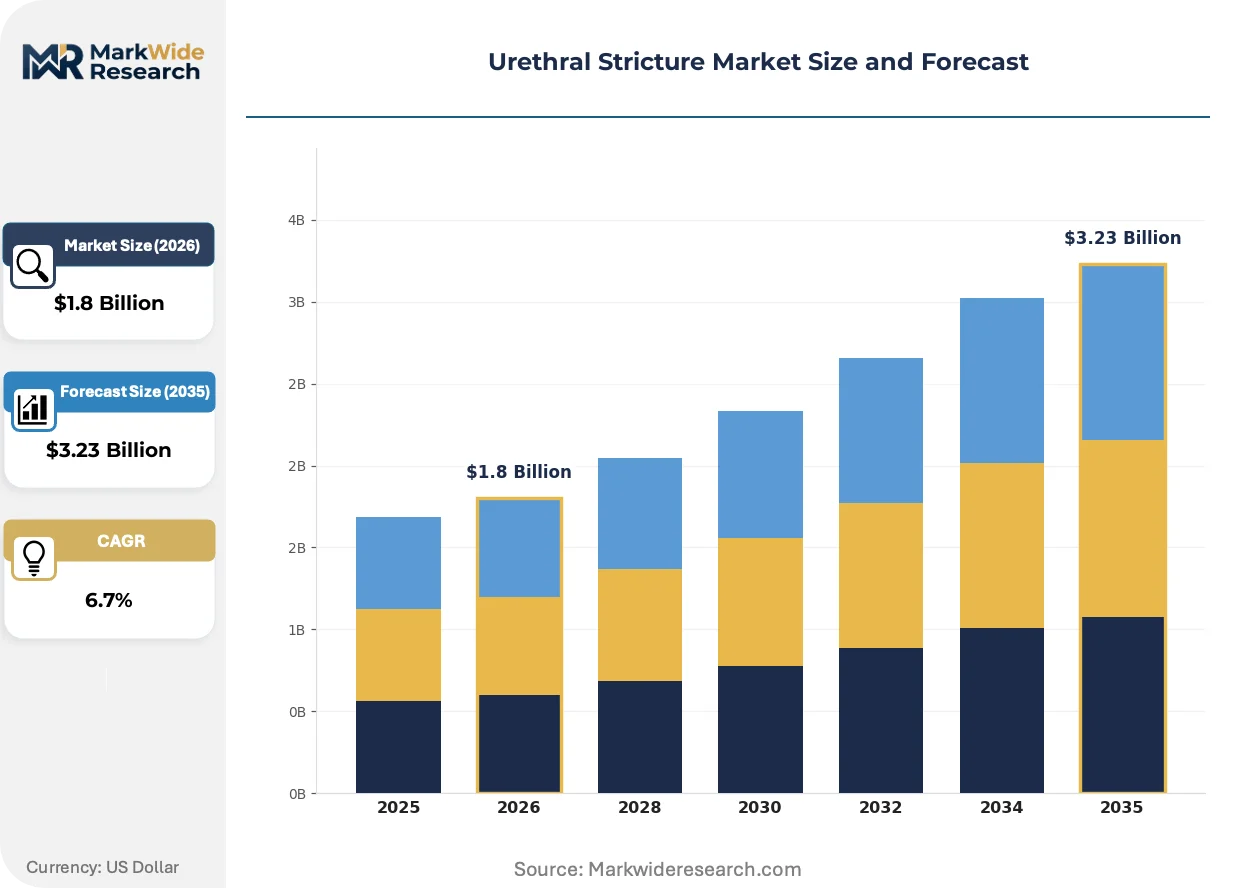
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urethral Stents, Surgical Instruments, Dilators, Transurethral Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Urgent Care Facilities Delivery Mode: Invasive, Minimal Invasive, Outpatient, Emergency Application: Urological Surgeries, Diagnostic Procedures, Preventative Care, Postoperative Care |
| Companies Covered | Boston Scientific Corporation, Stryker Corporation, Cook Medical, Olympus Corporation, Karl Storz, Richard Wolf GmbH, Teleflex Incorporated, B. Braun Melsungen AG, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urethral Stricture Market Strategic Shifts
Material science convergence with digital health infrastructure is redefining competitive advantage in urethral stricture management, shifting value capture from device sales toward integrated care pathways.
Biodegradable magnesium alloy stents are absorbing market attention as an alternative to permanent metal implants. Academic medical centers in Germany pilot these devices to eliminate secondary removal procedures. The technology is absorbing revenue from conventional stent replacement cycles while compressing total cost-of-ownership metrics for hospital procurement committees.
The EU Medical Device Regulation's post-market surveillance requirements for Class IIb and III implants mandate systematic clinical follow-up. Manufacturers must deploy patient registries and real-world evidence platforms to maintain conformity. Drug-eluting stent portfolios face the steepest compliance burden as notified bodies scrutinize long-term biocompatibility data.
Ambulatory surgical centers now specify bundled pricing for dilation procedures that include device, facility, and physician components. This procurement model displaces traditional fee-for-service purchasing in the United States and Germany. Hospital systems respond by consolidating vendor relationships to secure volume discounts on minimal invasive delivery systems.
Urethral Stricture Market Segmentation
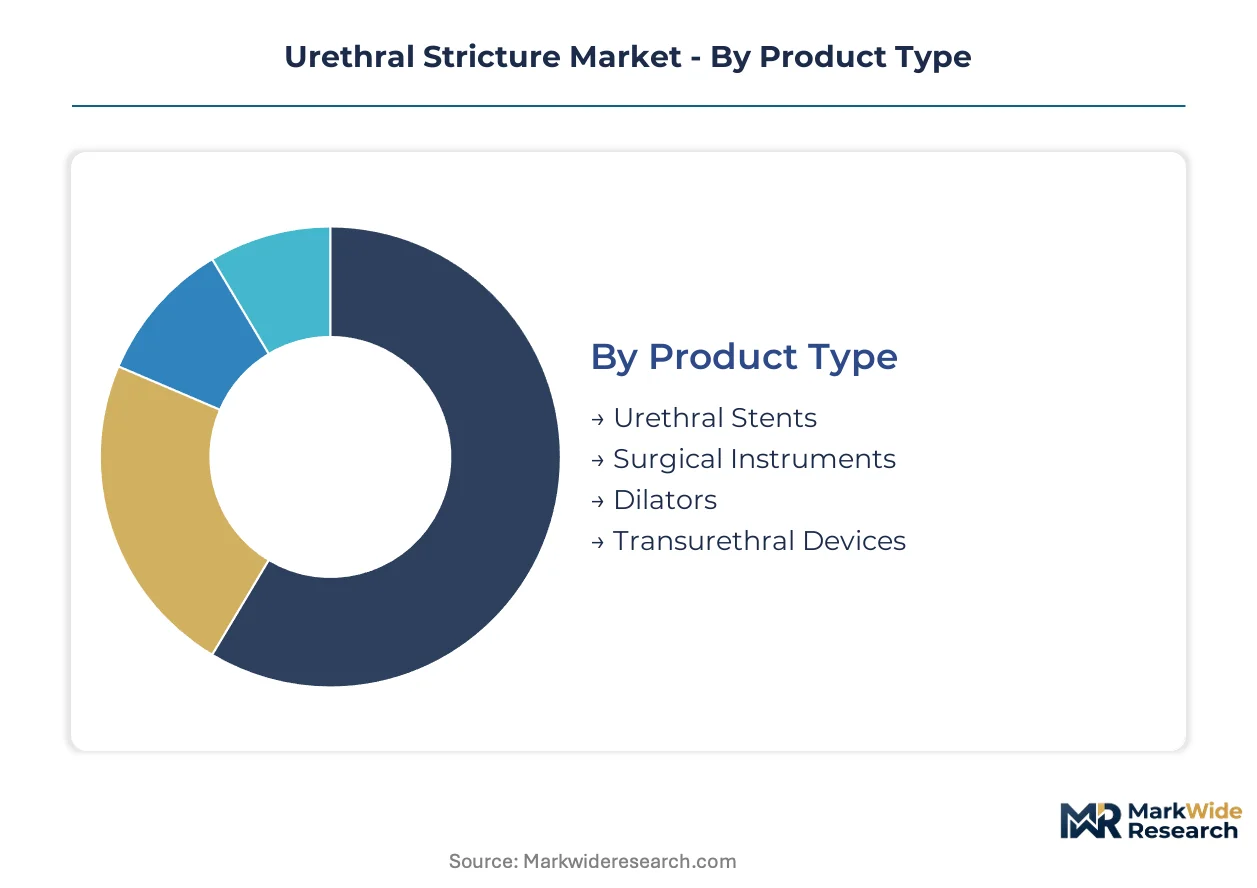
Urethral stricture management demands precise segmentation alignment between anatomical complexity, care setting economics, and reimbursement pathways. Device procurement committees evaluate product categories against episode-based payment models and ambulatory capability.
Product Type:
Urethral stents anchor volume share through recurring replacement cycles, while drug-eluting variants command premium positioning; surgical instruments and dilators split the remainder between acute intervention and maintenance protocols.
- Urethral Stents:Permanent and temporary mesh constructs restore luminal patency in spongiofibrotic strictures. Hospitals in Germany prioritize drug-eluting polymer coatings that suppress recurrence, extending replacement intervals while absorbing higher upfront procurement costs.
- Surgical Instruments:Specialized forceps, retractors, and suturing systems enable open urethroplasty with buccal mucosa grafts. Academic medical centers in the United States bypass stenting for these reconstructive toolsets where long-term patency data favors substitution over repeated dilation.
- Dilators:Graduated calibration systems permit serial urethral expansion without implantation.
- Transurethral Devices:Endoscopic platforms integrate visualization with therapeutic delivery.
Today's leader: Urethral Stents. Tomorrow's challenger: Surgical Instruments.
End User:
Care setting economics determine device selection, with inpatient reimbursement favoring complex reconstruction and outpatient incentives accelerating minimal invasive adoption.
- Hospitals:Tertiary centers manage complex urethroplasty requiring multidisciplinary urology, reconstructive surgery, and anesthesia teams. Inpatient stays and bundled payment models concentrate margin pools for implantable devices and substitution procedures.
- Ambulatory Surgical Centers:Same-day dilation protocols capture episode-based reimbursement from commercial payers. Facilities in the United States invest in minimal invasive delivery systems to displace hospital-based urethrotomy volume.
- Clinics:Office-based settings handle diagnostic workup and postoperative surveillance.
- Urgent Care Facilities:Acute urinary retention management requires rapid catheterization capability.
Revenue concentrates in Hospitals; Ambulatory Surgical Centers are expanding most quickly.
Delivery Mode:
Procedure invasiveness correlates directly with recovery timeline, reimbursement tier, and device complexity requirements.
- Minimal Invasive:Endoscopic dilation and temporary stent deployment enable same-day discharge. German ambulatory centers pilot biodegradable magnesium alloy constructs to eliminate secondary removal procedures, compressing total cost-of-ownership.
- Invasive:Open urethroplasty with graft harvest demands inpatient infrastructure and specialized surgical teams. Academic medical centers maintain preference for this modality where stricture length exceeds substitution thresholds.
- Outpatient:Scheduled surveillance and maintenance dilation occur outside acute settings.
- Emergency:Acute urinary retention requires immediate suprapubic or urethral catheterization.
Minimal Invasive delivery is climbing the fastest as payers recalibrate toward episode-based models.
Application:
Clinical intent spans definitive intervention, diagnostic clarification, recurrence prevention, and postoperative monitoring across the care continuum.
- Urological Surgeries:Definitive stricture management encompasses endoscopic incision, stent placement, and open reconstruction. Procedure volume concentrates in high-throughput centers where surgeon experience correlates with patency outcomes.
- Diagnostic Procedures:Cystoscopy and retrograde urethrography establish stricture location, length, and etiology. Accurate characterization determines candidacy for endoscopic versus open intervention.
- Preventative Care:Surveillance protocols detect recurrence before symptomatic progression.
- Postoperative Care:Catheter management and wound surveillance follow reconstruction.
Urological Surgeries dominate current value capture; Diagnostic Procedures are gaining share fastest through surveillance protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern urethral stricture management traces its clinical foundations to post-war reconstructive urology advances in Germany and the United States. These two markets continue to drive procedural innovation and regulatory precedent for implantable urological devices.
United States
Ambulatory surgical centers in Texas and Florida are scaling same-day dilation protocols to capture episode-based reimbursement from commercial payers. The FDA enforces ISO 10993 biocompatibility testing for permanent urethral implants under its Class IIb and III device oversight. Academic medical clusters in Boston and Cleveland maintain preference for open urethroplasty with buccal mucosa grafts where stricture length exceeds endoscopic thresholds.
Germany
Hospitals in Bavaria and North Rhine-Westphalia are expanding adoption of minimal invasive urethral stent procedures with drug-eluting polymer coatings. The EU Medical Device Regulation mandates notified body oversight and post-market surveillance for all Class IIb and III urological implants, compressing certification timelines. Berlin-based research centers are piloting biodegradable magnesium alloy stents to eliminate secondary removal procedures.
Japan
Metropolitan Tokyo and Osaka medical centers are advancing endoscopic platforms for diagnostic urethrography and therapeutic delivery. The PMDA requires localized clinical trials for novel stent materials, creating staggered market entry timelines compared to OECD counterparts. Kyushu region hospitals are integrating connected monitoring systems to satisfy post-market clinical follow-up mandates.
United Kingdom
NHS trusts in London and the Midlands are consolidating procurement for dilation systems under bundled payment frameworks. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR equivalence agreements for device certification. Manchester and Edinburgh academic centers are building multidisciplinary reconstructive surgery teams for complex urethroplasty procedures.
India
Corporate hospital chains in Maharashtra and Karnataka are importing minimal invasive delivery systems to serve rising trauma-related stricture caseloads. The Central Drugs Standard Control Organization regulates urological implants under its medical device rules framework. Delhi-NCR and Chennai clusters are developing domestic manufacturing capabilities for graduated dilator systems.
Urethral Stricture Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the urethral stricture device spectrum. The market structure concentrates around diversified medical technology conglomerates with deep clinical trial resources and specialized urological instrument fabricators with focused manufacturing expertise. Three archetypes dominate: integrated endourology platform owners, dedicated reconstructive surgery tool specialists, and regional dilation system manufacturers. Competitive moves center on M&A to acquire drug-eluting coating capabilities and strategic partnerships with ambulatory surgical center networks.
Among US-based diversified medical technology groups, Boston Scientific Corporation and Stryker Corporation exemplify the integrated platform archetype with broad endourology portfolios spanning visualization, therapeutic delivery, and implantable devices. Cook Medical, an Indiana-based private company, anchors the specialized manufacturing tier through focused production of dilation systems and urological access devices. German precision instrument fabricators including Karl Storz and Richard Wolf GmbH occupy positions in the rigid endoscopy and surgical visualization segment, leveraging Baden-Württemberg's optical engineering heritage. Olympus Corporation represents the Japanese multinational archetype with consolidated urological and gastrointestinal endoscopy platforms.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Stryker Corporation |
| Cook Medical |
| Olympus Corporation |
| Karl Storz |
| Richard Wolf GmbH |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Medtronic plc |
| Others |
Value Chain & Pricing Dynamics
Biocompatible polymer coating costs flow from specialty chemical suppliers through German and US medical device manufacturers into three-tier pricing structures across premium drug-eluting stents, standard permanent mesh constructs, and economy-grade temporary dilators. Procurement committees at ambulatory surgical centers compress margins on minimal invasive delivery systems while academic medical centers absorb premium positioning for complex reconstruction toolsets.
Pricing Analysis
Episode-based bundled pricing for same-day dilation procedures now dominates US and German procurement, separating premium drug-eluting variants with extended replacement intervals from standard metal stents and economy-grade calibration systems. Price differentiation hinges on ISO 10993 biocompatibility certification tier and surgeon training bundling. Pricing pressure intensifies in the standard tier as mid-tier manufacturers exit due to EU MDR validation cost floors. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with bundled payment carve-outs show least.
Supply Chain Analysis
Stent retrieval and refurbishment flows remain minimal given permanent implant designs, though biodegradable magnesium alloy pilots in Berlin and Bavaria are introducing reverse logistics for explant analysis. Manufacturing concentrates in Germany, the United States, and Japan, with optical engineering clusters in Baden-Württemberg feeding rigid endoscopy production. Nitinol wire and biocompatible polymer coatings draw from aerospace and specialty chemical supply bases. Single-source vulnerability runs through notified body certification bottlenecks for EU MDR Class III devices. Distribution runs through hospital procurement consortia and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urethral stricture market represents a late-cycle quality story as payers recalibrate reimbursement toward outpatient protocols with superior cost-of-ownership profiles, privileging manufacturers with drug-eluting stent portfolios and minimal invasive delivery capabilities.
For Market Incumbents: Acquire drug-eluting coating capabilities to defend against substitution urethroplasty preference at academic medical centers. Expand backward integration into biocompatible polymer supply to offset ISO 10993 testing cost inflation and secure margin pools in premium tier positioning. For New Entrants and Emerging Players: Enter via biodegradable stent material licensing to capture first-mover windows in Japanese PMDA localization requirements. Target Indian corporate hospital chains importing minimal invasive systems for trauma-related stricture caseloads, leveraging domestic dilator manufacturing partnerships as go-to-market anchor. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed mid-tier manufacturer cash flow generation. Long-term viability favors asset-light designers with regulatory approval pathways already cleared. Watch ambulatory surgical center same-day procedure volume as inflection indicator for stent replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body designation secures 18-24 month certification timelines for Class III urological implants. |
| Hospital System Partnership | Bundled procurement contracts with German and US ambulatory networks capture episode-based reimbursement flows. |
| Software Companion Development | Connected stent monitoring satisfies EU MDR post-market surveillance mandates while generating real-world evidence. |
| Reimbursement Strategy | Outpatient urethrotomy coding alignment with commercial payer episode-based models accelerates minimal invasive adoption. |
| FDA Submission | ISO 10993 biocompatibility validation under FDA Class IIb and III oversight opens US hospital procurement channels. |
Study Parameters
Multiple input streams — primary interviews with urology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR notified body designations, hospital procurement databases, and CMS Medicare reimbursement schedules; plus customs records for urological device trade flows — were reconciled through bottom-up and top-down triangulation.
Historical procedure volume trajectories were cross-referenced against expert panel inputs on EU MDR implementation timelines and payer reimbursement recalibration. Segmentation dimensions modeled include product type, end user facility tier, delivery mode invasiveness, and application intent across the projection horizon. CAGRs were derived from installed base replacement cycles, ambulatory capacity expansion, and drug-eluting stent penetration curves.
Inputs from notified body certification databases and hospital capital expenditure disclosures were available through the study window; gaps in real-world biodegradable stent performance data introduce uncertainty bands around magnesium alloy adoption forecasts. Practitioners should monitor EU MDR designation delays, ambulatory surgical center licensing expansions, and Japanese PMDA trial completion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Hematuria Treatment Market
Urology
Nordic Urinary Catheters Market
Urology
North America Transrectal Ultrasound Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Uropathy Treatment Market
Urology
Benign Prostatic Hyperplasia Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Obstructive Uropathy Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Ureterorenoscopes Market
Urology
Global Bladder Scanner Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Asia-Pacific Bladder Disorders Market