
 Mechanical Chest Compression System Market | 2026-2036
Mechanical Chest Compression System Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Chest Compression System Market Insights
Hospital procurement channels is rewriting how mechanical chest compression systems reach end users, with group purchasing organizations consolidating vendor negotiations across integrated delivery networks. ZOLL Medical Corporation leverages its direct EMS fleet relationships to sustain installed-base loyalty. Stryker Corporation anchors its position through trauma-system partnerships that bundle compression hardware with defibrillation platforms. Michigan Instruments competes on piston-driven mechanism reliability for hospital code-blue deployments.
A mechanical chest compression system delivers automated, rhythmic sternal depression via piston, load-distributing band, or suction-cup mechanism at depths of 50–60 mm and rates of 100–120 compressions per minute to maintain coronary and cerebral perfusion during cardiac arrest. The primary commercial purpose centers on eliminating rescuer fatigue, minimizing hands-off intervals, and standardizing compression quality across prehospital and in-hospital resuscitation scenarios. Automated devices lead unit shipments due to EMS agency preference for hands-free operation during patient transport, while software-driven technology represents the fastest-growing category as manufacturers integrate real-time compression depth feedback and post-event data logging. Portable devices command premium positioning in air-medical and tactical emergency settings where weight and battery autonomy determine procurement outcomes.
The FDA's Class II 510(k) clearance framework governs device safety and efficacy claims in the United States, while the EU Medical Device Regulation imposes stricter clinical evaluation and post-market surveillance obligations for CE-marked systems. Germany's KBA influences ambulance equipment standards across European EMS fleets, indirectly shaping compressor mounting and power-interface specifications. Stakeholders must monitor evolving ILCOR resuscitation guidelines and corresponding national protocol adoptions, as these directly determine whether automated compression receives preferred or conditional recommendation status in clinical practice standards.
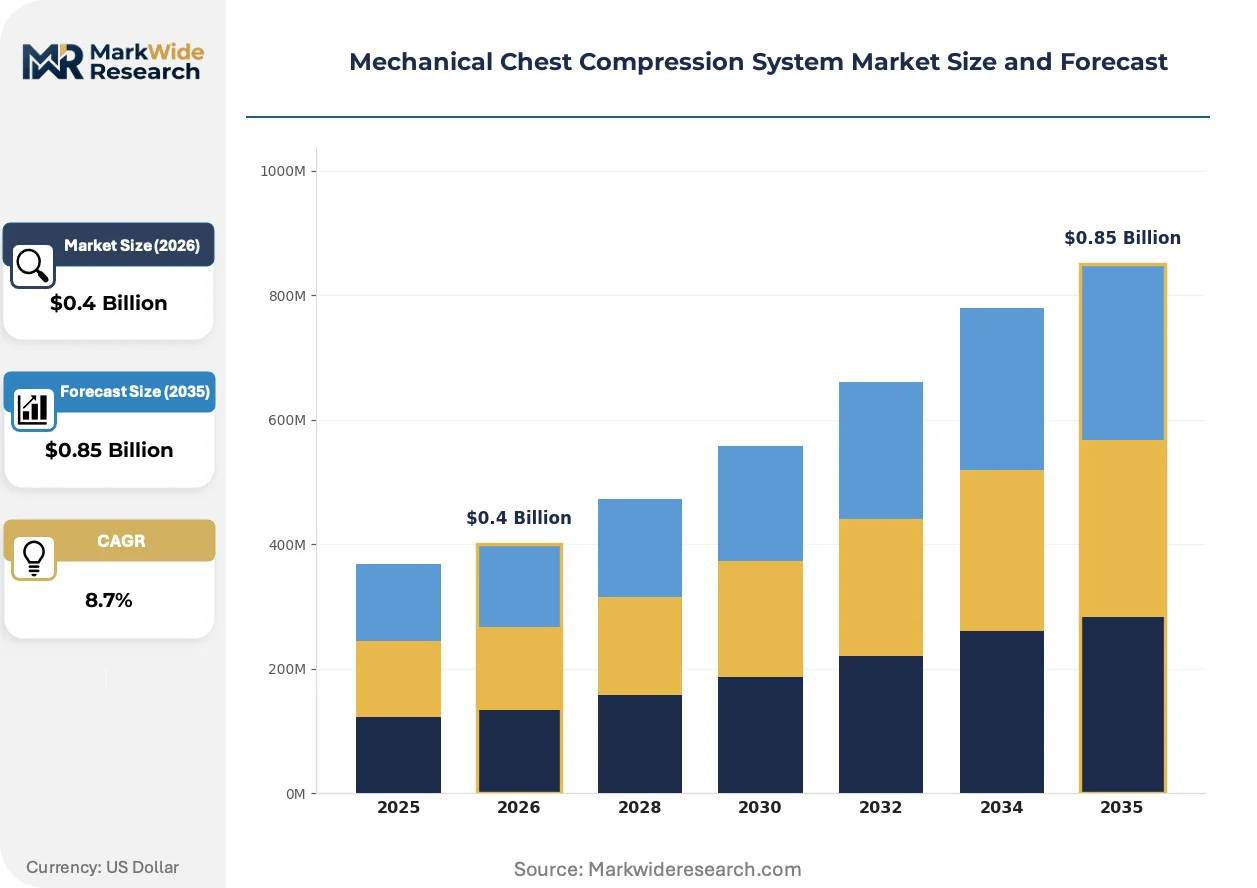
Market Dynamics
EMS agencies are automating manual CPR protocols, forcing equipment vendors to prove clinical equivalence against established resuscitation guidelines while navigating divergent national reimbursement frameworks.
Growth Catalysts
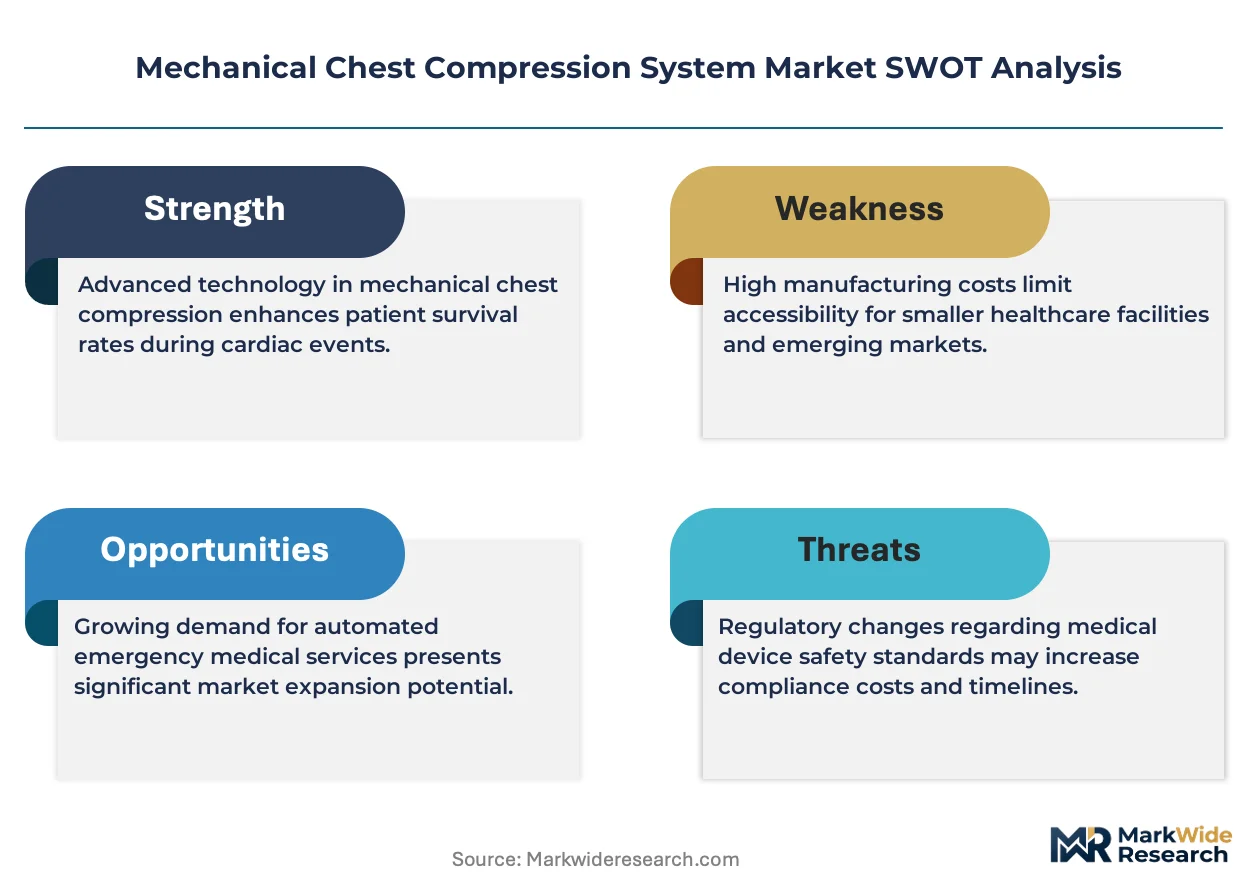
- FDA 510(k) Pathway:The premarket notification framework for Class II devices accelerates product entry timelines, compressing development-to-deployment cycles for piston-driven and load-distributing band systems.
- ILCOR Guideline Adoption:National protocol updates across emergency medical services create procurement mandates for automated compression devices in cardiac arrest response protocols.
- Air-Medical Transport:Helicopter and fixed-wing emergency services drive demand for portable battery-autonomous units where weight constraints and hands-free operation determine survival outcomes.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production clusters in East Asian manufacturing hubs, exposing portable device manufacturers to input cost volatility and logistics bottlenecks.
- EU MDR Compliance Burden:The Medical Device Regulation imposes extended clinical evaluation timelines and mandatory post-market surveillance, delaying CE-marked system launches.
- Manual CPR Training Infrastructure:Established basic life support certification programs and instructor networks create institutional inertia against capital-intensive automation transitions.
Strategic Opportunities
- Rural EMS Networks:Underpenetrated volunteer and municipal ambulance services in the Mountain West and Great Plains regions present first-mover expansion potential for automated deployment.
- Real-Time Feedback Convergence:Integration of compression depth sensors with cloud-based data logging is virtualizing quality assurance workflows, creating subscription revenue streams beyond hardware sales.
- Hospital Code-Blue Modernization:Inpatient rapid response teams seek piston-driven systems with defibrillator interoperability, opening bundled procurement channels through integrated delivery networks.
Industry Challenges
- Biomedical Technician Shortization:Specialized repair capabilities for pneumatic piston mechanisms and load-cell calibration remain scarce outside major metropolitan trauma centers.
- Legacy Defibrillator Integration:Proprietary communication protocols between compression devices and existing monitor-defibrillator fleets force costly adapter development or full-platform replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Chest Compression System Market |
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $0.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Devices, Manual Devices, Hybrid Devices, Portable Devices End User: Hospitals, Emergency Medical Services, Clinics, Home Care Technology: Pneumatic, Electric, Mechanical, Software-Driven Application: Cardiac Arrest, Trauma, Respiratory Distress, Surgical Procedures |
| Companies Covered | ZOLL Medical Corporation, Stryker Corporation, Michigan Instruments, Defibtech, Corpuls, CPR Medical Devices, Inc., SCHILLER, Resuscitation International, Brunswick Biomedical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Chest Compression System Market Trends and Innovations
Software-defined functionality is displacing mechanical-only architectures across the resuscitation equipment landscape, compressing product lifecycles and redefining vendor-customer relationships through data-enabled service models.
Real-time compression feedback technology is virtualizing quality control in resuscitation workflows. Load-distributing band systems now incorporate accelerometer-based depth measurement and immediate auditory correction prompts. Hospital code-blue teams and EMS supervisors adopt these platforms to standardize performance across rotating shift staff. The technology is virtualizing traditional instructor-led skills validation, reducing training overhead while capturing performance metrics for liability documentation.
The EU Medical Device Regulation tightens clinical evidence requirements for Class IIa and IIb resuscitation equipment. Manufacturers must submit systematic literature reviews and post-market clinical follow-up plans to notified bodies. German KBA ambulance equipment standards now reference MDR conformity as a prerequisite for fleet approval. European EMS procurement offices delay purchase decisions pending updated technical documentation, compressing competitive windows for non-compliant vendors.
Group purchasing organizations consolidate mechanical chest compression negotiations across multi-hospital systems. Integrated delivery networks in the Northeast and Midwest bundle compression hardware with defibrillator platforms and maintenance agreements. Traditional distributor relationships fragment as IDN supply chain offices demand direct manufacturer contracting and volume-tiered pricing structures. This concentration is most visible in Catholic health system networks, where standardization mandates span dozens of acute care facilities.
Mechanical Chest Compression System Market Segmentation
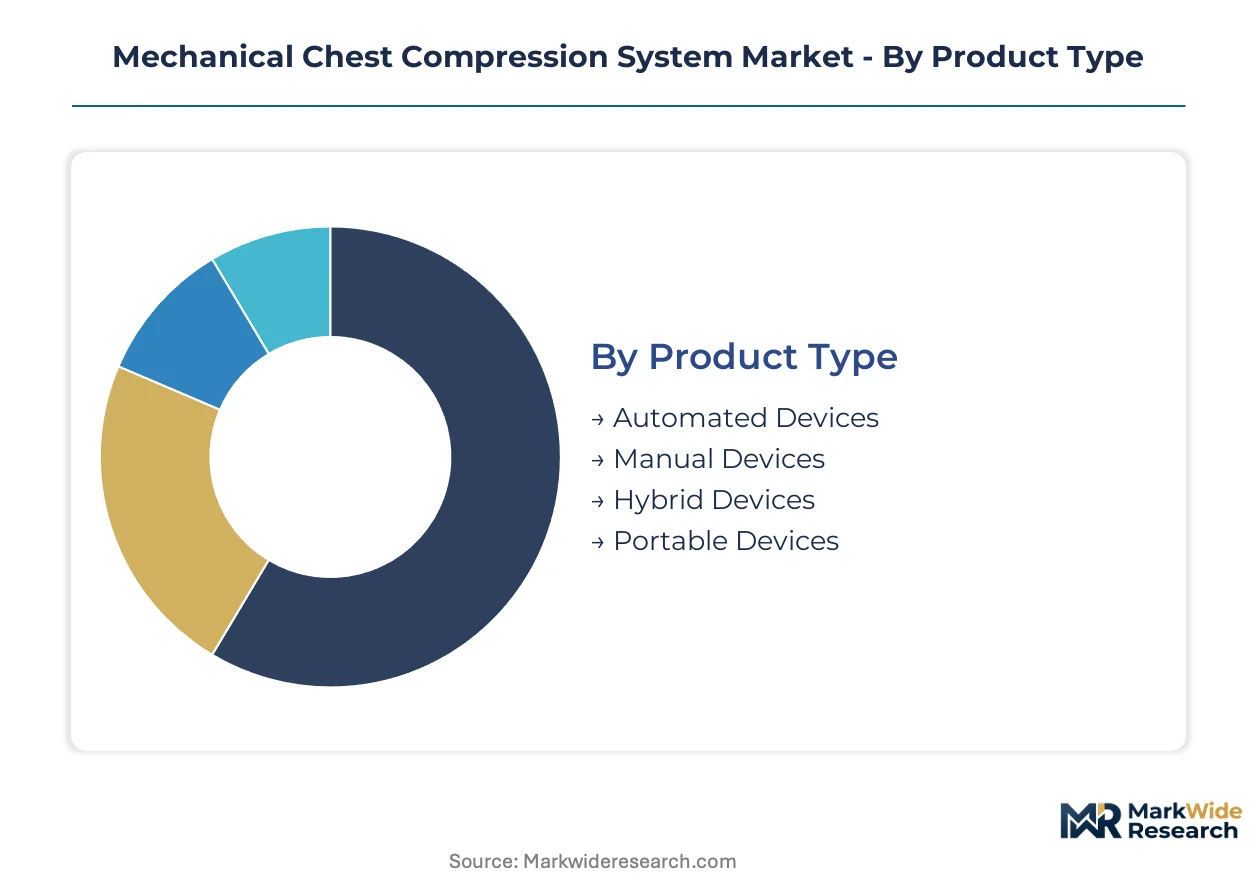
Mechanical chest compression systems fragment across four distinct dimensions that shape procurement patterns, service requirements, and technology roadmaps. Each segmentation axis reveals divergent margin profiles and customer loyalty mechanics that vendors must navigate.
Product Type:
After-sales-service intensity varies sharply across product categories, with automated platforms demanding specialized biomedical technician networks while portable units require battery logistics and field-replaceable component programs.
- Automated Devices:Piston-driven and load-distributing band mechanisms deliver hands-free compression at standardized depths and rates. EMS fleets in the United States concentrate procurement here, driven by protocol mandates for minimizing hands-off intervals during transport. By volume, automated devices lead. By growth pace, portable variants are ahead.
- Manual Devices:Suction-cup and piston-assisted systems retain operator control while reducing fatigue. Budget-constrained municipal ambulance services in rural Texas and Montana deploy these as bridge solutions toward full automation.
- Hybrid Devices:Operator-assisted mechanisms with selectable automation modes. German KBA-certified ambulance builders specify these for interfacility transfer vehicles requiring flexible deployment.
- Portable Devices:Battery-autonomous units under 10 kilograms for air-medical and tactical settings. Helicopter EMS operators in Colorado and Utah prioritize weight reduction and battery autonomy over compression feedback sophistication.
Service contract attachment rates run highest for automated installations and lowest for portable sales.
End User:
Customer concentration patterns split between capital-rich hospital systems with integrated delivery network purchasing power and fragmented EMS agencies with grant-dependent acquisition cycles.
- Hospitals:Inpatient rapid response teams and catheterization laboratories deploy piston-driven systems with defibrillator interoperability. Northeastern Catholic health system networks consolidate compression-defibrillator bundles across dozens of facilities.
- Emergency Medical Services:Prehospital agencies automate manual CPR protocols under ILCOR-aligned state mandates. Volunteer and municipal services in the Mountain West present first-mover expansion potential.
- Clinics:Outpatient surgery centers and urgent care facilities stock manual or hybrid devices for peri-arrest scenarios. Procurement concentrates in multi-site regional chains with standardized equipment formularies.
- Home Care:Hospice and palliative services deploy lightweight portable units for anticipated cardiac arrest in terminal patients. Reimbursement frameworks in Medicare Advantage plans increasingly cover rental arrangements.
Hospital procurement concentrates spending volume; EMS networks are expanding most quickly.
Technology:
Technology selection determines regulatory pathway complexity, with software-driven architectures facing heightened FDA cybersecurity guidance and EU MDR post-market surveillance obligations.
- Pneumatic:Compressed-gas piston mechanisms dominate hospital code-blue deployments for reliability and rapid cycle initiation. Michigan Instruments anchors market position through mechanism durability claims.
- Electric:Motor-driven systems with rechargeable battery packs. Stryker Corporation bundles electric compression with monitor-defibrillator platforms through trauma-system partnerships.
- Mechanical:Spring-loaded or purely kinetic devices without external power. Tactical emergency medicine programs in federal agencies specify these for electromagnetic interference resilience.
- Software-Driven:Sensor-integrated platforms with real-time depth feedback and cloud logging. This architecture commands premium positioning and is climbing the fastest as manufacturers virtualize quality assurance workflows.
Pneumatic systems retain installed-base dominance; software-driven architectures capture disproportionate R&D investment.
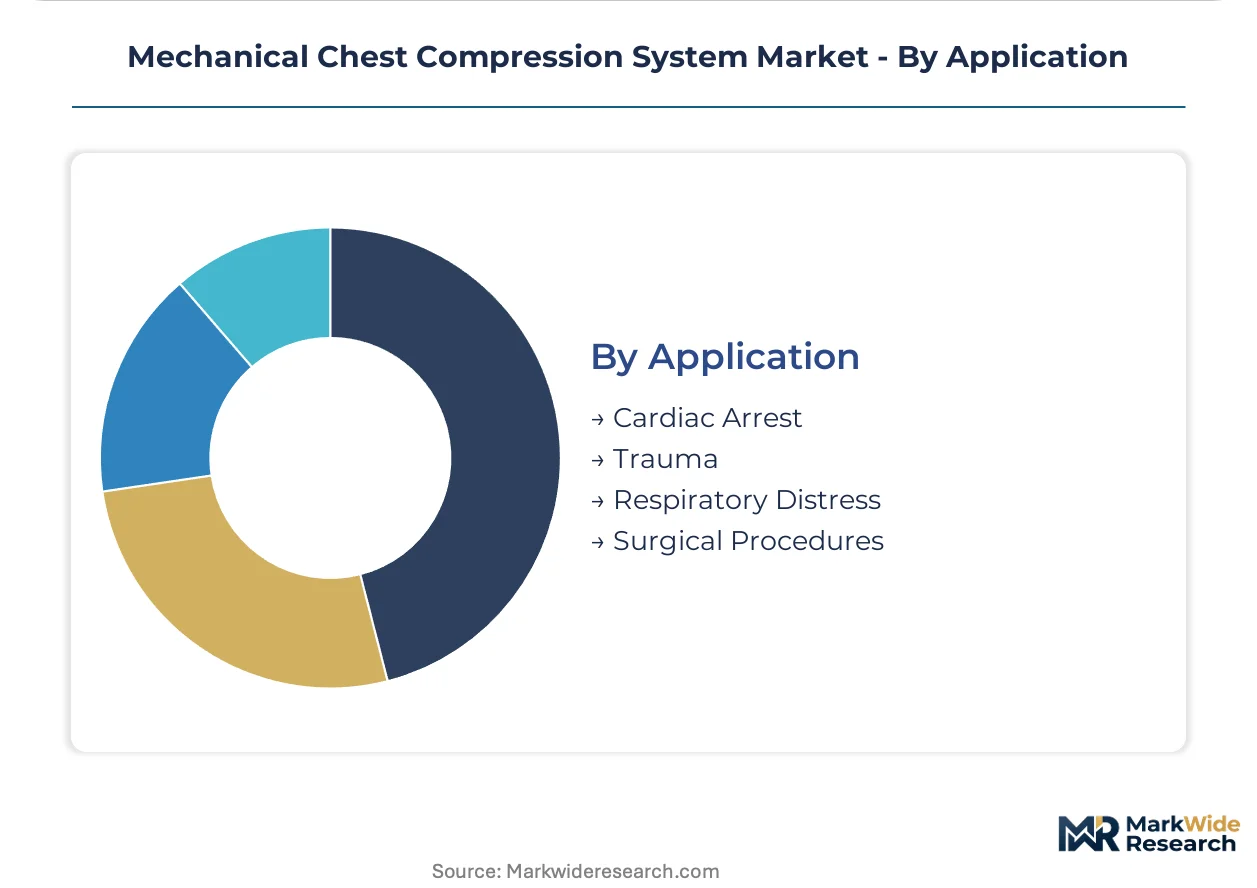
Application:
Clinical indication shapes device specification requirements, with cardiac arrest scenarios demanding full automation while trauma applications prioritize rapid deployment under field conditions.
- Cardiac Arrest:Primary indication driving protocol-mandated automation. Compression depth adherence to 50-60 millimeters at 100-120 cycles per minute determines survival outcomes in witnessed out-of-hospital events.
- Trauma:Hypovolemic and traumatic arrest scenarios require devices compatible with simultaneous hemorrhage control maneuvers. Military medical services specify rapid-application load-distributing bands.
- Respiratory Distress:Peri-arrest respiratory failure with impending circulatory collapse. Pediatric intensive care units in academic medical centers pilot pediatric-specific compression adaptations.
- Surgical Procedures:Intraoperative cardiac arrest during high-risk cardiac and vascular interventions. Hybrid operating rooms integrate compression systems with extracorporeal membrane oxygenation cannulation capabilities.
Cardiac arrest generates absolute procedure volume; trauma applications are gaining share fastest through defense and tactical medicine procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate highway network and its 45,000 miles of controlled-access corridors enable rapid EMS fleet deployment of automated compression systems from regional distribution hubs to cardiac arrest scenes within the golden-hour window.
United States
Hospital systems in the Northeast and Catholic health networks across the Midwest consolidate compression-defibrillator bundles through integrated delivery network purchasing offices. The FDA's 510(k) premarket notification pathway accelerates Class II device clearances for piston-driven and load-distributing band systems. Texas and Montana municipal ambulance services in the Mountain West and Great Plains deploy manual bridge devices pending full automation budget cycles.
Germany
The KBA ambulance equipment standards shape compressor mounting specifications and power-interface requirements across European EMS fleet procurement. EU MDR conformity has become prerequisite for CE-marked system approvals, extending clinical evaluation timelines. Bavarian ambulance builders and North Rhine-Westphalia trauma systems specify hybrid devices for interfacility transfer vehicles requiring flexible automation modes.
Japan
Metropolitan fire departments in Tokyo and Osaka prefectures automate CPR protocols under ILCOR-aligned national resuscitation guidelines. METI medical device regulations govern software-driven compression platforms with real-time feedback capabilities. Kansai region academic medical centers pilot pediatric-specific compression adaptations for peri-arrest respiratory failure scenarios.
United Kingdom
NHS ambulance trusts in England and Scotland standardize automated compression deployment under national cardiac arrest protocol updates. MHRA post-market surveillance requirements align with EU MDR transition timelines for legacy device registrations. London and Southeast trauma networks bundle compression hardware with defibrillator platforms through NHS Supply Chain procurement frameworks.
Australia
Rural and remote ambulance services across Queensland and Western Australia prioritize portable battery-autonomous units for helicopter EMS operations where weight constraints determine survival outcomes. TGA medical device regulations govern software-integrated platforms with cloud-based data logging. New South Wales aeromedical bases in Sydney and Newcastle specify sub-10 kilogram devices for rapid deployment in fixed-wing emergency transport.
Mechanical Chest Compression System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying piston mechanisms, load-distributing bands, and sensor arrays. The vendor base concentrates around three to five established manufacturers with installed-base relationships across EMS fleets and hospital networks. Two strategic archetypes dominate: trauma-system bundlers that pair compression hardware with defibrillator platforms, and mechanism reliability specialists that anchor hospital code-blue deployments. Competitive moves center on GPO contract consolidation and software-enabled service model transitions.
Within the platform integrator tier, ZOLL Medical Corporation and Stryker Corporation exemplify divergent channel strategies. ZOLL sustains direct EMS fleet relationships that reinforce installed-base loyalty across municipal and volunteer ambulance services. Stryker anchors trauma-system partnerships that bundle electric compression with monitor-defibrillator platforms. Michigan Instruments occupies a distinct position as a mechanism reliability specialist, with piston-driven architectures deployed in hospital rapid response scenarios where durability claims drive procurement decisions.
| Leading Market Players |
|---|
| ZOLL Medical Corporation |
| Stryker Corporation |
| Michigan Instruments |
| Defibtech |
| Corpuls |
| CPR Medical Devices, Inc. |
| SCHILLER |
| Resuscitation International |
| Brunswick Biomedical Technologies |
| Others |
Pricing and Supply Chain Analysis
East Asian battery cell manufacturing clusters in Shenzhen and Nagoya determine input cost trajectories for portable compression device producers, with lithium-ion supply concentration translating directly into OEM pricing leverage over EMS procurement offices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs mechanical chest compression system transactions. Premium software-driven platforms with real-time feedback command elevated positioning against piston-driven hospital installations and manual bridge devices for rural EMS. Pricing pressure stems from group purchasing organization consolidation across Catholic health system networks, compressing margins on bundled compression-defibrillator contracts. Municipal ambulance services in grant-dependent acquisition cycles exhibit highest price sensitivity; air-medical operators prioritizing weight-constrained battery autonomy demonstrate lowest.
Supply Chain Analysis
Export-control restrictions on advanced sensor arrays and lithium-ion battery management systems limit component flows from Chinese manufacturing hubs to North American and European assembly facilities. Component sourcing draws from South Korea for precision electric motors, Japan for accelerometer-based depth sensors, and China for battery cell production. Single-source vulnerability concentrates in semiconductor-dependent feedback controllers. Distribution runs through integrated delivery network supply chain offices demanding direct manufacturer contracting, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across rural EMS networks and home care hospice services creates multiple entry points, as reimbursement framework evolution in Medicare Advantage plans splinters demand into niche deployment models.
For Market Incumbents: Entrench installed-base loyalty through backward integration into battery logistics networks and captive biomedical technician training programs. Software-driven platform transitions threaten piston-driven mechanism specialists; CE marking investment under EU MDR tightens competitive moats against non-compliant vendors. For New Entrants and Emerging Players: Volunteer and municipal ambulance services across the Mountain West and Great Plains represent the most penetrable entry point, with manual-to-automation upgrade cycles creating equipment refresh windows. Pediatric-specific compression adaptations for academic medical centers offer specialized application entry; cloud-based quality assurance subscription models bypass capital-intensive hardware procurement barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mechanism reliability specialists with hospital code-blue installed bases over software-first entrants facing FDA cybersecurity guidance delays. Long-term viability hinges on defibrillator platform interoperability and GPO contract consolidation. Watch ILCOR guideline adoption velocity across state EMS protocols as inflection indicator for automation mandate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates Class II device clearance timelines for piston-driven and load-distributing band systems entering US markets. |
| CE Marking Pathway | EU MDR conformity opens German KBA-certified ambulance builder procurement channels across European EMS fleets. |
| Hospital System Partnership | Northeastern Catholic health network bundles consolidate compression-defibrillator contracts across dozens of acute care facilities. |
| Software Companion Development | Real-time depth feedback and cloud logging virtualize quality assurance workflows, creating recurring subscription revenue streams. |
| Reimbursement Strategy | Medicare Advantage plan coverage expansion for home care hospice rentals unlocks terminal patient segment demand. |
Research Methodology
Operator-level perspectives from EMS fleet managers, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and ILCOR guideline adoption tracking. Bottom-up unit shipment estimates triangulated against top-down market sizing across technology and end-user dimensions.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning product type, end-user category, technology architecture, and clinical application. CAGRs derived from elasticity-adjusted adoption curves incorporating reimbursement framework evolution and protocol mandate diffusion patterns. Forecast inputs included state-level EMS automation policy trajectories and integrated delivery network consolidation velocity.
Macroeconomic conditions sit as an overlay; deviation in lithium-ion commodity pricing and healthcare capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory pathway timelines and reimbursement expansion scope. Material shifts in EU MDR enforcement stringency or FDA cybersecurity guidance finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cryoablation System Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Creatinine Meter Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Medical Device Trays Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Radial Compression Devices Market