
 Nephrostomy Devices Market | 2026-2036
Nephrostomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrostomy Devices Market Intelligence
The adoption of small-bore, high-flexibility catheters is unwinding traditional procedural preferences for larger, more invasive devices, improving patient comfort and reducing trauma. Boston Scientific Corporation leverages its extensive urology portfolio to lead innovation in catheter material science. Cook Medical sustains its market position through a deep specialization in minimally invasive technologies and guidewires. Becton Dickinson and Company competes effectively on the strength of its broad hospital supply chain presence and established distribution channels.
A nephrostomy device is a medical instrument that creates a percutaneous channel to drain urine directly from the renal pelvis. These systems feature catheters made from materials like polyurethane, incorporating pigtail locking mechanisms for secure kidney placement. Hospitals constitute the primary end-user segment, handling most procedures for applications such as urinary obstruction and nephrolithiasis. Among product types, internal catheters hold a major share due to their necessity in managing chronic drainage requirements.
Device clearance is governed by stringent frameworks, including the FDA's 510(k) pathway in the United States and PMDA review in Japan. In Europe, compliance with the Medical Device Regulation (MDR) is mandatory for obtaining CE marking, which dictates design and post-market surveillance protocols. Manufacturers must navigate the complex balance between incorporating advanced anti-infective coatings and maintaining cost-effectiveness for hospital procurement systems.
Market Dynamics
The central dynamic shaping the nephrostomy devices market is the tension between advanced material science, which enables less invasive and safer procedures, and the intense cost-containment pressure exerted by hospital and ambulatory center procurement systems globally.
Growth Catalysts
- Biocompatible Materials:The development of advanced polymer coatings with hydrophilic and antimicrobial properties is reducing device-related friction and post-procedural infection rates, directly improving patient outcomes and encouraging wider use in hospital settings.
- Urological Disease Prevalence:A rising incidence of nephrolithiasis (kidney stones) and urinary obstructions, particularly within aging populations in North America and Europe, is expanding the base procedural volume requiring nephrostomy drainage.
- Healthcare Infrastructure Investment:Governments in several Asia-Pacific countries are increasing healthcare expenditure, improving access to advanced urological procedures and creating new demand for specialized medical devices like nephrostomy catheters.
Market Restraints
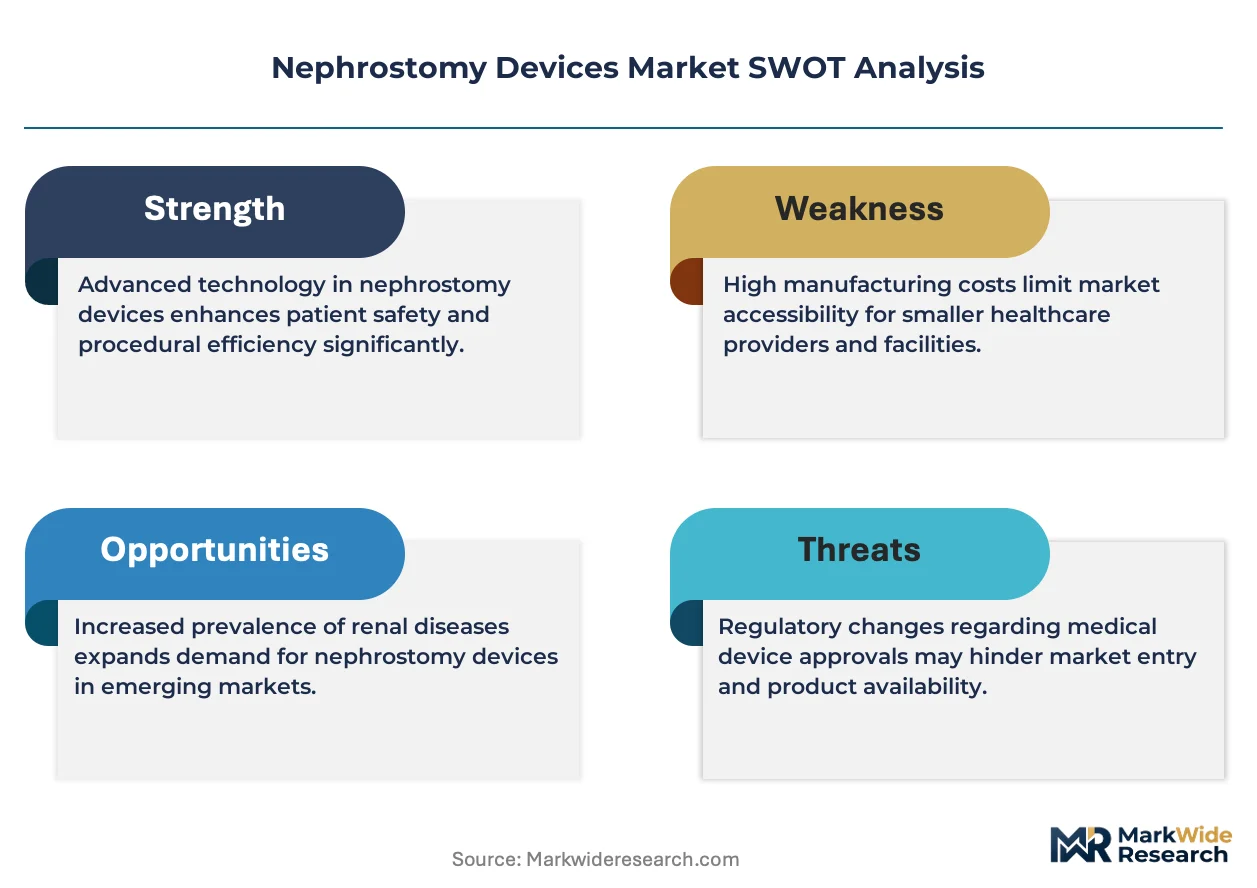
- Reimbursement Policies:Inconsistent or inadequate reimbursement for advanced, coated nephrostomy devices can slow their adoption in public health systems and smaller hospitals, favoring lower-cost, standard alternatives despite potential clinical benefits.
- Alternative Treatment Options:The availability and refinement of non-invasive or less-invasive treatments for kidney stones, such as extracorporeal shock wave lithotriopsy (ESWL), can reduce the number of cases that require percutaneous nephrostomy.
- Regulatory Scrutiny:Rigorous regulatory pathways, including the FDA's 510(k) and Europe's MDR, create high barriers to entry and can significantly delay the market introduction of innovative devices, adding to development costs.
Strategic Opportunities
- Emerging Market Penetration:There is significant opportunity for expansion in Latin American and Southeast Asian markets, where improving healthcare infrastructure and a growing middle class are increasing the demand for specialized urological interventions.
- Pediatric Applications:Designing and marketing smaller, more flexible nephrostomy devices specifically for pediatric patients represents an underserved niche, addressing unique anatomical challenges and clinical needs in this population.
- Smart Device Integration:Incorporating sensor technology into catheters to monitor for blockages, urine flow, or early signs of infection offers a pathway to create next-generation devices with enhanced diagnostic capabilities and improved patient safety.
Industry Challenges
- Specialized Skill Requirements:The effective placement of nephrostomy catheters requires highly trained interventional radiologists, and a shortage of these specialists in certain regions can act as a bottleneck, limiting procedural capacity and market growth. -
- Post-Market Surveillance Demands:Compliance with regulations like the EU MDR requires manufacturers to establish extensive post-market surveillance systems to continuously collect clinical data, adding significant operational complexity and ongoing costs.
- Supply Chain Vulnerabilities:The reliance on a limited number of suppliers for critical raw materials, such as specialized medical-grade polyurethane and guidewire alloys, exposes manufacturers to potential price volatility and supply disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrostomy Devices Market |
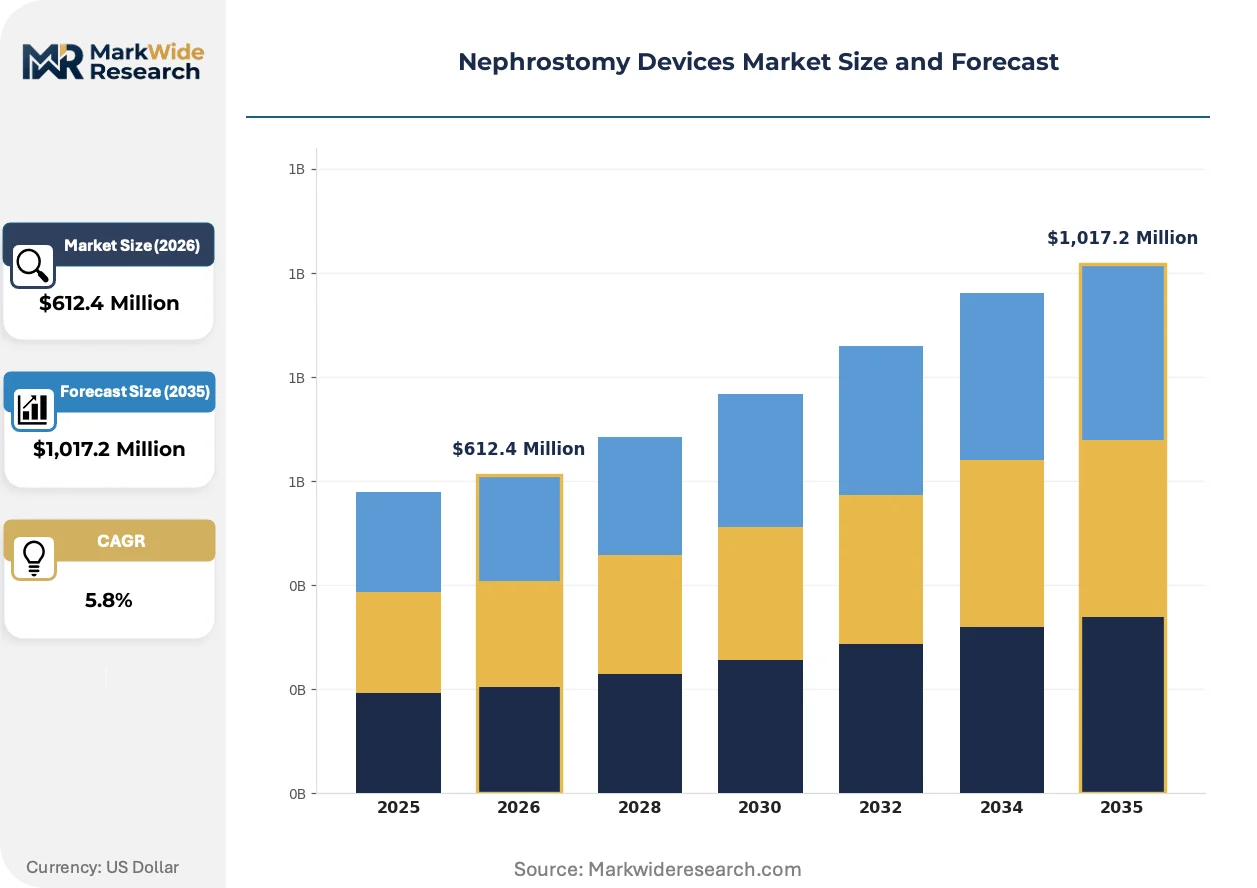
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Catheters, External Catheters, Drainage Bags, Accessories End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Settings Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Wholesalers Application: Urinary Obstruction, Nephrolithiasis, Hydronephrosis, Others |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Becton Dickinson and Company, Teleflex Incorporated, B. Braun SE, Cardinal Health, Coloplast, Medtronic, Argon Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrostomy Devices Market Strategic Shifts & Innovations
Material science innovation is fundamentally altering device design, enabling a transition toward smaller, more flexible catheters that enhance patient comfort. This evolution aligns with a broader healthcare system push for minimally invasive procedures and improved clinical outcomes in urological care.
Advanced hydrophilic and antimicrobial coatings on polyurethane catheters are a primary focus of product development, designed to reduce insertion trauma and lower the risk of catheter-associated urinary tract infections. Hospitals and specialized urology clinics are prioritizing these devices for long-term drainage and high-risk patient populations. This adoption is bifurcating the market into premium, feature-rich devices for complex cases and standard catheters for more routine, short-term applications.
Europe's Medical Device Regulation (MDR) is mandating a higher standard of clinical evidence for medical devices, including those for nephrostomy. The regulation forces manufacturers to conduct more rigorous clinical investigations and maintain robust post-market surveillance systems. Internal catheters and guidewires, particularly those with long-term implant durations, are most affected, prompting companies to re-evaluate their portfolios for compliance.
A distinct behavioral change is the migration of certain nephrostomy procedures from traditional inpatient hospital settings to outpatient ambulatory surgical centers. This movement is driven by payer incentives and hospital efforts to manage costs and bed capacity for more acute cases. The trend is especially visible in the United States, spurring demand for all-in-one procedural kits that are optimized for efficiency in an outpatient environment.
Nephrostomy Devices Market Segmentation
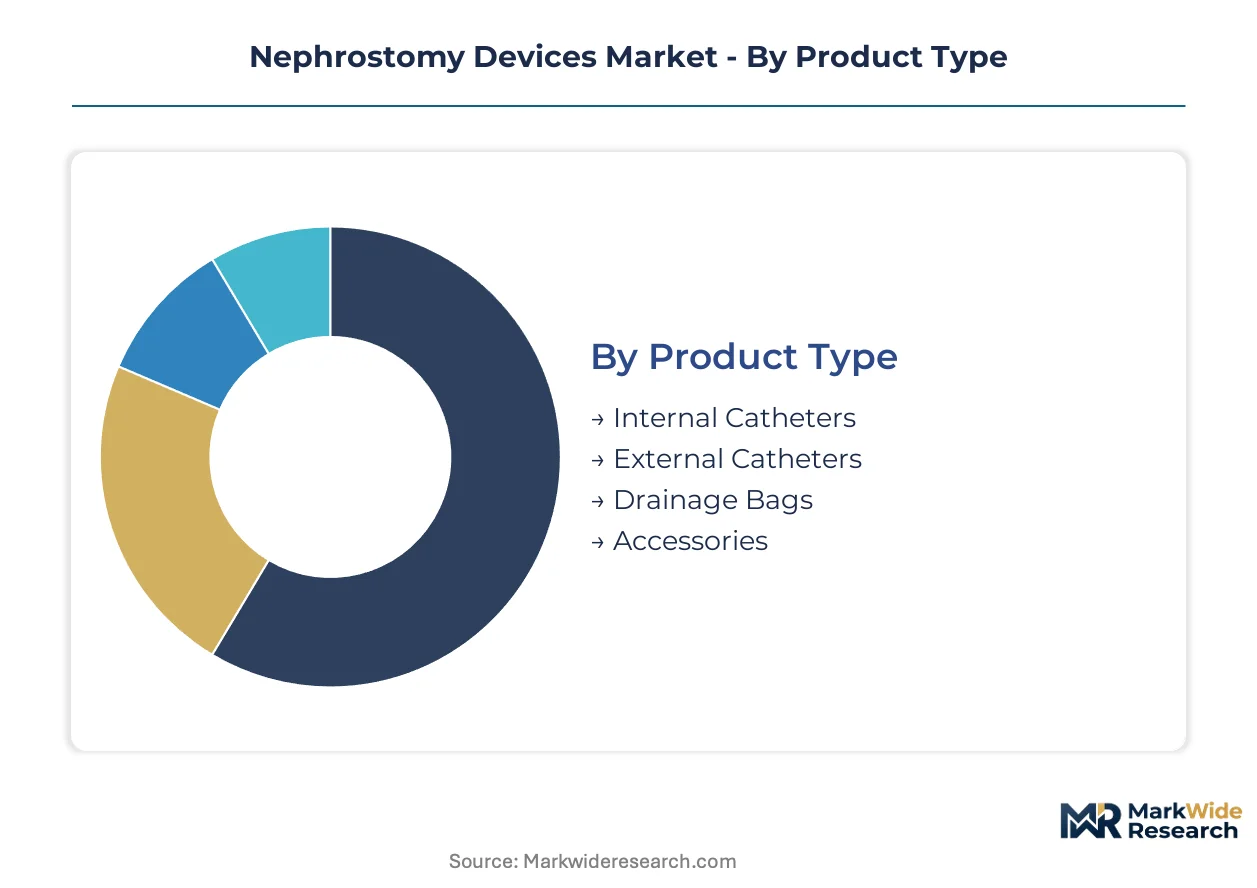
The nephrostomy devices market segments across product types, end-users, distribution channels, and applications. Understanding these divisions highlights areas of concentrated demand and specialized clinical requirements. This segmentation analysis provides a granular view of device utilization patterns and procurement dynamics within the healthcare system.
Product Type:
Margin pools within this category are heavily influenced by device complexity and material science innovations.
- Internal Catheters:These devices are designed for long-term urine drainage from the renal pelvis to the bladder, often featuring advanced biocompatible polymer coatings. Demand concentrates in hospital settings for chronic conditions, driven by improved patient comfort and reduced infection risk.
- External Catheters:Used for temporary or external urine drainage directly from the kidney, these catheters typically incorporate pigtail locking mechanisms for secure placement. Adoption is significant in acute care hospitals for immediate relief of urinary obstruction or post-surgical drainage.
- Drainage Bags:These sterile collection bags attach to nephrostomy catheters, managing drained urine volume and preventing reflux. They are essential accessories for both internal and external catheter systems across all care settings.
- Accessories:This segment includes guidewires, dilators, introducer needles, and fixation devices, crucial for safe and effective catheter insertion and maintenance.
Internal Catheters holds installed capacity. External Catheters is rotating up the share rankings.
End User:
Volume concentration dictates procurement patterns and device preferences across different healthcare facilities.
- Hospitals:These institutions serve as the primary end-users, managing complex urological conditions and performing the highest volume of nephrostomy procedures. Hospitals prioritize advanced devices with anti-infective properties for critical patient populations.
- Ambulatory Surgical Centers:A growing number of less complex nephrostomy procedures are migrating to these outpatient facilities, driven by cost-efficiency and patient convenience. These centers seek all-in-one procedural kits to optimize workflow.
- Clinics:Specialized urology clinics often manage post-procedural care and routine catheter changes, requiring a steady supply of standard nephrostomy devices and accessories.
- Home Care Settings:Patients with long-term drainage needs utilize nephrostomy devices in home care, requiring user-friendly designs and clear instructions for caregivers.
Growth in Ambulatory Surgical Centers is expanding most quickly, while Hospitals maintains its foundational role.
Distribution Channel:
Customer type dictates the go-to-market strategy for nephrostomy devices.
- Medical Distributors:This channel facilitates broad market access, leveraging established networks to supply a wide range of hospitals and clinics. Distributors manage logistics and inventory for diverse product portfolios.
- Direct Sales:Manufacturers utilize direct sales teams for high-value or highly specialized products, offering personalized support and clinical education to key accounts. This channel is crucial for new product introductions.
- Online Sales:E-commerce platforms provide a convenient channel for procurement of standard accessories and certain devices, particularly for smaller clinics or home care providers.
- Wholesalers:These entities purchase medical devices in bulk from manufacturers and distribute them to smaller distributors or directly to large healthcare systems.
The majority of transactions are facilitated by Medical Distributors, with Online Sales showing significant digital expansion.
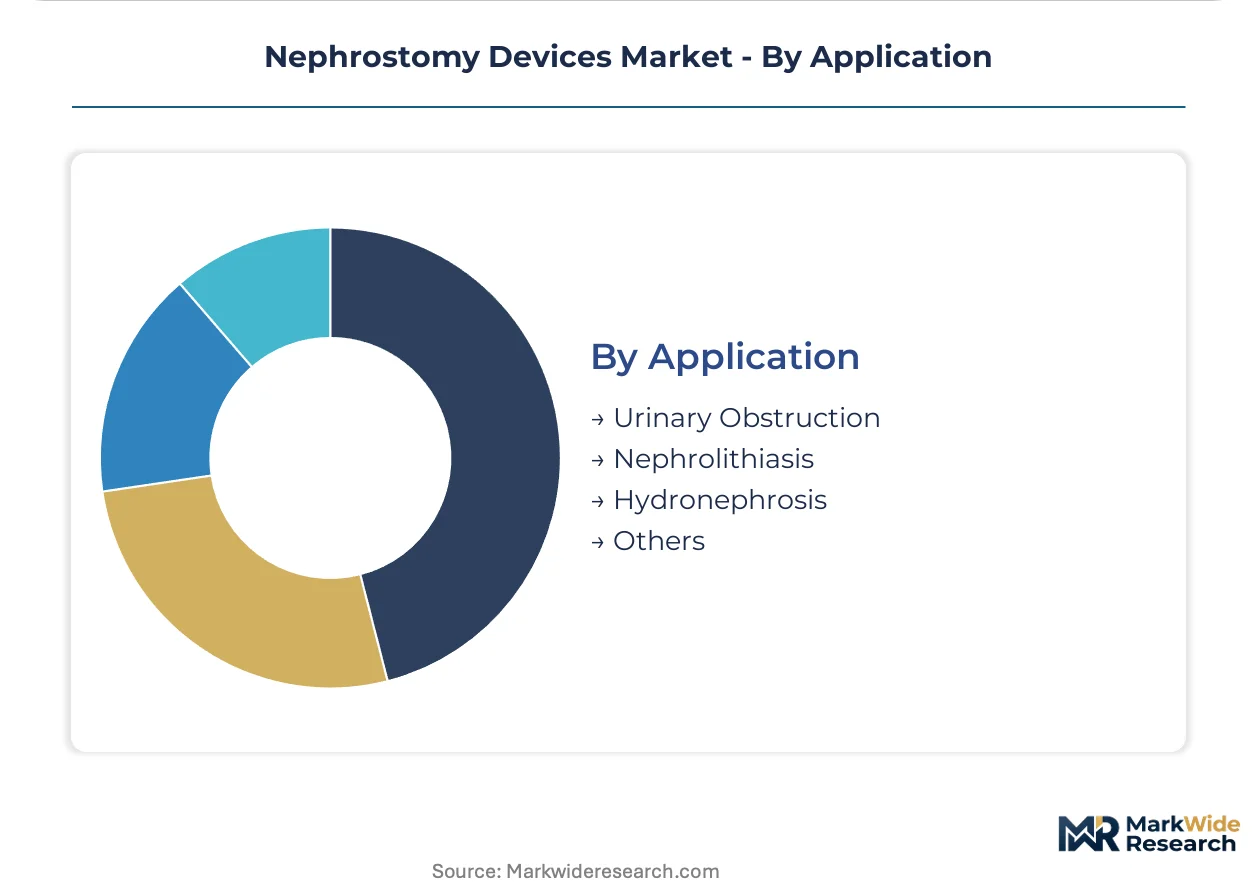
Application:
Maturity levels of treatment protocols influence device demand across various urological conditions.
- Urinary Obstruction:This application involves using nephrostomy devices to relieve blockages in the urinary tract caused by tumors, strictures, or congenital anomalies. These procedures are common across all age groups.
- Nephrolithiasis:Kidney stone management frequently requires nephrostomy for drainage, especially before or after surgical interventions like percutaneous nephrolithotomy. The rising incidence of kidney stones fuels demand in this segment.
- Hydronephrosis:This condition, characterized by kidney swelling due to urine backup, often necessitates nephrostomy drainage to prevent renal damage.
- Others:This category encompasses less common applications such as urinary diversion for bladder cancer, post-transplant complications, or diagnostic purposes.
Nephrolithiasis represents the fastest-growing procedural volume. Urinary Obstruction remains a consistently high-volume application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across global markets for nephrostomy devices, with some regions prioritizing advanced features despite higher costs, while others focus on cost-effective standard solutions. Procurement systems in developed economies often accommodate premium devices, whereas emerging markets frequently seek more budget-friendly options for broader patient access.
United States
High procedural volumes for nephrolithiasis and urinary obstruction drive significant demand for nephrostomy devices in the United States. The FDA's 510(k) pathway governs device clearance, ensuring a high standard of safety and efficacy for new products. Major medical device clusters in states like Massachusetts and California foster innovation in biocompatible materials and catheter design.
Germany
An aging population and a high incidence of urological diseases contribute to consistent demand for nephrostomy devices across Germany. Compliance with the Medical Device Regulation (MDR) is mandatory for market entry, influencing product development and post-market surveillance. The Munich and Stuttgart regions serve as hubs for medical technology manufacturing and research.
Japan
Japan's advanced healthcare infrastructure supports the adoption of sophisticated nephrostomy solutions, particularly those with anti-infective coatings. The Pharmaceuticals and Medical Devices Agency (PMDA) rigorously reviews devices, emphasizing patient safety and clinical evidence. Tokyo and Osaka remain key centers for medical device companies and specialized urology clinics.
United Kingdom
The National Health Service (NHS) in the United Kingdom manages a substantial volume of nephrostomy procedures, driven by the prevalence of kidney stones and urinary tract blockages. Devices must adhere to CE marking requirements, which align with European MDR standards for quality and performance. Medical technology parks around Cambridge and Oxford facilitate collaborative device development.
Brazil
Improving healthcare infrastructure and a growing middle class are expanding the market for specialized urological interventions in Brazil. ANVISA, the national health surveillance agency, regulates the approval and commercialization of medical devices within the country. São Paulo and Rio de Janeiro concentrate a significant portion of Brazil's advanced medical facilities and device distribution networks.
Nephrostomy Devices Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the nephrostomy devices market. The market structure exhibits a tiered consolidation, with large diversified medical device corporations dominating the premium segment and specialized manufacturers competing on innovation. Strategic partnerships and portfolio diversification represent dominant competitive moves among market participants.
Specialists in minimally invasive technologies and urology solutions, such as Cook Medical, consistently refine their product lines, focusing on guidewires and catheter designs. Boston Scientific Corporation leverages its extensive urology portfolio to lead innovation in catheter material science, targeting advanced biocompatible polymer coatings. Becton Dickinson and Company competes effectively through its broad hospital supply chain presence, ensuring wide distribution and accessibility for its range of devices.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Becton Dickinson and Company |
| Teleflex Incorporated |
| B. Braun SE |
| Cardinal Health |
| Coloplast |
| Medtronic |
| Argon Medical Devices |
Cost & Logistics Intelligence
Manufacturing scale economies in nephrostomy device production shape both supply concentration and market price floors. This dynamic emphasizes the critical role of material science innovation in balancing cost-effectiveness with advanced features.
Pricing Analysis
Europe’s Medical Device Regulation (MDR) dictates the pricing tier structure for nephrostomy devices, emphasizing advanced features like anti-infective coatings. The dominant pricing model is per-unit transactional, often negotiated through long-term hospital contracts. Price differentiation stems from device complexity, biocompatible polymer coatings, and the extent of clinical evidence. Pricing softness stems from intense cost-containment pressure from hospital procurement systems, with Ambulatory Surgical Centers exhibiting the highest price sensitivity compared to major hospitals.
Supply Chain Analysis
Reliance on specialized medical-grade polyurethane and guidewire alloys underwrites the nephrostomy device supply chain. Geographic supply concentration centers in the United States, Germany, and Japan, where advanced manufacturing capabilities reside. Raw material dependencies include medical-grade polymers and specific metal alloys for guidewires, creating single-source vulnerability. Distribution runs through a combination of medical distributors and direct sales teams to healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nephrostomy devices market experiences a buyer-power shift, driven by the increasing consolidation of hospital procurement systems. This consolidation enables greater leverage in negotiating device pricing and features.
For Market Incumbents: Secure leadership in advanced material science by continuously investing in biocompatible polymer coatings. This mitigates the threat of post-procedural infection rates and strengthens clinical outcomes. Strengthen distribution channels in emerging markets to counteract inconsistent reimbursement policies in developed economies. Generate robust clinical evidence for new devices to maintain compliance with stringent regulations like Europe's MDR.
For New Entrants and Emerging Players: Differentiate on specialized applications, such as pediatric nephrostomy devices, addressing unique anatomical challenges. Target underserved emerging markets like Latin America and Southeast Asia with cost-effective, all-in-one procedural kits. Focus on integrating sensor technology into catheters to monitor flow and detect early signs of infection. This go-to-market angle offers enhanced diagnostic capabilities and improved patient safety.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers specializing in long-term internal catheters with advanced coatings. The market offers long-term viability, driven by aging populations and persistent urological disease prevalence over the next decade. Target specialized manufacturers with strong intellectual property in minimally invasive technologies or smart device integration. The signal to watch for inflection is the accelerated adoption of sensor-integrated catheters in outpatient settings.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Ensures market access in the United States for innovative nephrostomy devices. |
| CE Marking Pathway | Mandates compliance with Europe's Medical Device Regulation for product commercialization across the EU. |
| Hospital System Partnership | Secures preferred vendor status and high-volume procurement contracts for advanced devices. |
| Software Companion Development | Integrates digital health solutions for enhanced device monitoring and patient management. |
| Reimbursement Strategy | Optimizes coverage and payment for advanced nephrostomy solutions in key markets. |
Research Approach
Demand-side practitioners and supply-side operators were consulted, combining in-depth interviews with secondary validation. Primary interviews engaged interventional radiologists, hospital procurement managers, urologists, and device engineers. Secondary data sources included FDA 510(k) filings, PMDA review documents, and industry association publications. This approach ensured robust bottom-up and top-down triangulation for market sizing.
The analytical framework spans across the analysis window, projecting market trends and growth trajectories. Segmentation dimensions modeled include product types, end-users, applications, distribution channels, and material science advancements. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key forecast inputs include urological disease prevalence and healthcare infrastructure investment.
Material uncertainties — shifts in reimbursement policies or new non-invasive treatments — sit outside the modeled envelope. Forecasts reflect a specific set of assumptions documented during the study period. Revision becomes warranted when regulatory frameworks or major technological disruptions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IV Poles Market
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
South America C-Arms Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Neuroendoscopy Devices Market