
 South Korea Aesthetic Devices Market | 2026-2036
South Korea Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Aesthetic Devices Market Analytics
Biocompatible polymer components are replacing metal housings in handheld applicators and is rebalancing unit economics for mid-range laser platforms. Jeisys Medical Inc. leverages its Seoul manufacturing base to sustain cost advantages in radiofrequency device assembly. Hironic Co., Ltd. anchors its position through dedicated R&D spending on dual-wavelength systems for pigmented lesion treatment. Alma Lasers Ltd. competes by extending its distributor network into secondary cities beyond the capital region.
South Korea aesthetic devices comprise electromechanical and energy-based systems engineered to deliver controlled thermal, optical, or acoustic energy to dermal and subcutaneous tissue, typically operating at wavelengths between 532 nm and 1064 nm for laser modalities or frequencies between 1 MHz and 40 MHz for radiofrequency platforms, with primary commercial purpose being cosmetic improvement without surgical incision. Injectable fillers and laser devices together command the dominant share of product-type revenue, while ultrasound-based body contouring platforms represent the fastest-expanding technology segment as clinics seek alternatives to cryolipolysis downtime. Dermatology centers and multi-specialty clinics constitute the highest-margin end-user channel due to their capacity for bundled treatment protocols and repeat device utilization.
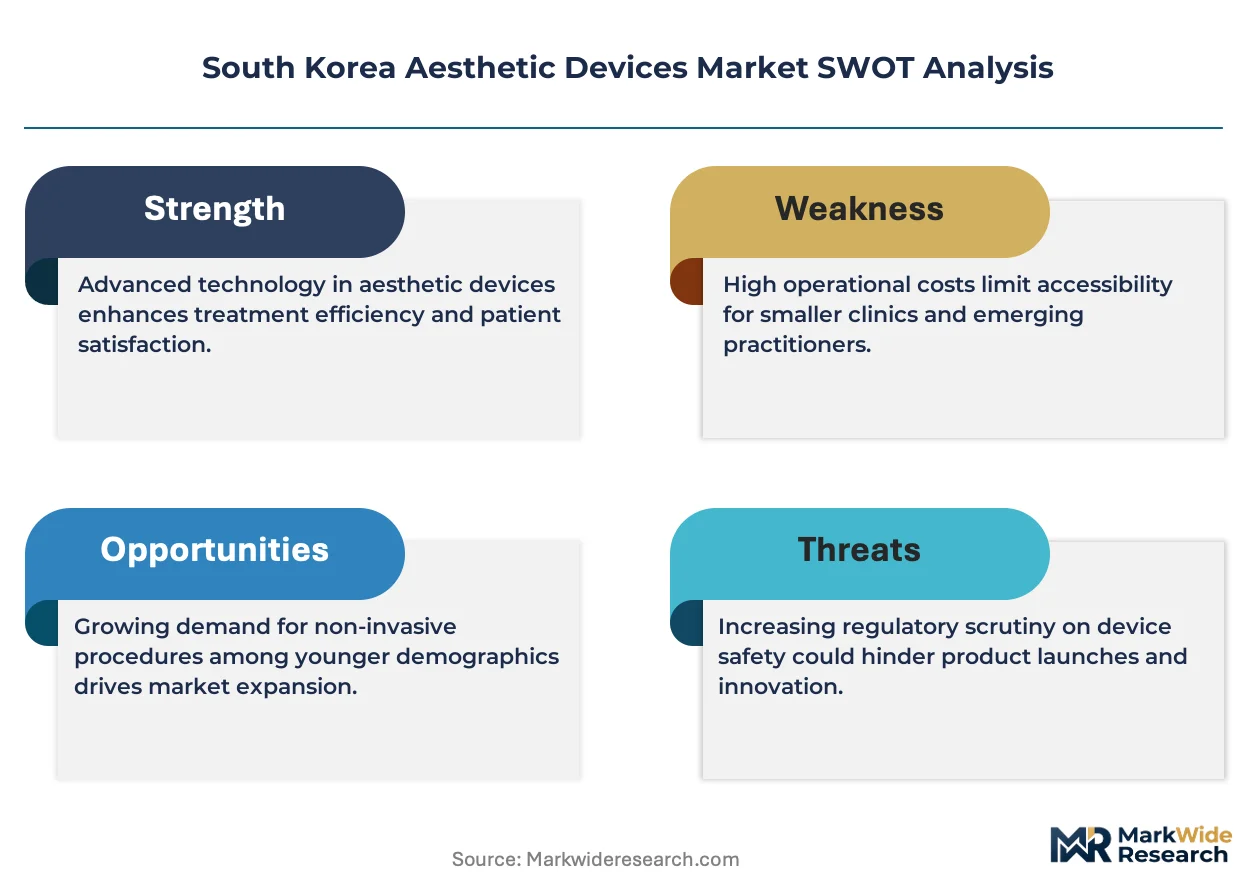
MFSD regulates device safety and clinical performance claims under the Medical Device Act, while KFDA-established electromagnetic compatibility standards shape design requirements for imported radiofrequency equipment. The Korean Ministry of Food and Drug Safety tightened adverse-event reporting thresholds for energy-based devices, pushing manufacturers toward more extensive pre-market clinical validation. Stakeholders must weigh domestic certification timelines against the revenue premium commanded by MFDS-approved platforms in neighboring export markets.
Market Dynamics
MFDS clearance pathway compression is accelerating domestic manufacturer entry timelines while simultaneously elevating clinical validation burdens for imported radiofrequency and ultrasound platforms.
Growth Catalysts
- MFDS Expedited Review Pathways:The Korean Ministry of Food and Drug Safety has streamlined electromagnetic compatibility documentation requirements for domestically assembled energy-based devices, cutting pre-market authorization cycles.
- Dermatology Center Expansion:Clinic chains across the Greater Seoul metropolitan area are scaling device procurement budgets to capture rising skin rejuvenation demand from aging urban demographics.
- Radiofrequency Platform Maturation:Advances in multi-polar electrode configurations are broadening treatable indications beyond facial tightening into submental contouring applications.
Market Restraints
- Optical Component Import Dependence:High-power laser diodes and precision sapphire crystals remain concentrated among German and Japanese suppliers, exposing domestic assemblers to yen-euro volatility.
- Clinical Validation Cost Escalation:MFDS tightened adverse-event reporting thresholds for energy-based devices, forcing manufacturers to fund larger pre-market safety cohorts.
- Cryolipolysis Substitution Pressure:Non-thermal fat reduction alternatives are capturing body contouring volume in Busan and secondary cities where downtime sensitivity runs higher.
Strategic Opportunities
- Daegu-Gwangju Corridor Penetration:Secondary metropolitan zones outside Seoul-Busan command lower clinic density per capita but rising disposable income profiles for aesthetic procedures.
- Dual-Wavelength Convergence:Platforms integrating 755 nm alexandrite with 1064 nm Nd:YAG sources enable sequential treatment of vascular and pigmented lesions in single sessions.
- Leasing Channel Development:Equipment finance partnerships are emerging as an alternative to outright purchase for mid-tier multi-specialty clinics managing capital constraints.
Industry Challenges
- Biomedical Engineer Talent Scarcity:The domestic labor pool lacks sufficient depth in thermal modeling and tissue optics to support rapid product iteration cycles.
- Legacy System Integration Friction:Clinics operating first-generation IPL platforms face compatibility barriers when upgrading to cloud-connected treatment logging systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Aesthetic Devices Market |
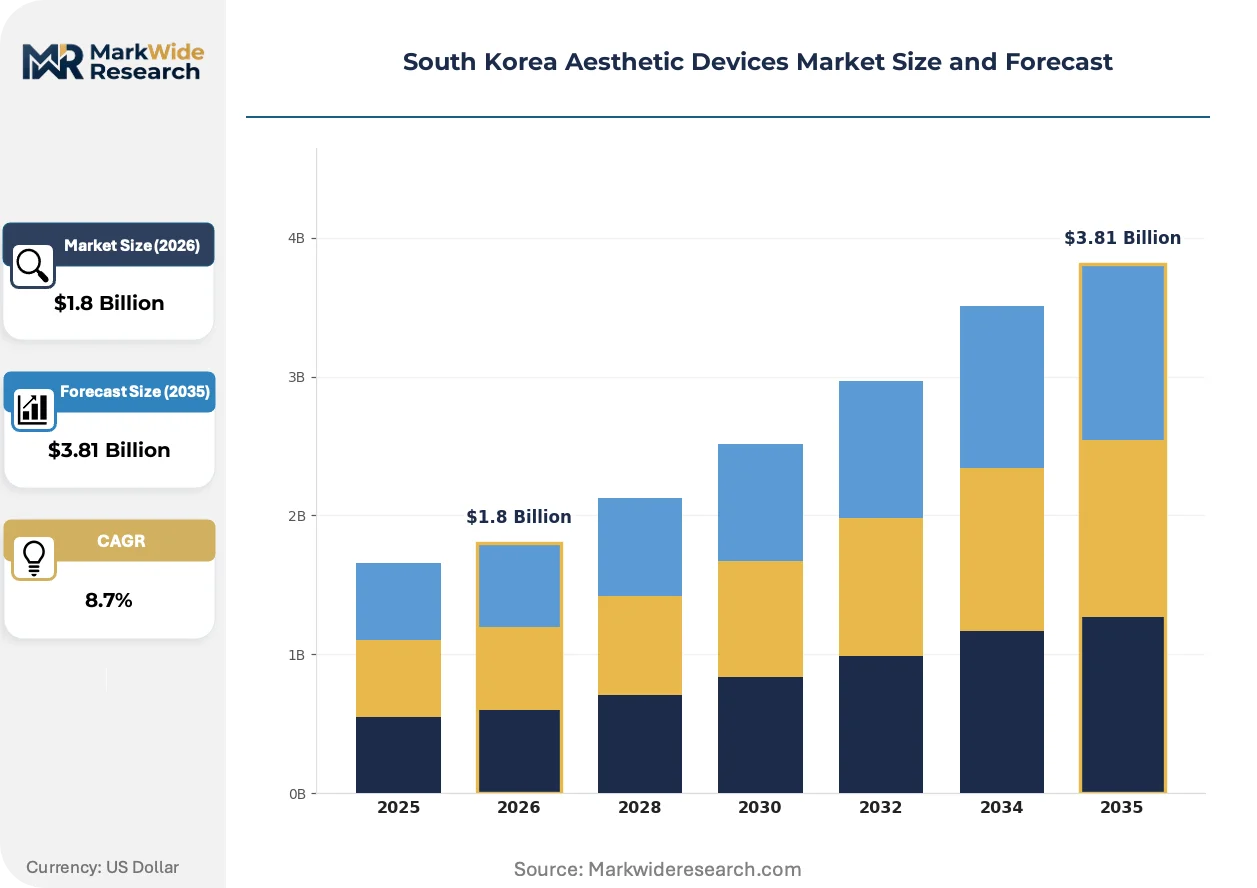
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Light Devices, Injectable Fillers, Body Contouring Devices Technology: Non-invasive, Minimally Invasive, Radiofrequency, Ultrasound End User: Clinics, Beauty Salons, Hospitals, Dermatology Centers Application: Skin Rejuvenation, Hair Removal, Body Sculpting, Acne Treatment |
| Companies Covered | Cynosure LLC, Jeisys Medical Inc., Classys Inc, Lumenis Be Ltd., Hironic Co., Ltd., Wontech Co., Ltd, AbbVie Inc, Alma Lasers Ltd., Candela Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Aesthetic Devices Market Evolving Landscape
Artificial intelligence-assisted treatment planning is compressing operator training curves while simultaneously raising performance expectations for energy delivery precision across Korean clinic networks.
Fractional radiofrequency microneedling is automating depth-controlled thermal injury patterns that previously required manual operator judgment, enabling consistent outcomes across less experienced technicians in high-volume Gangnam district practices, and compressing the skill premium that historically separated premium clinics from standard-tier competitors.
MFDS adverse-event database transparency mandates are forcing manufacturers to publish device-specific complication rates, creating competitive pressure for platforms with cleaner safety profiles while accelerating withdrawal of legacy systems with higher revision rates from the Korean market.
Clinic procurement committees are consolidating vendor relationships around full-platform suppliers capable of delivering bundled service contracts spanning laser, radiofrequency, and ultrasound modalities, displacing the prior pattern of best-of-breed device selection that fragmented maintenance obligations across multiple OEMs in Seoul metropolitan area chains.
South Korea Aesthetic Devices Market Segmentation
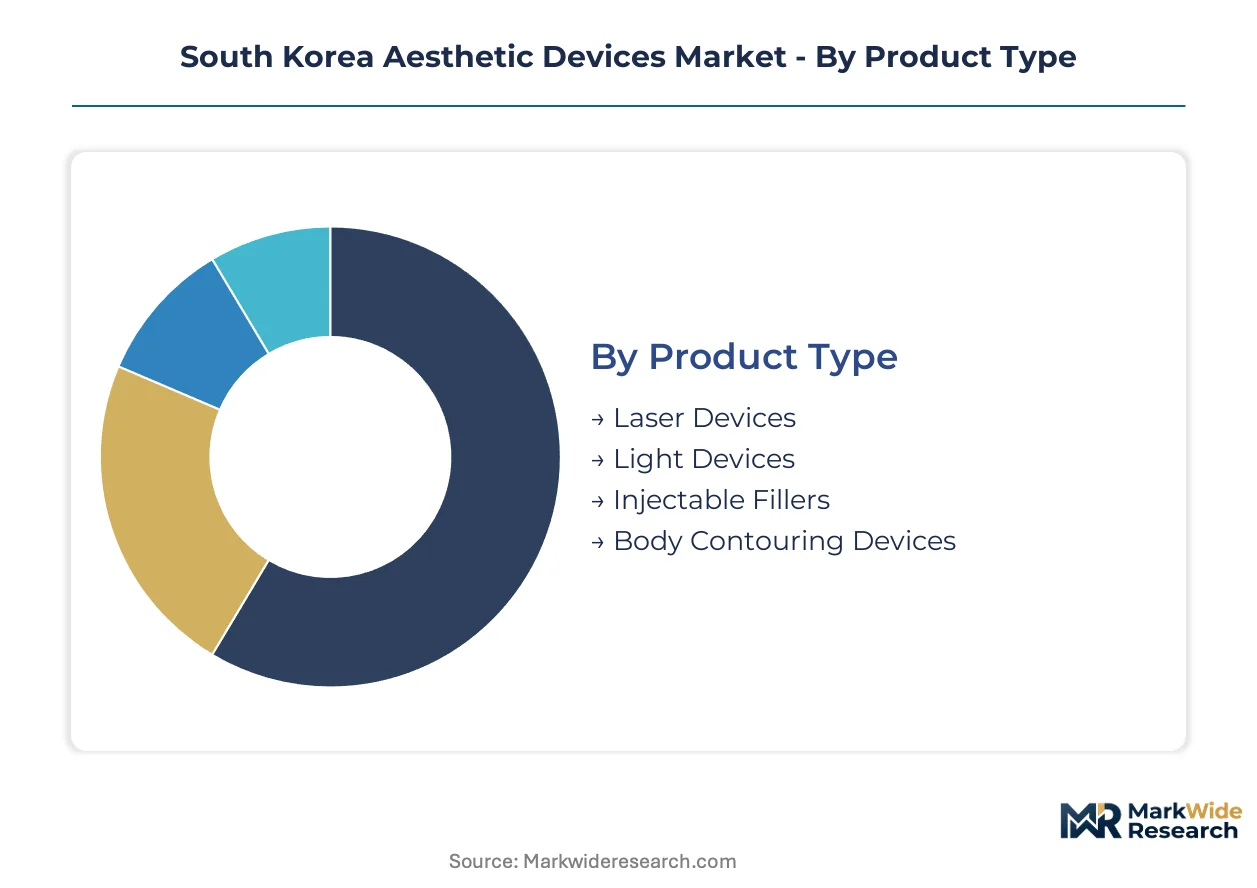
Device replacement cycles in South Korean aesthetic clinics now average three to four years, compressing procurement windows and forcing vendors to align refresh schedules with MFDS clearance timelines. Segmentation clarity enables manufacturers to map upgrade pathways across clinic tiers and metropolitan zones.
Product Type:
Clinic procurement committees prioritize replacement-ready platforms that minimize retraining costs and maximize utilization rates across existing treatment rooms.
- Laser Devices:Solid-state and diode laser systems operating at 532 nm to 1064 nm wavelengths dominate capital expenditure budgets in Seoul dermatology centers. Gangnam district chains favor multi-wavelength platforms enabling sequential vascular and pigmented lesion treatment without device switching.
- Injectable Fillers:Hyaluronic acid and calcium hydroxylapatite formulations command premium pricing in Busan metropolitan clinics targeting volume-based facial contouring protocols. MFDS biocompatibility testing requirements for new filler introductions have lengthened domestic manufacturer development cycles.
- Light Devices:IPL and LED platforms serve entry-level treatment rooms in Daegu multi-specialty clinics.
- Body Contouring Devices:Cryolipolysis and thermal alternatives capture secondary city demand where downtime sensitivity shapes modality selection.
Laser Devices sit at the top of the volume ranking, with Injectable Fillers climbing the fastest.
Technology:
Cost tier stratification separates premium platforms with integrated cooling systems from economy alternatives relying on external chillers.
- Radiofrequency:Multi-polar electrode configurations delivering 1 MHz to 40 MHz frequencies now extend into submental contouring applications beyond traditional facial tightening. Seoul clinic chains report higher patient throughput per treatment hour versus legacy monopolar systems.
- Ultrasound:High-intensity focused acoustic platforms enable non-thermal fat reduction with minimal recovery intervals, capturing body sculpting volume in Busan and Gwangju where patients prioritize same-day return to work. MFDS electromagnetic compatibility documentation requirements have compressed approval timelines for domestically assembled units.
- Non-invasive:Surface energy delivery systems dominate high-frequency appointment scheduling in beauty salon channels.
- Minimally Invasive:Fractional microneedle platforms bridge professional clinic and medical spa positioning.
Radiofrequency maintains the highest installed base, while Ultrasound gains share fastest among new platform acquisitions.
End User:
Margin structures vary sharply across channel types, with bundled protocol capacity determining vendor pricing power.
- Dermatology Centers:Specialist-owned facilities in Greater Seoul command premium device pricing through repeat utilization rates and cross-selling of maintenance skincare protocols. These centers prioritize MFDS-cleared platforms with published adverse-event databases to support malpractice insurance negotiations.
- Clinics:Multi-specialty operations in secondary metropolitan zones balance capital constraints against patient volume targets, driving interest in equipment leasing partnerships.
- Hospitals:Academic medical centers in Seoul anchor clinical validation studies for domestic manufacturers seeking export market credibility.
- Beauty Salons:Non-medical operators face regulatory boundaries on energy-based device operation, limiting addressable technology scope.
Dermatology Centers capture the highest revenue per device, with Clinics representing the broadest addressable unit volume.
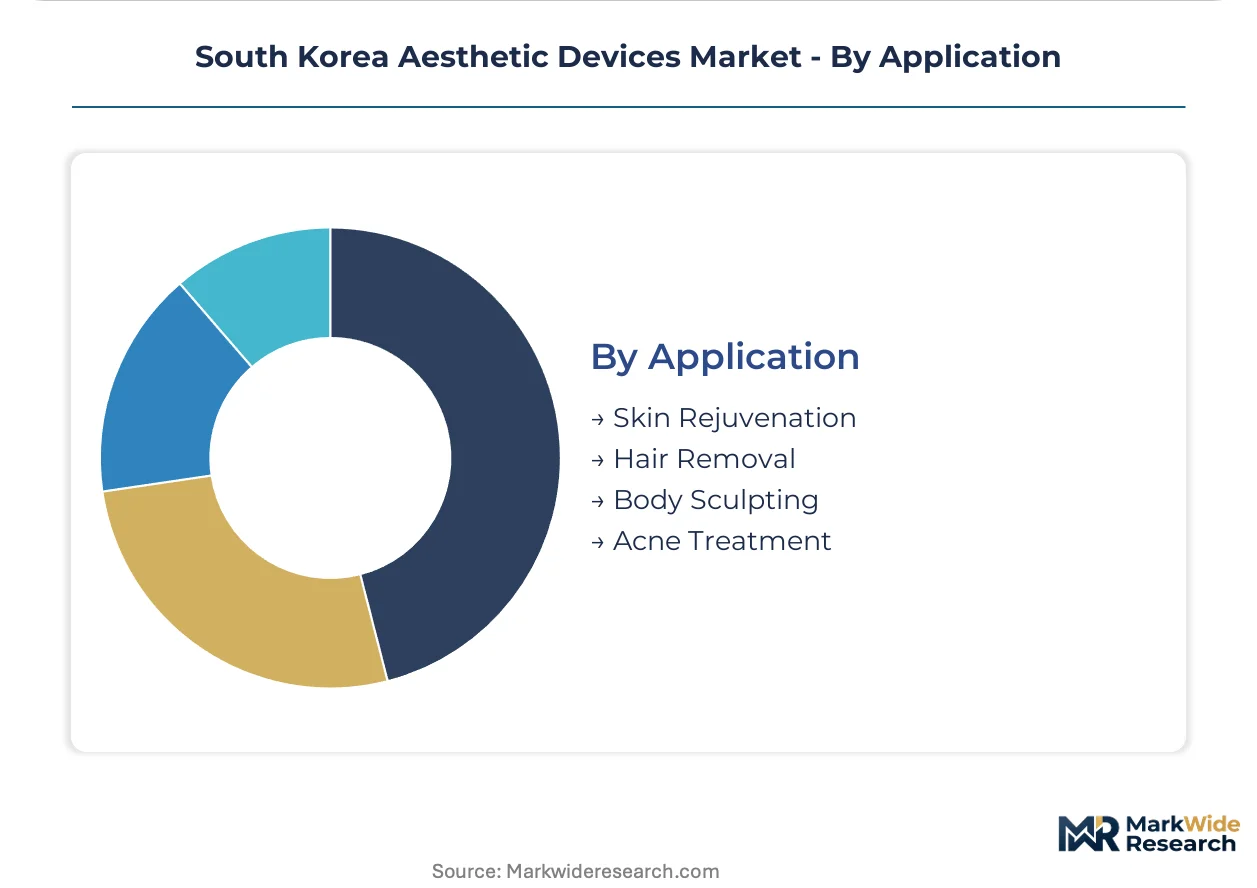
Application:
Patient demographics and disposable income profiles concentrate demand differently across metropolitan zones.
- Skin Rejuvenation:Fractional laser and radiofrequency protocols targeting photoaging command the highest appointment frequency in Gangnam district practices serving aging urban professionals. Treatment bundling with topical skincare regimens extends customer lifetime value metrics.
- Body Sculpting:Non-invasive fat reduction and muscle toning applications expand fastest in Busan and Incheon where post-pandemic wellness spending has shifted toward physique-oriented aesthetic goals. Ultrasound and electromagnetic platforms displace cryolipolysis in clinics emphasizing zero-downtime positioning.
- Hair Removal:Diode laser permanence protocols retain stable demand across clinic tiers.
- Acne Treatment:Blue light and photodynamic alternatives serve adolescent and young adult demographics in university-adjacent clinic locations.
Skin Rejuvenation leads procedure volume, while Body Sculpting demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area concentrates the majority of aesthetic device procurement activity, with clinic chains driving replacement cycles and technology upgrades across the metropolitan zone.
Seoul Capital Area
Gangnam district dermatology centers command premium pricing for multi-wavelength laser platforms and bundled treatment protocols. MFDS clearance pathways for domestically assembled radiofrequency devices have compressed approval timelines, accelerating manufacturer entry. Samsung-dong and Cheongdam clusters host the highest density of high-volume aesthetic practices in South Korea.
Busan-Ulsan
Body sculpting applications dominate procurement budgets as patient preferences shift toward zero-downtime ultrasound alternatives. The Korean Ministry of Food and Drug Safety electromagnetic compatibility standards shape design requirements for imported equipment entering this port region. Haeundae and Centum City medical zones anchor device distribution networks serving southeastern coastal clinics.
Daegu-Gyeongbuk
Rising disposable income profiles in this secondary corridor are expanding addressable clinic density per capita below Seoul levels. MFDS adverse-event reporting thresholds apply uniformly, elevating clinical validation burdens for new market entrants. Daegu metropolitan clinics increasingly source equipment through leasing partnerships rather than outright purchase.
Daejeon-Sejong
Government research institutions in this administrative hub anchor clinical validation studies for domestic manufacturers seeking export credibility. The region's academic medical centers participate in pre-market safety cohorts required under tightened MFDS regulations. Sejong City emerging clinic chains represent a nascent demand pocket for mid-range laser platforms.
Gwangju-Honam
Lower clinic saturation relative to the capital creates expansion opportunities for equipment vendors penetrating southwestern markets. MFDS biocompatibility testing requirements for new filler introductions have lengthened development cycles for regional distributors. Gwangju metropolitan aesthetic practices prioritize cost-efficient IPL and LED platforms for entry-level treatment rooms.
South Korea Aesthetic Devices Market Competitive Landscape
Domestic manufacturing scale-up dominates the current landscape as Korean assemblers exploit shortened MFDS clearance pathways. The vendor base separates into three tiers: multinational OEMs with full-platform portfolios, mid-cap domestic specialists, and emerging assemblers targeting price-sensitive secondary cities. Two strategic archetypes predominate: vertically integrated manufacturers controlling component supply chains, and distributor-dependent importers leveraging foreign technology. Capacity expansion and strategic equipment finance partnerships constitute the dominant competitive moves reshaping channel relationships.
Among Seoul-based manufacturers, Jeisys Medical Inc. and Hironic Co., Ltd. exemplify the vertically integrated archetype, sustaining cost advantages through captive assembly operations. Wontech Co., Ltd. occupies a position within the mid-cap specialist tier, while Classys Inc represents domestic players pursuing dual-wavelength convergence strategies. Alma Lasers Ltd., despite its foreign origin, anchors distributor network expansion into secondary metropolitan zones beyond the capital region. These named entities illustrate the competitive tension between domestic scale advantages and multinational technology access.
| Leading Market Players |
|---|
| Cynosure LLC |
| Jeisys Medical Inc. |
| Classys Inc |
| Lumenis Be Ltd. |
| Hironic Co., Ltd. |
| Wontech Co., Ltd |
| AbbVie Inc |
| Alma Lasers Ltd. |
| Candela Medical |
| Others |
Value Network & Pricing Analysis
Captive assembly operations at Seoul-based manufacturers anchor both cost positioning and margin defense against imported radiofrequency and ultrasound platforms. Domestic vertical integration into radiofrequency electrode fabrication and laser housing production insulates Korean assemblers from yen-euro volatility while compressing unit economics for mid-range platforms serving Gangnam district clinic chains.
Pricing Analysis
Input-cost pass-through from German and Japanese optical component suppliers feeds directly into premium-tier laser platform pricing, with sapphire crystal and high-power diode fluctuations compressing margins for domestic assemblers lacking backward integration. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-cleared multi-wavelength systems from single-modality imports and refurbished legacy units. Pricing pressure stems from equipment finance partnerships enabling mid-tier clinics to access premium platforms without capital outlay, eroding the historical price premium for outright purchase. Multi-specialty clinics in Daegu and Gwangju exhibit highest price sensitivity, while Seoul dermatology centers prioritize adverse-event database transparency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for high-power laser diodes and precision optics mandate qualification of both German and Japanese suppliers, extending procurement cycles for domestic manufacturers assembling in Seoul and Busan. Component flows concentrate from Germany, Japan, and domestic Korean fabrication facilities for radiofrequency electrodes and polymer housings. Raw material dependencies span sapphire substrates, rare-earth laser crystals, and biocompatible polymers for handheld applicators. Single-source vulnerability in high-power diode supply exposes assemblers to currency volatility and export licensing friction. Distribution runs through authorized medical device distributors serving clinic chains, with direct manufacturer relationships reserved for top-tier Seoul metropolitan accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS clearance pathway compression in South Korea creates a geographic-arbitrage opportunity against lengthier FDA and CE MDR timelines, enabling domestic manufacturers to capture regional export markets before multinational entrants secure competing approvals.
For Market Incumbents: Deploy adverse-event database transparency as a competitive lever. Jeisys Medical Inc. and Hironic Co., Ltd. should consolidate service contract bundling across laser, radiofrequency, and ultrasound modalities to displace best-of-breed fragmentation in Seoul clinic chains. Capacity addition in secondary metropolitan zones outside the capital defends against emerging assemblers targeting price-sensitive Daegu and Gwangju markets.
For New Entrants and Emerging Players: MFDS expedited review pathways for domestically assembled energy-based devices open a window for secondary city penetration. Target Daegu-Gwangju corridor clinics through equipment leasing partnerships rather than outright purchase competition. White-space exists in cloud-connected treatment logging systems compatible with legacy IPL platforms. Go-to-market through distributor networks anchored in Busan-Ulsan medical zones bypasses Seoul incumbent saturation.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap domestic specialists with captive assembly operations because MFDS clearance assets command premium multiples in neighboring export markets. Five-to-ten-year viability hinges on vertical integration depth in radiofrequency electrode and laser housing production. Target acquisition archetype: domestic assemblers with published adverse-event databases and existing distributor relationships in Busan or Gwangju. Signal to watch: equipment finance partnership announcements indicating channel control capture.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Expedited Clearance Pursuit | Compressed timelines enable domestic manufacturers to outpace FDA and CE MDR competitors in regional export markets. |
| Equipment Finance Partnership Development | Leasing structures unlock mid-tier clinic demand in Daegu and Gwangju without capital purchase barriers. |
| Dual-Wavelength Platform Convergence | Sequential 755 nm alexandrite and 1064 nm Nd:YAG integration captures vascular and pigmented lesion bundling revenue. |
| Cloud-Connected Treatment Logging Integration | Compatibility layers for legacy IPL platforms address integration friction blocking upgrade cycles in high-volume practices. |
| Secondary Metropolitan Distribution Expansion | Authorized distributor networks in Busan-Ulsan and Daegu-Gyeongbuk corridors capture rising disposable income profiles. |
Research Methodology
Direct dialogue with dermatology center procurement committees, biomedical engineers at domestic manufacturers, MFDS regulatory affairs specialists, and equipment finance underwriters grounded qualitative assessment in operational reality. Secondary validation drew from MFDS adverse-event database disclosures, Korean Medical Device Industry Association trade flow records, and hospital procurement database extracts. Bottom-up clinic installation counts triangulated against top-down manufacturer shipment estimates to anchor volume figures.
Segment-level value outputs across the analysis window reflect modeled adoption curves for radiofrequency, ultrasound, laser, and injectable filler platforms. Segmentation dimensions incorporated product type, technology modality, end-user channel tier, and metropolitan zone density. CAGRs derived from fitted growth curves applied to base-year installation stock and replacement cycle assumptions. Industry-specific forecast inputs included MFDS clearance timeline distributions and equipment finance penetration rates by clinic tier.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MFDS regulatory stringency shifts or yen-euro volatility spikes in optical component sourcing. Deviation in equipment finance partnership uptake rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Medical Manifolds Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
North America Pen Needles Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Catheter Systems Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Europe Ultrasound Devices Market