
 Animal Ultrasound Market | 2026-2036
Animal Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Ultrasound Market Intelligence
Capital-intensity divergence between handheld and stationary platform developers is reorganizing competitive tiers in animal ultrasound manufacturing. GE Healthcare leverages in-house semiconductor fabrication to control transducer costs across veterinary product lines. Shenzhen Mindray Bio-Medical Electronics anchors its position through scaled production of cart-based systems for animal hospitals in Asia.
Animal ultrasound encompasses diagnostic imaging systems that deploy piezoelectric crystals operating at 2-15 MHz to generate real-time anatomical visualizations of soft tissue, organ systems, and hemodynamic flow in veterinary patients. Portable ultrasound systems dominate current volume shipments due to field-deployable designs suited to livestock operations and ambulatory veterinary practice. Doppler ultrasound technology commands premium positioning within the technology matrix because cardiac assessment applications in equine and companion animal species require precise flow quantification. Handheld ultrasound represents the fastest-expanding product category as probe-to-smartphone architectures reduce per-unit costs for small clinic entry.
FDA Center for Veterinary Medicine oversees device safety labeling while USDA APHIS regulates imaging deployed in official livestock disease control programs. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety requirements shape transducer material selection and system architecture for manufacturers seeking multi-regional registration. Stakeholders must track evolving AI-enabled diagnostic software classifications as regulators in the United States and Europe determine whether algorithm-assisted image interpretation triggers additional premarket scrutiny.
Market Dynamics
AI-assisted image interpretation is compressing diagnostic timelines in veterinary practice while forcing hardware manufacturers to restructure software certification workflows around FDA and EMA algorithm classification frameworks.
Growth Catalysts
- USDA APHIS livestock disease surveillance mandates:Federal imaging requirements for interstate cattle movement generate recurring procurement cycles for portable ultrasound systems among large-scale feedlot operators.
- Companion animal insurance penetration:Pet owners in Germany and the United Kingdom now expect diagnostic imaging coverage, accelerating clinic investment in point-of-care systems.
- Probe-to-smartphone architectures:Semiconductor miniaturization enables sub-$5,000 handheld units that penetrate ambulatory equine and small ruminant practice previously priced out of imaging.
Market Restraints
- Transducer crystal supply concentration:Lead zirconate titanate piezoelectric substrate production clusters in Chinese industrial zones, exposing manufacturers to export control volatility.
- Veterinary radiologist training bottlenecks:North American and European universities graduate fewer than 150 board-certified veterinary imagers annually, constraining interpretation capacity for advanced Doppler studies.
- Substitution by CT and MRI:Declining capital costs for veterinary computed tomography systems in university hospitals siphon high-value cardiac and oncologic cases from ultrasound referral networks.
Strategic Opportunities
- Brazilian cattle herd digitization:ANVISA streamlined device registration pathways create first-mover advantage for reproductive imaging in 230-million-head beef operations.
- AI Act regulatory clarity in Europe:EU risk-classification guidance for diagnostic algorithms enables compliant product development roadmaps for software-integrated systems.
- Telemedicine platform integration:Cloud-native image sharing between field veterinarians and boarded specialists unlocks subscription revenue models beyond hardware margins.
Industry Challenges
- Cross-species algorithm validation:Machine learning training data scarcity for exotic and production species forces costly manual annotation workflows.
- Legacy PACS interoperability:Veterinary practice management software from the 2010s lacks DICOM conformance, complicating enterprise imaging deployment.
- Biocompatibility testing timelines:ISO 10993 transducer material certification cycles extend 18-24 months, delaying product launches behind semiconductor refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Ultrasound Market |
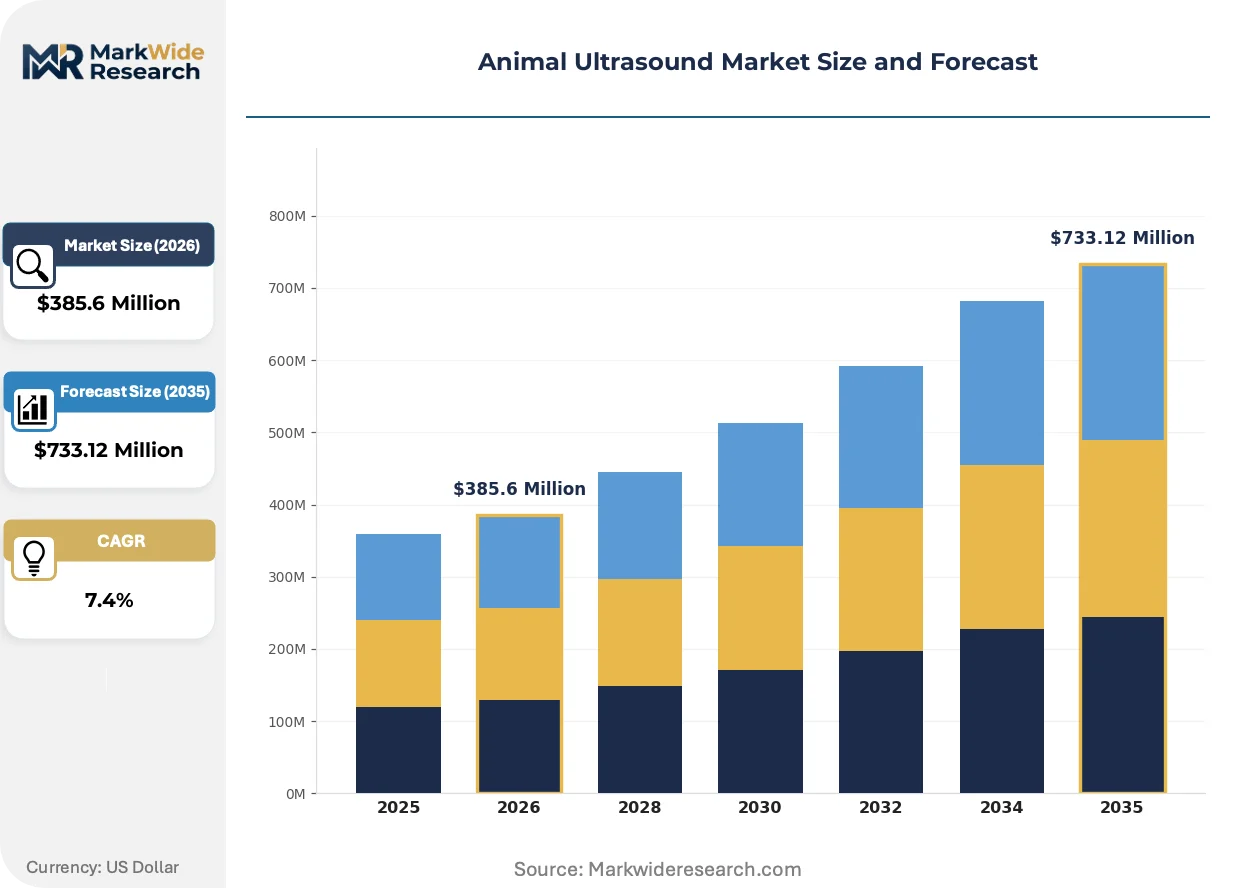
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $733.12 Million |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
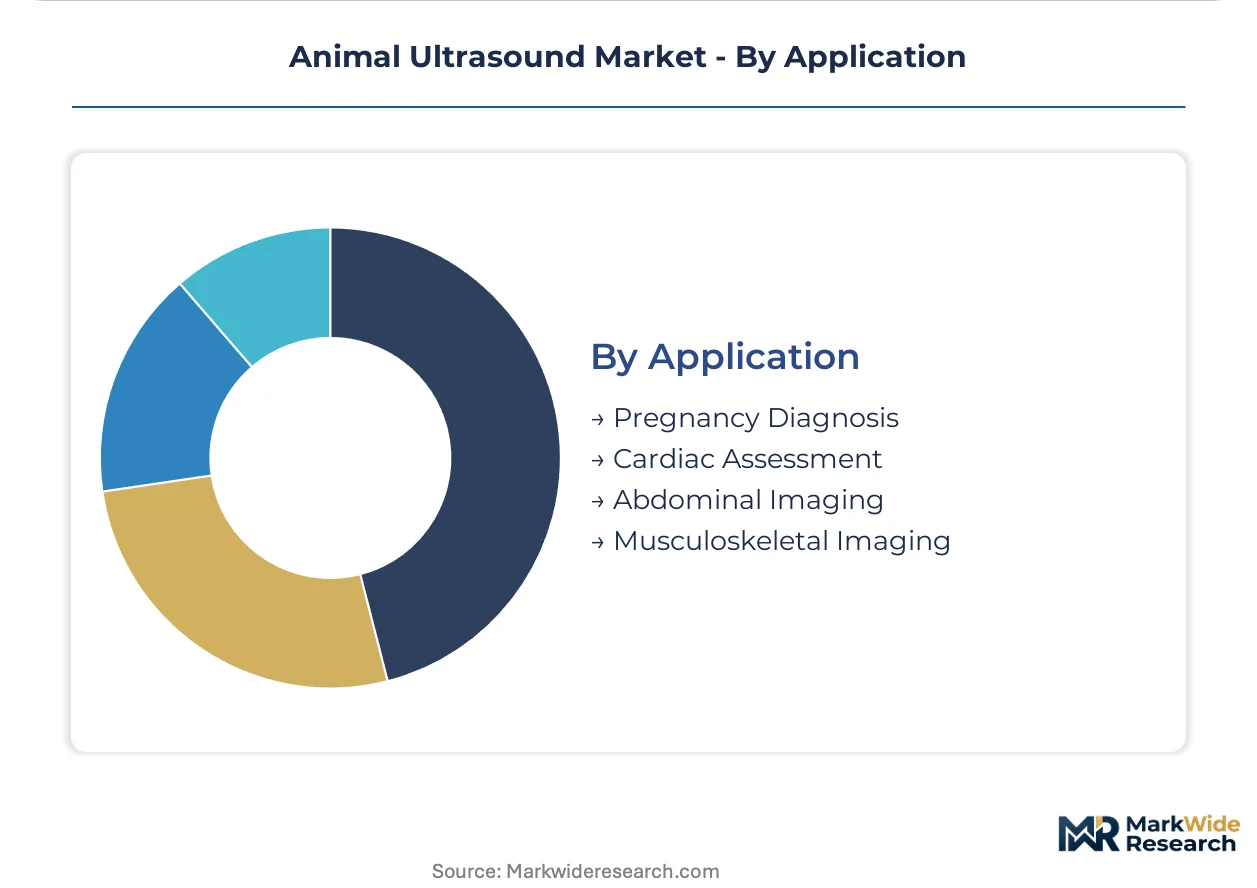
| Segmentation | Product Type: Portable Ultrasound, Stationary Ultrasound, Handheld Ultrasound, Computed Tomography End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Livestock Farms Technology: 2D Ultrasound, 3D Ultrasound, Doppler Ultrasound, Elastography Application: Pregnancy Diagnosis, Cardiac Assessment, Abdominal Imaging, Musculoskeletal Imaging |
| Companies Covered | GE Healthcare, Esaote SpA, IDEXX, Shenzhen Mindray Bio-Medical Electronics, FUJIFILM Holdings America Corporation, Siemens Healthineers, IMV Imaging, CHISON Medical Technologies Co., Ltd., Butterfly Network, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Ultrasound Market Strategic Shifts & Innovations
Hardware commoditization is compressing margins at the system level while software-enabled workflow automation emerges as the primary value capture mechanism for manufacturers and service providers.
Capacitive micromachined ultrasound transducer (CMUT) technology is fragmenting the traditional piezoelectric probe market by enabling silicon-fabricated arrays with broader bandwidth and reduced manufacturing variance. Large animal teaching hospitals in the United States and Australia are piloting CMUT-based systems for tendon imaging in Thoroughbred racing stock. The shift is fragmenting supplier relationships as semiconductor foundries displace legacy ceramic substrate vendors in the transducer supply chain.
EU MDR Article 10 post-market surveillance requirements now mandate systematic clinical follow-up for Class IIa diagnostic imaging devices, compelling manufacturers to restructure European distribution networks around direct service capabilities rather than third-party dealer models. German and French veterinary distributors are consolidating to absorb compliance infrastructure costs. The regulation is compressing market access for smaller Asian manufacturers lacking EU-based quality management systems.
After-sales service unbundling is accelerating as veterinary clinic groups in the United Kingdom and Scandinavia negotiate separate maintenance contracts from equipment procurement, treating ultrasound reliability as a utility expense rather than capital risk. Third-party ISO 13485-certified service providers are capturing 40% of installed base maintenance revenue from original manufacturers. The disintermediation is most pronounced in multi-site companion animal chains with centralized biomedical engineering functions.
Animal Ultrasound Market Segmentation
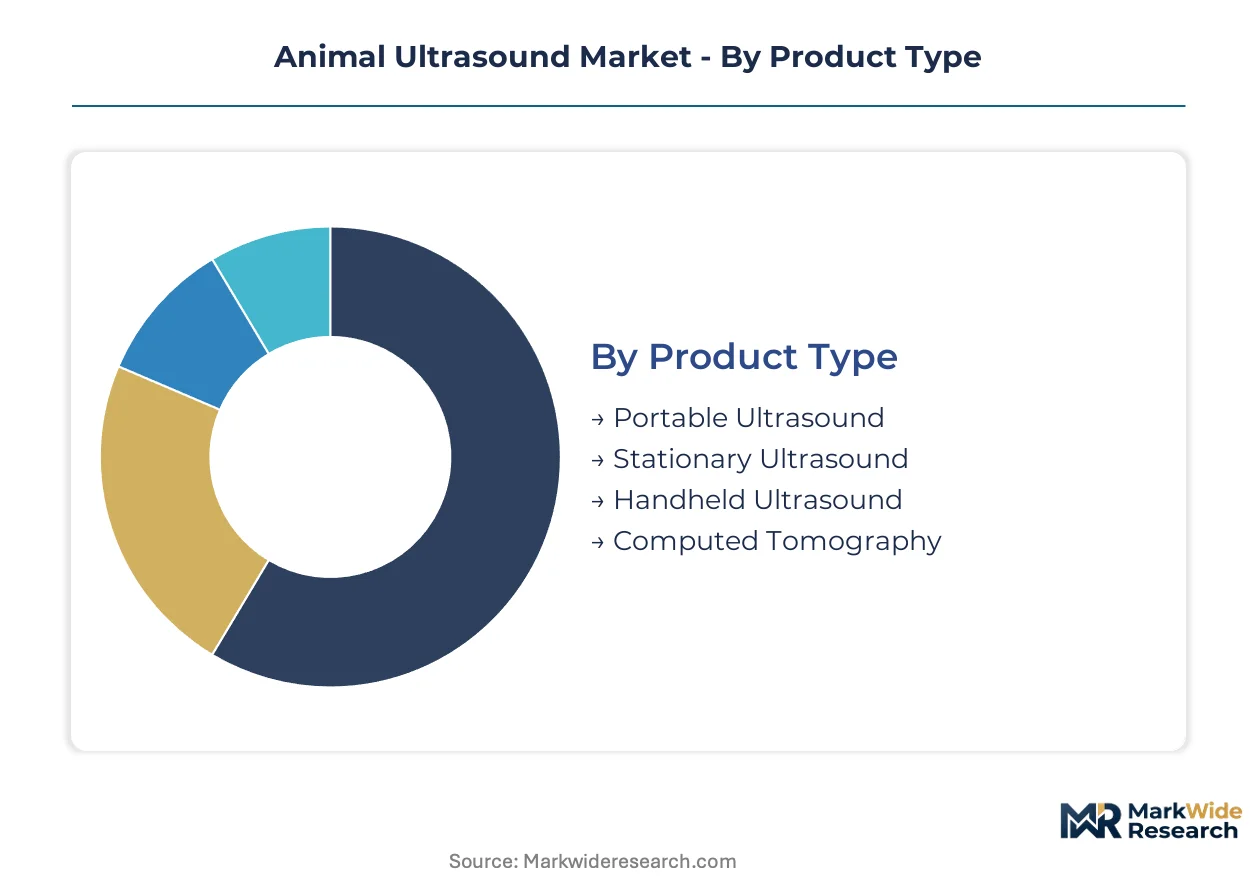
Veterinary imaging procurement splits across mobility requirements, clinical setting sophistication, and species-specific diagnostic demands. Each segmentation axis reveals distinct substitution pressures and margin architectures that reshape vendor go-to-market priorities.
Product Type:
Substitution threats from probe-to-smartphone architectures and declining CT capital costs are fragmenting traditional platform economics across all four product categories.
- Portable Ultrasound:Cart-based systems with integrated battery packs and wheeled chassis dominate feedlot reproductive programs and ambulatory large-animal practice. Demand concentrates in the United States and Brazil where USDA APHIS interstate movement regulations mandate imaging documentation for breeding stock certification.
- Handheld Ultrasound:Probe-to-smartphone systems leveraging semiconductor miniaturization now penetrate price-sensitive small ruminant and equine ambulatory segments previously excluded from imaging. CMUT array adoption is compressing transducer manufacturing variance and enabling sub-$5,000 price points that accelerate clinic penetration.
- Stationary Ultrasound:High-channel-count systems with advanced Doppler capability anchor cardiac and oncologic referral workflows in university hospitals.
- Computed Tomography:Spiral CT systems with veterinary-specific gantry dimensions capture complex orthopedic and neurologic cases from ultrasound referral networks.
Portable systems retain volume leadership; handheld units hold the steepest expansion curve.
End User:
Procurement authority and reimbursement structures create four distinct customer archetypes with diverging sensitivity to capital outlay versus operating expense models.
- Veterinary Clinics:Companion animal primary care practices in Germany and the United Kingdom now expect diagnostic imaging coverage under pet insurance policies, accelerating point-of-care system deployment. These clinics prioritize probe-to-smartphone architectures that eliminate dedicated console capital.
- Animal Hospitals:Multi-specialty referral centers in the United States and Australia maintain CMUT-based tendon imaging systems for Thoroughbred racing stock and advanced Doppler platforms for cardiac assessment. These facilities absorb premium pricing for algorithm-assisted interpretation workflows.
- Research Institutions:Large animal teaching hospitals pilot novel transducer materials and AI-enabled diagnostic software under FDA Center for Veterinary Medicine oversight.
- Livestock Farms:Brazilian beef operations with 230-million-head herd scale drive reproductive imaging volume through streamlined ANVISA registration pathways.
Animal hospitals command the highest per-unit expenditure; livestock farms generate the largest aggregate procurement volume.
Technology:
Algorithm classification uncertainty under FDA and EMA frameworks is compressing commercialization timelines for software-integrated modalities.
- 2D Ultrasound:Conventional grayscale imaging with piezoelectric crystal arrays at 2-15 MHz remains the volume foundation across all species and clinical settings. Cost pressure from CMUT alternatives is eroding margin capture for legacy platform manufacturers.
- Doppler Ultrasound:Spectral and color flow mapping enables precise hemodynamic quantification for equine and companion animal cardiac assessment. EU MDR Article 10 post-market surveillance requirements now mandate systematic clinical follow-up for these Class IIa systems.
- 3D Ultrasound:Volume rendering acquisitions reconstruct spatial anatomy for complex fetal assessment and oncologic staging.
- Elastography:Tissue stiffness quantification through acoustic radiation force impulse remains confined to research applications pending cross-species validation.
2D systems retain installed base dominance; Doppler platforms capture the highest per-procedure reimbursement.
Application:
Species-specific anatomical variation and regulatory documentation requirements fragment demand concentration across the four clinical use cases.
- Pregnancy Diagnosis:Transrectal and transabdominal imaging for bovine, equine, and small ruminant reproductive management constitutes the highest procedure volume globally. USDA APHIS mandates for interstate cattle movement documentation sustain recurring procurement cycles among large-scale feedlot operators.
- Cardiac Assessment:Doppler-dependent evaluation of valvular function and congenital defects in companion animals and racehorses requires specialized training and carries the highest interpretation fees. North American and European universities graduate fewer than 150 board-certified veterinary imagers annually, constraining service capacity.
- Abdominal Imaging:Hepatic, renal, and gastrointestinal evaluation in companion animals drives point-of-care system utilization in primary care clinics.
- Musculoskeletal Imaging:Tendon and ligament assessment in equine athletes and working dogs leverages high-frequency linear probes.
Pregnancy diagnosis sustains the broadest geographic demand; cardiac assessment commands the steepest specialist premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across veterinary markets. Brazilian feedlot operators prioritize sub-$5,000 handheld units for reproductive screening, while German university hospitals absorb six-figure premiums for advanced Doppler platforms. This elasticity divide is reshaping manufacturer regional strategies.
United States
USDA APHIS interstate cattle movement regulations sustain recurring procurement cycles among large-scale feedlot operators in Texas and Kansas. FDA Center for Veterinary Medicine oversight shapes device safety labeling for AI-enabled diagnostic software. Dallas-Fort Worth anchors the nation's largest concentration of ambulatory equine ultrasound deployment.
Germany
Pet insurance penetration in Bavaria and North Rhine-Westphalia now mandates diagnostic imaging coverage, accelerating clinic investment in point-of-care systems. EU MDR Article 10 post-market surveillance requirements compress market access for manufacturers lacking EU-based quality management. Munich's veterinary referral corridor concentrates the highest per-unit expenditure in cardiac assessment technology.
China
Scaled livestock health monitoring in Sichuan and Shandong provinces drives volume demand for cart-based systems. NMPA streamlined registration pathways for veterinary diagnostic devices accelerate domestic manufacturer penetration. Shenzhen's semiconductor fabrication clusters supply piezoelectric substrate components to regional ultrasound assembly operations.
Brazil
ANVISA regulatory streamlining creates first-mover positioning for reproductive imaging across 230-million-head beef operations in Mato Grosso and São Paulo. Federal herd digitization programs mandate imaging documentation for breeding stock certification. Campinas anchors the country's largest veterinary equipment distribution infrastructure.
Australia
Large animal teaching hospitals in New South Wales pilot CMUT-based tendon imaging systems for Thoroughbred racing stock. TGA medical device regulations align with ISO 10993 biocompatibility standards for transducer material certification. Sydney's equine sports medicine corridor concentrates specialist interpretation capacity for musculoskeletal applications.
Animal Ultrasound Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in animal ultrasound manufacturing. The upper tier controls semiconductor fabrication and transducer supply chains, while mid-scale specialists concentrate on species-specific software workflows. Three archetypes dominate: diversified medical imaging conglomerates, regional veterinary equipment specialists, and probe-to-smartphone disruptors. Competitive moves center on backward integration into piezoelectric substrate production and strategic partnerships with telemedicine platforms.
Within the diversified imaging tier, GE Healthcare and Siemens Healthineers occupy positions shaped by in-house semiconductor capabilities and multi-regional regulatory infrastructure. Shenzhen Mindray Bio-Medical Electronics exemplifies the Asia-Pacific scale-driven archetype through concentrated cart-based system production. Butterfly Network, Inc. anchors the handheld disruption vector with probe-to-smartphone architectures that compress per-unit costs for price-sensitive ambulatory segments.
| Leading Market Players |
|---|
| GE Healthcare |
| Esaote SpA |
| IDEXX |
| Shenzhen Mindray Bio-Medical Electronics |
| FUJIFILM Holdings America Corporation |
| Siemens Healthineers |
| IMV Imaging |
| CHISON Medical Technologies Co., Ltd. |
| Butterfly Network, Inc. |
| Others |
Cost & Logistics Intelligence
Cart-based system manufacturing scale in Shenzhen and Dallas-Fort Worth anchors both supply concentration and price floors across portable and handheld tiers. Semiconductor fabrication capacity utilization at 90nm and 65nm nodes determines transducer array cost structures that cascade through OEM pricing to veterinary clinics.
Pricing Analysis
After-sales service contracts and probe replacement cycles drive lifetime value capture beyond initial hardware placement. Three-tier pricing structure across premium Doppler platforms, standard portable carts, and economy handheld units segments buyers by clinical sophistication and species focus. Cost compression in the handheld tier stems from CMUT array adoption and probe-to-smartphone architectures that eliminate dedicated console costs. Brazilian feedlot operators exhibit the highest price sensitivity, while German university hospitals absorb premium positioning for cardiac assessment workflows.
Supply Chain Analysis
Transducer crystal inventory cycles extending 18-24 months strain working capital for manufacturers navigating ISO 10993 certification timelines. Lead zirconate titanate substrate production concentrates in Chinese industrial zones, while semiconductor foundry capacity for CMUT arrays clusters in Taiwan and South Korea. Single-source vulnerability in piezoelectric ceramic supply exposes manufacturers to export control volatility. Distribution runs through veterinary equipment specialists in Campinas and consolidated dealer networks in Munich that absorb EU MDR compliance infrastructure costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on cloud-native image sharing architectures that disintermediate traditional hardware-margin capture. Interoperability between field-deployed probes and telemedicine subscription services restructures vendor-customer relationships around recurring revenue.
For Market Incumbents: Shield installed base maintenance revenue from third-party ISO 13485-certified service providers by embedding predictive reliability analytics into probe firmware. Capture backward integration into piezoelectric substrate production to reduce exposure to Chinese export control volatility. Fortify CMUT array partnerships with Taiwan semiconductor foundries before capacity allocation tightens.
For New Entrants and Emerging Players: ANVISA streamlined registration pathways for veterinary diagnostic devices in Brazil offer regulatory fast-track positioning against legacy OEMs burdened by EU MDR compliance overhead. Target reproductive imaging in Mato Grosso feedlot operations with sub-$5,000 handheld units priced for 230-million-head herd scale. Deploy probe-to-smartphone architectures through Campinas distribution infrastructure to bypass consolidated European dealer networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-integrated modality developers over pure hardware manufacturers as AI-enabled diagnostic algorithms compress interpretation timelines. Long-term viability rests on recurring revenue attachment rates rather than per-unit hardware margins. Monitor FDA algorithm classification guidance for veterinary diagnostic software as the inflection signal determining whether AI-assisted workflows trigger additional premarket scrutiny or accelerate commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Cloud-native image sharing unlocks subscription revenue beyond hardware margins for field veterinarians. |
| CMUT Array Manufacturing Scale-Up | Silicon-fabricated transducers displace legacy ceramic substrates in tendon imaging applications. |
| EU MDR Quality System Investment | Direct service capabilities replace third-party dealer models for Article 10 post-market surveillance compliance. |
| Brazilian Regulatory Fast-Track | ANVISA streamlined pathways accelerate penetration in 230-million-head beef operations. |
| AI Diagnostic Software Certification | FDA Center for Veterinary Medicine algorithm classification determines premarket scrutiny requirements. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, USDA APHIS regulatory guidance, EU MDR technical documentation, and NMPA veterinary device registrations. Interviews with veterinary clinic owners, biomedical engineering directors at multi-site chains, semiconductor procurement leads at transducer manufacturers, and regulatory affairs specialists at imaging OEMs informed demand and supply-side assessments. Bottom-up unit shipment estimates triangulate against top-down expenditure analysis across the four product categories.
Segmentation dimensions modeled include product mobility tier, end-user clinical setting, technology modality, and application across species types. CAGRs derive from fitted growth curves applied to historical procurement patterns and projected insurance penetration trajectories. Forecast inputs incorporate semiconductor cost curves for piezoelectric substrates and CMUT arrays, plus regulatory timeline assumptions for AI-enabled diagnostic software classifications.
Decision-makers should treat outputs as directional under assumptions of stable FDA-USDA regulatory alignment and continued semiconductor fabrication capacity expansion; material deviation in export control regimes or algorithm classification stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sputum Ejection Machine Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Injection Pen Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
US Stethoscope Market
Medical Devices
Depression Devices Market
Medical Devices
India Minimally Invasive Surgery Devices Market