
 Chile Respiratory Devices Market | 2026-2036
Chile Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Respiratory Devices Market Outlook
Buyer concentration across Chile's home care segment is expanding as patients transition from hospital-based treatment to monitored domestic therapy. ResMed Inc. leverages its cloud-connected CPAP platforms to capture recurring revenue from remote patient management. Fisher & Paykel Healthcare Ltd anchors the acute care channel through humidification systems integrated into ventilator circuits. Koninklijke Philips NV competes across both institutional and home settings with portable oxygen concentrator lines.
Respiratory devices encompass mechanical apparatus designed to assist, control, or supplement pulmonary ventilation through positive or negative pressure delivery, typically incorporating flow sensors, humidification chambers, and alarm systems operating at respiratory rates between 6 and 150 breaths per minute. These systems serve critical therapeutic functions for patients with compromised gas exchange, chronic obstruction, or acute respiratory failure across hospital and ambulatory environments. Ventilators command the highest capital investment per unit and dominate replacement cycles in Chile's public hospital procurement. Home care settings represent the fastest-expanding end user channel as reimbursement frameworks extend coverage for domiciliary oxygen and sleep apnea therapy. Positive pressure technology leads installed base volume while high-frequency ventilation occupies the premium critical care tier with concentrated margin pools.
ISP, Chile's national pharmaceutical regulator, mandates pre-market registration and clinical evidence submission for all Class II and III respiratory devices, extending approval timelines and favoring established suppliers with dedicated regulatory affairs capacity. The Ministry of Health's HTA unit evaluates cost-effectiveness for public sector procurement, directing hospital purchasing toward devices with demonstrated outcomes in COPD and acute respiratory distress syndrome applications. Stakeholders must monitor whether ISP aligns its technical standards with MERCOSUR harmonization initiatives or maintains country-specific requirements that fragment market access protocols.
Market Dynamics
Cloud-connected respiratory platforms are compressing service delivery timelines across Chile's home care segment, forcing incumbents to reconfigure revenue models around remote patient monitoring rather than discrete device sales.
Growth Catalysts
- ISP registration pathways:The national pharmaceutical regulator's structured pre-market review process rewards manufacturers with established clinical dossiers, accelerating approval timelines for Class II humidification systems.
- Metropolitan hospital network expansion:Santiago's public procurement clusters are consolidating ventilator purchases through centralized Ministry of Health tenders, creating volume incentives for multi-unit suppliers.
- Telemonitoring infrastructure:Cellular-enabled CPAP devices are capturing patient adherence data streams that justify extended reimbursement codes for domiciliary sleep apnea therapy.
Market Restraints
- Import dependency for sensors:Flow transducers and pressure valves concentrate in East Asian manufacturing hubs, exposing Chilean distributors to ocean freight volatility and extended lead times.
- ISP technical standards divergence:Country-specific electromagnetic compatibility testing requirements fragment product registration efforts, delaying market entry for manufacturers pursuing MERCOSUR harmonization.
- Limited domestic technical service capacity:Biomedical engineering specialization in ventilator calibration remains concentrated in Santiago, constraining maintenance response times for regional hospital networks.
Strategic Opportunities
- Valparaíso regional home care penetration:Secondary coastal cities exhibit underdeveloped oxygen concentrator distribution networks relative to patient prevalence rates for COPD.
- High-frequency ventilation in private critical care:Premium ICU segments in Santiago's private clinic clusters show capacity for advanced oscillatory systems addressing acute respiratory distress syndrome.
- ISP-MERCOSUR alignment negotiations:Pending regulatory harmonization discussions could streamline technical documentation requirements across Southern Cone markets.
Industry Challenges
- Biomedical technician certification bottlenecks:ISP-mandated service personnel qualifications for Class III ventilator maintenance outpace training program output.
- Legacy device integration complexity:Hospital networks operating mixed fleets of pneumatic and electronic ventilator platforms face interoperability barriers with centralized monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Respiratory Devices Market |
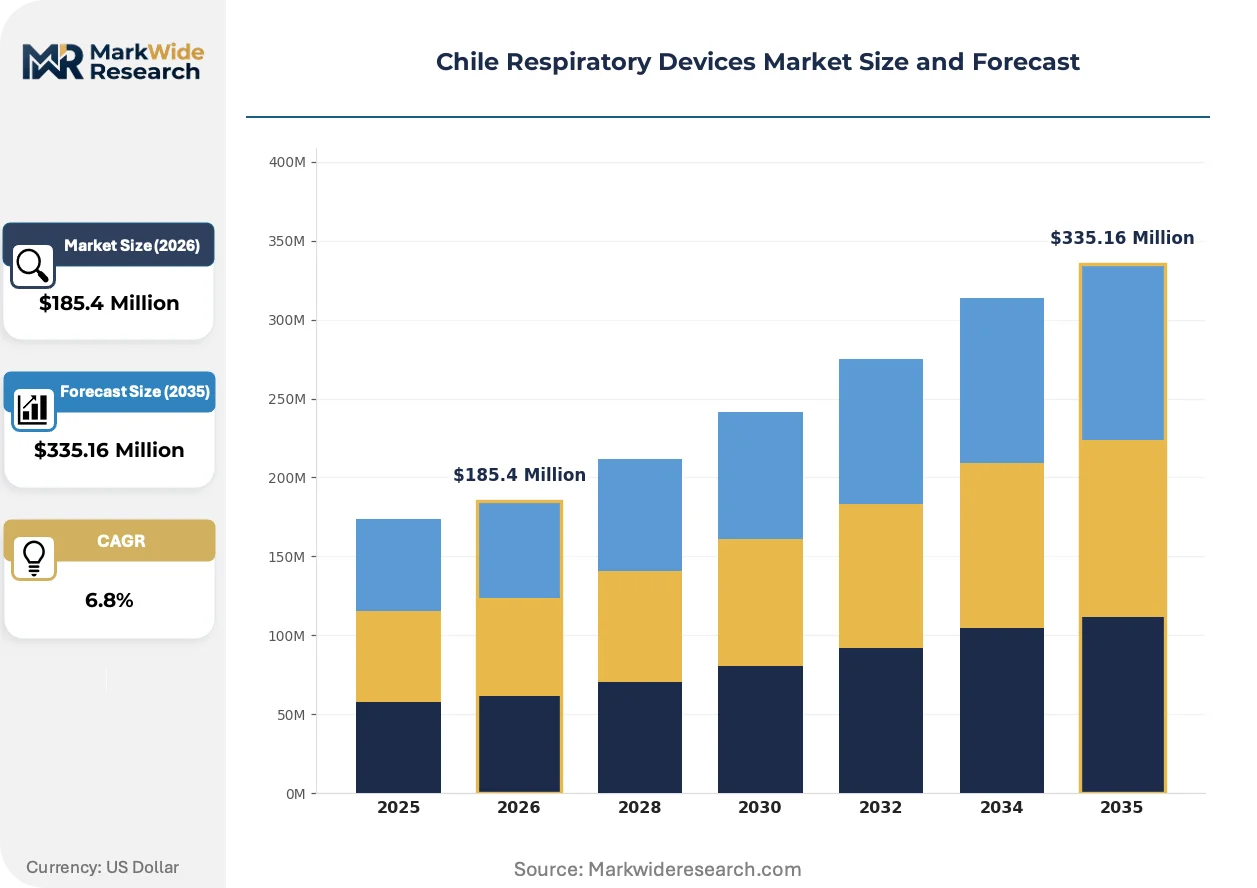
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Nebulizers, CPAP Machines, Oxygen Concentrators End User: Hospitals, Home Care Settings, Clinics, Long-Term Care Facilities Technology: Mechanical Ventilation, High-Frequency Ventilation, Positive Pressure, Negative Pressure Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Acute Respiratory Distress Syndrome |
| Companies Covered | Dragerwerk AG, GE Healthcare, Koninklijke Philips NV, Medtronic PLC, Fisher & Paykel Healthcare Ltd, GlaxoSmithKline PLC, Invacare Corporation, ResMed Inc., Hamilton Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Respiratory Devices Market Strategic Shifts
Respiratory device architectures are converging around sensor fusion and connectivity layers that transform standalone therapeutic equipment into data-generating nodes within integrated care networks.
Cloud-native CPAP platforms are integrating pulse oximetry and airflow pressure sensors into unified data streams for remote titration adjustments. Chilean sleep clinics are adopting these systems to reduce in-laboratory polysomnography backlogs. The technology is integrating patient-generated health data into insurer risk assessment frameworks, compressing prior authorization timelines for therapy initiation.
ISP's technical standards for electromagnetic compatibility are tightening testing protocols for wireless-enabled respiratory devices. Manufacturers must now submit additional documentation on 2.4 GHz band interference mitigation. Private clinic procurement committees are responding by prioritizing devices with pre-certified modular architectures that simplify registration amendments.
Hospital purchasing committees are unbundling device acquisition from multi-year service contracts, forcing manufacturers to compete on discrete price points for ventilator hardware. Santiago's public hospital network is piloting performance-based maintenance agreements where technician response times determine contract renewal. This behavioral shift concentrates supplier selection authority within centralized biomedical engineering departments rather than distributed clinical units.
Chile Respiratory Devices Market Segmentation
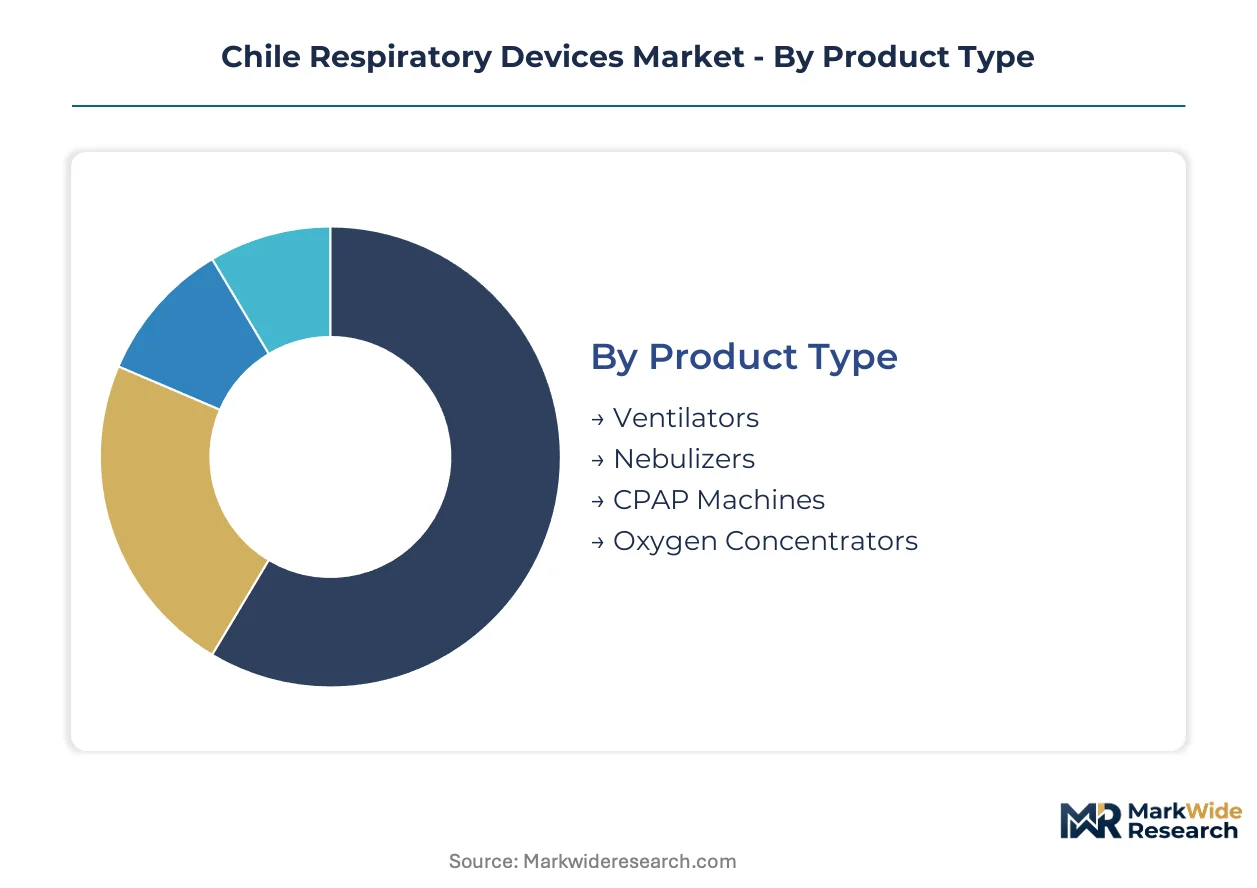
Respiratory device procurement patterns in Chile diverge sharply across clinical settings and therapeutic applications. Understanding these segment boundaries clarifies where capital deployment concentrates and where reimbursement frameworks create expansion corridors.
Product Type:
Ventilators demand the heaviest upfront capital commitment, with ICU-grade units requiring dedicated infrastructure and biomedical engineering support that smaller product categories avoid.
- Ventilators:Electromechanical systems delivering controlled tidal volumes through positive pressure circuits, incorporating microprocessor-driven flow sensors and alarm modules. Santiago's public hospital network concentrates replacement demand as centralized Ministry tenders consolidate procurement authority.
- CPAP Machines:Continuous positive airway pressure devices with blower motors, humidification chambers, and cellular connectivity modules for remote adherence monitoring. Home care settings in Chile's metropolitan regions absorb volume growth as ISP extends reimbursement codes for domiciliary sleep apnea therapy.
- Nebulizers:Compressor-driven or ultrasonic aerosol delivery systems for bronchodilator administration.
- Oxygen Concentrators:Pressure swing adsorption units generating medical-grade oxygen from ambient air.
Most installed capacity flows through Ventilators. Expansion is steepest in CPAP Machines.
End User:
Customer type determines service intensity requirements and procurement authority distribution across Chile's healthcare infrastructure.
- Hospitals:Acute care institutions operating centralized biomedical engineering departments with ISP-mandated maintenance certifications for Class III devices. Santiago's metropolitan clusters dominate capital expenditure as consolidated tenders replace fragmented purchasing.
- Home Care Settings:Domiciliary environments where patients or family members operate devices with remote clinical oversight. Chile's aging demographic and ISP reimbursement expansion for portable oxygen and sleep therapy accelerate channel growth.
- Clinics:Outpatient facilities with intermediate acuity requirements and limited on-site technical service capacity.
- Long-Term Care Facilities:Residential institutions managing chronic respiratory conditions with nursing support but variable biomedical technician availability.
Procurement volume concentrates in Hospitals. Home Care Settings are climbing the fastest.
Technology:
Engineering complexity and clinical application scope vary substantially across pressure delivery modalities.
- Mechanical Ventilation:Conventional positive pressure systems operating at respiratory rates of 6-40 breaths per minute with volume or pressure control modes. Chile's public ICU infrastructure depends on this installed base for COPD exacerbation and post-surgical recovery.
- High-Frequency Ventilation:Oscillatory systems delivering small tidal volumes at frequencies exceeding 150 breaths per minute. Santiago's private critical care clusters represent the primary addressable market for these premium platforms in acute respiratory distress syndrome management.
- Positive Pressure:Broad category encompassing non-invasive and invasive delivery modes.
- Negative Pressure:Iron lung and cuirass systems for select neuromuscular applications.
Mechanical Ventilation dominates current installed base. High-Frequency Ventilation is gaining share fastest in premium segments.
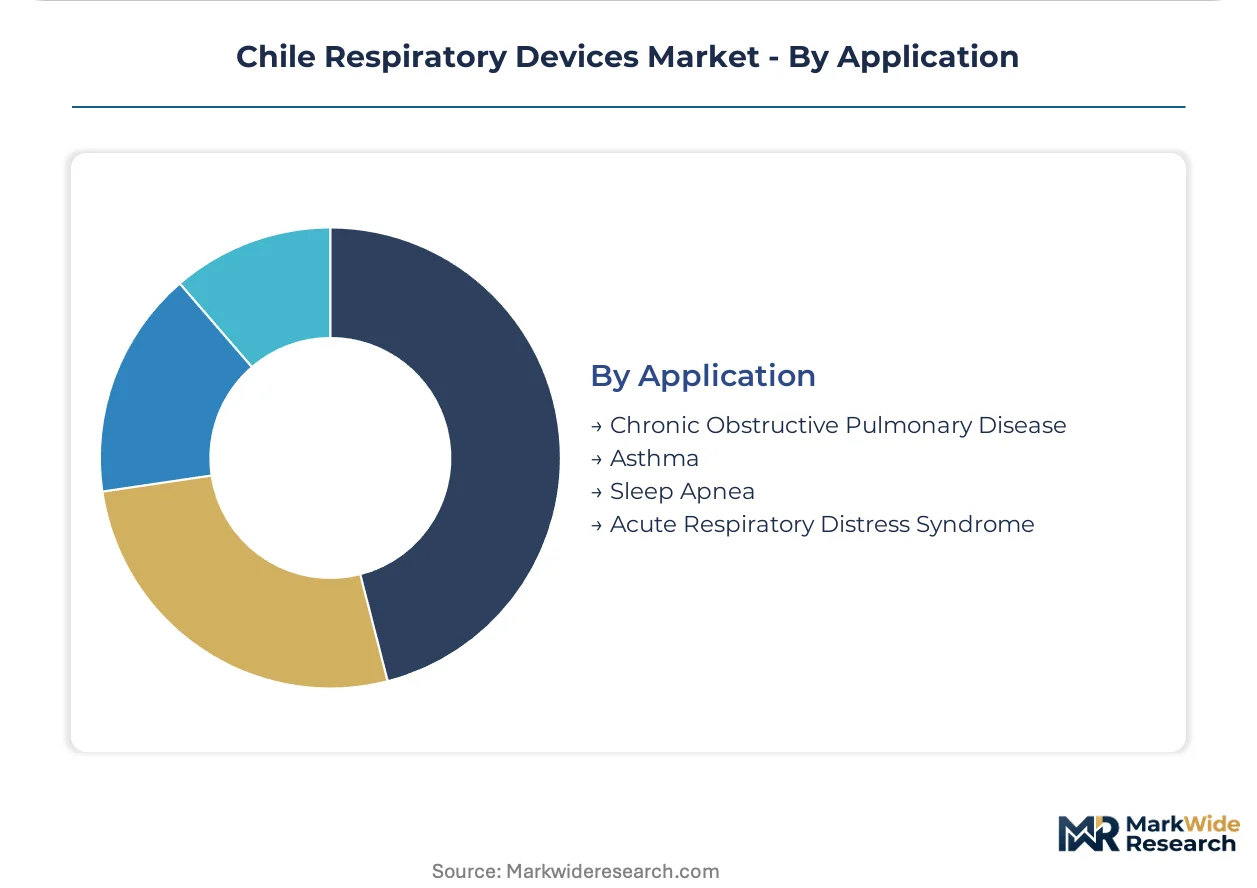
Application:
Disease prevalence and reimbursement eligibility shape demand concentration across therapeutic indications.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring long-term oxygen therapy and acute exacerbation management. Chile's Ministry of Health HTA unit directs public procurement toward devices with demonstrated outcomes in COPD applications.
- Sleep Apnea:Obstructive and central sleep-disordered breathing requiring nightly positive pressure intervention. ISP reimbursement framework extensions for domiciliary CPAP therapy concentrate demand growth in metropolitan home care networks.
- Asthma:Reversible airway obstruction managed primarily through pharmacotherapy with device support for severe cases.
- Acute Respiratory Distress Syndrome:Life-threatening pulmonary inflammation requiring ICU-level mechanical ventilation.
Patient volume flows heaviest through Chronic Obstructive Pulmonary Disease. Sleep Apnea shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's respiratory device infrastructure diverges from Argentina's fragmented procurement landscape through centralized Ministry of Health tenders and stricter ISP registration protocols. Neighboring markets present contrasting regulatory maturity and channel development patterns.
Argentina
Provincial health ministries operate decentralized purchasing for ventilator fleets, creating inconsistent technical specifications across jurisdictions. ANMAT registration timelines for Class III devices extend approval cycles, favoring manufacturers with established Buenos Aires distributor networks. The metropolitan hospital cluster concentrates demand for acute care systems.
Brazil
ANVISA's harmonization with MERCOSUR technical standards accelerates cross-border registration for manufacturers holding Chilean ISP approvals. São Paulo's private hospital networks drive premium ventilator demand while public SUS procurement emphasizes cost containment. The southeastern industrial corridor hosts regional distribution hubs serving southern cone markets.
Colombia
INVIMA's risk-based classification system for medical devices creates registration pathway parallels with Chile's ISP framework. Bogotá's tertiary hospital network concentrates high-frequency ventilation acquisitions for critical care expansion. Caribbean coastal cities exhibit underdeveloped home oxygen distribution relative to COPD prevalence.
Peru
DIGEMID's strengthening post-market surveillance requirements mirror Chile's ISP technical standards evolution. Lima's public hospital consolidation through EsSalud tenders compresses supplier margins while accelerating volume commitments. Andean regional networks face biomedical technician scarcity for ventilator maintenance.
Mexico
COFEPRIS alignment with FDA recognition agreements offers pathway efficiencies for manufacturers holding US approvals. Mexico City metropolitan hospitals anchor demand for portable oxygen concentrators amid expanding domiciliary reimbursement. Northern border states leverage maquiladora infrastructure for component sourcing.
Chile Respiratory Devices Market Competitive Environment
European producers anchor one tier; Asia-Pacific specialists hold component supply positions. The vendor base concentrates around established respiratory multinationals with dedicated regulatory affairs capacity for ISP navigation. Three archetypes dominate: integrated critical care platform suppliers, cloud-connected home therapy specialists, and regional distribution-focused device aggregators. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Within the integrated platform tier, Dragerwerk AG and Hamilton Medical exemplify European engineering-led positioning. ResMed Inc. and Fisher & Paykel Healthcare Ltd occupy distinct connectivity-focused and humidification-specialist archetypes respectively. Koninklijke Philips NV represents the diversified health technology conglomerate model spanning institutional and ambulatory channels.
| Leading Market Players |
|---|
| Dragerwerk AG |
| GE Healthcare |
| Koninklijke Philips NV |
| Medtronic PLC |
| Fisher & Paykel Healthcare Ltd |
| GlaxoSmithKline PLC |
| Invacare Corporation |
| ResMed Inc. |
| Hamilton Medical |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineering specialization concentrated in Santiago generates labor-cost differentials that widen pricing-tier spreads between premium ICU ventilators and standard home care devices across Chile's respiratory device market. ISP-mandated technician certifications for Class III device maintenance inflate service-contract premiums, compressing margins on economy-tier oxygen concentrators while sustaining pricing power in high-frequency ventilation systems.
Pricing Analysis
Capacity additions in East Asian sensor manufacturing hubs are reshaping price floors for flow transducers and pressure valves, transmitting cost volatility through Chilean distributor networks. Three-tier pricing structure across premium, standard, and economy levels separates ISP-certified Class III ventilators from Class II humidification systems and unbranded nebulizer imports. Price differentiation hinges on electromagnetic compatibility certification grade and after-sales service bundling. Cost compression in economy-tier concentrators is intensifying because ocean freight volatility erodes landed cost advantages. Home care patients exhibit highest price sensitivity; private ICU procurement committees demonstrate lowest.
Supply Chain Analysis
Ocean freight volatility from East Asian manufacturing hubs exposes Chilean distributors to extended lead times and working capital pressure for critical sensor components. Flow transducers, pressure valves, and microprocessor modules draw from China, South Korea, and Taiwan manufacturing concentrations. Raw material dependencies span medical-grade aluminum for ventilator housings, semiconductor-grade silicon for sensor substrates, and specialized polymers for humidification chambers. Single-source vulnerability concentrates in pneumatic valve assemblies. Distribution runs through Santiago-based authorized distributors with regional hospital service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
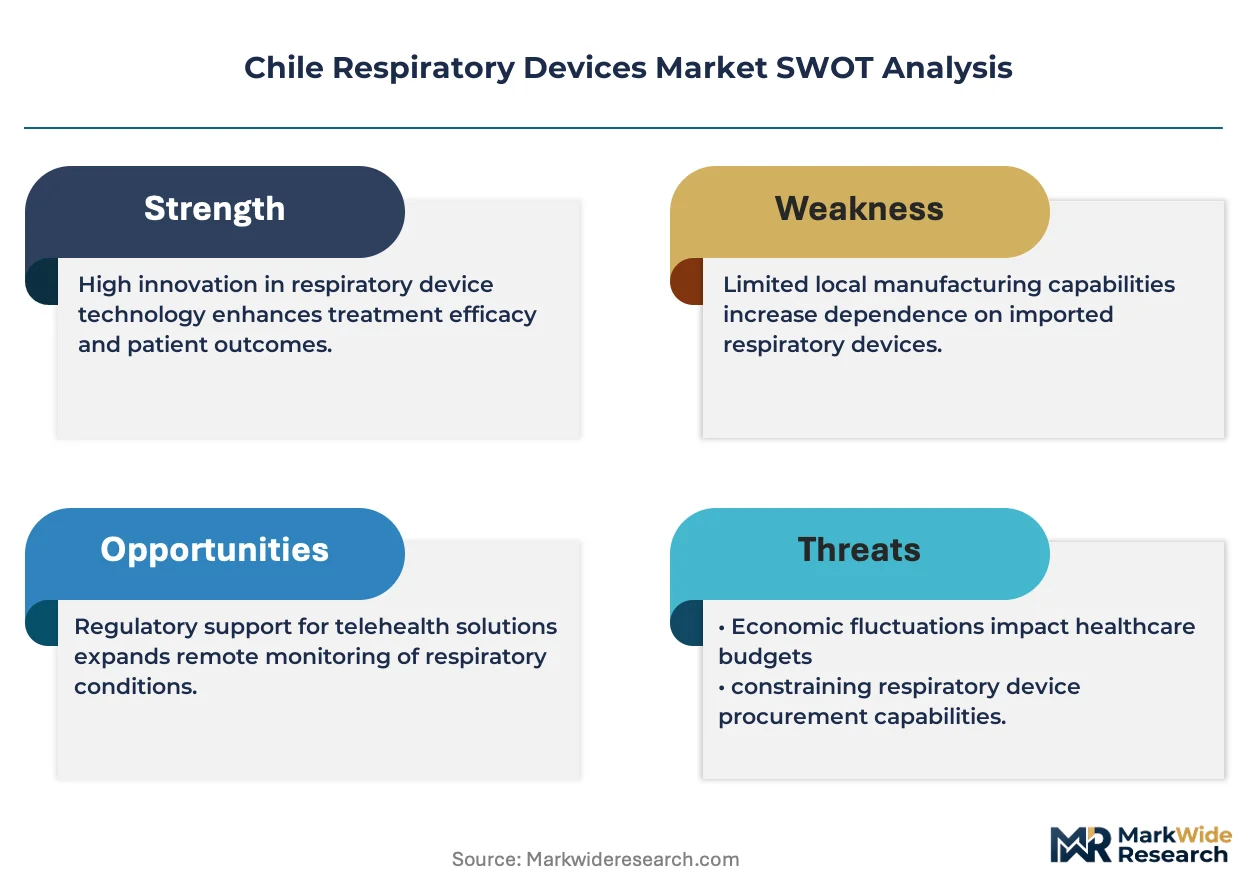
Chile's respiratory device market operates as a regulatory compounder where ISP reimbursement framework extensions for domiciliary therapy create demand acceleration corridors. The Ministry of Health's HTA unit cost-effectiveness mandates concentrate procurement authority toward outcome-demonstrated platforms.
For Market Incumbents: Deepen cloud-connected platform integration to capture recurring revenue from remote patient monitoring subscriptions, insulating against hardware price erosion. Fortify biomedical technician training partnerships with Santiago universities to address ISP-mandated certification bottlenecks. Anchor defensive positioning through exclusive service contracts with consolidated public hospital tenders.
For New Entrants and Emerging Players: Regional distributor networks in Valparaíso and secondary coastal cities represent the most penetrable channel infrastructure for oxygen concentrator market entry. Target underdeveloped home care penetration in COPD-prevalent zones outside Santiago metropolitan clusters. Pursue ISP registration pathway partnerships with established clinical dossier holders to compress approval timelines.
For Investors and Strategic Acquirers: Integrated health technology conglomerates are the most active acquirer in this space, seeking connectivity-enabled home therapy platforms. Five-to-ten year viability centers on reimbursement expansion sustainability and MERCOSUR harmonization execution. Monitor ISP-MERCOSUR alignment negotiation progress as inflection indicator for cross-border registration efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| ISP Registration Pathway Investment | Accelerated Class II device approvals reward established clinical dossier capacity. |
| Cloud-Connected Platform Development | Cellular-enabled CPAP devices capture recurring revenue from remote adherence monitoring. |
| Biomedical Technician Training Partnership | Santiago university alliances address ISP-mandated Class III maintenance certification gaps. |
| Valparaíso Regional Distribution Expansion | Secondary coastal cities exhibit oxygen concentrator network underdevelopment relative to COPD prevalence. |
| High-Frequency Ventilation ICU Partnership | Santiago private clinic clusters show capacity for premium oscillatory system adoption. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, ISP regulatory affairs specialists, and home care distributor principals anchored qualitative grounding for this analysis. Secondary validation drew from ISP registration databases, Ministry of Health HTA unit procurement records, GPO contract repositories, and MERCOSUR technical harmonization documentation. Bottom-up installed base estimates triangulated against top-down reimbursement expenditure flows.
Bottom-up modeling segmented volume and value across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from trend extrapolation of ISP reimbursement code expansions, metropolitan hospital tender consolidation patterns, and home care demographic shift velocities. Industry-specific inputs incorporated COPD prevalence trajectories and sleep apnea diagnostic rate acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ISP-MERCOSUR harmonization timing and ocean freight cost normalization. Forecasts reflect documented assumptions on reimbursement continuity and regulatory pathway stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Cranial Clamps Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
Light Therapy Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Automated Compounding Systems Market