
 Hip Shield Market | 2026-2036
Hip Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Shield Market Foresight
Hospital procurement is rebalancing toward senior care facilities and home health agencies as acute-care spending flattens. AliMed leverages its established distribution through long-term care supply chains to sustain volume leadership in North American institutional accounts. Tytex A/S anchors its position with European-certified textile-integrated shields that navigate CE marking and MDR compliance requirements. HipSaver competes through product specialization in low-profile garments designed for ambulatory patients who resist traditional bulky pads.
A hip shield is a wearable protective garment engineered to dissipate kinetic energy from lateral falls and reduce femoral neck fracture risk, typically constructed from viscoelastic foam layers bonded to polyethylene shells or ballistic nylon covers with moisture-wicking interfaces. The primary commercial purpose centers on preventing hip fractures in populations with compromised bone density, where a single fracture event triggers cascading healthcare costs and mortality escalation. Wearable shields and protective pads together occupy the dominant revenue position, though harness systems represent the fastest-growing configuration as post-surgical protocols expand their use beyond fall prevention into active rehabilitation. Senior care facilities command the largest end-user share, while home patients constitute the margin-accretive segment due to lower price sensitivity and direct-to-consumer channel premiums.
FDA clearance pathways for Class I medical device garments shape product development timelines and labeling claims in the United States, while the EU MDR and CE marking requirements impose clinical evidence standards that filter out lower-tier suppliers in Europe. Japan's PMDA and METI coordinate standards for elderly care equipment that align with public long-term care insurance reimbursement schedules. Stakeholders must monitor how evolving fall-prevention protocols in reimbursement systems determine whether hip shields remain classified as durable medical equipment or shift toward wellness apparel categories with divergent margin structures.
Market Dynamics
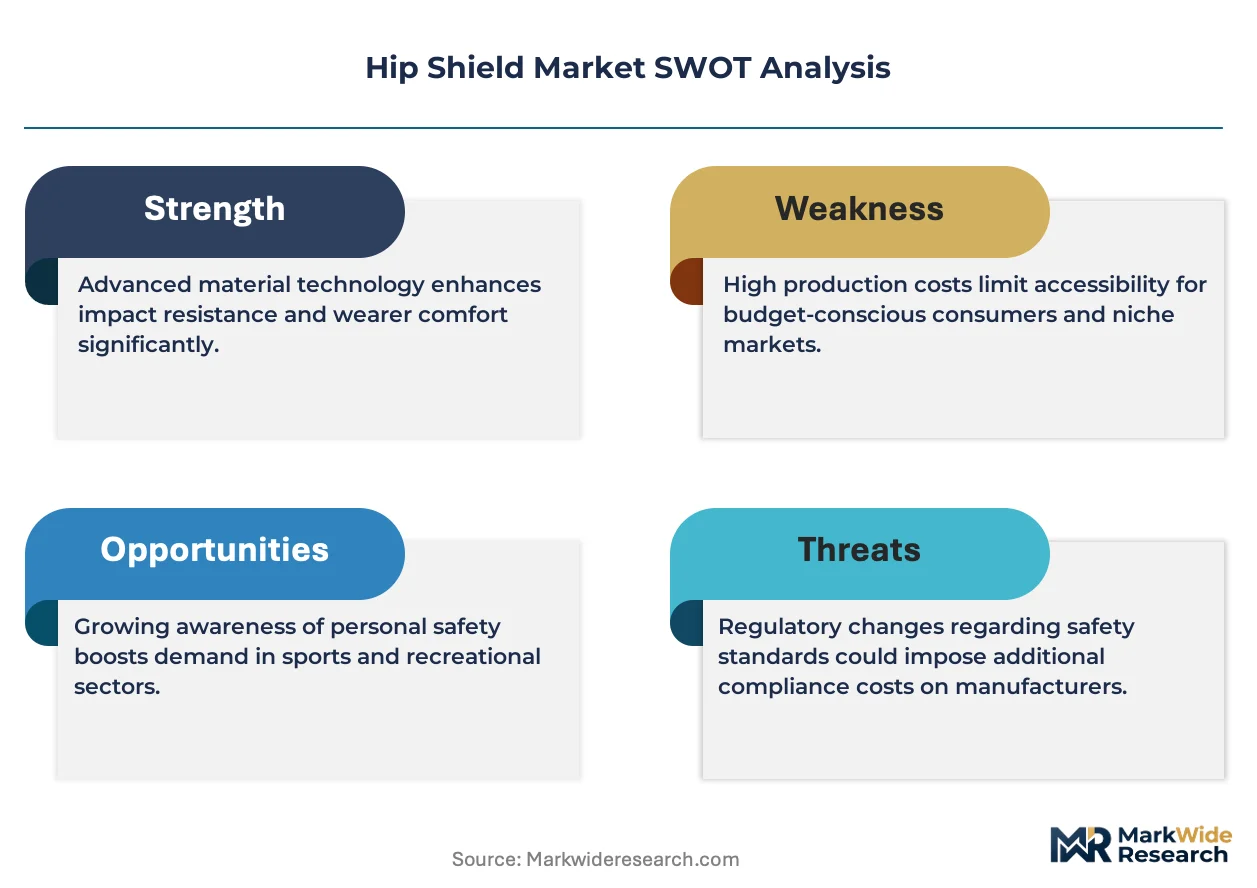
Hospital procurement departments are redirecting capital toward senior care facilities as acute-care spending flattens, while foam-polyethylene composite designs displace single-material pads in clinical fall-prevention protocols. This reallocation concentrates purchasing power in long-term care supply chains.
Growth Catalysts
- MDR compliance requirements:The EU Medical Device Regulation imposes clinical evidence standards that filter out lower-tier suppliers, consolidating volume among certified textile-integrated shield manufacturers in European institutional accounts.
- Japan's long-term care insurance:METI and PMDA coordinated standards for elderly care equipment align with public reimbursement schedules, expanding insured access to wearable hip protectors in home health settings.
- Viscoelastic foam bonding:Advances in multi-layer energy dissipation materials enable thinner garment profiles that reduce patient resistance and extend wear-time compliance in ambulatory populations.
Market Restraints
- Polyethylene resin volatility:Input cost fluctuations for shell materials compress margins on economy-tier shields and deter price-sensitive home health procurement.
- East Asian manufacturing concentration:Ballistic nylon cover and moisture-wicking interface production clusters in specific supplier geographies expose buyers to logistics disruption and tariff exposure.
- FDA Class I labeling constraints:Clearance pathways for medical device garments restrict marketing claims to mechanical protection, preventing positioning against wellness apparel competitors in direct-to-consumer channels.
Strategic Opportunities
- Home health agency channel:Lower price sensitivity among direct-to-consumer buyers supports premium positioning for low-profile garments outside institutional purchasing contracts.
- Harness system rehabilitation:Post-surgical protocols are expanding hip shield use from fall prevention into active mobility rehabilitation, opening orthopedic clinic and physical therapy distribution.
- Reimbursement recategorization:Shifting classification from durable medical equipment toward preventive wellness apparel in select jurisdictions would unlock retail margin structures and reduce procurement cycle friction.
Industry Challenges
- Biomechanical testing expertise:Validating energy dissipation performance across body mass indices and fall angles requires specialized laboratory capacity that constrains product line expansion timelines.
- Legacy garment integration:Moisture-wicking interfaces must interface with existing institutional laundering protocols without degrading viscoelastic foam properties, complicating hospital adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Shield Market |
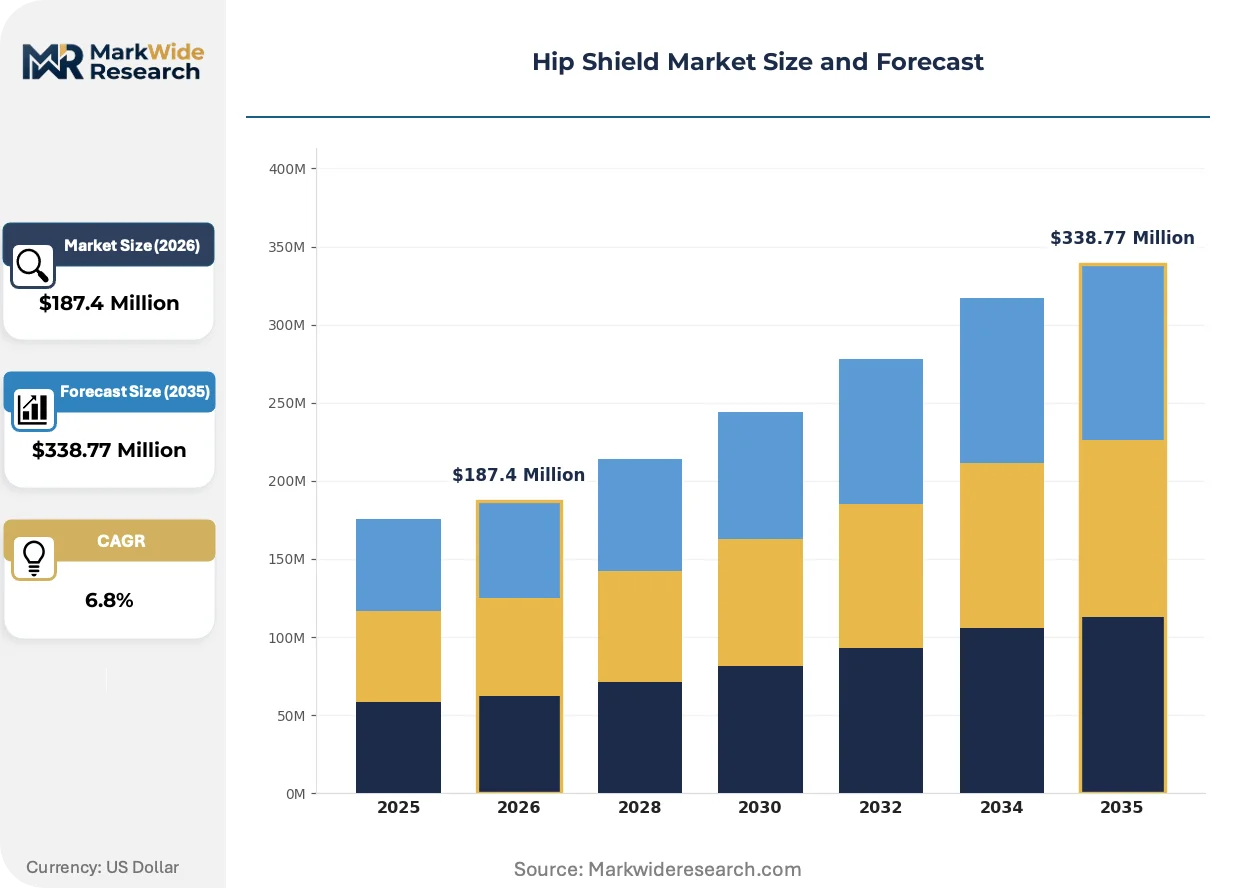
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Shields, Protective Pads, Harness Systems, Impact Vests End User: Senior Care Facilities, Home Patients, Athletes, Rehabilitation Centers Material: Polyethylene, Foam, Ballistic Nylon, Carbon Fiber Application: Fall Prevention, Sports Safety, Post-Surgery Support, Daily Living Activities |
| Companies Covered | AliMed, Tytex A/S, HipSaver, Medline Industries, Posey Company, Pelican Manufacturing, ComfiHips, Promedics, Impactwear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Shield Market Shifts & Advancements
Material science convergence with textile engineering is compressing shield profiles while maintaining impact absorption. These developments are reshaping competitive positioning around patient compliance and clinical integration rather than raw protection metrics.
Shear-thickening fluid liners are integrating with traditional foam-polyethylene sandwiches to create adaptive stiffness that responds to impact velocity. Senior care facilities in Germany and Japan are piloting these hybrid garments for high-fall-risk residents. The technology is integrating fall protection with thermal comfort, eliminating the bulk that previously drove non-compliance among ambulatory patients.
CE marking under the EU MDR now requires clinical evidence for hip shield efficacy claims, elevating documentation burdens for new entrants. European textile-integrated shield manufacturers are responding by sponsoring prospective fracture-reduction studies in nursing home populations. This regulatory tightening is compressing the supplier base to firms with sustained R&D budgets and institutional trial access.
Direct-to-consumer channels are capturing margin-accretive home patient segments that bypass group purchasing organization contracting. Specialty medical supply retailers and orthopedic clinic dispensaries are displacing traditional durable medical equipment distributors for premium garment sales. This channel rotation is most visible in United States metropolitan markets where aging-in-place demographics concentrate and long-term care insurance penetration supports out-of-pocket shield purchases.
Hip Shield Market Segmentation
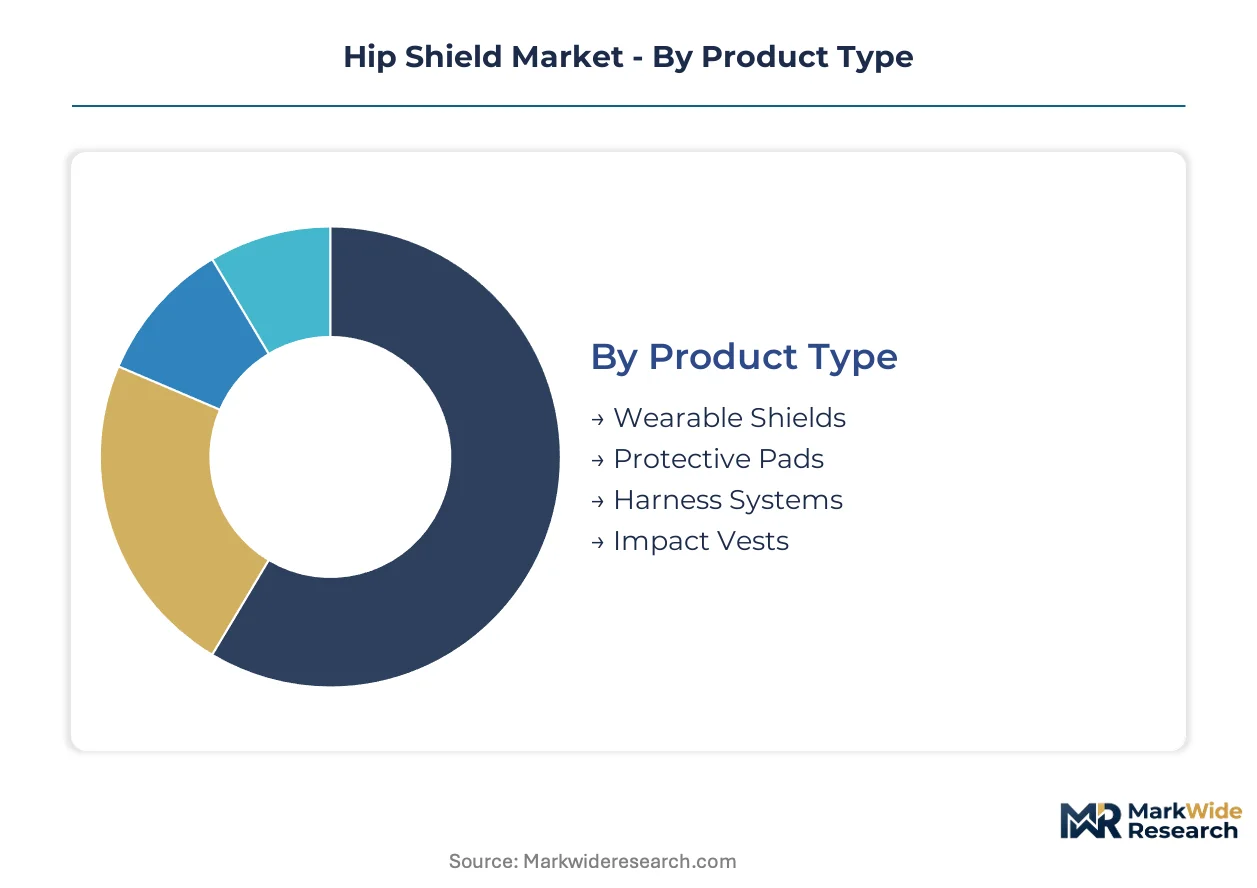
Hip shield procurement patterns diverge sharply between institutional buyers optimizing for laundering durability and home patients prioritizing garment discretion. Segmentation reveals how material choices and product configurations align with distinct fall-risk profiles across care settings.
Product Type:
Upgrade cycles accelerate as foam-polyethylene composites displace legacy single-material pads in clinical procurement protocols.
- Wearable Shields:Textile-integrated garments with viscoelastic foam layers bonded to polyethylene shells dominate senior care facility purchasing in the United States and Germany. Moisture-wicking interfaces extend wear-time compliance among ambulatory patients who resist bulkier alternatives.
- Protective Pads:Removable pad inserts designed for institutional laundering protocols command volume leadership through long-term care supply chains. CE marking and MDR compliance requirements filter lower-tier suppliers, consolidating procurement among certified manufacturers in European accounts.
- Harness Systems:Post-surgical protocols expand these configurations beyond fall prevention into active rehabilitation, opening orthopedic clinic distribution.
- Impact Vests:Full-torso protection garments serve athletes and high-mobility seniors requiring broader impact coverage.
Volume placements concentrate in Wearable Shields; the faster expansion belongs to Harness Systems.
End User:
Customer type determines margin structure, with direct-to-consumer channels capturing premium pricing outside group purchasing organization contracting.
- Senior Care Facilities:Institutional buyers command the largest procurement volume through long-term care supply chains. FDA Class I labeling constraints and laundering protocol compatibility drive vendor selection criteria in North American accounts.
- Home Patients:Lower price sensitivity supports premium positioning for low-profile garments, with specialty medical supply retailers displacing traditional durable medical equipment distributors in metropolitan markets.
- Athletes:Equestrian and contact sports participants generate demand for high-performance impact protection with thermal comfort features.
- Rehabilitation Centers:Post-acute facilities integrate hip shields into mobility protocols following orthopedic surgery.
Procurement volume clusters in Senior Care Facilities; margin accretion concentrates in Home Patients.
Material:
Supply concentration for cover fabrics and shell resins shapes regional manufacturing footprints and tariff exposure.
- Polyethylene:Shell material input cost volatility compresses margins on economy-tier shields and deters price-sensitive home health procurement. East Asian manufacturing concentration exposes buyers to logistics disruption.
- Foam:Viscoelastic formulations enable thinner garment profiles that reduce patient resistance and extend wear-time compliance. Multi-layer energy dissipation advances drive clinical preference in German and Japanese pilot programs.
- Ballistic Nylon:Cover production clusters in specific supplier geographies, creating tariff exposure for North American and European garment assemblers.
- Carbon Fiber:Ultra-lightweight shells serve high-performance athletic applications with premium pricing tiers.
Volume procurement favors Foam-Polyethylene composites; Carbon Fiber commands the steepest expansion trajectory in specialty segments.
Application:
Reimbursement recategorization risk shifts classification boundaries between durable medical equipment and wellness apparel.
- Fall Prevention:Core clinical indication driving institutional procurement in the United States, Germany, and Japan where aging demographics and reimbursement codes for fracture prevention gear overlap.
- Sports Safety:Equestrian and contact sports applications demand adaptive stiffness responding to impact velocity, with shear-thickening fluid liners gaining traction.
- Post-Surgery Support:Orthopedic protocols expand hip shield use into active mobility rehabilitation, creating physical therapy channel opportunities.
- Daily Living Activities:Aging-in-place demographics support out-of-pocket purchases where long-term care insurance penetration enables direct-to-consumer sales.
Fall Prevention anchors institutional volume; Post-Surgery Support is expanding most quickly through rehabilitation channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's special economic zones for elderly care equipment concentrate hip shield manufacturing and distribution incentives around Osaka and Nagoya, accelerating regional supply chain formation.
United States
Medicare Advantage plans in Florida and Arizona are expanding supplemental benefits for fall-prevention devices. FDA Class I medical device pathways govern clearance timelines for wearable protective garments. Minneapolis-based long-term care supply chains are consolidating procurement through group purchasing organizations.
Germany
Public health insurance funds in Bavaria and North Rhine-Westphalia reimburse certified hip protectors under fracture prevention protocols. EU MDR clinical evidence requirements filter supplier bases to established textile-integrated shield manufacturers. Stuttgart's medical textile cluster hosts CE marking consultancy services for garment compliance.
Japan
Metropolitan Tokyo and Osaka prefectures deploy wearable hip protectors through long-term care insurance tiered benefit schedules. METI and PMDA coordinate elderly care equipment standards with municipal procurement guidelines. Nagoya's industrial belt manufactures viscoelastic foam layers for domestic shield producers.
United Kingdom
NHS Integrated Care Boards in Greater Manchester and West Midlands pilot fall-prevention garment programs for high-risk elderly populations. MHRA regulations align with EU MDR transitional provisions for textile medical devices. Yorkshire's technical textile sector supplies moisture-wicking interface fabrics to shield assemblers.
Hip Shield Market Competitive Landscape
Top-tier vendors anchor institutional procurement channels, while mid-tier specialists compete through product differentiation and regional certification advantages. The supplier base stratifies across three tiers: established durable medical equipment distributors with long-term care supply chain penetration, textile-integrated shield specialists with European regulatory compliance capabilities, and low-profile garment innovators targeting direct-to-consumer ambulatory segments. Dominant competitive moves include strategic partnerships with senior care facility networks and portfolio diversification into harness system configurations for rehabilitation markets.
Among North American institutional suppliers, AliMed and HipSaver exemplify divergent archetypes within the competitive set. AliMed occupies a position representing established durable medical equipment distribution scale, while HipSaver exemplifies specialization in low-profile garment design for patient compliance. Tytex A/S anchors the European-certified textile-integrated tier, representing compliance-forward positioning under MDR requirements. These three entities collectively illustrate how geographic regulatory environments and channel focus determine competitive positioning.
| Leading Market Players |
|---|
| AliMed |
| Tytex A/S |
| HipSaver |
| Medline Industries |
| Posey Company |
| Pelican Manufacturing |
| ComfiHips |
| Promedics |
| Impactwear |
| Others |
Supply & Pricing Matrix
Captive production of viscoelastic foam layers in Nagoya and Osaka anchors both supply security and pricing power for Japanese domestic shield manufacturers, insulating them from polyethylene resin volatility that compresses margins elsewhere. This backward integration into core energy-dissipation materials enables premium positioning in METI-coordinated procurement channels while forcing non-integrated assemblers toward spot-market material sourcing.
Pricing Analysis
Short lead-time premiums command substantial markups in institutional procurement cycles where senior care facilities face regulatory compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked textile-integrated garments from FDA Class I cleared devices and unregistered wellness apparel. Pricing pressure stems from East Asian resin volatility compressing margins on economy-tier shields. Home patients exhibit lowest price sensitivity, while group purchasing organization contracting drives acute cost consciousness in senior care facility procurement.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Stuttgart, and Osaka operate hub-and-spoke patterns feeding long-term care supply chains. Manufacturing concentrates in China for ballistic nylon covers, Japan for viscoelastic foam formulations, and Germany for CE-marked textile assembly. Raw material dependencies include polyethylene resin, shear-thickening fluid compounds, and moisture-wicking technical fabrics. Tariff exposure on East Asian cover materials creates supply chain risk for North American garment assemblers. Distribution runs through durable medical equipment distributors, specialty medical supply retailers, and direct-to-consumer orthopedic clinic dispensaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into foam formulation and textile weaving capabilities has become the decisive competitive race, with players securing captive supply of viscoelastic layers and moisture-wicking interfaces to defend margin structure against resin volatility.
For Market Incumbents: To counter polyethylene resin volatility and tariff exposure on East Asian cover materials, AliMed and Tytex A/S should deepen backward integration into domestic foam production and nearshore textile weaving capacity. Certification investment in EU MDR clinical evidence standards filters lower-tier competitors and consolidates procurement power among compliant manufacturers. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most penetrable route for low-profile garment specialists targeting home patient segments in United States metropolitan markets where aging-in-place demographics concentrate. Specialty medical supply e-commerce platforms and orthopedic clinic telehealth partnerships provide white-space entry points outside group purchasing organization contracting. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by durable medical equipment distributors seeking textile-integrated shield capabilities and rehabilitation channel access. Long-term viability favors manufacturers with sustained R&D budgets for shear-thickening fluid liner development and institutional trial sponsorship capacity. The signal to watch is reimbursement recategorization from durable medical equipment toward wellness apparel in select jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter supplier bases to certified textile-integrated shield manufacturers. |
| Backward Integration into Foam Production | Captive viscoelastic formulation capacity insulates margins from polyethylene resin spot-market volatility. |
| Hospital System Partnership | Long-term care supply chain penetration through group purchasing organization contracts anchors volume placement. |
| Reimbursement Strategy | Classification shift from durable medical equipment toward wellness apparel unlocks retail margin structures. |
| Software Companion Development | Fall-risk monitoring integration with hip shield garments creates physical therapy channel differentiation. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification trajectories, and Japanese long-term care insurance reimbursement schedules anchored the trend analysis, supplemented by interviews with hospital procurement managers, senior care facility administrators, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA device classification databases, CE marking registries, METI elderly care equipment standards, hospital procurement databases, and CMS Medicare durable medical equipment claims data. Bottom-up demand modeling triangulated against top-down market sizing across institutional and direct-to-consumer channels.
Input-output matrix framing connected raw material flow assumptions through foam formulation, textile assembly, and garment distribution stages to end-user demand segments. Segmentation dimensions modeled include product configuration, end-user archetype, material composition, and application indication across the projection horizon. CAGRs were derived from regression analysis of historical procurement volume trends and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated aging demographic trajectories and reimbursement code evolution in United States, German, and Japanese markets.
The model holds under stable regulatory classification and reimbursement schedule continuity; deviation in FDA device reclassification or EU MDR enforcement intensity would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
GCC Adult Diaper Market