
 Ablation Devices Market | 2026-2036
Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ablation Devices Market Analysis
A shortage of board-certified electrophysiologists is redrawing competitive dynamics in catheter ablation. Medtronic leverages its integrated mapping and ablation platform to secure long-term contracts with academic medical centers. Boston Scientific Corporation anchors its position through sustained investment in pulsed field ablation research pipelines.
Ablation devices are instruments that apply thermal, electrical, or mechanical energy to destroy pathological tissue through controlled cellular necrosis, typically operating at temperatures between 50°C and 100°C for thermal modalities or at cryogenic ranges below -40°C for tissue freezing. These systems serve primarily to treat cardiac arrhythmias, solid tumors, and chronic pain conditions through minimally invasive access routes. Radiofrequency systems occupy the largest installed base across electrophysiology labs, while cryoablation segments command premium pricing in atrial fibrillation procedures due to superior safety profiles. Microwave ablation competes aggressively in interventional oncology, where liver and lung tumor applications drive replacement cycles.
FDA breakthrough device designation and CE marking under the EU MDR create divergent compliance burdens for manufacturers seeking parallel market entry. The EPA regulates fluorinated gas emissions from cryoablation systems, adding sustainability reporting requirements to product lifecycle management. Stakeholders must monitor evolving reimbursement codes for pulsed field ablation as payors evaluate procedure cost-effectiveness against radiofrequency standards.
Market Dynamics
Pulsed field ablation is compressing procedure times and expanding treatable patient populations beyond traditional thermal energy limits, forcing electrophysiology suite operators to reconfigure capital allocation toward next-generation platforms.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated clearance pathways compress time-to-market for novel ablation modalities, incentivizing R&D investment in cardiac electrophysiology platforms.
- Catheter-based arrhythmia treatment:Minimally invasive procedures displace long-term pharmaceutical management in hospital systems, expanding addressable procedure volumes across integrated delivery networks.
- Atrial fibrillation prevalence:Aging demographics in developed healthcare systems generate sustained demand for rhythm control interventions beyond pharmacological options.
Market Restraints
- Electrophysiologist supply concentration:Board-certified specialist shortages in the United States create procedural bottlenecks that constrain volume expansion regardless of device availability.
- Cryogenic gas input volatility:Fluorinated gas supply disruptions and EPA emissions reporting requirements add operational complexity and cost uncertainty to cryoablation system operators.
- Reimbursement code lag:CMS and commercial payor evaluation timelines for pulsed field ablation procedures create adoption friction against established radiofrequency standards.
Strategic Opportunities
- Outpatient migration:Ambulatory surgical centers in the United States seek compact, single-use catheter platforms that reduce capital footprint and sterilization overhead.
- Interventional oncology expansion:Microwave ablation systems penetrate liver and lung tumor applications where thermal penetration depth requirements exceed radiofrequency capabilities.
- EU MDR compliance leverage:CE marking under strengthened European device regulations creates competitive moats for manufacturers with established quality management systems.
Industry Challenges
- Electrophysiology lab capex cycles:Integrated mapping and ablation platform upgrades require multi-million dollar capital commitments that strain hospital system budgets.
- Cross-modality training requirements:Physician certification for pulsed field ablation demands additional proctored cases beyond existing radiofrequency or cryoablation credentials.
- Legacy system integration:New catheter technologies must interface with installed base mapping workstations, creating software compatibility and data workflow complications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ablation Devices Market |
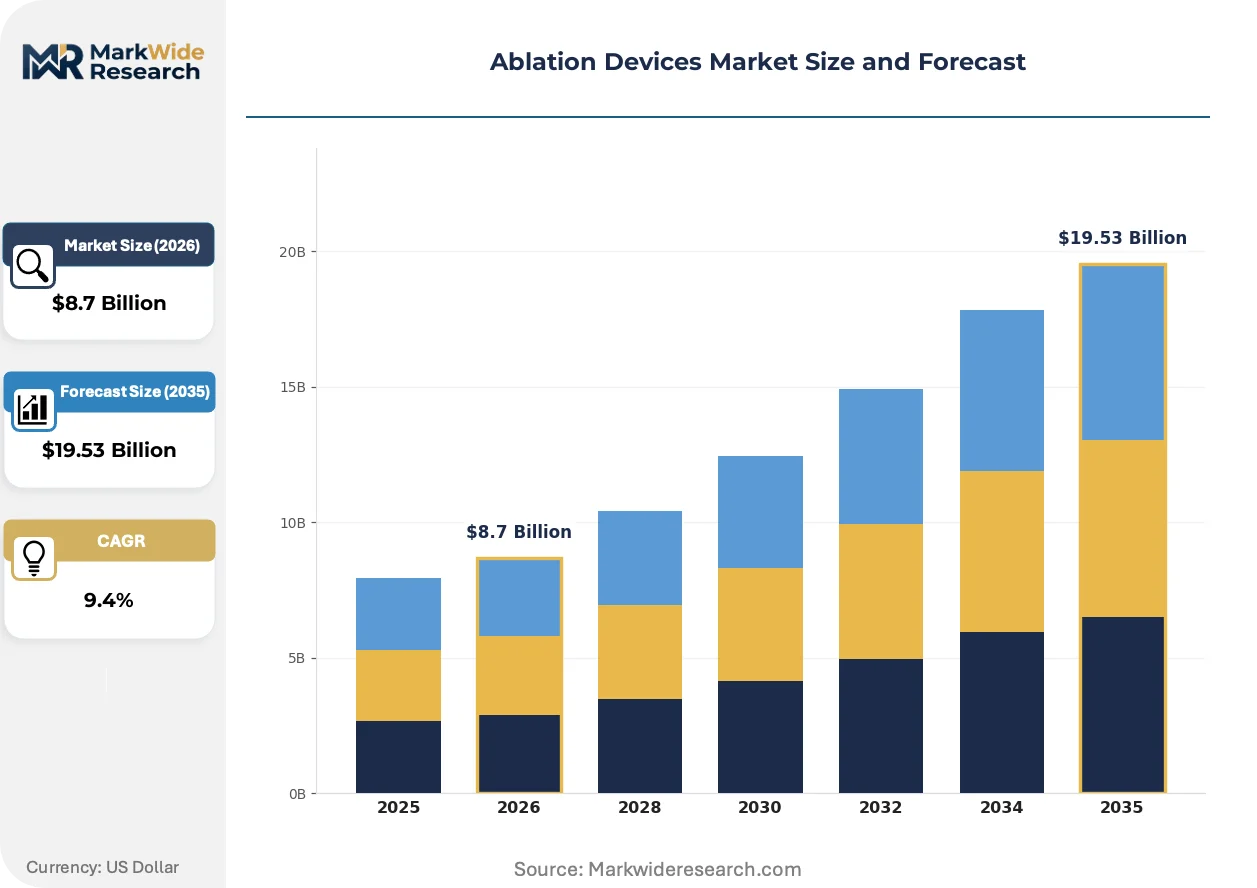
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Laser, Cryoablation, Microwave Application: Pain Management, Oncology, Cardiovascular, Gynecology End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Laboratories Technology: Electrosurgical Systems, Imaging Systems, Navigation Systems, Energy Delivery Systems |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Abbott, AtriCure, Stryker, Smith & Nephew, AngioDynamics, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ablation Devices Market Emerging Trajectories
Energy delivery mechanisms and procedural workflows are converging toward precision targeting and reduced collateral tissue damage, reshaping competitive differentiation in electrophysiology and interventional oncology segments.
High-density electrode arrays with integrated micro-sensors are miniaturizing mapping resolution to sub-millimeter scales. Academic medical centers in the United States deploy these platforms for complex atrial substrate ablation. The technology is miniaturizing hardware footprints while expanding real-time electrogram acquisition channels, compressing the distinction between diagnostic mapping and therapeutic delivery phases.
EPA fluorinated gas regulations under the AIM Act mandate phasedown of hydrofluorocarbon emissions from medical device applications. Cryoablation system manufacturers face reformulation requirements for balloon inflation gases and enhanced recovery equipment installation. European operators confront parallel pressure through the EU F-Gas Regulation, accelerating research into alternative cooling chemistries and closed-loop gas recycling architectures.
Hospital procurement committees increasingly unbundle electrophysiology suite contracts, separating mapping system subscriptions from disposable catheter supply agreements. Integrated delivery networks in the United States negotiate multi-year disposable commitments independent of capital equipment vendors. This pattern concentrates purchasing leverage among high-volume centers while fragmenting vendor relationships across academic and community hospital tiers.
Ablation Devices Market Segmentation
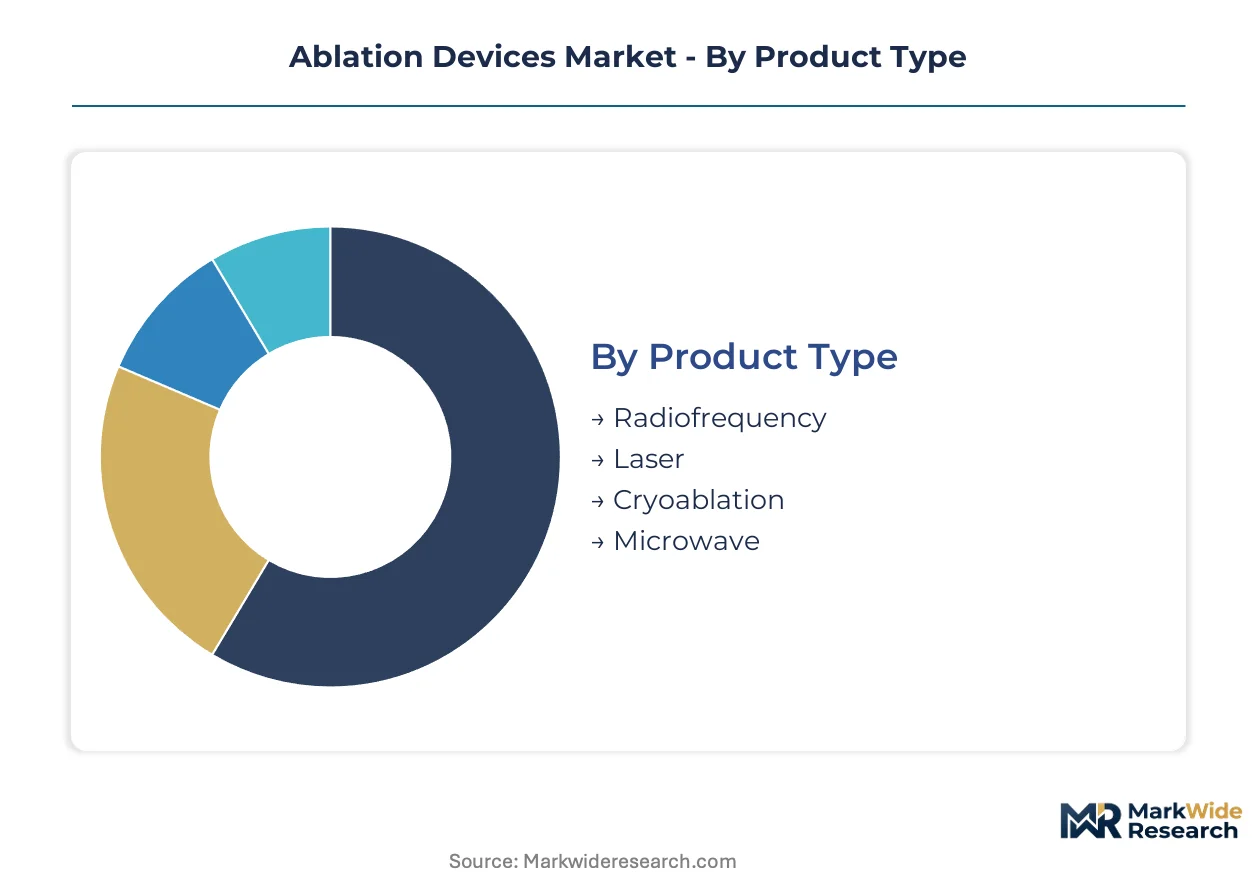
Ablation device purchasing patterns diverge sharply across clinical settings and energy modalities. Hospital procurement committees weigh capital intensity against procedure throughput, while outpatient migration reshapes disposable catheter specifications.
Product Type:
Radiofrequency and cryoablation systems anchor domestic demand in the United States, while microwave platforms find stronger export traction in interventional oncology markets across Germany and Japan.
- Radiofrequency:Thermal energy delivery through resistive heating at 460-480 kHz dominates cardiac electrophysiology suites. United States hospital systems prioritize integrated mapping compatibility over standalone cost, driving consolidation around multi-electrode catheter platforms.
- Cryoablation:Balloon-based tissue freezing using nitrous oxide or refrigerant gases commands premium positioning in atrial fibrillation workflows. European operators under EU F-Gas Regulation pressure accelerate adoption despite fluorinated gas compliance costs.
- Laser:Photocoagulation systems target retinal and dermatological applications with precise wavelength control.
- Microwave:Electromagnetic field ablation at 915 MHz or 2.45 GHz penetrates deeper tissue volumes for hepatic and pulmonary tumor indications.
Radiofrequency holds the largest share; momentum sits with cryoablation as safety profiles reshape physician preference.
Application:
Cardiovascular and pain management applications concentrate procedure volume in high-acuity hospital settings, while oncology applications expand through ambulatory surgical center networks seeking same-day discharge protocols.
- Cardiovascular:Catheter-based arrhythmia treatment encompasses atrial fibrillation, ventricular tachycardia, and supraventricular tachycardia substrates. United States electrophysiology labs drive replacement cycles as pulsed field modalities displace thermal energy platforms.
- Oncology:Percutaneous tumor ablation targets liver, lung, renal, and bone metastases through image-guided access. Japanese and German interventional radiology departments favor microwave systems for lesions exceeding three centimeters in diameter.
- Pain Management:Radiofrequency neurotomy addresses facet joint and sacroiliac dysfunction in spine care settings.
- Gynecology:Endometrial ablation systems treat abnormal uterine bleeding through hysteroscopic or global cavity approaches.
Cardiovascular generates the highest revenue intensity; oncology is climbing the fastest as cancer center construction accelerates.
End User:
Capital equipment procurement concentrates among academic medical centers with electrophysiology fellowship programs, while disposable catheter demand fragments across community hospital tiers and freestanding surgical facilities.
- Hospitals:Integrated delivery networks negotiate bundled contracts spanning mapping workstations, ablation generators, and multi-year disposable commitments. Cleveland Clinic and Mayo Clinic anchor volume through high-complexity substrate ablation referrals.
- Ambulatory Surgery Centers:Medicare reimbursement expansion for outpatient cardiac ablation drives demand for compact, single-use platforms. Texas and Florida certificate-of-need exemptions accelerate ASC facility licensing.
- Specialty Clinics:Pain management and gynecology-focused operators prioritize lower-capital radiofrequency systems.
- Research Laboratories:Academic investigators evaluate next-generation energy modalities through FDA investigational device exemption protocols.
Hospitals retain the dominant installed base; ambulatory surgery centers are gaining share fastest as site-of-service economics shift.
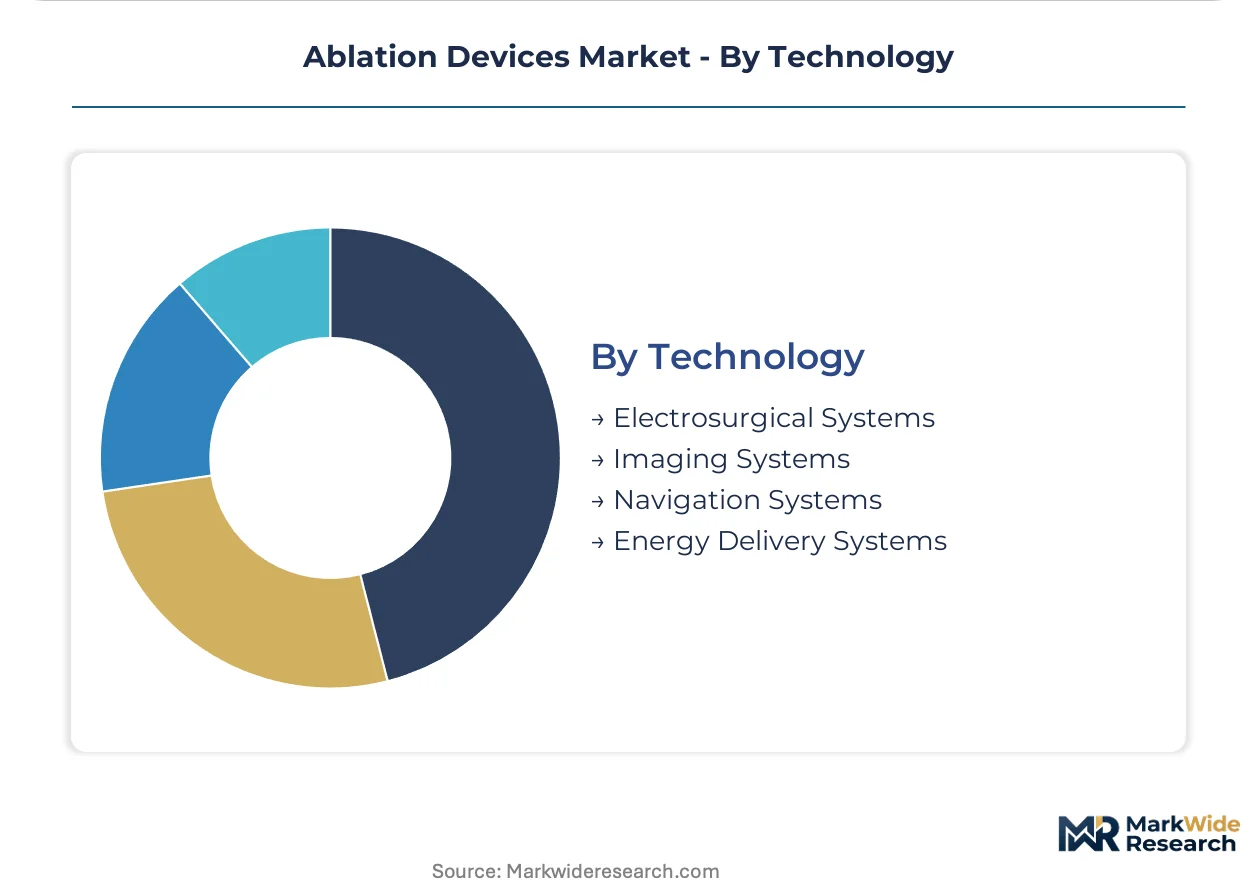
Technology:
Energy delivery and navigation system integration determines competitive positioning, with imaging modality choices varying by clinical application and reimbursement environment.
- Energy Delivery Systems:Generator hardware and catheter interfaces govern power modulation, temperature monitoring, and impedance feedback. Pulsed field ablation platforms require redesigned electrical architectures incompatible with legacy radiofrequency generators.
- Navigation Systems:Electromagnetic and impedance-based tracking enables catheter localization within three-dimensional cardiac maps. Stereotaxis robotic magnetic navigation retains niche positioning in complex pediatric cases.
- Imaging Systems:Intracardiac echocardiography and fluoroscopy guidance support transseptal access and lesion monitoring.
- Electrosurgical Systems:General surgical ablation units serve gynecological and soft tissue applications outside electrophysiology.
Energy delivery systems command the highest R&D investment; navigation systems are expanding most quickly as precision targeting reduces fluoroscopy exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems deploy ablation devices predominantly for cardiac electrophysiology, while German and Japanese operators concentrate capacity in interventional oncology applications. This consumption-mix differential reflects divergent reimbursement architectures and specialist training pipelines across developed healthcare markets.
United States
Integrated delivery networks in Texas and Florida drive outpatient migration of cardiac ablation procedures to ambulatory surgical centers. FDA breakthrough device designation pathways accelerate pulsed field ablation platform approvals, compressing commercialization timelines. The Cleveland Clinic and Mayo Clinic anchor high-complexity substrate ablation referral volumes in Ohio and Minnesota.
Germany
Interventional radiology departments in Munich and Heidelberg favor microwave systems for hepatic and pulmonary tumor indications exceeding three centimeters. EU F-Gas Regulation compliance costs pressure cryoablation operators to adopt closed-loop gas recycling architectures. The Baden-Württemberg medical technology cluster around Stuttgart hosts precision catheter manufacturing supply chains.
Japan
Tokyo and Osaka cancer centers expand percutaneous tumor ablation capacity through same-day discharge protocols. PMDA regulatory timelines for novel energy modalities remain conservative relative to FDA pathways, delaying pulsed field platform entry. METI industrial policy supports domestic electrosurgical generator production in the Chubu region.
United Kingdom
NHS England procurement frameworks unbundle electrophysiology suite contracts, separating mapping system subscriptions from disposable catheter supply agreements. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance burdens for manufacturers. The Oxford-Cambridge-London golden triangle concentrates academic research into next-generation ablation energy delivery.
China
Tier-one hospitals in Beijing and Shanghai deploy radiofrequency systems for atrial fibrillation volume expansion. NMPA regulatory pathways for imported catheter platforms require domestic clinical trial data, extending time-to-market for multinational manufacturers. The Yangtze River Delta medical device manufacturing base supplies cost-competitive generator hardware to Southeast Asian export markets.
Ablation Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the ablation devices market. The upper tier commands bundled contract negotiations with academic medical centers and integrated delivery networks. The specialist tier competes through modality-specific innovation in pulsed field, microwave, or cryogenic energy delivery. Two dominant competitive moves define current positioning: strategic partnerships with mapping system vendors to ensure software compatibility, and geographic expansion into ambulatory surgical center networks seeking compact disposable platforms.
Within the integrated leader tier, Medtronic and Boston Scientific Corporation exemplify full-platform strategies spanning mapping, navigation, and energy delivery systems. Abbott occupies a position bridging cardiac rhythm management and electrophysiology ablation portfolios. These three companies represent divergent responses to the pulsed field transition—some anchoring through sustained R&D commitment, others through acquisition of emerging technology developers.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Abbott |
| AtriCure |
| Stryker |
| Smith & Nephew |
| AngioDynamics |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough device designation and parallel EU MDR conformity assessment create dual gating mechanisms that simultaneously filter supplier qualification and stratify price positioning across electrophysiology suites. These certification regimes concentrate purchasing leverage among integrated delivery networks that can absorb compliance overhead while fragmenting vendor access for smaller hospital systems.
Pricing Analysis
Long-term bundled contracts dominate electrophysiology suite procurement, with integrated delivery networks negotiating multi-year disposable commitments separate from capital equipment subscriptions. Price differentiation rests on mapping system compatibility and proctoring support depth, with academic medical centers least sensitive due to fellowship training subsidies. Cost compression in radiofrequency catheter tiers intensifies as pulsed field platforms capture premium positioning. Community hospitals exhibit highest price sensitivity, driving demand for compact single-use platforms with reduced sterilization overhead.
Supply Chain Analysis
Strategic stockpiling of fluorinated gases characterizes cryoablation system operators facing EPA phasedown mandates and EU F-Gas Regulation supply uncertainty. Component manufacturing concentrates in the United States, Germany, and Japan, with precision catheter fabrication anchored in Baden-Württemberg and the Minneapolis medical technology corridor. Raw material dependencies span nitrous oxide refrigerants, platinum-iridium electrode alloys, and specialized polymer balloon substrates. Single-source vulnerability in fluorinated gas supply chains elevates operational risk. Distribution runs through GPO contracts and direct hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment and physician training switching costs protect incumbent positions against disruptive energy modalities.
For Market Incumbents: Compound mapping platform stickiness through software companion development that locks electrophysiology labs into integrated workflow ecosystems. Deepen backward integration into precision catheter manufacturing to defend margin position against disposable commoditization pressure. Prioritize pulsed field ablation certification investment ahead of reimbursement code finalization to capture first-mover physician training relationships. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable entry pathway for novel energy delivery architectures. Target ambulatory surgical center networks in Texas and Florida certificate-of-need exemption zones where compact platform demand outstrips incumbent supply flexibility. Pursue hospital system partnership models that unbundle mapping subscriptions from disposable supply agreements. For Investors and Strategic Acquirers: CMS reimbursement code finalization for pulsed field ablation reshapes the acquisition landscape toward platforms with established proctored case volumes. Long-term viability centers on electrophysiologist training pipeline control rather than device hardware differentiation alone. Monitor FDA 510(k) clearance velocity for microwave ablation oncology extensions as the inflection signal for interventional radiology platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated clearance compresses commercialization timelines for pulsed field platforms against thermal legacy systems. |
| CE Marking Under EU MDR | Strengthened conformity requirements create competitive moats for manufacturers with established quality management infrastructure. |
| Hospital System Partnership | Bundled contract negotiation with Cleveland Clinic and Mayo Clinic anchors high-complexity substrate ablation referral volumes. |
| Software Companion Development | Mapping workstation integration locks electrophysiology labs into proprietary data workflow ecosystems. |
| Reimbursement Strategy | CMS code establishment for outpatient cardiac ablation drives ambulatory surgical center site-of-service migration. |
Methodological Framework
Cross-validation between electrophysiologist interviews and hospital procurement database analysis anchors the qualitative findings on catheter purchasing patterns. Primary fieldwork encompassed biomedical engineers, GPO contracts managers, and EP lab directors across academic and community hospital tiers. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement data, and EU MDR notified body certification records. Bottom-up procedure volume estimates triangulate against top-down generator installed base assessments.
Sensitivity analysis tested forecast robustness across electrophysiologist supply shortage severity and pulsed field reimbursement lag scenarios. The modeling framework segments by energy modality, clinical application, end-user setting, and geographic regulatory cluster. CAGRs derive from procedure volume elasticity to aging demographic penetration and capital equipment replacement cycle timing. Cryogenic gas price volatility and EPA compliance cost trajectories feed into cryoablation segment projections.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough designation throughput assumptions or electrophysiology fellowship expansion rates would require recalibration. Forecasts reflect documented assumptions regarding pulsed field physician training pipeline development. Revision becomes warranted when CMS reimbursement code finalization timelines deviate materially from modeled pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Intravaginal Device Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Light Therapy Beauty Devices Market