
 US Bathroom and Toilet Assist Devices Market | 2026-2036
US Bathroom and Toilet Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Bathroom and Toilet Assist Devices Market Analytics
Aluminum is shifting from premium-positioned grab bars toward mid-tier toilet seat lifts as fabricators seek weight reduction without sacrificing load ratings above 250 pounds. Drive Medical leverages vertical integration across its plastic molding and assembly operations to protect margin pools in portable commodes. Invacare Corporation anchors its position through durable medical equipment dealer networks that control shelf placement in independent pharmacies. Etac AB differentiates via Scandinavian design protocols that emphasize corrosion-resistant stainless steel finishes for wet-environment longevity.
Bathroom and toilet assist devices encompass mechanically or electrically actuated products that support safe transfer, positioning, and personal hygiene for users with limited mobility, typically fabricated from injection-molded polymers, extruded aluminum tubing, or 304-grade stainless steel and tested to ADA grab bar bend strength standards of 250 lbf. These products serve residential retrofit, acute care discharge planning, and long-term skilled nursing applications where fall prevention drives procurement specifications. Toilet seat lifts command expanding margin pools as powered variants with lithium battery packs displace manual hydraulic units in Medicare Advantage reimbursement channels. Grab bars remain the volume foundation but face commoditization pressure from imported stainless steel variants sold through online retail platforms. Aids for personal hygiene represent the fastest-growing product class as bidet attachments and cleansing sprays penetrate senior living construction specifications.
The FDA regulates powered toilet seat lifts as Class I medical devices under 510(k) exempt status, while the Department of Justice enforces ADA Title III accessibility standards that mandate grab bar placement in public and commercial restrooms, directly shaping renovation demand cycles. CMS reimbursement schedules through Medicare Part B and state Medicaid waiver programs determine out-of-pocket exposure for homebound seniors, creating state-by-state demand variation tied to HCBS funding levels. Stakeholders must monitor pending CMS rulemaking on in-home accessibility equipment preauthorization requirements that could reshape distributor inventory strategies and direct-to-consumer channel economics.
Market Dynamics
Medicare Advantage reimbursement channels are compressing product lifecycles by favoring powered toilet seat lifts over manual hydraulic units, forcing fabricators to retool assembly lines toward lithium battery integration and smart sensor calibration.
Growth Catalysts
- ADA Title III retrofit mandates:The Department of Justice enforces accessibility standards that require grab bar placement in commercial restrooms, directly accelerating renovation cycles across retail, hospitality, and healthcare facilities.
- Florida senior population concentration:Demographic clustering in the Sun Belt states generates localized demand spikes for home healthcare agencies expanding procurement of assistive bathing equipment.
- Lithium battery power systems:Electrification of toilet seat lifts enables longer operational cycles between charges, expanding Medicare Advantage coverage eligibility and reducing caregiver intervention frequency.
Market Restraints
- Aluminum price volatility:Extruded tubing costs fluctuate with energy-intensive smelting operations, squeezing margin pools for mid-tier toilet seat lift fabricators competing on weight reduction.
- Import commoditization pressure:Stainless steel grab bars from offshore suppliers flood online retail platforms, eroding price discipline among domestic distributors serving independent pharmacies.
- 510(k) exempt status limitations:FDA Class I classification for powered lifts restricts clinical evidence requirements, creating reimbursement uncertainty when Medicare Advantage plans demand outcomes documentation.
Strategic Opportunities
- Texas Medicaid waiver expansion:Home and Community-Based Services funding increases create reimbursement pathways for bidet attachments and cleansing sprays in senior living construction specifications.
- Arizona assisted living construction:New facility development in Phoenix and Tucson metro areas specifies corrosion-resistant wet-environment equipment, favoring fabricators with 304-grade stainless steel protocols.
- Direct-to-consumer channel maturation:E-commerce platforms bypass durable medical equipment dealer networks, capturing margin previously allocated to shelf placement fees in independent retail.
Industry Challenges
- ADA bend strength testing capacity:Third-party laboratories face backlogs validating 250 lbf load ratings, delaying product launches and inventory positioning for seasonal retrofit demand windows.
- Caregiver training standardization:Inconsistent protocols across home healthcare agencies for powered lift operation create liability exposure and product return rates that erode channel economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bathroom and Toilet Assist Devices Market |
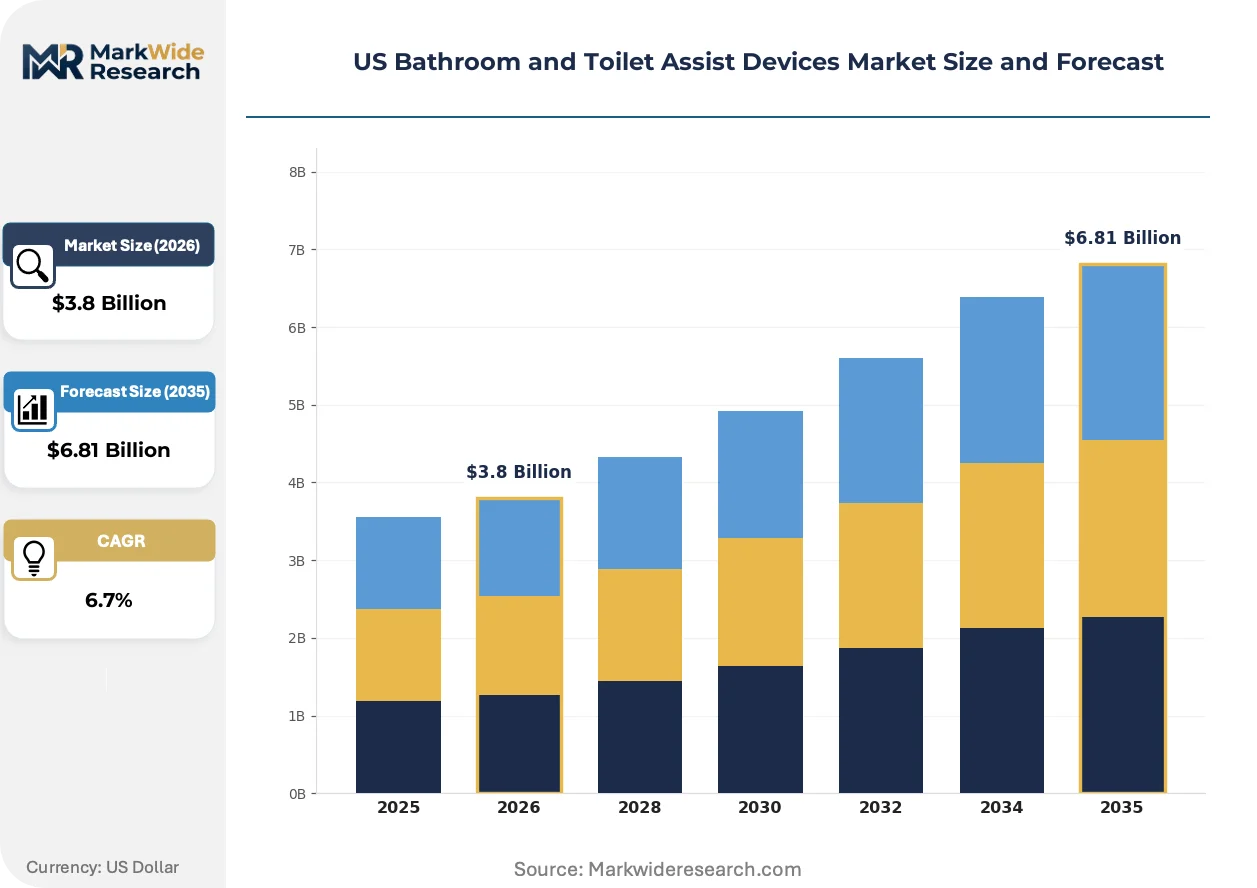
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grab Bars, Toilet Seat Lifts, Aids for Personal Hygiene, Portable Commodes End User: Seniors, Disabled Individuals, Caregivers, Healthcare Facilities Material: Plastic, Stainless Steel, Aluminum, Rubber Distribution Channel: Online Retail, Medical Supply Stores, Pharmacies, Direct Sales |
| Companies Covered | Drive Medical, Etac AB, Invacare Corporation, ArjoHuntleigh, Sunrise Medical, GF Health Products, Handicare, Prism Medical, Carex Health Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bathroom and Toilet Assist Devices Market Evolving Landscape
Electrification and sensor integration are compressing traditional mechanical product categories while regulatory pressure on fall prevention accelerates specification upgrades in institutional procurement.
Smart sensor arrays embedded in toilet seat lifts is unifying position detection, weight monitoring, and emergency alert functions into single hardware platforms. Skilled nursing facilities in California and New York are piloting these integrated systems for remote patient monitoring compliance. This convergence is unifying previously separate device categories into unified fall-prevention ecosystems that reduce installation footprint and maintenance contracts.
CMS rulemaking on in-home accessibility equipment preauthorization is tightening documentation requirements for powered device reimbursement. Home healthcare agencies are responding by investing in clinical assessment software that automates prior authorization submissions. The policy shift most acutely affects distributors serving Medicare Advantage populations in Florida and Texas, where inventory strategies now emphasize configurable kits over finished goods.
Facility managers are consolidating vendor relationships to reduce procurement transaction costs across multiple building sites. Senior living operators in Arizona and Nevada now specify single-source contracts covering grab bars, lifts, and hygiene aids, displacing fragmented purchasing through local durable medical equipment dealers. This concentration is most visible in the Sun Belt states where construction pipelines for age-restricted communities remain active.
US Bathroom and Toilet Assist Devices Market Segmentation
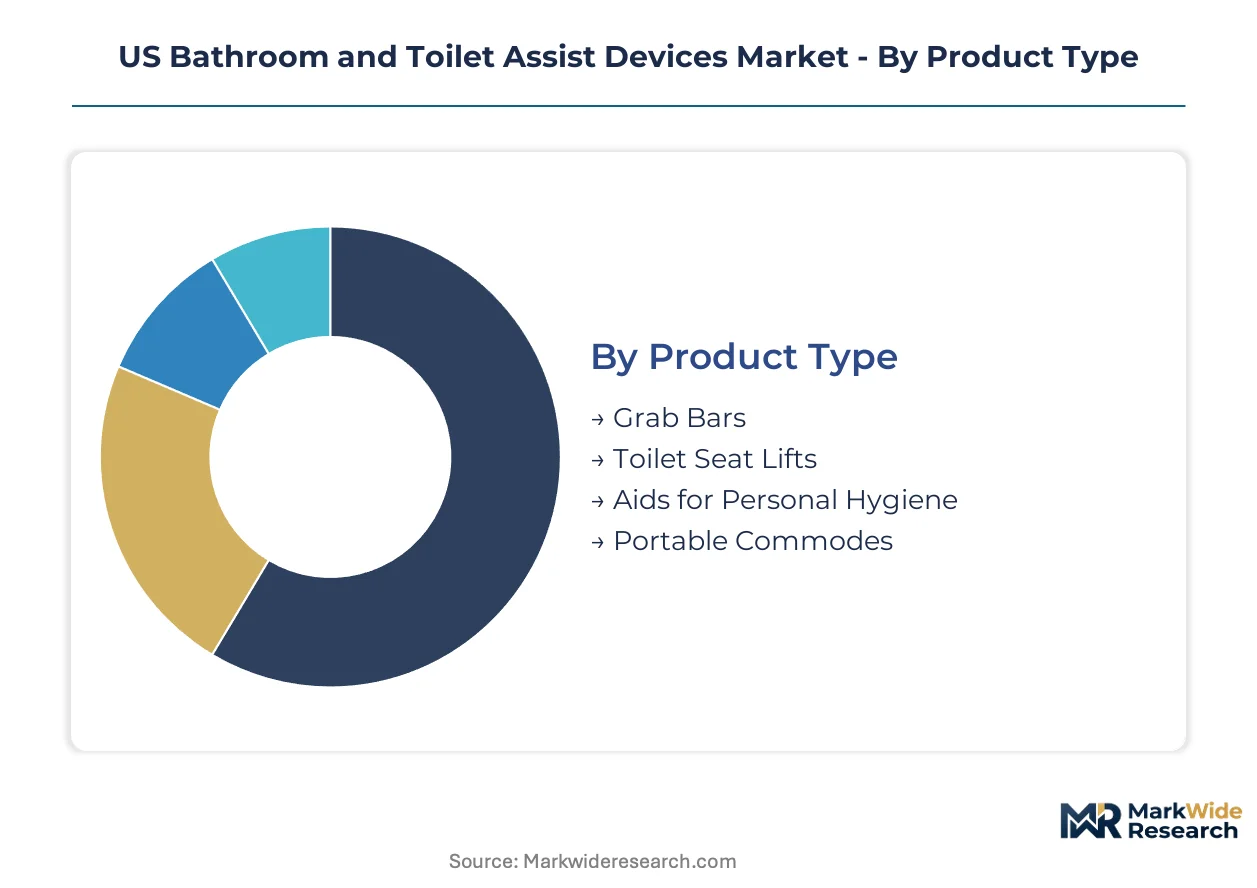
Segmentation in the US bathroom and toilet assist devices market reveals how procurement specifications diverge across Medicare reimbursement channels, ADA retrofit mandates, and direct-to-consumer purchasing. Material selection and power system configuration now determine margin capture more than traditional volume metrics.
Product Type:
Electrification and sensor integration are compressing traditional mechanical categories while fall-prevention mandates accelerate specification upgrades across institutional procurement.
- Grab Bars:Fabricated from 304-grade stainless steel or extruded aluminum tubing, these products anchor ADA Title III compliance in commercial restroom renovations. Florida and Texas healthcare facilities specify corrosion-resistant finishes for high-humidity environments, driving demand for marine-grade coatings above standard brushed steel.
- Toilet Seat Lifts:Powered variants with lithium battery packs displace manual hydraulic units in Medicare Advantage channels, enabling longer operational cycles between charges. Arizona skilled nursing facilities pilot smart sensor arrays that unify position detection with emergency alert functions.
- Aids for Personal Hygiene:Bidet attachments and cleansing sprays penetrate senior living construction specifications as infection control protocols intensify.
- Portable Commodes:Injection-molded polymer frames with tool-free assembly target home healthcare agency procurement for acute care discharge planning.
Grab bars lead on scale; aids for personal hygiene lead on momentum.
End User:
Reimbursement pathways and liability exposure create distinct purchasing behaviors across patient and institutional segments.
- Seniors:Medicare Part B and state Medicaid waiver programs determine out-of-pocket exposure, with Florida's HCBS funding levels creating localized demand concentration for powered lift configurations.
- Disabled Individuals:ADA Title III enforcement drives accessibility retrofit specifications in residential and commercial applications, particularly in Sun Belt states with aging housing stock.
- Caregivers:Home healthcare agencies face inconsistent training protocols for powered lift operation, creating product return exposure that erodes channel economics.
- Healthcare Facilities:Skilled nursing operators in California and New York consolidate vendor relationships into single-source contracts covering multiple building sites.
Seniors dominate volume; healthcare facilities dominate specification authority.
Material:
Weight reduction targets and wet-environment longevity requirements are shifting procurement specifications across metal and polymer categories.
- Plastic:Injection-molded polymers enable tool-free assembly in portable commodes, with Drive Medical leveraging captive molding operations to protect margin pools.
- Stainless Steel:304-grade finishes anchor corrosion resistance specifications in Arizona and Nevada senior living construction, where facility managers prioritize wet-environment longevity.
- Aluminum:Extruded tubing migrates from premium grab bars toward mid-tier toilet seat lifts as fabricators pursue weight reduction without sacrificing 250-pound load ratings.
- Rubber:Anti-slip grip surfaces and vibration dampening components complement primary structural materials in safety-critical applications.
Stainless steel leads on specification premium; aluminum leads on substitution velocity.
Distribution Channel:
Channel economics are fragmenting as e-commerce platforms bypass traditional durable medical equipment dealer networks.
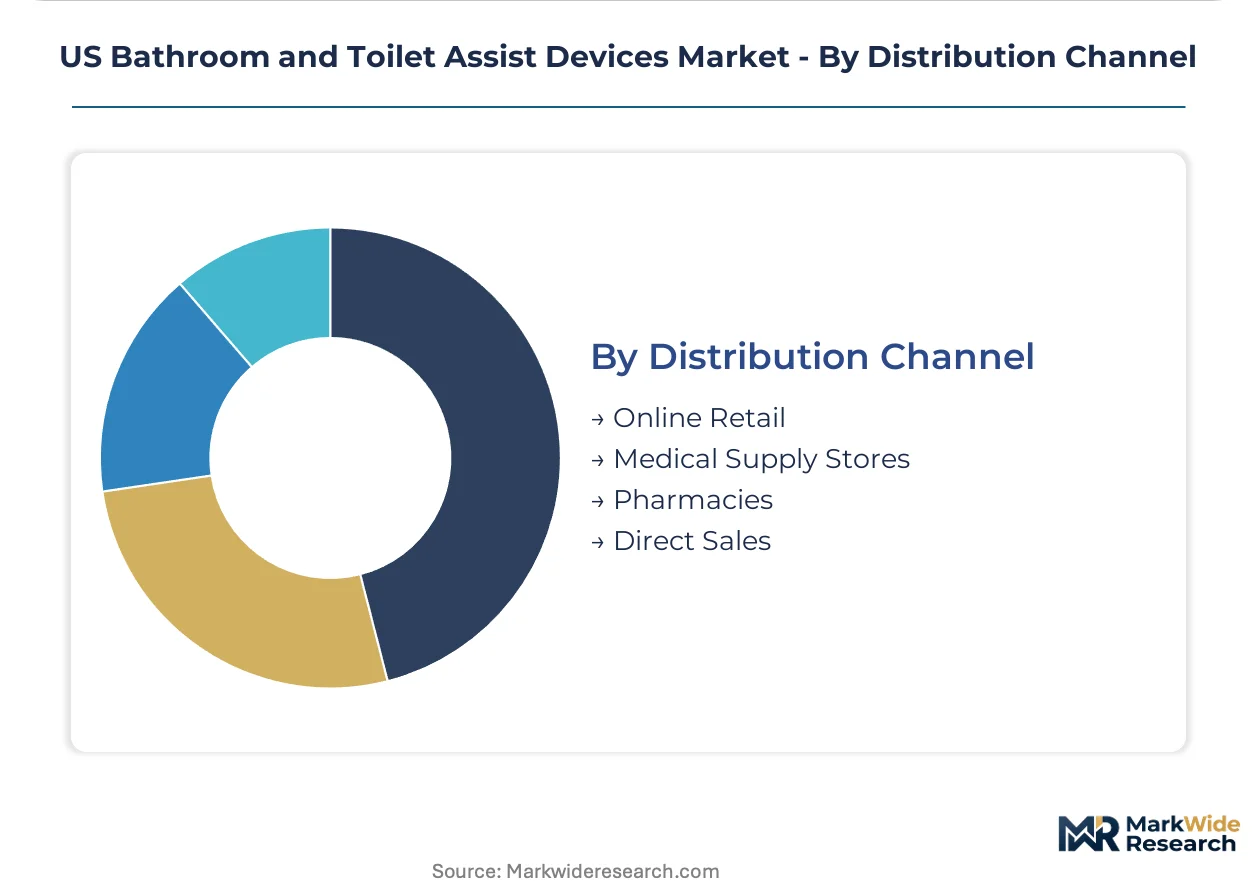
- Online Retail:Direct-to-consumer platforms capture margin previously allocated to shelf placement fees, with imported stainless steel grab bars flooding digital marketplaces and eroding price discipline.
- Medical Supply Stores:Invacare Corporation anchors position through dealer networks controlling inventory positioning for institutional procurement.
- Pharmacies:Independent retail locations face margin compression as Medicare Advantage reimbursement channels favor configurable kits over finished goods.
- Direct Sales:Home healthcare agencies in Texas and Florida invest in clinical assessment software that automates prior authorization submissions for CMS compliance.
Medical supply stores lead on institutional access; online retail leads on margin recapture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt corridor anchors domestic demand concentration for bathroom and toilet assist devices, with state-level Medicaid waiver programs and senior housing construction pipelines creating localized procurement surges across Florida, Texas, and Arizona metropolitan clusters.
Florida
Miami-Dade and Tampa Bay metro areas drive procurement volumes as home healthcare agencies expand service footprints for discharged acute care patients. State HCBS funding levels exceed national averages, reducing out-of-pocket exposure for powered toilet seat lifts. Jacksonville medical device distributors maintain inventory positioning for seasonal retiree migration patterns.
Texas
Houston and Dallas-Fort Worth skilled nursing operators consolidate vendor relationships into single-source contracts covering multiple building sites. Medicaid waiver expansion creates reimbursement pathways for bidet attachments in senior living construction specifications. Austin healthcare real estate development specifies corrosion-resistant wet-environment equipment for new assisted living facilities.
Arizona
Phoenix and Tucson construction pipelines for age-restricted communities remain active, with facility managers prioritizing 304-grade stainless steel protocols for wet-environment longevity. Medicare Advantage penetration rates in Maricopa County exceed national benchmarks, accelerating powered lift adoption. Flagstaff retirement communities pilot smart sensor arrays for remote patient monitoring compliance.
California
Los Angeles and San Francisco skilled nursing facilities pilot integrated fall-prevention ecosystems unifying position detection with emergency alert functions. State building codes exceed federal ADA standards, mandating grab bar placement in residential retrofits. San Diego home healthcare agencies invest in clinical assessment software automating CMS prior authorization submissions.
New York
Downstate healthcare systems face CMS rulemaking tightening documentation requirements for powered device reimbursement. Long Island independent pharmacies face margin compression as Medicare Advantage channels favor configurable kits over finished goods. Upstate rural counties experience caregiver training standardization gaps creating product return exposure.
US Bathroom and Toilet Assist Devices Market Competitive Landscape
Global majors compete with regional champions across distribution channel access, with durable medical equipment dealer networks controlling institutional shelf placement while direct-to-consumer platforms erode traditional margin pools. The vendor base fragments across three tiers: vertically integrated manufacturers with captive molding operations, Scandinavian design specialists emphasizing wet-environment longevity, and import-dependent distributors serving price-sensitive online retail. Dominant competitive moves include backward integration into polymer supply chains and consolidation of multi-product vendor relationships by senior living operators seeking procurement transaction cost reduction.
Within the vertically integrated tier, Drive Medical exemplifies captive production strategies protecting margin pools in portable commodes. Etac AB and Invacare Corporation occupy distinct positioning vectors, with the former representing Scandinavian design protocols and the latter anchoring durable medical equipment dealer network control. These three fabricators illustrate how material specialization and channel access determine competitive separation in a market where electrification and sensor integration compress traditional mechanical categories.
| Leading Market Players |
|---|
| Drive Medical |
| Etac AB |
| Invacare Corporation |
| ArjoHuntleigh |
| Sunrise Medical |
| GF Health Products |
| Handicare |
| Prism Medical |
| Carex Health Brands |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up durable medical equipment distributors anchor pricing discipline through captive dealer networks in Florida and Texas, while their consolidated procurement leverage compresses margin pools for independent pharmacy suppliers facing Medicare Advantage reimbursement shifts.
Pricing Analysis
Aluminum extrusion costs pass through directly to mid-tier toilet seat lift fabricators, forcing three-tier pricing structure across premium, standard, and economy levels differentiated by lithium battery integration and load certification tier. Price differentiation hinges on ADA bend strength testing documentation and Medicare Advantage reimbursement eligibility, with powered variants commanding premium positioning. Pricing pressure stems from import commoditization of stainless steel grab bars flooding online retail platforms. Home healthcare agencies exhibit highest price sensitivity due to CMS preauthorization documentation burdens, while skilled nursing facilities prioritize specification compliance over unit cost.
Supply Chain Analysis
304-grade stainless steel supply rests on Chinese and Taiwanese mill producers, with extruded aluminum tubing drawing from domestic smelters and Mexican fabricators. Raw material dependencies center on lithium battery cells, injection-molded polymer resins, and corrosion-resistant coating chemistries. Tariff exposure on Chinese steel inputs creates margin volatility for grab bar manufacturers. Distribution runs through durable medical equipment dealer networks controlling institutional shelf placement, with direct-to-consumer platforms eroding traditional channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through lithium battery cost curves and powered lift premium-tier displacement of manual hydraulic units in Medicare Advantage channels.
For Market Incumbents: Acquire clinical assessment software capabilities to automate CMS prior authorization workflows for home healthcare agency clients. Consolidate corrosion-resistant stainless steel finishing capacity in Arizona and Nevada to capture senior living construction specifications. Defend against import commoditization by embedding smart sensor arrays that create switching costs for skilled nursing facility contracts.
For New Entrants and Emerging Players: The gap between premium powered lifts and economy manual units creates entry space for mid-tier lithium battery configurations targeting Texas Medicaid waiver expansion. Penetrate direct-to-consumer channels with bidet attachments and cleansing sprays where reimbursement documentation requirements are lighter. Partner with independent pharmacies facing margin compression to offer configurable kit assembly services.
For Investors and Strategic Acquirers: Valuations sit cheapest among import-dependent distributors serving price-sensitive online retail without captive manufacturing. Long-term viability favors fabricators with backward integration into polymer molding or aluminum extrusion. Watch CMS rulemaking on in-home accessibility equipment preauthorization as the inflection signal for distributor inventory strategy shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Class I exempt status limits clinical evidence requirements but creates reimbursement uncertainty for Medicare Advantage plans demanding outcomes data. |
| Hospital System Partnership | Skilled nursing operators in California and New York consolidate vendor relationships into single-source contracts covering multiple building sites. |
| Software Companion Development | Clinical assessment platforms automate prior authorization submissions for home healthcare agencies facing CMS documentation tightening. |
| Reimbursement Strategy | Medicare Advantage channels favor powered toilet seat lifts with lithium battery packs over manual hydraulic units. |
| CE Marking Pathway | Scandinavian design protocols emphasizing corrosion-resistant stainless steel finishes enable wet-environment longevity claims for export positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and durable medical equipment dealer principals with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement schedules, ADA Title III enforcement records, and hospital procurement databases. Bottom-up demand modeling across product type, material, and distribution channel segments was triangulated with top-down market sizing.
Segment-weighting approaches applied differential growth assumptions across powered versus mechanical toilet seat lifts, stainless steel versus aluminum grab bars, and institutional versus direct-to-consumer channels throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating state-level HCBS funding trajectories and senior housing construction pipelines. Forecast inputs included Medicare Advantage penetration rates and aluminum price volatility indices.
Caveats apply where CMS rulemaking on preauthorization requirements or aluminum smelting energy cost shocks could materially shift the outlook. A small set of named triggers—lithium battery supply constraints, ADA testing laboratory backlogs, and Florida retiree migration pattern disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cholesterol Monitors Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Appendage Management Market
Medical Devices
Europe C-Arms Market
Medical Devices
Pulse Lavage Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Computer Aided Trauma Fixators Market