
 Needle Destroyer Market | 2026-2036
Needle Destroyer Market Size, Share, and Industry Trends Forecast 2026-2036
Needle Destroyer Market Intelligence
The use of high-temperature resistant polymers for device casings, replacing standard ABS plastics, is expanding the operational lifespan and safety profile of new needle destroyer models. This material upgrade allows for higher internal operating temperatures in electrothermal units. GPC Medical Ltd. leverages this trend in its hospital-grade product lines. Amkay Products Limited, in contrast, competes by offering a broad range of devices for diverse clinical settings.
A needle destroyer is a device designed to render hypodermic needles unusable immediately after a single use, preventing needlestick injuries and syringe reuse. Electrothermal models operate by melting the needle at temperatures above 1,400°C, while mechanical versions physically shear the needle. Hospitals remain the largest end-user segment due to high patient turnover and waste volume. However, demand from clinics is accelerating, driven by the need for point-of-care waste management solutions.
Regulatory frameworks are critical to market adoption. The World Health Organization's sharps management guidelines, the U.S. Occupational Safety and Health Administration's (OSHA) Bloodborne Pathogens Standard, and India's Bio-Medical Waste Management Rules mandate safe needle disposal. These regulations directly compel healthcare facilities to invest in compliant disposal technologies. The key decision for manufacturers now centers on balancing cost-effective design with adherence to increasingly stringent international safety and electrical standards.
Market Dynamics
The imperative for healthcare worker safety and the prevention of infectious disease transmission serves as the central structural force in the needle destroyer market. Global and national regulations, including guidelines from the World Health Organization, directly mandate engineered controls for sharps disposal.
Growth Catalysts
- Regulatory Mandates:India's Bio-Medical Waste Management Rules compel healthcare facilities of all sizes to adopt immediate, on-site needle destruction, creating a consistent source of demand from hospitals, clinics, and diagnostic labs.
- Occupational Safety Standards:The U.S. Occupational Safety and Health Administration's (OSHA) Bloodborne Pathogens Standard requires employers to provide safety-engineered devices, which includes needle destroyers, to minimize employee exposure to contaminated sharps.
- Material Science Advances:The use of high-temperature resistant polymers in device casings enhances the durability and safety of electrothermal units, allowing for more reliable performance in high-volume hospital environments and expanding the device's operational lifespan.
Market Restraints
- High Initial Cost:The significant capital investment required for advanced electrothermal needle destroyers acts as a barrier for smaller clinics and healthcare providers in resource-constrained settings, slowing widespread adoption.
- Substitution by Services:The availability of traditional sharps containers combined with third-party medical waste disposal and mail-back services presents a lower-cost alternative, particularly for facilities with low needle usage volumes.
- Mechanical Device Limitations:Some mechanical shear-type models do not completely destroy the needle hub, leaving potential for misuse or needlestick injuries and failing to meet the strictest institutional or regulatory standards for needle obliteration.
Strategic Opportunities
- Underpenetrated Verticals:Significant opportunity exists in expanding sales and marketing efforts toward veterinary clinics, dental offices, and aesthetic medicine practices, where adoption of dedicated needle destruction technology currently lags behind general hospitals.
- Digital Integration:Developing models with integrated IoT capabilities to automate usage logs and waste-tracking for compliance reporting offers a value-added service for large hospital networks managing complex regulatory requirements.
- Portable Device Development:Creating compact, battery-powered needle destroyers addresses the unmet needs of home healthcare providers, mobile phlebotomy services, and emergency medical teams for point-of-use sharps disposal in non-clinical settings.
Industry Challenges
- Certification Complexity:Navigating disparate international electrical safety standards, such as CE marking in Europe and UL listing in the United States, for electrothermal models creates long and costly development cycles for manufacturers.
- Component Price Volatility:Fluctuations in the price and availability of specialized electronic components and heat-resistant polymers create uncertainty in manufacturing costs and can compress profit margins for device producers.
- Performance Standardization Gaps:The absence of a universally accepted standard for measuring needle destruction efficacy complicates procurement for healthcare buyers and allows for performance inconsistencies between competing products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle Destroyer Market |
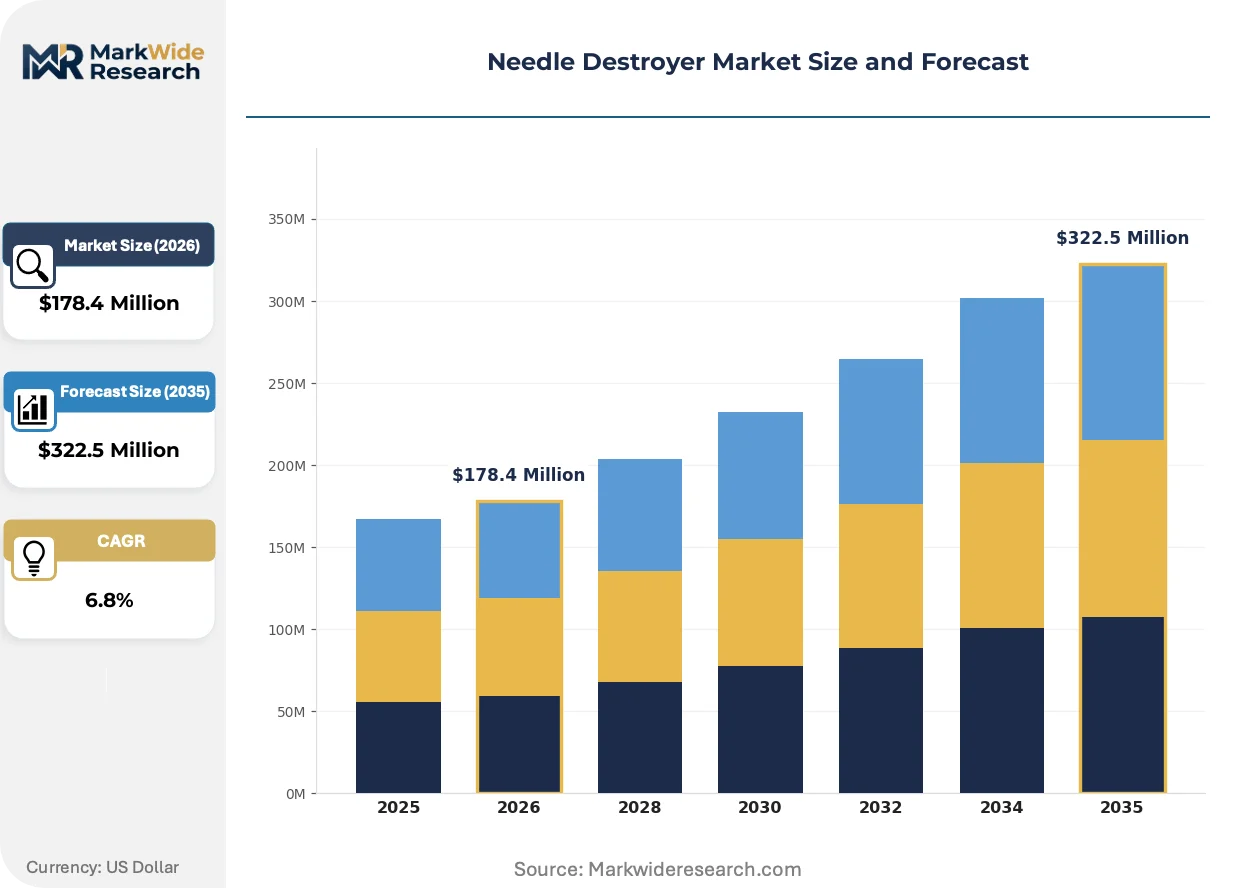
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $322.5 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Mobile End User: Hospitals, Clinics, Laboratories, Pharmaceutical Technology: Electrothermal, Thermal, Mechanical, Laser Service Type: Maintenance, Installation, Training, Support |
| Companies Covered | Amkay Products Limited, Bornemann Maschinenbau GmbH, Blacksmith Surgical, Cecon Pollutech Systems Pvt. Ltd., GPC Medical Ltd., Invitro Biotech Ltd., Millennium Surgical Corp, Surgipro Inc., Surgitech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle Destroyer Market Strategic Shifts & Innovations
A fundamental shift is underway from standalone disposal hardware toward integrated systems that embed needle destruction within broader clinical safety and compliance workflows. This evolution prioritizes data generation and process automation over simple mechanical action, reshaping the value proposition for next-generation devices.
Smart needle destroyers incorporating IoT sensors and wireless connectivity are gaining traction. Large hospital systems and clinical research organizations are the earliest adopters, seeking to automate safety protocols and compliance documentation. This technology is unifying the physical act of needle destruction with digital inventory management and auditable waste-tracking logs, creating a single, streamlined process for sharps management.
The European Union's Medical Device Regulation (MDR) is imposing more stringent requirements for clinical evidence and post-market surveillance. This directly increases the compliance burden for manufacturers seeking to sell devices within the EU. Hospital-grade electrothermal units are particularly affected, compelling producers to invest significantly in robust quality management systems and lifecycle documentation to secure and maintain their CE marking.
Demand patterns are moving toward decentralized, point-of-care waste management solutions, especially in outpatient and ambulatory settings. This model displaces reliance on periodic pickups by centralized biohazardous waste haulers with immediate, on-site needle obliteration. The shift is most visible in markets like India and Brazil, where national regulations strongly encourage immediate sharps neutralization to curb infection risks and illegal reuse.
Needle Destroyer Market Segmentation
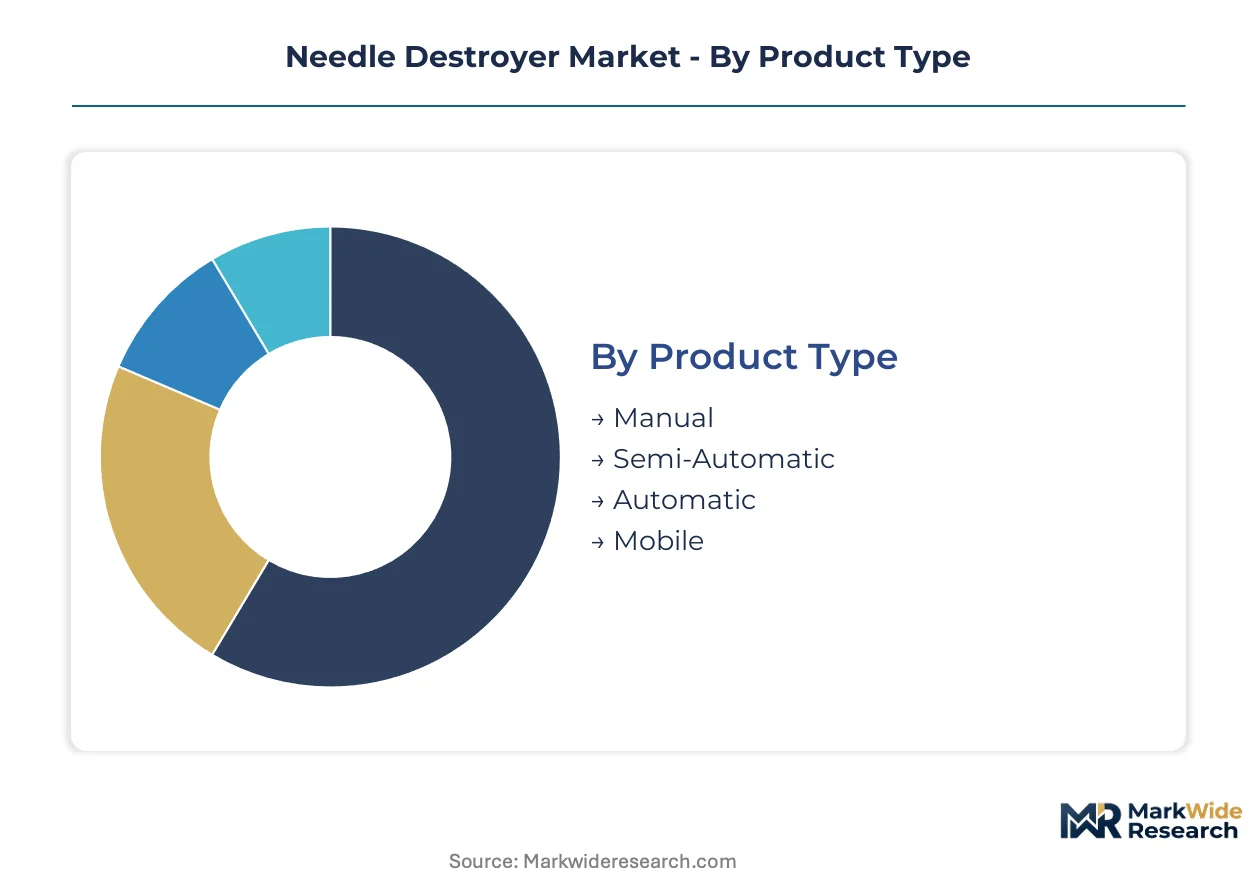
Segmentation for needle destroyers highlights diverse operational needs and regulatory compliance across healthcare settings. Understanding these distinct segments helps manufacturers tailor devices for specific user requirements, from high-volume hospital use to mobile point-of-care applications. This granular view informs strategic product development and market penetration strategies.
Product Type:
Product type segmentation differentiates needle destroyers based on their operational mechanism and degree of user intervention required for sharps destruction.
- Automatic:These advanced devices integrate sensors and automated mechanisms to detect and destroy needles with minimal human interaction, enhancing safety and throughput. Demand for automatic units is concentrating in large hospital systems in India, driven by stringent national bio-medical waste management rules.
- Mobile:Designed for portability and point-of-care use, mobile needle destroyers are compact, often battery-powered, and facilitate immediate sharps disposal in non-clinical environments. Demand is concentrating in home healthcare and emergency medical services, addressing the need for immediate waste management.
- Manual:These basic units require direct user action to shear or crush needles, often serving smaller clinics with lower patient volumes.
- Semi-Automatic:These devices offer partial automation, typically for needle feeding or disposal, balancing cost and efficiency for mid-sized healthcare facilities.
Mature deployment sits with Manual and Semi-Automatic models. Newer deployment is concentrated in Automatic and Mobile units.
End User:
End-user segmentation highlights the diverse operational contexts where needle destroyers are deployed, reflecting varying volumes, regulatory pressures, and safety protocols.
- Hospitals:These facilities represent the largest segment due to high patient turnover and significant waste volumes, necessitating robust, high-capacity needle destruction solutions. Demand in hospitals is driven by stringent occupational safety standards like the U.S. OSHA Bloodborne Pathogens Standard.
- Clinics:This segment includes outpatient facilities and general practitioner offices, where point-of-care waste management is increasingly critical to prevent needlestick injuries. Demand from clinics is accelerating in countries like Brazil, responding to national regulations encouraging immediate sharps neutralization.
- Laboratories:Research and diagnostic laboratories utilize needle destroyers for safe disposal of sharps used in sample handling and testing procedures.
- Pharmaceutical:Pharmaceutical companies use these devices in R&D and manufacturing for safe disposal of needles from drug administration or testing.
The Hospitals segment dominates current market share, while demand from Clinics is expanding most quickly.
Technology:
Technology segmentation delineates needle destroyers by their underlying method of rendering needles unusable, impacting destruction efficacy and operational costs.
- Electrothermal:These devices employ high temperatures, often exceeding 1,400°C, to melt and encapsulate needles, achieving complete obliteration and preventing reuse. Electrothermal units are preferred in high-volume hospital settings due to their superior safety profile and compliance with stringent waste management rules.
- Mechanical:Mechanical destroyers physically shear, bend, or crush needles, offering a cost-effective solution for immediate sharps inactivation without requiring electrical power. These models find significant application in smaller clinics and remote healthcare facilities seeking basic, reliable disposal methods.
- Thermal:This category encompasses methods that use heat to deform or melt needles, often at lower temperatures than electrothermal units, for safe disposal.
- Laser:Laser-based systems represent an emerging technology for precise and complete needle destruction, though they currently face higher initial costs and complexity.
The Mechanical technology represents the most widely adopted solution, with Electrothermal gaining traction for specialized applications.
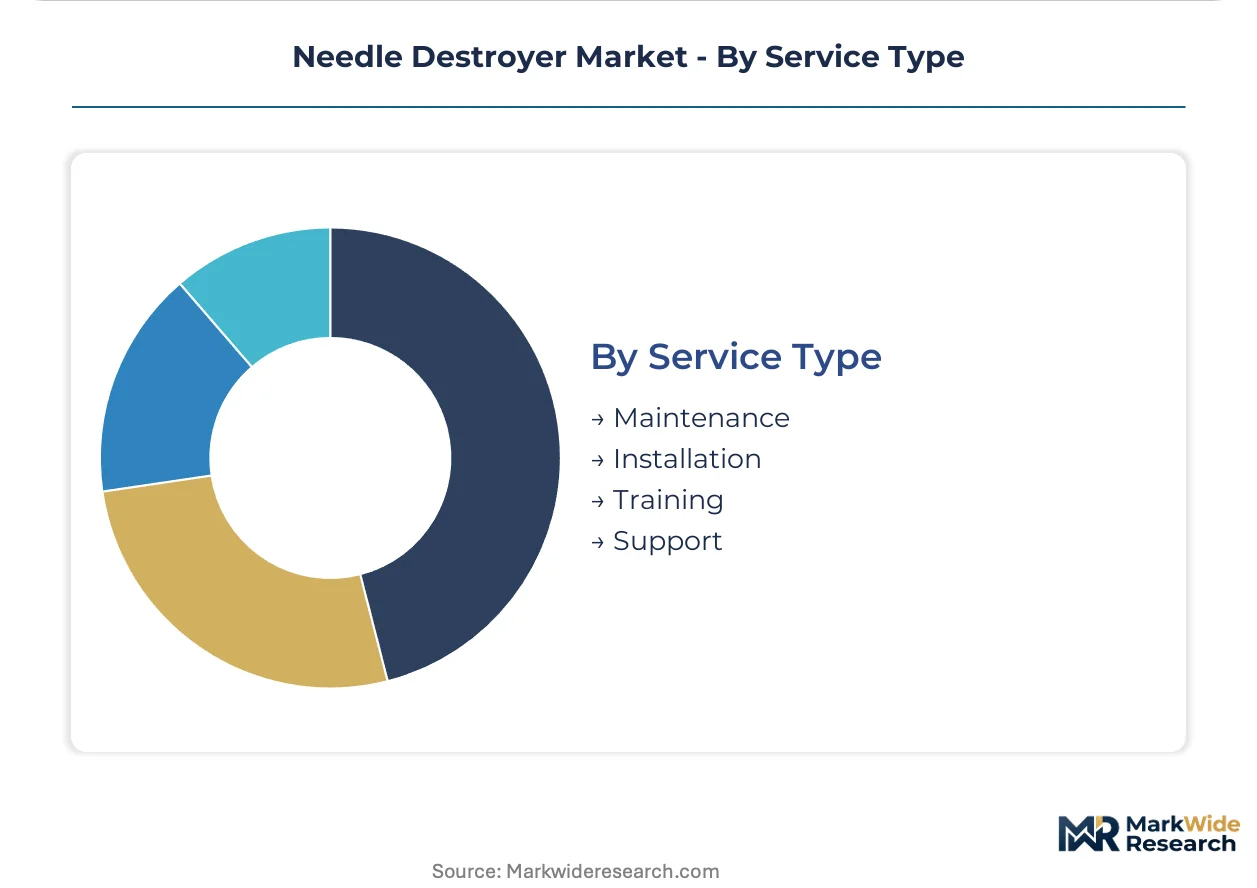
Service Type:
Service type segmentation captures the essential post-sale offerings that ensure optimal performance, longevity, and safe operation of needle destruction equipment.
- Maintenance:This service includes routine inspections, repairs, and calibration to ensure the continuous, safe, and efficient operation of needle destroyers over their lifespan. Robust maintenance programs are critical for large hospital networks to ensure uninterrupted compliance with safety protocols.
- Training:Providing comprehensive instruction on the proper and safe use of needle destroyers is vital for healthcare workers to prevent accidents and maximize device efficacy. Effective training programs are essential for new device adoption across diverse clinical settings in countries like India.
- Installation:This service ensures correct setup and integration of needle destroyer units into healthcare facility infrastructure, adhering to safety and electrical standards.
- Support:Technical assistance and troubleshooting services address operational issues, minimizing downtime and ensuring user satisfaction for healthcare providers.
Ensuring device longevity primarily involves Maintenance, while Training is crucial for user proficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's medical device parks, such as those in Andhra Pradesh and Gujarat, concentrate manufacturing for needle destroyers. These zones benefit from national policies encouraging domestic production and adherence to bio-medical waste management rules. Such concentrated efforts support the wider adoption of safe disposal technologies across the country, influencing regional dynamics.
India
India's stringent Bio-Medical Waste Management Rules compel healthcare facilities to adopt immediate, on-site needle destruction. This regulatory framework creates consistent demand from hospitals, clinics, and diagnostic labs. The Delhi-NCR region, with its dense network of healthcare providers, experiences substantial procurement of needle destroyers.
United States
Occupational safety standards and the prevention of infectious disease transmission drive needle destroyer demand in the United States. The U.S. OSHA Bloodborne Pathogens Standard mandates safety-engineered devices for sharps disposal in healthcare settings. Healthcare networks in major metropolitan areas such as New York and Chicago prioritize compliant disposal technologies.
Germany
Germany's advanced healthcare infrastructure and high patient safety standards necessitate robust needle destruction solutions. The European Union's Medical Device Regulation (MDR) imposes stringent requirements for devices sold within the country, including needle destroyers. Major hospital systems in cities like Munich and Berlin actively integrate electrothermal units to meet compliance and safety needs.
Brazil
Demand from clinics is accelerating in Brazil, driven by the need for point-of-care waste management solutions. National regulations strongly encourage immediate sharps neutralization to curb infection risks and illegal reuse. Healthcare facilities in urban centers like São Paulo and Rio de Janeiro increasingly procure decentralized disposal technologies.
Needle Destroyer Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, impacting competitive positioning. The market for needle destroyers exhibits a tiered structure, with established players focusing on hospital-grade solutions and newer entrants targeting mobile or smaller clinic needs. Strategic archetypes include specialized medical device manufacturers, broader healthcare equipment providers, and regional suppliers focusing on cost-effective mechanical units. Companies pursue portfolio diversification to address various end-user requirements and geographic expansion into underserved markets.
Among specialized providers, Amkay Products Limited exemplifies a strategy of offering a broad range of devices for diverse clinical settings. GPC Medical Ltd. represents manufacturers leveraging material science advances for hospital-grade product lines. Bornemann Maschinenbau GmbH, a German engineering firm, occupies a position focused on precision manufacturing for medical equipment. These companies anchor different segments, from comprehensive product portfolios to high-performance electrothermal units and precision engineered solutions.
| Leading Market Players |
|---|
| Amkay Products Limited |
| Bornemann Maschinenbau GmbH |
| Blacksmith Surgical |
| Cecon Pollutech Systems Pvt. Ltd. |
| GPC Medical Ltd. |
| Invitro Biotech Ltd. |
| Millennium Surgical Corp |
| Surgipro Inc. |
| Surgitech |
| Others |
Cost & Logistics Intelligence
Outsourced production of standard mechanical components influences pricing power for basic needle destroyers, particularly in cost-sensitive markets. This approach enables manufacturers to leverage lower labor costs and specialized fabrication expertise.
Pricing Analysis
Volume-driven sales of basic mechanical needle destroyers contrast with margin-rich electrothermal units. Pricing stratifies across premium, standard, and economy tiers, influenced by material quality like high-temperature resistant polymers and crucial certifications such as CE marking. Pricing pressure stems from the availability of traditional sharps containers and third-party disposal services. Smaller clinics and healthcare providers in resource-constrained settings exhibit the highest price sensitivity, while large hospital networks prioritize safety and regulatory compliance.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize the needle destroyer supply chain, particularly for reaching diverse healthcare facilities. Manufacturing concentrates in India and China for volume production, with precision components often sourced from Germany. The supply chain relies on specialized electronic components and heat-resistant polymers, making it vulnerable to component price volatility. Distribution runs through direct sales channels for large hospital systems and extensive distributor networks for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The needle destroyer market is undergoing a technology-transition phase, with advanced electrothermal models increasingly displacing legacy mechanical versions. This shift prioritizes enhanced safety and complete needle obliteration over basic physical destruction.
For Market Incumbents:Anchor hospital-grade product lines by investing in advanced electrothermal unit R&D and securing long-term supply contracts for high-temperature resistant polymers. This defends against substitution by lower-cost third-party disposal services and strengthens compliance with stringent international electrical standards. Pursue certification investments like CE marking and UL listing to maintain market access. Deepen vertical integration into specialized component manufacturing to control quality and costs.
For New Entrants and Emerging Players:Begin with targeting underpenetrated verticals such as veterinary clinics, dental offices, and aesthetic medicine practices. Develop compact, battery-powered portable devices for home healthcare providers and mobile phlebotomy services to address unmet point-of-use needs. Offer cost-effective semi-automatic models bundled with comprehensive training programs to facilitate adoption in smaller clinical settings. Focus on digital integration for automated usage logs to attract clinics with compliance reporting requirements.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized medical device manufacturers possessing strong intellectual property in electrothermal technology or IoT integration. The long-term viability of this market remains robust, driven by persistent regulatory mandates for sharps disposal and the imperative for healthcare worker safety. Target firms with established distribution networks in high-growth regions like India and Brazil. The signal to watch is a sustained increase in adoption rates of smart, connected needle destroyers within mid-sized clinics.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Smart, IoT-enabled Electrothermal Destroyer | This introduces advanced units that automate compliance reporting for large hospital networks. |
| Geographic Expansion into Emerging Markets | This captures demand from regions like India with strict bio-medical waste management rules. |
| Strategic Partnership with Waste Management Firms | This creates integrated sharps disposal solutions, offering value-added services to healthcare facilities. |
| Certification Investment for Global Standards | This ensures market access and regulatory compliance for electrothermal models in diverse countries. |
| Manufacturing Scale-Up for Heat-Resistant Polymers | This secures critical material supply and enhances the durability of high-performance device casings. |
Research Approach
Document review covered World Health Organization guidelines, OSHA Bloodborne Pathogens Standard, and national bio-medical waste management rules, complemented by interviews with industry stakeholders. Primary research included discussions with hospital procurement managers, biomedical engineers, and medical device R&D directors. This approach facilitated bottom-up and top-down triangulation of market data. Secondary validation involved analysis of medical device industry reports.
Cross-referencing historical market data with expert panel input established the analytical framework across the analysis window. The model segmented the market by product type, end user, technology, service type, and regional regulatory compliance. Compound Annual Growth Rates were derived from an assessment of healthcare infrastructure spending and sharps injury rates. This provided a robust basis for market projections.
Underlying measurement precision varies by segment; hospital and electrothermal units carry tighter precision than mobile or manual models. Forecasts reflect assumptions regarding regulatory enforcement and healthcare investment, though component price volatility and evolving international electrical standards pose specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pupillometer Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Oral Appliance Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Pleural Catheters Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
US Stethoscope Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Global Self Care Medical Devices Market