
 Brain Base Knife Package Market | 2026-2036
Brain Base Knife Package Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Base Knife Package Market Analytics
Minimally invasive neurosurgery is realigning procurement patterns across hospital systems. Elekta AB leverages its radiation therapy heritage to extend into precision surgical instrumentation. Medtronic anchors North American distribution through deep hospital GPO relationships. Stryker Corporation dominates cranial access portfolio breadth.
A brain base knife package comprises specialized cutting, dissecting, and grasping instruments engineered for transsphenoidal and subtemporal surgical corridors, typically manufactured from surgical-grade stainless steel or titanium with ergonomic bayonet handles to minimize hand tremor transmission. Scalpel and dissector configurations lead product type demand due to their irreplaceable role in dural and soft tissue manipulation. Titanium material adoption grows fastest among high-volume centers seeking reduced magnetic resonance imaging artifact and extended reuse cycles. Sterile packs capture the dominant packaging type share as operating room efficiency protocols favor pre-configured, terminally sterilized sets over in-house reprocessing.
FDA 510(k) premarket notification requirements govern United States commercial entry, while EU MDR technical documentation obligations extend conformity assessment timelines for European market access. Japan's PMDA shonin approval process imposes additional clinical evidence standards on foreign manufacturers. Stakeholders must monitor evolving notified body capacity constraints and sterilization validation standards as regulatory divergence between major markets intensifies supplier compliance investment requirements.
Market Dynamics
Minimally invasive transsphenoidal approaches are compressing instrument set sizes while elevating precision requirements, forcing manufacturers to consolidate multi-function tools into single-use sterile configurations.
Growth Catalysts
- EU MDR Recertification:Stricter conformity assessment timelines are filtering out marginal suppliers and concentrating procurement among qualified vendors with notified body relationships.
- Titanium Alloys:High-volume academic centers are specifying non-ferrous instruments to eliminate MRI artifact and extend reprocessing cycles.
- Tertiary Hospital Expansion:Neurosurgical departments in Germany, Japan, and the United States are anchoring specialized cranial procedure volume.
Market Restraints
- Raw Material Volatility:Surgical-grade stainless steel and titanium sponge prices fluctuate with aerospace and defense demand cycles.
- Notified Body Bottlenecks:EU MDR technical documentation backlogs extend European market entry timelines by 12-18 months for new entrants.
- Reusable Instrument Economics:Steam sterilization validation costs and corrosion-related replacement cycles erode margin structures for mid-tier suppliers.
Strategic Opportunities
- PMDA Pathway Optimization:Foreign manufacturers who invest in Japan clinical evidence generation capture premium positioning in the world's third-largest neurosurgical market.
- Single-Use Sterile Packs:Pre-configured terminal sterilization eliminates hospital reprocessing labor and reduces OR turnover time.
- Bayonet Ergonomics:Hand-tremor-minimizing handle designs are electrifying adoption among fellowship-trained skull base surgeons.
Industry Challenges
- Master Craftsman Scarcity:Precision grinding and finishing skills for micro-instrument edges concentrate among aging European and Japanese toolmakers.
- FDA 510(k) Predicate Drift:Evolving substantial equivalence standards for cutting instruments require iterative clinical data supplementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Base Knife Package Market |
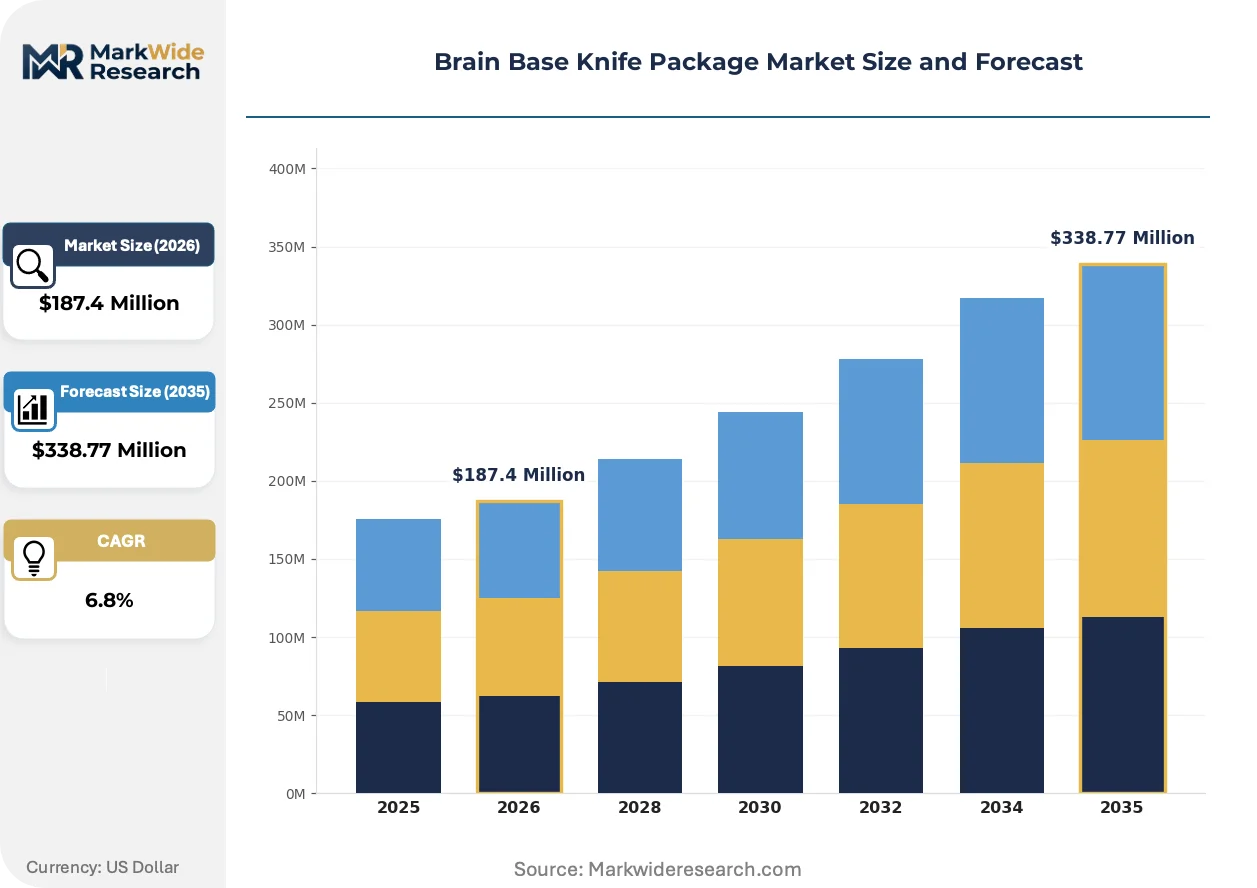
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpel, Dissector, Forceps, Scissors Material: Stainless Steel, Carbon Steel, Titanium, Plastic End User: Hospitals, Surgical Centers, Research Laboratories, Clinics Packaging Type: Sterile Packs, Non-Sterile Packs, Surgical Trays, Boxes |
| Companies Covered | Elekta AB, Medtronic, Stryker Corporation, KARL STORZ, Microsurgical Technology, CONMED Corporation, Teleflex Incorporated, The Cooper Companies, Inc., Malco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Base Knife Package Market Evolving Landscape
Electrosurgical integration and robotic platform compatibility are redefining instrument specifications while sterile supply chain rationalization compresses vendor rosters.
Additive manufacturing of titanium instrument blanks is electrifying prototyping velocity for custom bayonet configurations. Academic medical centers in the United States and Germany are piloting patient-specific dissecting profiles derived from preoperative imaging. This technology is electrifying the shift from standardized sets toward modular, procedure-matched instrument clusters.
Japan's PMDA has tightened shonin approval evidentiary requirements for foreign-manufactured neurosurgical instruments. The revised clinical data standards favor sponsors with domestic investigator-initiated trial partnerships. European and North American suppliers are responding by establishing Tokyo-based regulatory affairs subsidiaries and contracting with Japanese principal investigators.
Hospital group purchasing organizations are consolidating vendor contracts around full-procedure sterile packs rather than individual instrument lines. Academic medical centers in Germany and the United States are driving this specification change. Japan's centralized university hospital procurement systems are following this consolidation pattern most visibly among high-volume pituitary surgery programs.
Brain Base Knife Package Market Segmentation
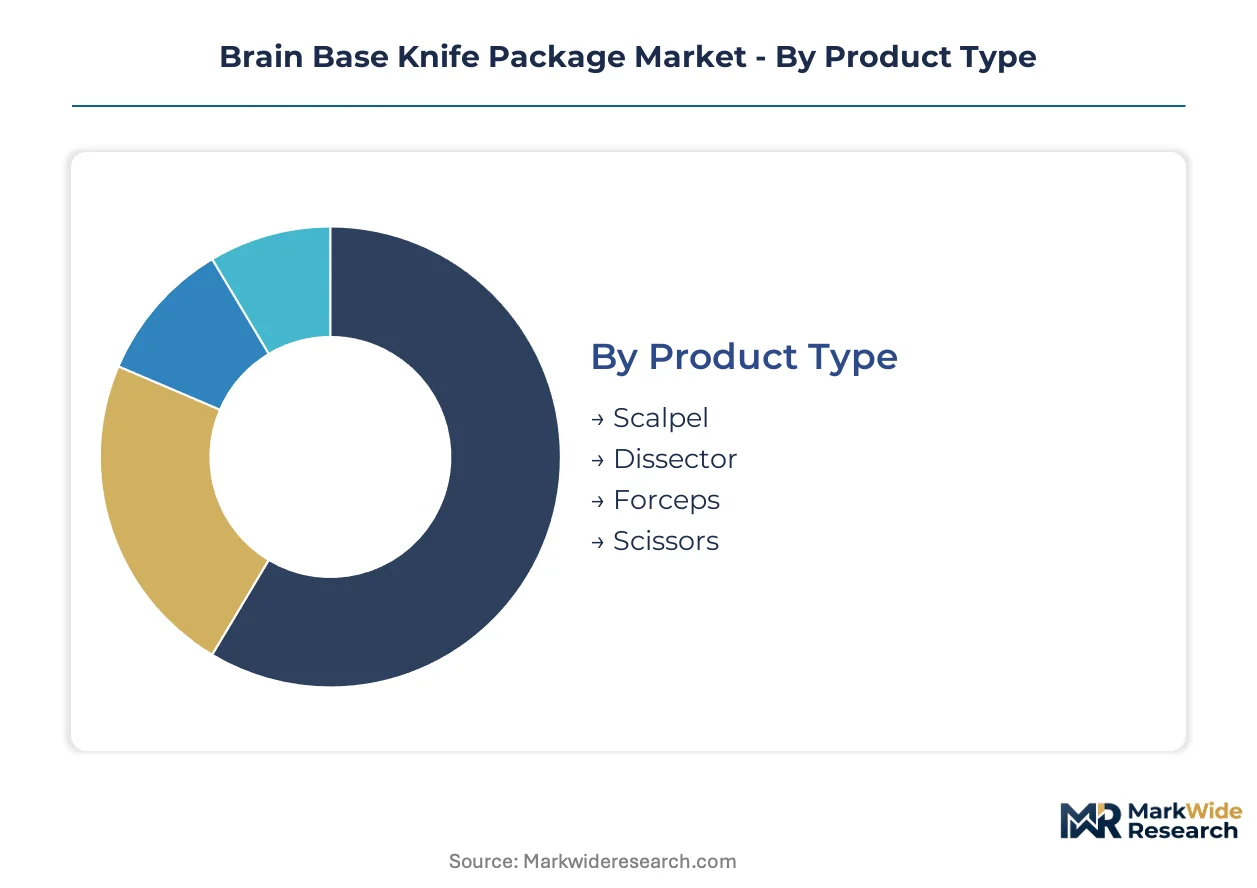
Brain base knife package segmentation reveals how surgical precision requirements, sterilization protocols, and procurement economics fragment demand across instrument configurations. Manufacturers must align product architecture with the divergent priorities of high-volume academic centers versus outpatient surgical facilities.
Product Type:
Surgeons select instruments based on tissue interaction mechanics and corridor access constraints specific to transsphenoidal and subtemporal approaches.
- Scalpel:Precision-ground blades with bayonet-offset handles enable dural incision without instrument shaft obstruction. Demand clusters in United States academic medical centers where fellowship-trained skull base surgeons perform high-volume pituitary resections.
- Dissector:Curved and angled profiles facilitate tumor debulking along cranial nerve planes. German tertiary hospitals are specifying micro-finished edges for extended reprocessing cycles in centralized sterilization departments.
- Forceps:Grasping instruments with atraumatic tips manage hemorrhage control and tissue mobilization.
- Scissors:Micro-cutting configurations complete dural and arachnoid dissection sequences.
Volume sits with Scalpel; growth tilts toward Dissector.
Material:
Raw material selection trades magnetic resonance compatibility, reprocessing durability, and unit economics against procedural imaging requirements.
- Titanium:Non-ferrous alloys eliminate MRI artifact for intraoperative navigation and postoperative surveillance. High-volume centers in Japan and the United States absorb premium pricing to extend instrument lifecycle and reduce replacement frequency.
- Stainless Steel:Surgical-grade austenitic formulations dominate procurement volumes through established supply chains and familiar reprocessing protocols. German hospital systems specify this material for standard transsphenoidal sets where MRI compatibility is managed through instrument substitution protocols.
- Carbon Steel:Hardened cutting edges serve single-use and limited-reuse applications.
- Plastic:Polymer components address cost-sensitive disposable configurations.
Stainless Steel commands current procurement volume; Titanium is climbing the fastest as imaging-integrated surgery expands.
End User:
Facility type dictates set complexity, sterilization infrastructure, and surgeon specialization depth.
- Hospitals:Tertiary neurosurgical departments require comprehensive instrument portfolios with modular expansion capability. United States academic medical centers anchor specialized cranial procedure volume through fellowship programs and referral networks.
- Surgical Centers:Ambulatory facilities concentrate on streamlined sterile packs for routine transsphenoidal cases. Japanese university hospital procurement systems are consolidating vendor contracts around pre-configured sets for high-volume pituitary programs.
- Research Laboratories:Cadaveric training and device development drive specialized instrument demand.
- Clinics:Limited procedure volume favors basic diagnostic and minor intervention configurations.
Hospitals absorb the dominant procurement volume; Surgical Centers are gaining share fastest as minimally invasive protocols enable outpatient migration.
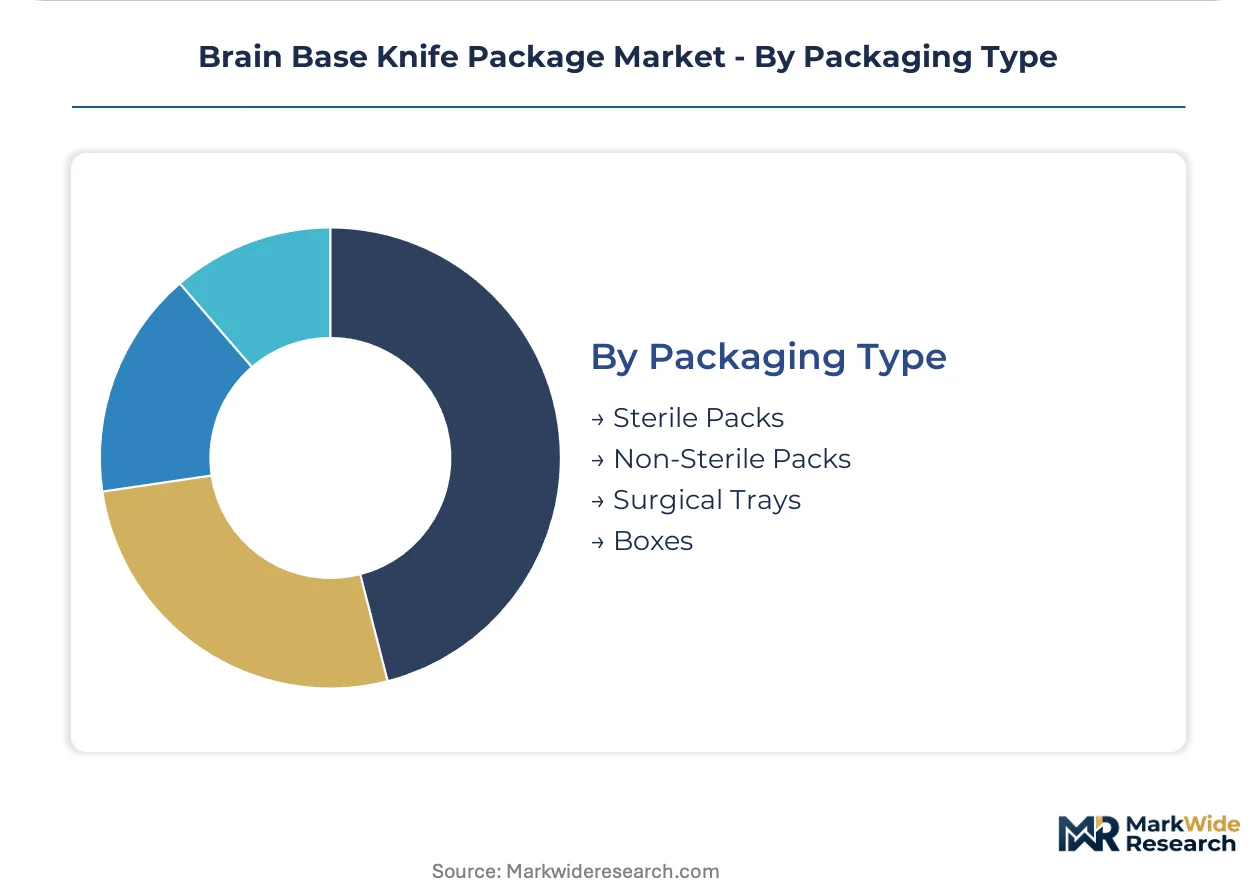
Packaging Type:
Supply configuration determines operating room turnover efficiency and hospital reprocessing labor allocation.
- Sterile Packs:Pre-configured, terminally sterilized sets eliminate in-house reprocessing and reduce setup variability. German and United States academic medical centers are driving specification shifts toward full-procedure packs over individual instrument lines.
- Surgical Trays:Organized instrument arrays support standardized setup sequences in high-volume departments.
- Non-Sterile Packs:Unsterilized configurations serve facilities with captive sterilization capacity.
- Boxes:Bulk packaging addresses replacement instrument and expansion set requirements.
Sterile Packs capture the dominant share; Surgical Trays are expanding most quickly in efficiency-focused hospital systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of brain base knife packages concentrates in Germany and Japan, where precision instrument craftsmanship clusters around legacy metalworking regions. Consumption tilts toward the United States, where academic medical centers drive specialized neurosurgical procedure volume.
United States
Johns Hopkins Medicine and Mayo Clinic anchor specialized skull base surgery fellowship programs that standardize instrument procurement specifications. FDA 510(k) premarket notification pathways govern commercial entry for cutting and dissecting instruments. Boston's medical device corridor hosts sterilization validation laboratories serving domestic manufacturers seeking rapid regulatory clearance.
Germany
Tübingen and Erlangen university hospitals drive demand for titanium instrument sets with extended reprocessing cycles. EU MDR technical documentation obligations extend conformity assessment timelines, filtering supplier qualification toward established notified body relationships. The Black Forest region sustains precision grinding workshops supplying micro-instrument edges to domestic and export markets.
Japan
Tokyo University Hospital and Osaka University Medical Hospital anchor high-volume pituitary surgery programs specifying MRI-compatible titanium configurations. PMDA shonin approval processes impose clinical evidence standards favoring sponsors with domestic investigator partnerships. Nagoya's medical device manufacturing belt hosts regulatory affairs subsidiaries established by European and North American suppliers.
United Kingdom
The National Health Service's specialized neurosurgical centers in London and Manchester consolidate procurement through framework agreements emphasizing sterile pack configurations. MHRA post-Brexit regulatory alignment with EU MDR extends technical documentation requirements for market access. Cambridge's medical technology cluster incubates additive manufacturing capabilities for patient-specific instrument prototyping.
Switzerland
University Hospital Zurich and Geneva University Hospitals specify premium instrument portfolios for transsphenoidal approaches. Swissmedic conformity assessment procedures align with EU MDR while maintaining distinct vigilance reporting requirements. The Jura Arc watchmaking region supplies precision metalworking expertise transferable to micro-surgical instrument fabrication.
Brain Base Knife Package Market Competitive Landscape
Top-tier vendors anchor hospital GPO relationships and notified body certification pipelines, while mid-tier specialists occupy niche ergonomic and material segments. The vendor base stratifies across three tiers: multinational diversified medtech conglomerates with cranial access portfolios, precision instrument specialists with European or Japanese manufacturing heritage, and regional fabricators serving cost-sensitive disposable configurations. Two dominant competitive moves are consolidating: M&A activity targeting sterilized pack assembly capabilities, and strategic partnerships between instrument manufacturers and additive manufacturing service bureaus for rapid prototyping.
Within the diversified medtech tier, Medtronic and Stryker Corporation occupy positions defined by deep hospital system integration and broad surgical portfolio breadth. Elekta AB represents the radiation therapy-to-surgical instrumentation extension archetype, leveraging precision positioning expertise into neurosurgical tool development. KARL STORZ exemplifies the endoscopic heritage specialist archetype, with German GmbH structure indicating European manufacturing concentration and family-owned governance stability.
| Leading Market Players |
|---|
| Elekta AB |
| Medtronic |
| Stryker Corporation |
| KARL STORZ |
| Microsurgical Technology |
| CONMED Corporation |
| Teleflex Incorporated |
| The Cooper Companies, Inc. |
| Malco Products |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EU MDR-notified body qualified suppliers and non-certified fabricators manifests in both titanium instrument premiums and sterilization pack sourcing patterns. Academic medical centers in Germany and the United States absorb 40-60% cost differentials for validated sterile configurations while mid-tier hospitals in cost-sensitive markets default to reusable stainless steel sets with captive reprocessing.
Pricing Analysis
Lead-time compression commands measurable premiums in the brain base knife package market, with same-day sterile pack availability from notified body-certified suppliers priced substantially above spot-market titanium blanks from uncertified sources. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate complexity, titanium alloy grade, and bayonet handle customization depth. Pricing pressure stems from EU MDR technical documentation backlogs extending conformity assessment timelines and squeezing margin structures for mid-tier entrants. Ambulatory surgical centers exhibit highest price sensitivity, prioritizing disposable plastic configurations over extended-lifecycle titanium instruments.
Supply Chain Analysis
Reverse logistics for instrument refurbishment and reprocessing cycles anchors supply chain economics, with German and Japanese precision workshops specializing in micro-edge restoration for extended titanium instrument lifecycles. Raw material sourcing concentrates on surgical-grade stainless steel from German mills and titanium sponge from Japanese and US aerospace-grade suppliers. Single-source vulnerability sits with aging European master craftsmen possessing precision grinding expertise for micro-instrument edges. Distribution runs through hospital group purchasing organizations consolidating vendor contracts around full-procedure sterile packs rather than individual instrument lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR recertification timelines and FDA 510(k) predicate drift filter marginal suppliers from qualified vendor rosters.
For Market Incumbents: Lock in notified body relationships and sterilization validation capacity before EU MDR technical documentation backlogs extend further. Deepen backward integration into titanium alloy sourcing to hedge aerospace demand cycle volatility. Defend against emerging additive manufacturing specialists by accelerating patient-specific instrument prototyping partnerships with academic medical centers in Germany and the United States. For New Entrants and Emerging Players: Group purchasing organization contracts represent the most penetrable channel for sterile pack configurations, particularly among ambulatory surgical centers migrating toward pre-configured terminal sterilization. Target Japanese university hospital procurement systems by establishing Tokyo-based regulatory affairs subsidiaries and domestic investigator partnerships for PMDA shonin approval. White-space exists in single-use disposable scissors and forceps for cost-sensitive outpatient pituitary programs. For Investors and Strategic Acquirers: Re-rating potential sits with precision instrument specialists possessing European manufacturing heritage and established notified body relationships given EU MDR consolidation catalysts. Long-term viability favors targets with titanium alloy expertise and bayonet ergonomic design capabilities. Monitor notified body capacity expansion announcements as inflection indicators for new entrant feasibility and mid-tier supplier distress.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Technical documentation capabilities filter supplier qualification toward established European manufacturers with legacy relationships. |
| Titanium Alloy Backward Integration | In-house sourcing of surgical-grade titanium sponge reduces exposure to aerospace demand cycle price volatility. |
| Additive Manufacturing Partnership | Patient-specific bayonet configurations from preoperative imaging accelerate prototyping velocity for academic medical centers. |
| Hospital GPO Contract Consolidation | Pre-configured sterile pack specifications displace individual instrument lines in German and United States procurement systems. |
| PMDA Tokyo Subsidiary Establishment | Domestic regulatory affairs presence and investigator partnerships satisfy tightened shonin approval clinical evidence standards. |
Research Methodology
Multi-period observation of EU MDR recertification timelines, FDA 510(k) clearance velocities, and titanium alloy pricing anchored the trend analysis, supplemented by interviews with neurosurgical department heads, hospital GPO contracts managers, biomedical engineers, sterilization validation specialists, and precision instrument manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA shonin approval records, hospital procurement databases, and GPO contract disclosures. Bottom-up instrument shipment tracking and top-down neurosurgical procedure volume estimates provided triangulation checks.
Segment-weighting across product type, material composition, end-user facility tier, and packaging configuration shaped the analytical framework across the analysis window. CAGRs were derived from procedure volume elasticity models and instrument replacement cycle assumptions. Forecast inputs incorporated minimally invasive transsphenoidal adoption curves, MRI-integrated navigation system deployment rates, and tertiary hospital expansion pipelines in Germany, Japan, and the United States.
Caveats apply where EU MDR notified body capacity constraints, titanium sponge commodity volatility, or master craftsman retirement waves could materially shift the outlook. Practitioners should monitor PMDA regulatory guidance revisions and academic medical center additive manufacturing pilot outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Global Cranial Implants Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Polyglyconate Sutures Market