
 Oral Appliance Market | 2026-2036
Oral Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Appliance Market Analytics
ISO 13485 certification timelines for custom oral appliance manufacturers is collapsing from eighteen months to under nine months in several jurisdictions. ResMed leverages its respiratory therapy ecosystem to cross-sell oral appliances through sleep clinic networks. SomnoMed sustains geographic dominance across Europe and Australia with direct-to-dentist distribution infrastructure. ProSomnus Sleep Technologies specializes in precision-milled nylon devices, differentiating on material biocompatibility and digital workflow integration.
An oral appliance is a removable intraoral device fabricated from thermoplastic, acrylic, silicone, or metal substrates, designed to reposition the mandible or tongue to maintain patent upper airway patency during sleep; primary specifications include vertical opening range of 2–10 mm and protrusion adjustability in 0.25 mm increments for obstructive sleep apnea therapy. Mandibular advancement devices command the largest revenue pool due to established reimbursement and clinical validation, while custom appliances fabricated via CAD/CAM milling represent the fastest-expanding segment as dental laboratories adopt chairside digital scanning. Tongue retaining devices occupy a narrower niche for edentulous patients or those with significant temporomandibular joint concerns.
FDA 510(k) premarket notification requirements govern US market entry for sleep apnea indications, while the EU Medical Device Regulation (MDR) Class IIa classification imposes clinical evidence and post-market surveillance obligations on manufacturers selling in Europe. Health Canada's Medical Devices Bureau maintains comparable review standards, creating a triad of stringent regulatory environments that favor established players with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving reimbursement decisions from national health technology assessment bodies, as coverage determinations for oral appliance therapy versus continuous positive airway pressure directly shape prescribing behavior and patient out-of-pocket exposure.
Market Dynamics
CAD/CAM digital workflows are collapsing fabrication timelines for mandibular advancement devices while FDA 510(k) clearance pathways compress product qualification cycles, fundamentally restructuring competitive advantage toward manufacturers with integrated regulatory and digital manufacturing capabilities.
Growth Catalysts
- Reimbursement Stabilization:Established CPT codes for oral appliance therapy in US dental sleep medicine practices reduce patient out-of-pocket friction and accelerate prescribing velocity among trained specialists.
- ISO 13485 Certification Acceleration:Collapsing quality management system timelines from eighteen months to under nine months in several jurisdictions enables faster market entry for custom appliance manufacturers.
- Specialist Training Proliferation:Expanding dental sleep medicine residency programs and continuing education curricula build prescriber capacity for mandibular advancement device therapy across major metropolitan clusters.
Market Restraints
- Biocompatible Nylon Feedstock Concentration:Precision-milled device manufacturers face supply vulnerability from limited qualified medical-grade polymer suppliers concentrated in German and Swiss chemical production basins.
- EU MDR Clinical Evidence Burden:Class IIa classification under the Medical Device Regulation imposes post-market surveillance and clinical performance documentation obligations that extend commercialization timelines for European market entry.
- CPAP Substitution Threat:Continuous positive airway pressure therapy retains first-line status in AASM clinical guidelines and dominates severe obstructive sleep apnea segments through established respiratory therapy infrastructure.
Strategic Opportunities
- Edentulous Patient Segment:Tongue retaining devices address an underserved population excluded from mandibular advancement therapy due to dental arch integrity requirements.
- Chairside Digital Integration:Intraoral scanning and same-day milling convergence enables direct-to-patient fabrication models that bypass traditional dental laboratory intermediaries.
- Australian Direct Distribution:Established sleep clinic networks and favorable TGA regulatory alignment create expansion pathways for vertically integrated appliance manufacturers seeking geographic diversification beyond saturated North American markets.
Industry Challenges
- CAD/CAM Technician Scarcity:Dental laboratories face acute shortages of operators proficient in 3D scanning, design software, and five-axis milling equipment for medical device tolerances.
- FDA 510(k) Predicate Device Strategy:Substantial equivalence determinations require careful navigation of evolving FDA guidance documents specific to obstructive sleep apnea indications and material biocompatibility standards.
- Legacy Practice Management Integration:Sleep medicine clinics and dental practices encounter friction connecting digital appliance workflows with existing electronic health record and billing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Appliance Market |
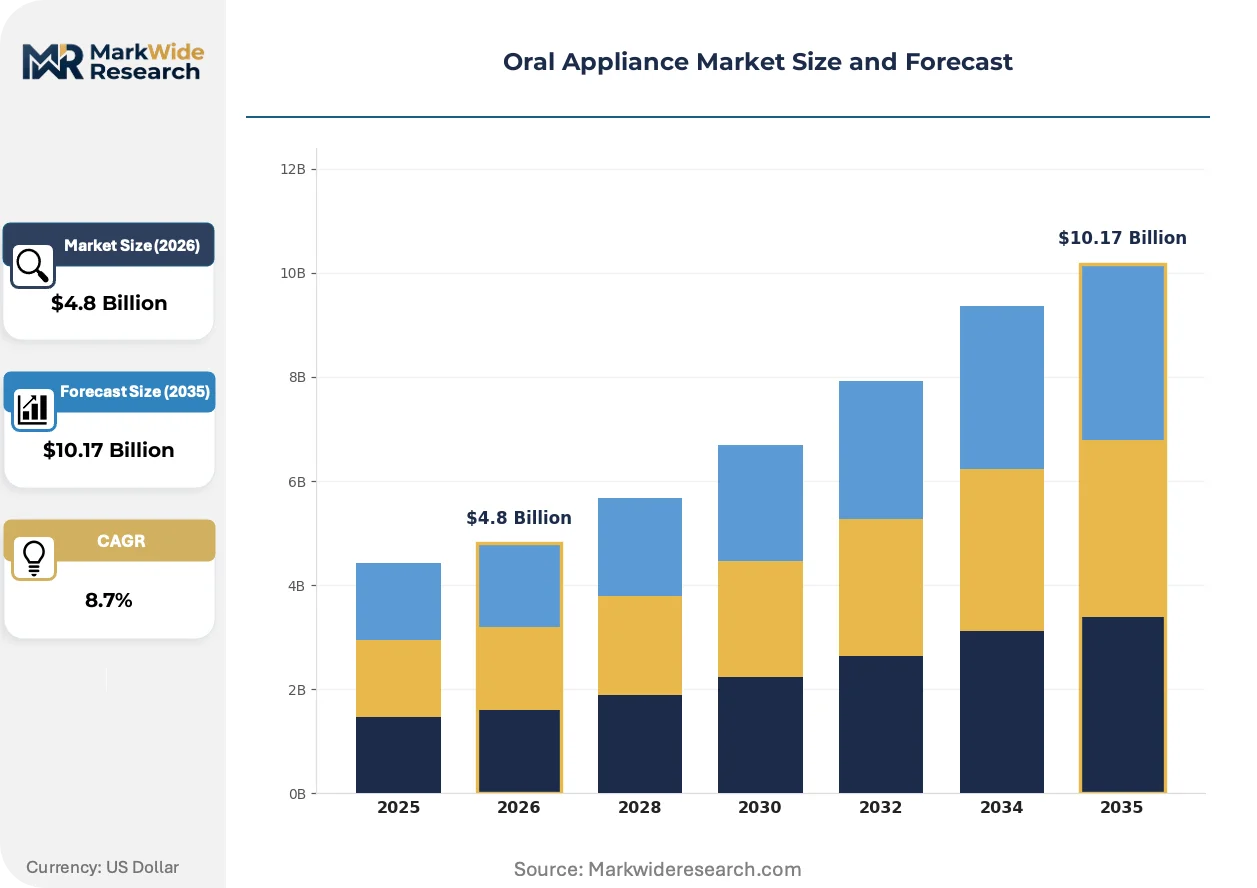
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mandibular Advancement Device, Tongue Retaining Device, Combination Device, Custom Appliance End User: Individuals, Dentists, Sleep Clinics, Hospitals Material: Thermoplastic, Acrylic, Silicone, Metal Application: Sleep Apnea, Snoring, Orthodontic Treatment, Teeth Grinding |
| Companies Covered | ResMed, SomnoMed, ProSomnus Sleep Technologies, Vivos Therapeutics, Glidewell, Whole You, Airway Management, Panthera Dental, DynaFlex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Appliance Market Evolving Landscape
Digital manufacturing convergence with regulatory automation is redrawing competitive boundaries in oral appliance production, compressing the gap between patient scan and delivered therapy while elevating material science and precision tolerances as differentiation vectors.
Precision-milled nylon substrates are bifurcating the custom appliance segment from traditional thermoplastic vacuum-formed alternatives. Dental sleep medicine practices with chairside milling capacity are capturing same-day delivery premiums. This technology is bifurcating market structure into high-throughput digital laboratories and declining conventional fabrication operations.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa sleep apnea devices. Manufacturers must now maintain vigilance systems capturing device performance and adverse events across distributed patient populations. European notified bodies are prioritizing review resources toward submissions with robust post-market clinical follow-up protocols, advantaging established players with dedicated regulatory affairs infrastructure.
Patient acquisition patterns are rotating from specialist referral channels toward direct-to-consumer screening and telehealth consultation models. Sleep technology retailers and online diagnostic platforms are disaggregating traditional sleep clinic gatekeeper functions. This channel fragmentation is most pronounced in United States markets where home sleep testing regulatory clarity and direct-pay appliance models circumvent traditional insurance preauthorization requirements.
Oral Appliance Market Segmentation
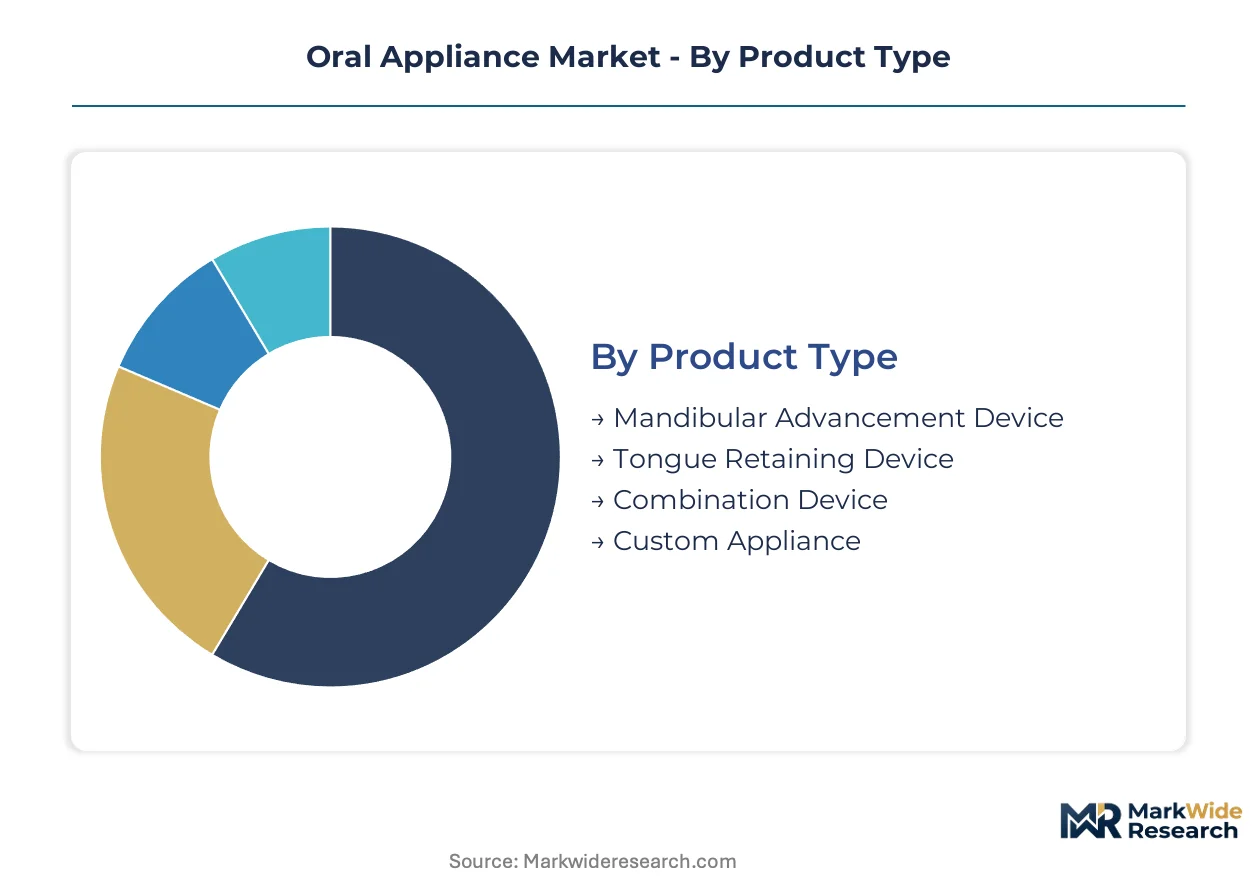
Segmentation in oral appliances determines reimbursement pathways, fabrication workflows, and competitive positioning. Product type and material selection directly influence regulatory classification and clinical indication scope.
Product Type:
Continuous positive airway pressure therapy exerts the strongest substitution pressure on mandibular advancement alternatives, forcing product-level differentiation around comfort and adherence metrics.
- Mandibular Advancement Device:Repositions the lower jaw forward to maintain airway patency using adjustable acrylic or nylon frameworks with 0.25 mm protrusion increments. Demand concentrates in United States dental sleep medicine practices where established CPT reimbursement codes reduce patient cost friction.
- Custom Appliance:Precision-milled from patient-specific digital scans via CAD/CAM workflows, delivering superior fit tolerances and biocompatibility. Fabrication timelines are collapsing from weeks to same-day delivery in chairside-equipped practices.
- Tongue Retaining Device:Suction-based mechanism for edentulous patients excluded from mandibular therapy.
- Combination Device:Hybrid mandibular-tongue repositioning for complex airway anatomy.
Mandibular advancement devices retain volume leadership; custom appliances hold the steepest expansion curve.
End User:
Cost tier stratification separates high-touch clinical delivery from emerging direct-to-consumer channels reshaping patient acquisition economics.
- Dentists:Primary gatekeepers for mandibular advancement therapy with specialized training in dental sleep medicine. United States metropolitan clusters show the highest prescriber density.
- Sleep Clinics:Integrated respiratory therapy settings where oral appliances serve as CPAP alternatives or combination therapy.
- Individuals:Direct-pay purchasers through telehealth screening platforms bypassing traditional insurance preauthorization.
- Hospitals:Acute care settings for perioperative sleep apnea management and surgical candidacy screening.
Dentists dominate prescription volume; sleep clinics are gaining share fastest through respiratory therapy cross-selling.
Material:
Supply concentration in German and Swiss chemical basins creates feedstock vulnerability for precision-milled segments.
- Thermoplastic:Vacuum-formed EVA or copolymer sheets for boil-and-bite or laboratory-fabricated devices. Lower cost position sustains volume in price-sensitive segments.
- Nylon:Medical-grade polyamide substrates for five-axis milled appliances with superior biocompatibility and durability.
- Acrylic:Conventional heat-cured resin for adjustable devices with metal hardware integration.
- Silicone:Soft liner applications for tongue retaining mechanisms and comfort enhancement.
- Metal:Titanium or chrome-cobalt frameworks for edentulous patients requiring skeletal retention.
Thermoplastic materials retain volume leadership; nylon substrates are climbing the fastest on digital workflow adoption.
Application:
Clinical guideline hierarchies and reimbursement scope differentiate addressable market size across indications.
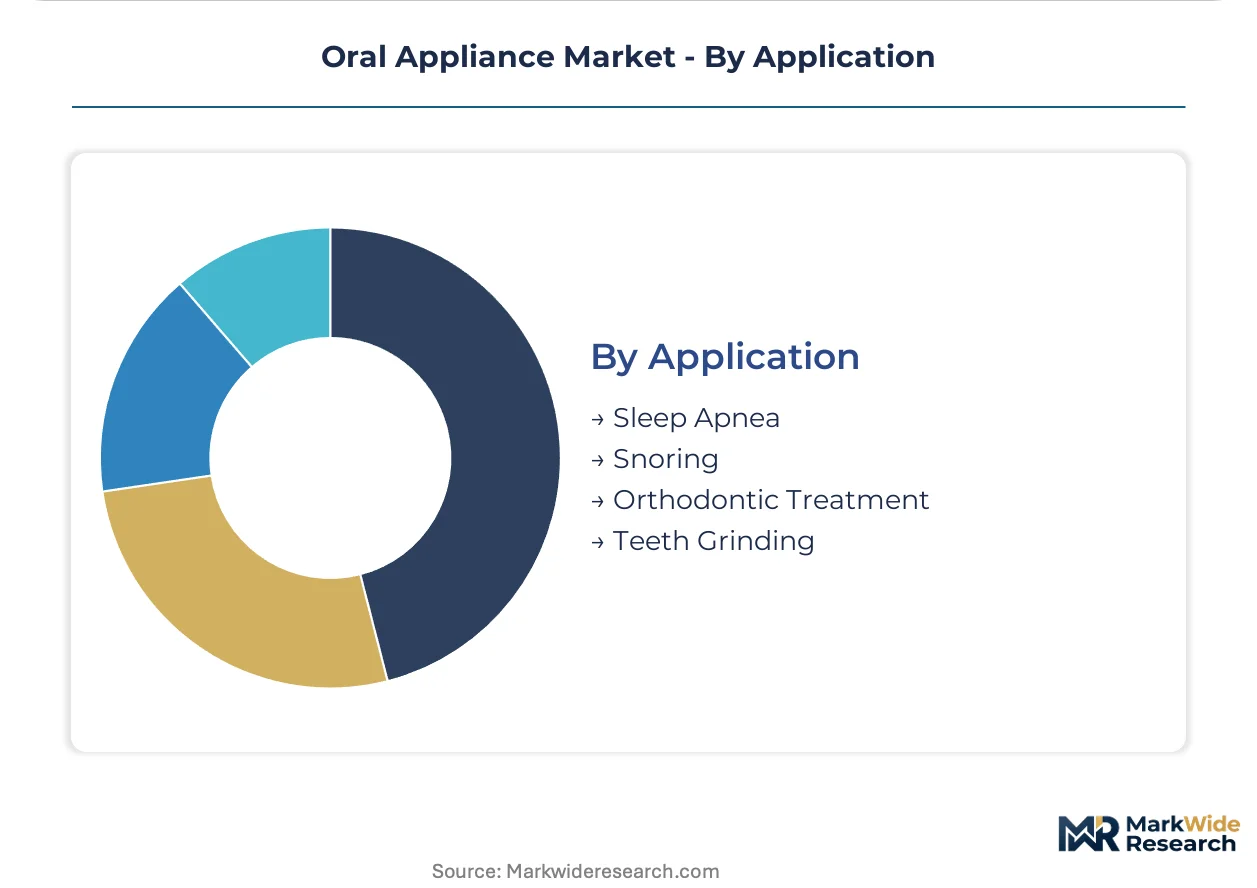
- Sleep Apnea:FDA 510(k) cleared devices for obstructive sleep apnea therapy with established insurance coverage in United States markets. AASM guidelines position oral appliances as first-line for mild-to-moderate cases.
- Snoring:Direct-pay consumer segment with minimal regulatory burden and higher margin profiles.
- Teeth Grinding:Bruxism splints and night guards with overlapping fabrication infrastructure but distinct reimbursement codes.
- Orthodontic Treatment:Myofunctional and habit-breaking appliances with pediatric and adult applications.
Sleep apnea applications retain volume leadership; snoring indications hold the steepest expansion curve on direct-to-consumer channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dental sleep medicine specialists and sleep clinic networks concentrate demand across mature reimbursement environments, with regulatory clearance pathways and prescriber training density determining market penetration depth.
United States
FDA 510(k) clearance pathways and established CPT reimbursement codes drive prescribing velocity among dental sleep medicine specialists. The American Academy of Sleep Medicine guidelines position oral appliances as first-line therapy for mild-to-moderate obstructive sleep apnea. Major metropolitan clusters including Dallas, Houston, and Phoenix show the highest prescriber density per capita.
Germany
EU MDR Class IIa classification imposes clinical evidence and post-market surveillance obligations on manufacturers entering the European market. German dental laboratories concentrate precision-milled nylon device production around Stuttgart and Munich manufacturing basins. The country's statutory health insurance system maintains favorable coverage determinations for mandibular advancement therapy.
Australia
TGA regulatory alignment with FDA standards accelerates product registration timelines for manufacturers with existing US clearances. Direct-to-dentist distribution networks concentrate in Sydney and Melbourne sleep clinic corridors. The national health insurance system provides reimbursement parity between oral appliances and CPAP therapy for eligible patients.
Canada
Health Canada's Medical Devices Bureau maintains review standards comparable to FDA requirements, creating streamlined pathways for cross-border product registration. Provincial reimbursement variations create demand concentration in Ontario and British Columbia dental sleep medicine practices. Toronto and Vancouver host the highest density of trained mandibular advancement device prescribers.
Switzerland
Swissmedic regulatory oversight and medical-grade polymer feedstock concentration attract precision-milled device manufacturers seeking supply chain proximity. Swiss dental technology clusters around Zurich and Basel supply qualified nylon substrates to global appliance fabricators. The country's mandatory health insurance framework covers oral appliance therapy for diagnosed obstructive sleep apnea.
Oral Appliance Market Competitive Landscape
Player mix skews toward respiratory therapy conglomerates with dental sleep medicine cross-selling capabilities, mid-scale precision manufacturers with CAD/CAM integration, and specialized dental laboratory networks with regional fabrication capacity. Three archetypes dominate: vertically integrated sleep therapy ecosystems, digital-native appliance specialists, and conventional dental laboratory intermediaries. Competitive moves concentrate on regulatory clearance portfolio expansion and chairside digital workflow partnerships.
Within the respiratory therapy ecosystem tier, ResMed exemplifies cross-selling integration through sleep clinic network penetration. SomnoMed anchors the direct-to-dentist distribution archetype with established geographic presence across Europe and Australia. ProSomnus Sleep Technologies occupies a position representing precision-milled nylon specialization and digital workflow integration. These three companies illustrate the strategic segmentation between scale-driven respiratory conglomerates, regionally focused distribution specialists, and technology-differentiated precision manufacturers.
| Leading Market Players |
|---|
| ResMed |
| SomnoMed |
| ProSomnus Sleep Technologies |
| Vivos Therapeutics |
| Glidewell |
| Whole You |
| Airway Management |
| Panthera Dental |
| DynaFlex |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways and ISO 13485 certification requirements simultaneously gate supply qualification and stratify price tiers across the oral appliance market. Manufacturers bearing these regulatory burdens capture premium positioning against uncertified competitors while facing compressed margins from accelerated certification timelines.
Pricing Analysis
Cost-plus contracts with medical-grade nylon feedstock indexation dominate precision-milled device procurement. Three-tier pricing structure across premium CAD/CAM-customized, standard laboratory-fabricated, and economy thermoplastic boil-and-bite levels reflects certification grade and vertical integration depth. Pricing pressure stems from collapsing ISO 13485 timelines compressing competitive moats. Individual direct-pay purchasers exhibit highest price sensitivity; hospital systems and integrated sleep clinic networks demonstrate lowest sensitivity due to reimbursement pass-through structures.
Supply Chain Analysis
Germany and Switzerland anchor medical-grade polyamide production for precision-milled appliances, with Stuttgart and Basel chemical basins supplying qualified feedstock globally. Device fabrication draws from German milling equipment, Swiss polymer substrates, and United States digital scanning hardware. Single-source vulnerability concentrates in qualified nylon suppliers subject to REACH regulatory restrictions. Distribution runs through direct-to-dentist networks in established markets and sleep clinic cross-selling channels in integrated respiratory therapy settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral appliance penetration sits at early-cycle expansion, propelled by CAD/CAM workflow adoption collapsing patient-to-device timelines from weeks toward same-day delivery.
For Market Incumbents: Compound regulatory clearance portfolios through parallel FDA 510(k) and EU MDR submission strategies. Deepen backward integration into medical-grade nylon supply through captive relationships with Stuttgart and Basel chemical producers. CPAP therapy ecosystems pose acute substitution threat through respiratory therapy cross-selling; defend through chairside digital workflow partnerships that accelerate delivery velocity beyond hospital-based alternatives.
For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest regulatory validation for mandibular advancement devices. Target edentulous patient segments excluded from mandibular therapy through tongue retaining device specialization. Australian TGA alignment with FDA standards enables geographic diversification with minimal incremental regulatory investment. Telehealth-integrated direct-to-consumer screening platforms provide lowest-friction patient acquisition channel.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across chairside CAD/CAM-equipped dental practices, enabling scalable asset-light deployment models. Five-to-ten year viability favors precision-milled specialists with integrated digital workflows over conventional thermoplastic fabricators facing obsolescence. Acquisition target archetype: mid-scale manufacturers with ISO 13485 certification and established dentist relationships. Monitor FDA 510(k) clearance velocity as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Accelerates US market entry for sleep apnea indications through predicate device strategies. |
| EU MDR Clinical Evidence Investment | Satisfies Class IIa post-market surveillance obligations for European notified body prioritization. |
| Chairside Digital Workflow Partnership | Captures same-day delivery premiums through intraoral scanning and five-axis milling convergence. |
| Medical-Grade Polymer Supply Agreement | Secures qualified nylon feedstock from German and Swiss chemical production basins. |
| Sleep Clinic Network Integration | Enables respiratory therapy cross-selling through established CPAP patient pipelines. |
Research Methodology
Operator-level perspectives from dental sleep medicine practitioners, CAD/CAM laboratory technicians, regulatory affairs specialists at device manufacturers, and sleep clinic medical directors anchored the qualitative base. Primary interviews triangulated with secondary validation from FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, TGA registration records, and CMS reimbursement code determinations. Bottom-up patient volume estimates and top-down market sizing converged through iterative cross-checking against dental laboratory production capacity and sleep clinic prescribing data.
Sensitivity analysis tested forecast robustness across certification timeline scenarios, CAD/CAM adoption curves, and CPAP substitution pressure intensities. Segmentation dimensions modeled include product type, material substrate, end-user channel, and application indication across the projection horizon. CAGRs derived from regression analysis of historical reimbursement code expansion, prescriber training program proliferation, and digital manufacturing equipment installation trends. Industry-specific inputs incorporated ISO 13485 certification velocity and FDA 510(k) clearance cycle compression.
Decision-makers should treat outputs as directional under assumptions of stable CPT reimbursement codes and continued CAD/CAM adoption acceleration; material deviation in FDA guidance or EU MDR enforcement stringency would warrant model refresh. Specific risks include biocompatible nylon supply disruption, CPAP therapy guideline revisions elevating first-line status, and direct-to-consumer channel regulatory restriction. Recalibration cycles align with material shifts in reimbursement determinations and digital workflow penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Memory Implants Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market