
 North America Laser Hair Removal Market | 2026-2036
North America Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laser Hair Removal Market Analytics
Diode laser arrays is rebalancing capital costs against treatment efficiency across the North America laser hair removal landscape. Candela Medical leverages its installed base of Alexandrite platforms to sustain recurring revenue from consumables and service contracts. Cutera competes through multi-modality workstations that anchor cross-selling opportunities in skin rejuvenation. Alma Lasers dominates the mid-market segment with portable diode systems that extend practice reach into secondary cities.
Laser hair removal employs selective photothermolysis where melanin in hair follicles absorbs concentrated light energy at wavelengths between 755 nm and 1064 nm, destroying the bulb while sparing surrounding tissue through controlled pulse duration and cooling mechanisms. The diode laser segment leads procedure volumes due to its efficacy across broader skin phototypes, while the ND:YAG laser category captures demand from darker skin populations previously excluded from treatment. Clinics and medical spas represent the primary end-user channel where per-session economics favor high-utilization platforms, though at-home devices are fragmenting the maintenance-treatment margin pool.
FDA device classification under 21 CFR 878.4810 governs laser hair removal system safety and efficacy claims, while state medical boards in California, Texas, and Florida regulate operator certification and supervision requirements. Health Canada Medical Device Licensing imposes parallel electromagnetic compatibility and biocompatibility standards that manufacturers must satisfy for cross-border commercialization. Stakeholders should monitor evolving state-level scope-of-practice debates that could expand or restrict technician-performed procedures.
Market Dynamics
Diode laser wavelength refinement is compressing treatment times while broadening addressable skin phototypes, forcing device manufacturers to recalibrate platform economics around throughput rather than per-session pricing power.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance for incremental wavelength modifications reduces time-to-market for next-generation systems, incentivizing R&D investment in tunable diode arrays.
- Medical spa channel expansion:Non-physician operators in Texas and Florida scope-of-practice frameworks are extending service availability beyond traditional dermatology clinic footprints.
- Post-pandemic deferred demand normalization:Appointment backlogs in California aesthetic practices are converting consultation inquiries into multi-session treatment packages at elevated booking rates.
Market Restraints
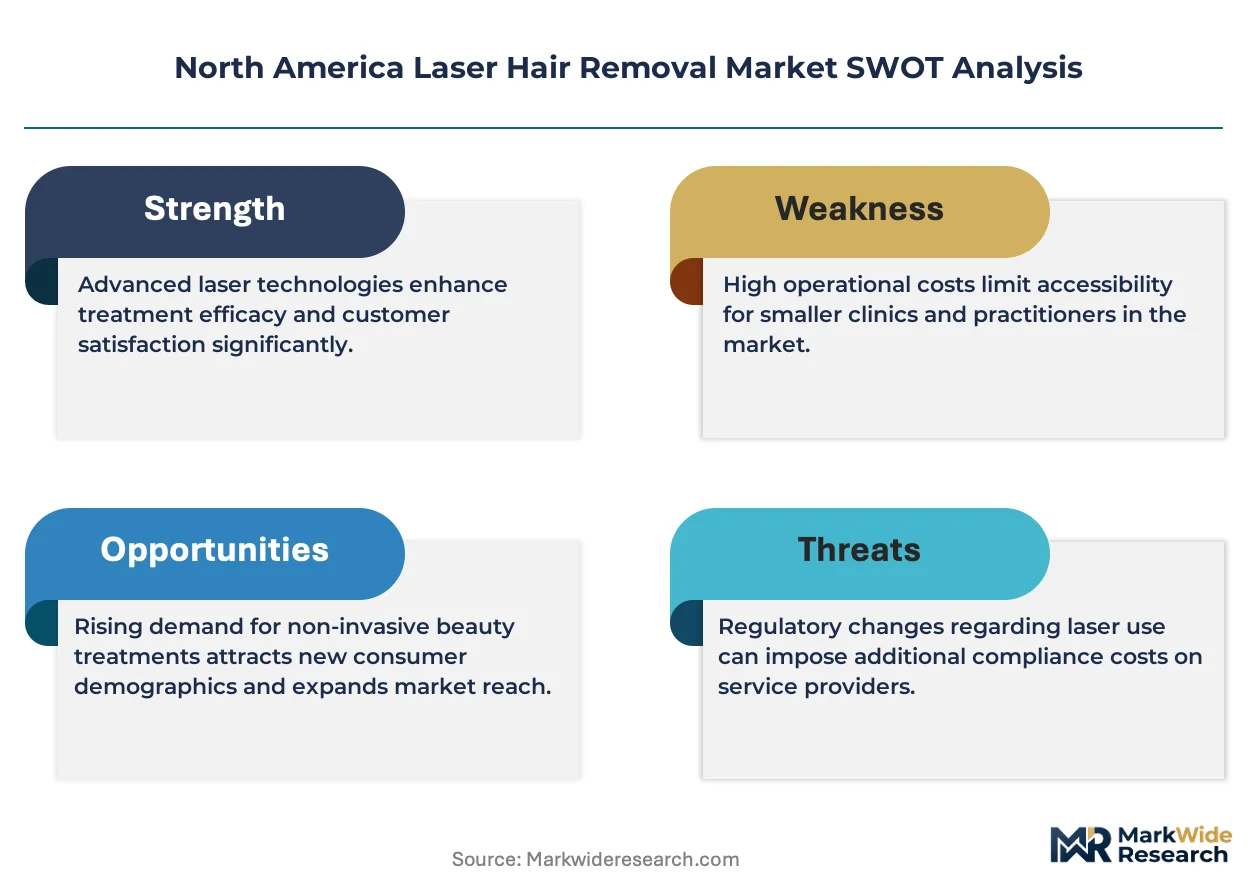
- Consumables cost concentration:Single-source supply of sapphire cooling tips and replacement handpieces from German and Israeli component houses creates margin pressure during currency volatility.
- Technical efficacy ceiling on fine vellus hair:Melanin-deficient follicles resist photothermal destruction across all commercially available wavelengths, limiting addressable anatomy for facial procedures.
- State-level supervision variance:California's physician oversight requirements impose higher labor costs than Texas direct-access models, fragmenting clinic operating economics across jurisdictions.
Strategic Opportunities
- Canadian provincial coverage expansion:Ontario and British Columbia are piloting selective cosmetic procedure insurance carve-outs for hirsutism-related diagnoses, opening institutional reimbursement channels.
- At-home maintenance device convergence:Integration of IPL technology with smartphone-guided treatment protocols is capturing between-session touch-up revenue previously retained by clinic operators.
- Men's grooming vertical penetration:Back and chest hair removal protocols are penetrating athletic and corporate professional segments previously underserved by female-skewed marketing.
Industry Challenges
- Laser safety officer certification bottlenecks:State medical boards in high-volume jurisdictions face inspection backlog delays of six to nine months for new facility approvals.
- Legacy Alexandrite platform obsolescence risk:Clinics holding fully depreciated 755 nm systems face capex replacement decisions amid diode platform performance convergence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laser Hair Removal Market |
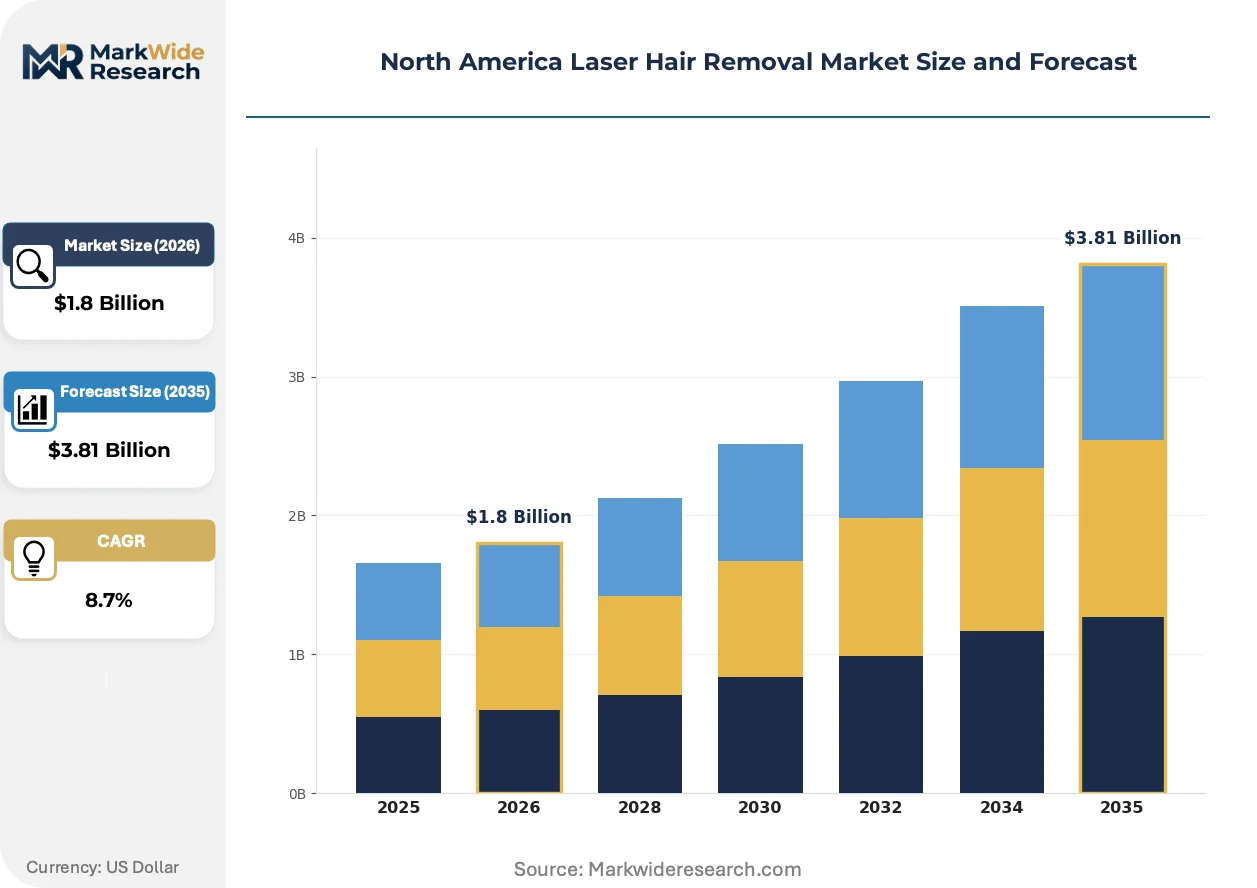
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Laser, Alexandrite Laser, ND:YAG Laser, Ruby Laser End User: Clinics, At-home Users, Salons, Hospitals Technology: Pulsed Light, Fractional Laser, Continuous Wave, Intense Pulsed Light Application: Facial Hair Removal, Body Hair Removal, Skin Rejuvenation, Hair Growth Reduction |
| Companies Covered | Cynosure, Candela Medical, Cutera, Lumenis, Alma Lasers, Sciton, Venus Concept, Lutronic Corporation, Bausch Health Companies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laser Hair Removal Market Evolving Landscape
Wavelength multiplexing and real-time skin cooling advances are redefining treatment protocols across the North American aesthetic device landscape, compressing session intervals while elevating safety margins for darker skin phototypes.
Triple-wavelength diode systems combining 755 nm, 810 nm, and 1064 nm outputs in single handpieces are expanding into high-volume medical spa chains seeking to minimize device count per treatment room. California and Texas operators are standardizing on these platforms to reduce technician training complexity across diverse client demographics. The technology is expanding into price-competitive secondary markets where capital efficiency constraints previously excluded multi-device configurations.
FDA's evolving guidance on substantial equivalence determinations for laser hair removal devices is compressing 510(k) review timelines for manufacturers demonstrating predicate device similarity. Health Canada's parallel Medical Device Single Audit Program recognition is enabling synchronized US-Canada market entry for compliant OEMs. Smaller device manufacturers with limited regulatory affairs staffing are outsourcing submission preparation to specialized consultancies to navigate this accelerated pathway.
Subscription-based equipment leasing models are displacing outright purchase arrangements among independent dermatology practices and emerging medical spa operators. Device manufacturers and third-party medical equipment financiers are capturing recurring revenue streams through per-procedure usage fees bundled with maintenance and software updates. This financing structure is most visible in Florida and Arizona markets where rapid clinic formation outpaces traditional capital access for physician entrepreneurs.
North America Laser Hair Removal Market Segmentation
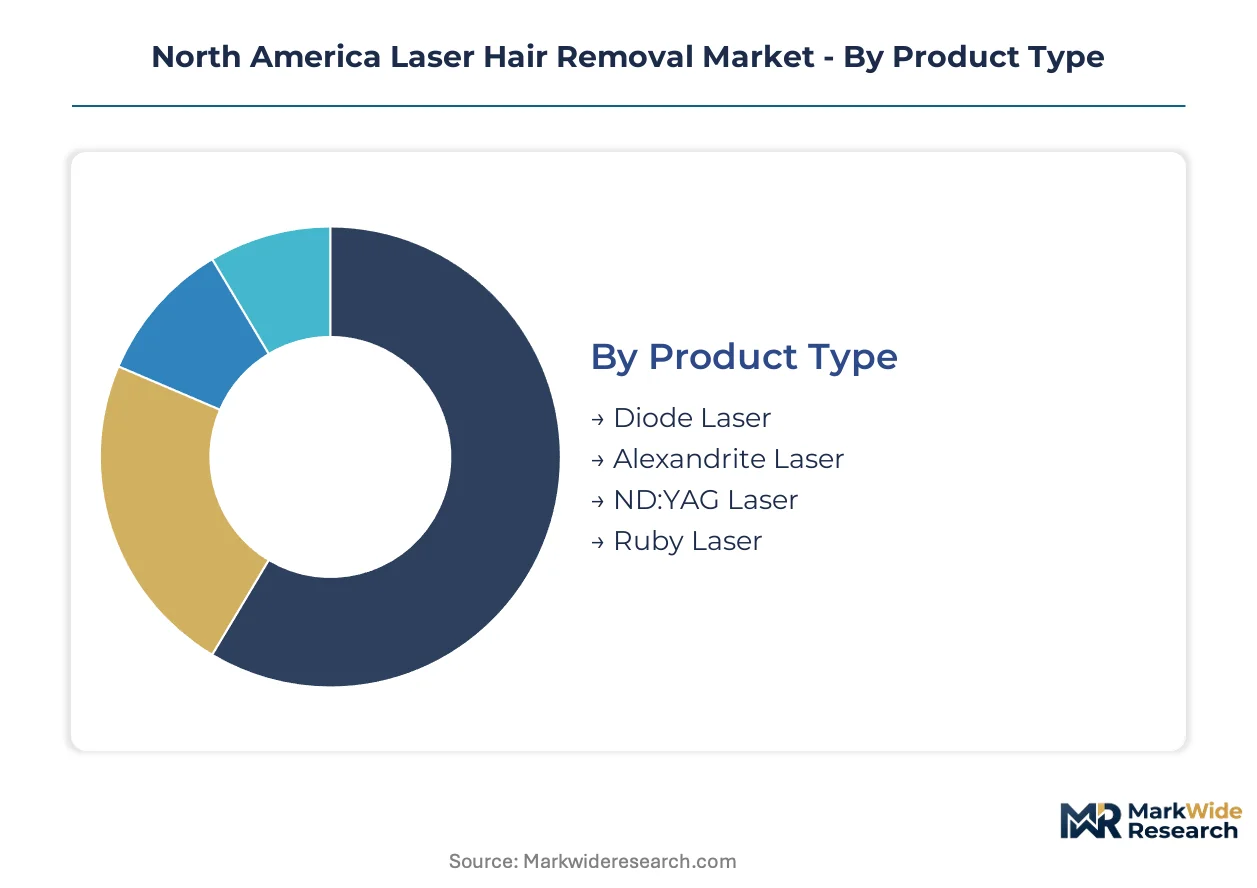
Segmentation in the North America laser hair removal market reveals how technology specifications, operator settings, and treatment protocols fragment purchasing decisions across distinct buyer profiles. Equipment manufacturers calibrate platform features to match the divergent capital constraints and throughput requirements of medical spas, dermatology clinics, and direct-to-consumer channels.
Product Type:
Customization intensity varies sharply across laser platforms, with tunable wavelength systems commanding premium positioning against fixed-configuration alternatives.
- Diode Laser:These 800-810 nm semiconductor arrays deliver consistent melanin absorption across broader skin phototypes through adjustable pulse widths and integrated contact cooling. Texas and Florida medical spa chains are consolidating procurement around diode platforms to simplify technician training and reduce device inventory per treatment room. The segment captures the majority of new capital deployment where operators prioritize versatility over wavelength specialization.
- Alexandrite Laser:Chromium-doped alexandrite crystals generate 755 nm output with exceptional efficacy on lighter skin types, though melanin-rich populations require careful parameter adjustment. California dermatology practices with established client bases in higher Fitzpatrick skin types are retaining these systems for specific anatomical applications where speed advantages justify dedicated platform investment.
- ND:YAG Laser:Neodymium-doped yttrium aluminum garnet systems operating at 1064 nm penetrate deeper with reduced epidermal absorption, serving darker skin phototypes previously excluded from laser hair removal protocols.
- Ruby Laser:The original 694 nm laser hair removal technology retains niche utilization for fine hair applications where shorter wavelengths optimize follicular targeting, though thermal injury risks constrain addressable demographics.
Most installed capacity flows through Diode Laser platforms. Expansion is steepest in ND:YAG Laser configurations as previously underserved patient populations enter the addressable market.
End User:
Capital intensity and regulatory exposure separate institutional purchasers from direct-to-consumer acquisition patterns.
- Clinics:Dermatology and aesthetic medicine practices deploy Class II medical laser systems under physician supervision, with California's oversight requirements imposing higher operational compliance costs than Texas direct-access frameworks. These operators concentrate procedure volume and capture premium pricing through medical credentialing.
- At-home Users:FDA-cleared IPL devices and lower-energy diode systems penetrate the maintenance-treatment segment, with smartphone-guided protocols reducing operator error risks for unsupervised consumers.
- Salons:Non-medical aesthetic operators in states with permissive scope-of-practice regulations are expanding service menus, though supervision requirements fragment operating economics across jurisdictions.
- Hospitals:Academic medical centers and integrated health systems deploy laser hair removal for hirsutism-related diagnoses, with Ontario and British Columbia piloting selective insurance carve-outs for these indications.
Revenue concentration sits with Clinics. At-home Users are gaining share fastest as device manufacturers capture between-session touch-up revenue previously retained by professional operators.
Technology:
Energy delivery mechanisms differentiate treatment protocols across precision, speed, and safety margin requirements.
- Pulsed Light:Q-switched and long-pulse modalities concentrate energy delivery into microsecond-to-millisecond bursts, enabling selective photothermolysis while minimizing thermal diffusion to surrounding tissue.
- Fractional Laser:Microbeam array technology creates microscopic treatment zones with intervening intact tissue, accelerating recovery timelines for combination hair removal and skin rejuvenation protocols.
- Continuous Wave:Sustained energy output configurations serve specific research and specialized clinical applications where precise thermal control outweighs speed considerations.
- Intense Pulsed Light:Broadband filtered flashlamp systems span 500-1200 nm with adjustable cut-off filters, offering cost advantages for multi-application platforms though with reduced specificity compared to monochromatic lasers.
Pulsed Light dominates professional installation bases. Intense Pulsed Light is expanding most quickly in at-home device categories where manufacturing cost constraints favor non-laser optical sources.
Application:
Anatomical treatment zones and intended outcomes drive handpiece configuration and parameter selection across the installed base.
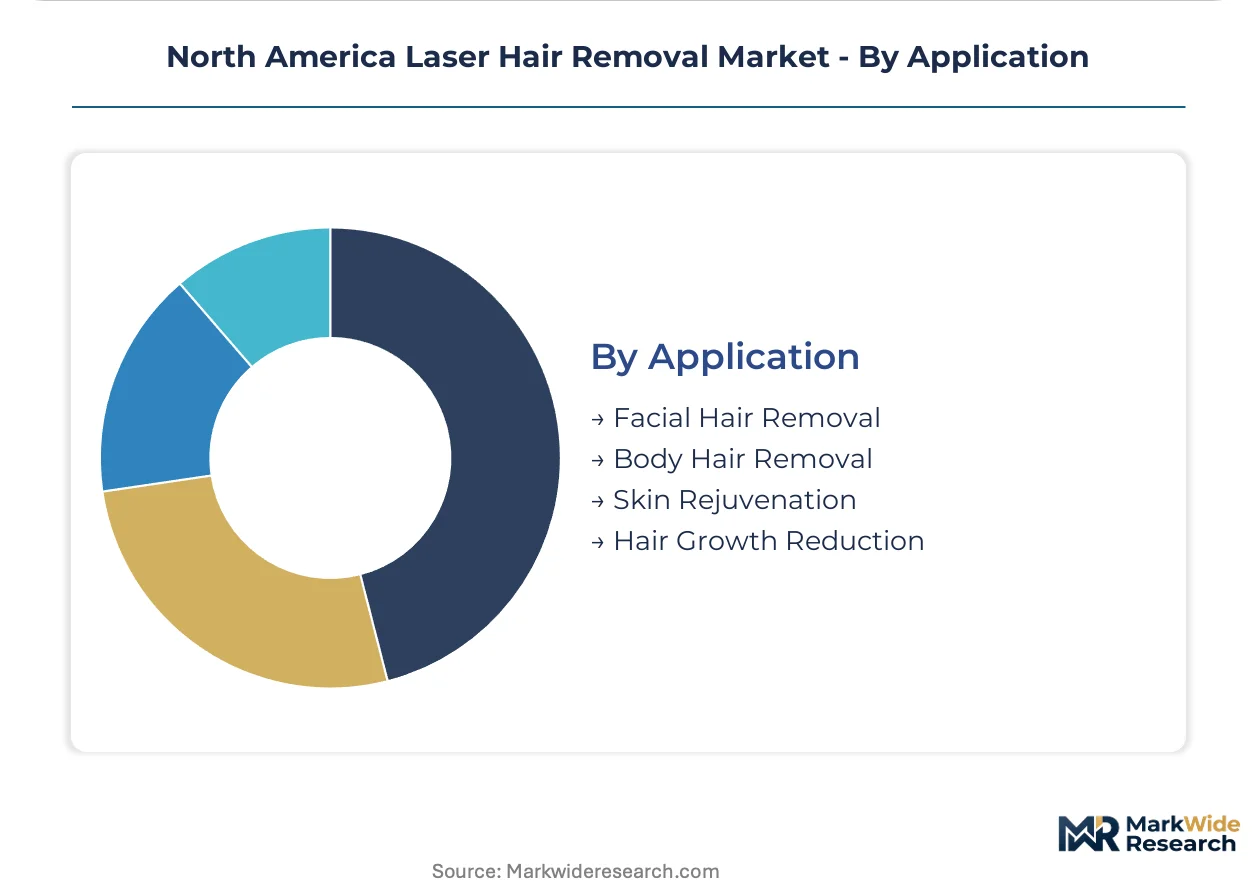
- Facial Hair Removal:Smaller spot sizes and enhanced cooling mechanisms address the curved anatomy and heightened sensitivity of upper lip, chin, and sideburn regions, where fine vellus hair resistance limits efficacy across available wavelengths.
- Body Hair Removal:Large-area protocols for back, chest, and leg applications prioritize speed and coverage efficiency, with men's grooming verticals penetrating athletic and corporate professional segments previously underserved by female-skewed marketing.
- Skin Rejuvenation:Combination platforms leverage hair removal handpieces for photorejuvenation applications, capturing incremental revenue per device through cross-selling opportunities.
- Hair Growth Reduction:Maintenance protocols between complete removal cycles represent recurring revenue streams, though at-home device convergence is fragmenting this margin pool.
Body Hair Removal commands the largest procedure volume base. Facial Hair Removal is climbing the fastest as male demographic penetration accelerates and precision protocol refinements expand addressable anatomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Los Angeles-San Francisco corridor anchors aesthetic device deployment density across North America, with clinic formation rates exceeding national averages by substantial margins. California, Texas, and Florida concentrate the majority of installed laser hair removal capacity. Canadian provincial markets are accelerating catch-up growth as regulatory harmonization reduces cross-border commercialization friction.
United States
California dermatology practices and Texas medical spa chains drive procedure volume through divergent operating models shaped by state supervision requirements. FDA 510(k) clearances for new diode wavelengths accelerate faster than Health Canada parallel reviews, compressing time-to-market for domestic manufacturers. The Miami-Fort Lauderdale corridor in Florida exhibits the highest medical spa density per capita, with subscription-based equipment leasing displacing outright purchase arrangements among new entrants.
Canada
Ontario and British Columbia are piloting selective insurance carve-outs for hirsutism-related laser hair removal diagnoses, opening institutional reimbursement channels previously confined to cosmetic self-pay. Health Canada Medical Device Licensing imposes electromagnetic compatibility and biocompatibility standards that manufacturers must satisfy for cross-border commercialization. Toronto and Vancouver aesthetic clinic networks are standardizing on triple-wavelength diode platforms to minimize device inventory per treatment room.
Mexico
Medical tourism corridors in Baja California and Mexico City are capturing price-sensitive demand from US border states, with Tijuana clinics reporting elevated cross-border consultation volumes. COFEPRIS medical device registration creates parallel regulatory requirements for manufacturers seeking market access outside the USMCA framework. Guadalajara's emerging aesthetic device distribution hubs are consolidating procurement for Central American affiliate clinics.
North America Laser Hair Removal Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers seek to anchor recurring revenue streams through service contracts and consumables supply. The vendor base exhibits moderate concentration, with established aesthetic laser specialists holding installed base advantages against emerging challengers. Three archetypes populate the competitive terrain: wavelength-specialized platform developers, multi-modality workstation integrators, and mid-market portable system suppliers. Technology licensing agreements and subscription-based equipment financing represent the dominant competitive moves reshaping capital deployment patterns among clinic operators.
Within the wavelength-specialized tier, Cynosure and Candela Medical occupy positions anchored by extensive installed bases of Alexandrite and diode platforms. Cutera exemplifies the multi-modality workstation approach, with its corporate structure supporting cross-selling architectures that bundle hair removal with skin rejuvenation applications. Alma Lasers represents the mid-market portable system archetype, with its geographic nomenclature indicating Israeli origins and its product positioning targeting secondary city expansion where capital efficiency constraints exclude multi-device configurations.
| Leading Market Players |
|---|
| Cynosure |
| Candela Medical |
| Cutera |
| Lumenis |
| Alma Lasers |
| Sciton |
| Venus Concept |
| Lutronic Corporation |
| Bausch Health Companies |
| Others |
Value Network & Pricing Analysis
Certified laser safety officers concentrated in California, Texas, and Florida command wage premiums that widen pricing spreads between premium dermatology clinics and economy medical spa chains. Labor-cost differentials across state supervision regimes separate three-tier pricing structures where physician-supervised California operators extract premium rates against direct-access Texas models.
Pricing Analysis
Input-cost pass-through from German and Israeli sapphire cooling tip suppliers compresses margins on consumables-dependent service contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared triple-wavelength platforms from fixed-configuration diode systems and at-home IPL maintenance devices. Pricing pressure stems from subscription-based equipment leasing displacing outright purchases among Florida and Arizona clinic formations. Price-sensitive independent medical spa operators in secondary cities drive economy-tier volume, while established California dermatology practices exhibit lowest sensitivity due to entrenched client bases.
Supply Chain Analysis
Domestic-content mandates under USMCA rules of origin reshape sourcing for diode laser arrays and handpiece assemblies. Component manufacturing concentrates in Israel, Germany, and the United States for optical crystals, semiconductor arrays, and cooling systems. Raw material dependencies span neodymium-doped yttrium aluminum garnet crystals, chromium-doped alexandrite, and sapphire substrates. Single-source vulnerability from Israeli component houses creates exposure during currency volatility episodes. Distribution runs through authorized medical device distributors with FDA establishment registration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA 510(k) pathway acceleration for incremental wavelength modifications continuously expands addressable treatment populations and sustains equipment refresh cycles.
For Market Incumbents: Acquire installed base service contracts from distressed independent clinics in Florida and Arizona subscription-leasing markets. Consolidate aftermarket consumables supply positions against emerging third-party sapphire tip manufacturers. Reinforce technician certification program control to lock in recurring training revenue streams.
For New Entrants and Emerging Players: Begin with portable diode platforms targeting Canadian secondary cities where Health Canada harmonization reduces regulatory entry costs. Exploit white-space in Ontario and British Columbia institutional reimbursement pilots for hirsutism-related diagnoses. Pursue smartphone-guided at-home device protocols capturing between-session maintenance revenue.
For Investors and Strategic Acquirers: Medical device manufacturers with aesthetic portfolio gaps are the most active acquirer in this space, seeking wavelength-specialized platform developers to fill modality holes. Long-term viability hinges on recurring consumables attachment rates rather than upfront equipment sales. Monitor Health Canada provincial coverage expansion signals as inflection indicators for institutional reimbursement channel development.
| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Wavelength Platform Launch | Consolidates device inventory for Texas medical spa chains seeking demographic versatility. |
| Subscription Equipment Leasing | Captures recurring revenue from Arizona physician entrepreneurs with constrained capital access. |
| FDA 510(k) Submission Acceleration | Compresses time-to-market for diode wavelength refinements against predicate device benchmarks. |
| Health Canada Synchronization | Enables parallel US-Canada commercialization through Medical Device Single Audit Program recognition. |
| At-Home IPL Companion Development | Fragments clinic-retained maintenance revenue through smartphone-guided consumer protocols. |
Research Methodology
Multiple input streams — primary interviews with device manufacturers, clinical operators, and regulatory consultants, secondary validation through FDA 510(k) databases and Health Canada Medical Device Licensing records, and trade flow analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder discussions encompassed biomedical engineers at dermatology practices, medical spa chain procurement directors, GPO contracts managers for hospital systems, and regulatory affairs specialists at aesthetic device OEMs. Secondary sources included FDA Establishment Registration and Device Listing databases, Health Canada MDALL records, state medical board scope-of-practice filings, and medical equipment financing disclosure documents.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed laser technology type, end-user channel, energy delivery mechanism, and anatomical application zone. CAGRs were derived from equipment shipment trajectories, procedure volume estimates, and capital deployment patterns across clinic formation rates. Industry-specific forecast inputs captured FDA clearance velocity for new wavelengths and provincial reimbursement pilot expansion timelines in Canada.
Caveats apply where Health Canada provincial coverage decisions or state-level scope-of-practice regulatory shifts could materially shift the outlook. Forecasts reflect assumptions around consumables supply chain stability and technician certification pipeline throughput. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Posture Correction Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market