
 Global Dental Suture Market | 2026-2036
Global Dental Suture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Suture Market Foresight
CE marking under the EU Medical Device Regulation is collapsing the competitive field for non-European manufacturers seeking European dental clinic access. B. Braun Melsungen AG leverages its vertically integrated polymer production to control raw material quality for absorbable sutures. Ethicon US, LLC anchors its position through extensive surgeon training programs that lock in institutional purchasing loyalty across academic dental hospitals.
Dental sutures are sterile, thread-like implantable devices manufactured from natural or synthetic polymers, typically ranging from 3-0 to 6-0 in diameter, designed to approximate soft tissue margins following oral surgical procedures and maintain wound closure during the critical 7-14 day healing phase. Absorbable polyglactin variants lead volume due to their predictable tensile strength retention and hydrolytic degradation profile that eliminates removal appointments. Monofilament constructions command premium positioning in implant dentistry applications where bacterial wicking resistance determines infection outcomes and long-term graft survival.
FDA 510(k) clearance requirements and the EU MDR's reinforced clinical evidence standards are elevating compliance costs, filtering smaller manufacturers from premium segments while accelerating consolidation among firms with dedicated regulatory affairs infrastructure. Japan's PMDA enforces JIS-compliant biocompatibility testing that adds six-to-twelve months to market entry timelines for foreign suture suppliers. Stakeholders must monitor evolving polymer biocompatibility standards and surgeon preference shifts toward barbed configurations that reduce operative time in high-volume oral surgery settings.
Market Dynamics
Polymer innovation cycles and regulatory clearance pathway compression are restructuring competitive access barriers, concentrating procurement authority within hospital-affiliated oral surgery networks that now dictate suture specification standards.
Growth Catalysts
- Implant dentistry volume expansion:Oral surgery centers in the United States, Germany, and China are expanding suture procurement to match rising guided bone regeneration and immediate implant placement procedures.
- FDA 510(k) pathway streamlining:The FDA's updated Class II medical device clearance frameworks are reducing time-to-market for novel absorbable polymer formulations, accelerating product refresh cycles.
- CE marking concentration effects:EU MDR compliance requirements are filtering non-European manufacturers from European dental clinic access, creating protected market pockets for certified suppliers.
Market Restraints
- Raw material supply concentration:High-grade polyglactin and poliglecaprone feedstocks concentrate among three specialty chemical suppliers, exposing suture manufacturers to input cost volatility.
- Clinical evidence burden escalation:EU MDR's reinforced clinical evidence standards and Japan's PMDA biocompatibility testing requirements are extending market entry timelines by six-to-twelve months for foreign entrants.
- Monofilament technical limitations:Current synthetic monofilament constructions exhibit reduced knot security compared to braided alternatives, limiting adoption in high-tension wound closure applications.
Strategic Opportunities
- Barbed suture penetration gaps:Self-anchoring barbed configurations remain underpenetrated in high-volume oral surgery settings outside the United States, presenting first-mover expansion potential.
- India's dental infrastructure buildout:India's PLI scheme for medical devices and expanding private dental hospital chains are creating new procurement entry points for compliant suppliers.
- Antimicrobial polymer convergence:Integration of triclosan or chlorhexidine coatings with absorbable base polymers addresses infection resistance demands in implant dentistry applications.
Industry Challenges
- Regulatory affairs talent scarcity:Firms face acute shortages of specialists capable of navigating simultaneous FDA 510(k), EU MDR, and Japan PMDA submission requirements.
- Polymer biocompatibility certification lag:Evolving ISO 10993 testing protocols and updated cytotoxicity standards are forcing reformulation cycles that compress product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Suture Market |
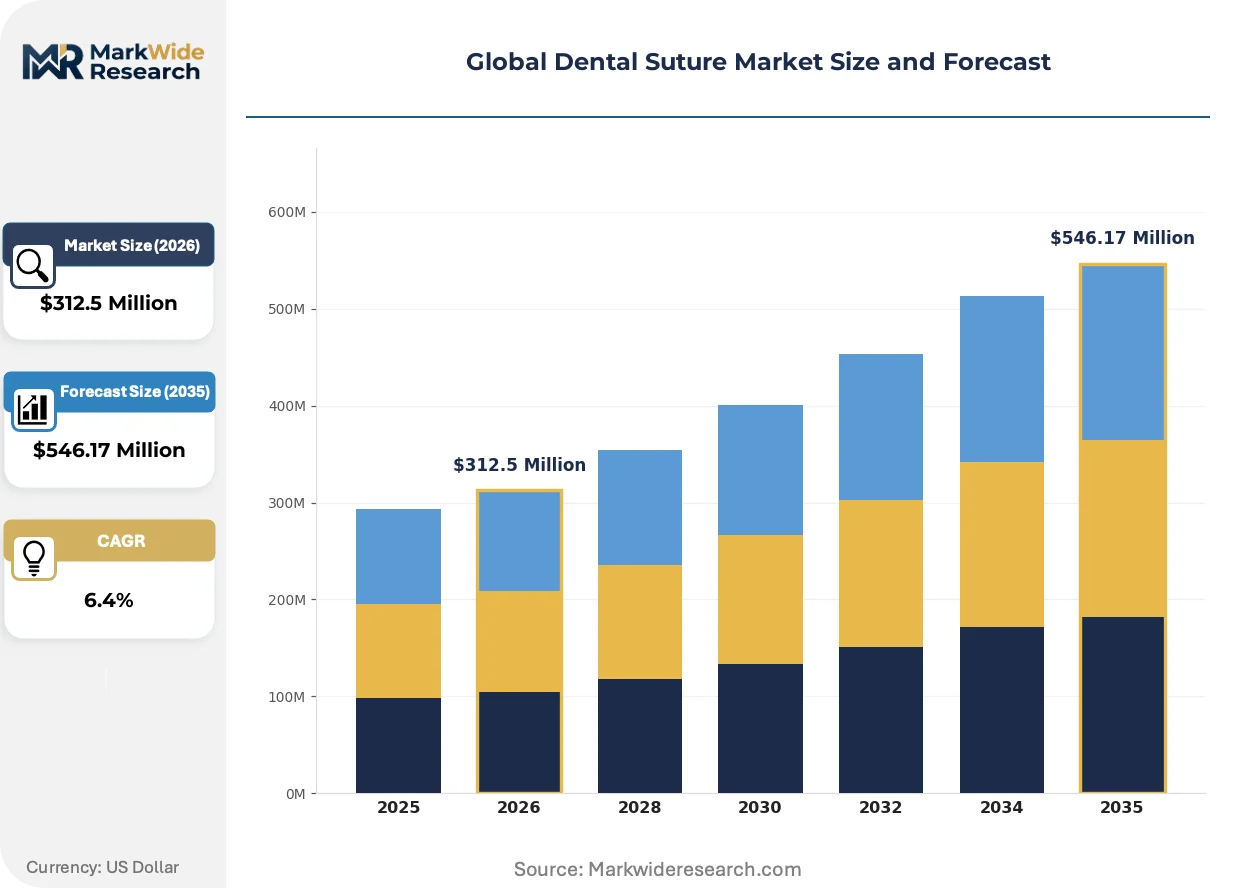
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-Absorbable, Barbed, Multifilament, Monofilament Material: Silk, Polyglactin, Polyglycolic Acid, Nylon, Polyester, Catgut Application: Periodontics, Endodontics, Oral Surgery, Implant Dentistry, Orthodontics End User: Dental Clinics, Oral Surgeons, Academic Institutions, Dental Laboratories |
| Companies Covered | Advanced Medical Solutions Group PLC, Assut Europe S.p.A., B. Braun Melsungen AG, Osteogenics Biomedical, Surgical Specialties Corporation, Ethicon US, LLC, Teleflex Incorporated, Shandong Sinorgmed Co., Ltd, DemeTECH Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Suture Market Shifts & Advancements
Active polymer engineering and surgeon workflow optimization are converging to redefine suture performance benchmarks, with infection resistance and operative efficiency emerging as the decisive competitive dimensions.
Antimicrobial-coated absorbable polymers are fragmenting the traditional suture value proposition. Polyglactin variants incorporating triclosan or ionic silver demonstrate measurable bacterial load reduction in peri-implant soft tissue models. Oral surgery departments in academic medical centers are specifying these formulations for immediate implant protocols where infection determines graft survival outcomes.
EU MDR's reinforced clinical evidence standards are elevating compliance infrastructure as a competitive moat. The regulation's requirement for post-market surveillance systems and notified body recertification is filtering smaller manufacturers from premium segments. German and Swiss dental clinics are consolidating procurement around suppliers with dedicated regulatory affairs capabilities and established quality management systems.
Surgeon preference is pivoting toward barbed configurations that eliminate knot-tying steps in high-volume settings. Self-anchoring polydioxanone and polyglyconate monofilaments reduce operative time in full-arch reconstruction and multiple extraction cases. This behavioral shift is most visible in United States metropolitan hospital networks where case throughput directly determines departmental revenue allocation.
Global Dental Suture Market Segmentation
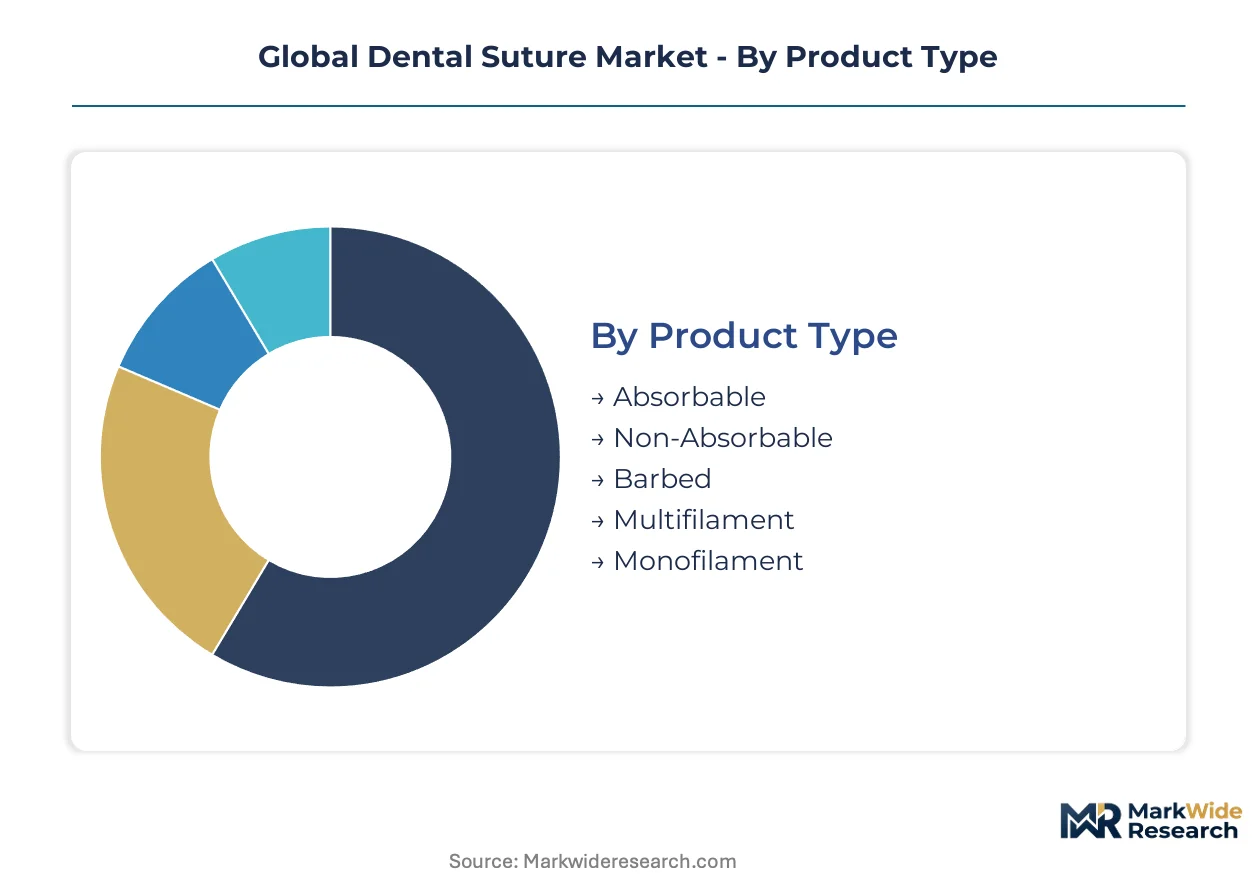
Dental suture procurement channels vary sharply by product complexity and clinical setting. Hospital-affiliated oral surgery networks favor premium absorbable formulations with established biocompatibility profiles, while independent dental clinics prioritize cost-efficient multifilament alternatives for routine extractions.
Product Type:
Channel-mix dynamics concentrate high-margin absorbable and barbed variants within hospital procurement systems, while non-absorbable and multifilament lines flow through independent distributor networks serving private practice dentists.
- Absorbable:Polyglactin and poliglecaprone formulations hydrolyze predictably within 7-14 days, eliminating removal appointments. Demand concentrates in implant dentistry centers across the United States, Germany, and China where case volumes justify premium pricing.
- Barbed:Self-anchoring configurations eliminate knot-tying steps in full-arch reconstructions. Oral surgery departments in United States metropolitan hospital networks specify these for throughput-sensitive procedures where operative time directly determines revenue allocation.
- Non-Absorbable:Silk and nylon constructions require post-operative removal, limiting use to specific orthodontic and periodontal applications.
- Multifilament:Braided synthetic and natural fiber constructions offer superior knot security for high-tension wound closures in academic training environments.
- Monofilament:Smooth synthetic surfaces resist bacterial colonization, commanding specification in immediate implant protocols where infection determines graft survival.
By volume, multifilament leads across price-sensitive independent clinics. By growth pace, barbed configurations are expanding most quickly in high-throughput hospital settings.
Material:
Cost tier stratification separates premium synthetic polymers specified by academic medical centers from economy-grade natural fibers serving developing-market dental clinics.
- Polyglactin:Copolymer of glycolide and lactide delivers predictable tensile strength retention with complete hydrolytic absorption. Implant dentistry volumes in Germany and China drive procurement expansion for guided bone regeneration procedures.
- Nylon:Polyamide monofilament provides permanent tensile strength for orthodontic applications and periodontal flap surgeries. Demand clusters in United States academic institutions where training protocols emphasize handling characteristics.
- Silk:Natural protein fiber with braided construction offers exceptional knot security at economy price points.
- Polyglycolic Acid:Homopolymer variant absorbs more rapidly than polyglactin, suited to short-healing-interval extractions.
- Polyester:Non-absorbable synthetic with braided construction serves long-term orthodontic anchorage applications.
- Catgut:Collagen-based natural material retains niche use in traditional practice settings despite synthetic displacement.
Polyglactin dominates procurement value. Nylon commands the steepest expansion trajectory in orthodontic specialist practices.
Application:
Procedure complexity determines material specification, with implant and oral surgery applications driving premium polymer adoption while orthodontics and endodontics sustain commodity-grade demand.
- Implant Dentistry:Immediate placement and guided bone regeneration protocols demand antimicrobial-coated absorbable polymers with bacterial wicking resistance. United States hospital networks specify these formulations for graft survival-critical cases.
- Oral Surgery:Multiple extractions and full-arch reconstructions favor barbed configurations that reduce operative time. German oral surgery centers lead European adoption of self-anchoring polydioxanone monofilaments.
- Periodontics:Flap surgeries and gingival grafting procedures utilize both absorbable and non-absorbable options depending on healing interval requirements.
- Endodontics:Apical surgery applications require fine-diameter sutures with minimal tissue reaction.
- Orthodontics:Long-term anchorage and soft tissue management sustain demand for permanent nylon and polyester constructions.
Oral surgery generates the highest suture consumption per procedure. Implant dentistry shows the fastest specification upgrade rate toward premium antimicrobial formulations.
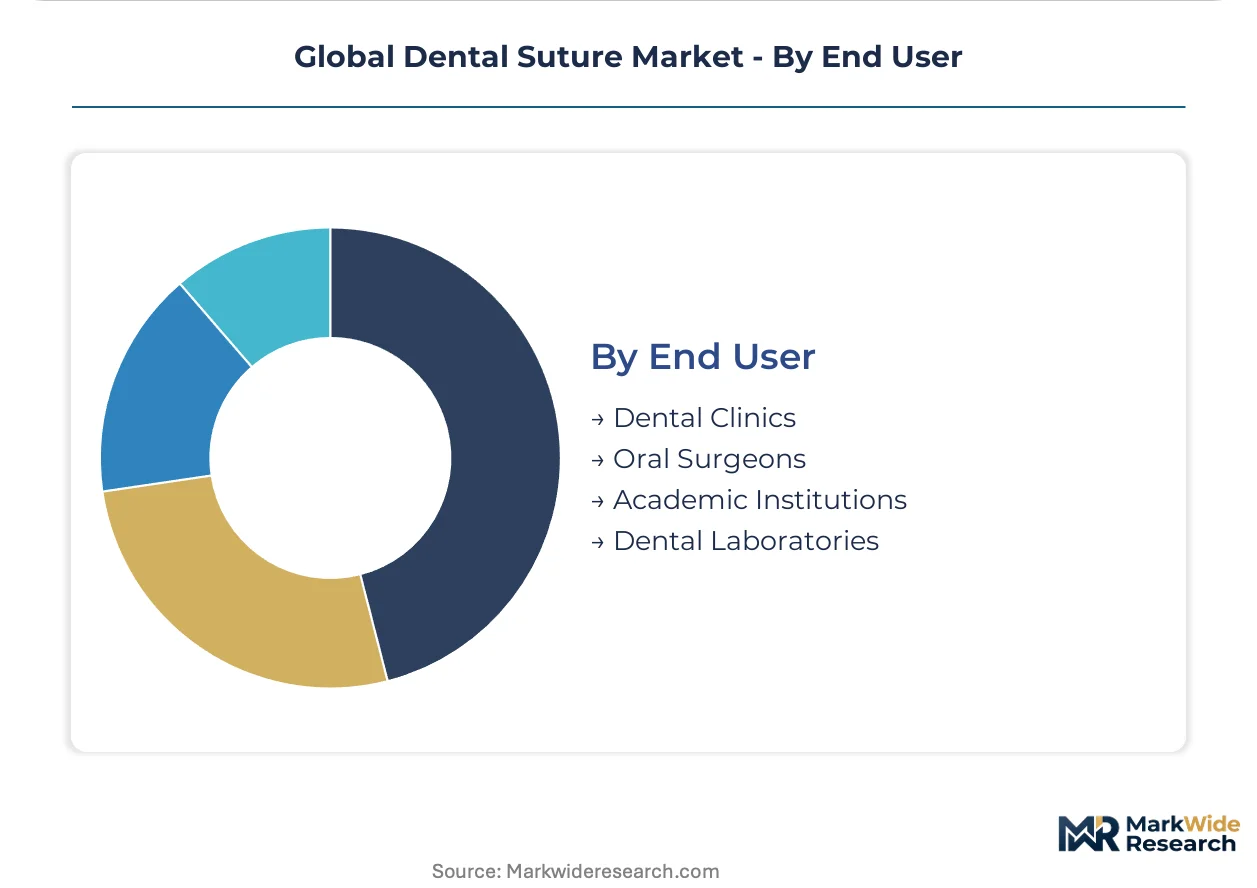
End User:
Customer type segmentation reveals divergent procurement authority, with hospital-affiliated oral surgeons controlling premium specification standards while dental clinics prioritize distributor availability and price competitiveness.
- Oral Surgeons:Hospital-based specialists command institutional purchasing loyalty through training program relationships and established quality management system requirements. Academic medical centers in the United States and Germany consolidate procurement around suppliers with dedicated regulatory affairs infrastructure.
- Dental Clinics:Independent practices and small group practices drive volume for economy-grade multifilament and non-absorbable lines through distributor networks.
- Academic Institutions:Dental schools and residency programs require broad product portfolios for training purposes, sustaining demand across all material categories.
- Dental Laboratories:Limited direct suture procurement, primarily supporting surgical guide fabrication and auxiliary supply functions.
Oral surgeons command the highest per-procedure spend. Dental clinics represent the largest absolute volume channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-affiliated oral surgery networks in the United States, Germany, and China concentrate procurement authority for premium absorbable sutures. Implant dentistry volumes in these markets drive specification standards that filter down to secondary markets through training program influence and regulatory reference.
United States
Metropolitan hospital networks in Boston, New York, and Los Angeles anchor demand for barbed polydioxanone configurations that reduce operative time in full-arch reconstructions. FDA 510(k) pathway streamlining for Class II absorbable polymers accelerates product refresh cycles for domestic manufacturers. Academic medical centers in the Northeast corridor consolidate procurement around suppliers with dedicated regulatory affairs infrastructure and established surgeon training relationships.
Germany
Oral surgery centers in Munich, Hamburg, and Berlin specify antimicrobial-coated polyglactin variants for immediate implant protocols where infection determines graft survival. EU MDR compliance requirements filter non-European manufacturers from clinic access, creating protected procurement pockets for CE-marked suppliers. The country's notified body concentration and quality management system expertise elevate compliance infrastructure as a competitive moat.
China
Private dental hospital chains in Shanghai, Beijing, and Guangzhou expand suture procurement to match rising guided bone regeneration volumes. NMPA medical device registration requirements and GB standards compliance extend market entry timelines for foreign suppliers. Domestic manufacturers leverage cost positioning to capture volume in price-sensitive tier-two city clinics while international brands retain premium positioning in tier-one implant centers.
Japan
Academic dental hospitals in Tokyo, Osaka, and Nagoya sustain demand for fine-diameter monofilaments with minimal tissue reaction. PMDA enforces JIS-compliant biocompatibility testing that adds six-to-twelve months to foreign supplier market entry. The country's aging demographic and periodontal disease prevalence drive procedure volumes that concentrate procurement authority within university-affiliated oral surgery departments.
India
Private dental hospital chains in Mumbai, Delhi-NCR, and Bangalore create new procurement entry points as the country's PLI scheme for medical devices expands domestic manufacturing capacity. CDSCO medical device regulations and import substitution policies favor local production for routine extraction sutures while premium implant applications retain international supplier dependence. Cost-efficient multifilament constructions dominate volume in independent clinic networks.
Global Dental Suture Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with captive polymer production capabilities and specialized suture manufacturers with regulatory-focused business models. Market structure concentrates procurement influence within hospital-affiliated oral surgery networks that specify premium absorbable formulations. Three archetypes dominate: vertically integrated polymer producers controlling raw material quality, training-program-anchored suppliers locking institutional loyalty, and regulatory-specialist firms navigating multi-jurisdiction compliance. Competitive moves center on M&A to acquire regulatory affairs talent and capacity expansion in India and Southeast Asia to capture PLI scheme benefits.
Within the diversified conglomerate tier, B. Braun Melsungen AG and Ethicon US, LLC exemplify contrasting strategic positions. B. Braun leverages its German manufacturing base and captive polymer production to control input quality for absorbable suture lines. Ethicon anchors its presence through extensive surgeon training infrastructure that locks in institutional purchasing loyalty across academic dental hospitals. Among specialized manufacturers, Shandong Sinorgmed Co., Ltd. occupies a position representing Chinese domestic cost-competitive production, while DemeTECH Corporation and Surgical Specialties Corporation sit within the regulatory-specialist archetype focused on multi-jurisdiction clearance capabilities. Assut Europe S.p.A. exemplifies the European specialist model with CE marking concentration effects protecting its clinic access position.
| Leading Market Players |
|---|
| Advanced Medical Solutions Group PLC |
| Assut Europe S.p.A. |
| B. Braun Melsungen AG |
| Osteogenics Biomedical |
| Surgical Specialties Corporation |
| Ethicon US, LLC |
| Teleflex Incorporated |
| Shandong Sinorgmed Co., Ltd |
| DemeTECH Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between hospital-affiliated oral surgery networks and certified suture manufacturers lock in both polyglactin feedstock access and price visibility across the contract duration. These arrangements insulate procurement teams from spot-market volatility in high-grade polymer inputs while exposing smaller independent clinics to cost compression.
Pricing Analysis
Cost-plus contracts with glycolide-lactide monomer indexation dominate procurement between German polymer producers and multinational suture manufacturers. Three-tier pricing structure across premium antimicrobial-coated, standard absorbable, and economy multifilament levels separates academic medical centers from independent dental clinics from developing-market distributors. Pricing pressure stems from India's PLI scheme expanding domestic manufacturing capacity for routine extraction sutures. Independent dental clinics exhibit highest price sensitivity, while United States hospital networks prioritize infection resistance outcomes over unit cost.
Supply Chain Analysis
Germany, China, and the United States anchor global production of medical-grade polyglactin and poliglecaprone polymers. Suture manufacturing draws from specialty chemical feedstocks, precision extrusion equipment, and sterilization packaging materials. Single-source vulnerability concentrates in three specialty chemical suppliers controlling high-grade glycolide and lactide monomers. Distribution runs through hospital procurement consortia in developed markets and independent distributor networks in price-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tissue adhesives and laser wound closure technologies threaten suture volumes in routine extraction applications, forcing incumbents to defend position through polymer innovation and surgeon workflow integration.
For Market Incumbents: Compound regulatory affairs infrastructure investments to compress multi-jurisdiction clearance timelines for antimicrobial-coated formulations. Deepen backward integration into polyglactin polymer production to secure input quality and margin control against feedstock cost volatility. Lock in institutional purchasing loyalty through expanded surgeon training programs that embed proprietary handling techniques. For New Entrants and Emerging Players: Differentiate on barbed suture configurations for high-throughput oral surgery settings outside the United States where self-anchoring polydioxanone remains underpenetrated. Target India's private dental hospital chains through CDSCO-compliant manufacturing partnerships that leverage PLI scheme benefits. Lead with operative time reduction value propositions rather than price competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory-specialist firms with dedicated EU MDR and FDA 510(k) capabilities. Long-term viability hinges on acquisition of notified body relationships and quality management system infrastructure rather than manufacturing scale alone. Watch for inflection in Japan PMDA biocompatibility testing timeline extensions that would advantage domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | CE marking under reinforced clinical evidence standards filters non-European competitors from German clinic access. |
| Antimicrobial Polymer Development | Triclosan and ionic silver integration addresses infection resistance demands in United States immediate implant protocols. |
| Hospital System Partnership | Academic medical center procurement consolidation locks in specification standards across training program networks. |
| Regulatory Affairs Talent Acquisition | Specialist hiring compresses FDA 510(k) and PMDA submission timelines for novel absorbable formulations. |
| India Manufacturing Scale-Up | PLI scheme participation captures cost-positioning advantages in tier-two city dental clinic expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oral surgeons, hospital procurement managers, biomedical engineers, and GPO contracts administrators. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, NMPA registration databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down polymer consumption data were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions including suture construction type, absorbability profile, material chemistry, application procedure complexity, and end-user procurement channel. CAGRs were derived from trend extrapolation of implant dentistry procedure volumes, regulatory clearance velocity, and surgeon preference shift patterns toward barbed configurations.
The analysis sits within stated boundaries; outcomes outside stable FDA 510(k) pathway timelines, sustained EU MDR enforcement intensity, or continued India PLI scheme funding would require recalibration. Forecasts reflect assumptions regarding polymer biocompatibility standard stability and hospital network procurement consolidation trajectories. Recalibration cycles align with material shifts in regulatory clearance requirements and antimicrobial coating efficacy validation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Dental Consumables Market