
 Global Pupillometer Market | 2026-2036
Global Pupillometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pupillometer Market Foresight
Digital infrared imaging is narrowing the performance gap between handheld screening devices and laboratory-grade diagnostic systems. NeurOptics, Inc. leverages its specialized focus on automated pupillometry to anchor premium positioning in emergency medicine workflows. NIDEK CO., LTD. competes through its broader ophthalmic platform integration, while Reichert Technologies differentiates via longstanding channel control across North American eye care practices.
A pupillometer is an optical instrument that quantifies pupil diameter, reactivity, and constriction velocity under controlled light stimuli, typically employing infrared illumination to eliminate visible light interference during measurement. The device serves clinical and research applications requiring objective, repeatable assessment of autonomic nervous system function and neurological status. Handheld units currently dominate volume shipments due to point-of-care deployment flexibility, whereas video imaging technology captures expanding share as algorithms improve motion-artifact correction. Wireless connectivity represents the fastest-growing product configuration, driven by electronic health record integration mandates and remote monitoring protocols in sports medicine clinics.
The FDA's 510(k) clearance framework governs commercial entry for pupillometers in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for infrared and electro-optical measurement systems sold in European markets. ISO 10993 biocompatibility standards additionally constrain material selection for devices contacting periocular tissue. Stakeholders must monitor evolving reimbursement codes for pupillary evaluation in traumatic brain injury protocols, as coverage determinations will dictate hospital capital allocation priorities across neurology centers and emergency departments.
Market Dynamics
Neurology centers and emergency departments are consolidating diagnostic workflows around automated pupillary assessment, compressing procurement cycles for infrared-enabled devices while elevating software integration requirements over standalone hardware specifications.
Growth Catalysts
- Traumatic brain injury protocol standardization:Hospital systems across the United States are embedding quantitative pupillometry into Level I trauma center accreditation requirements, mandating objective neurological monitoring tools.
- EU Medical Device Regulation clinical evidence pathways:MDR Article 61 and Annex XIV requirements for Class IIa electro-optical devices are accelerating peer-reviewed publication volume, legitimizing automated pupillometry for reimbursement negotiations.
- Wireless connectivity mandates:Electronic health record integration requirements in Medicare-certified facilities are pulling Ethernet-deprived legacy devices out of service.
Market Restraints
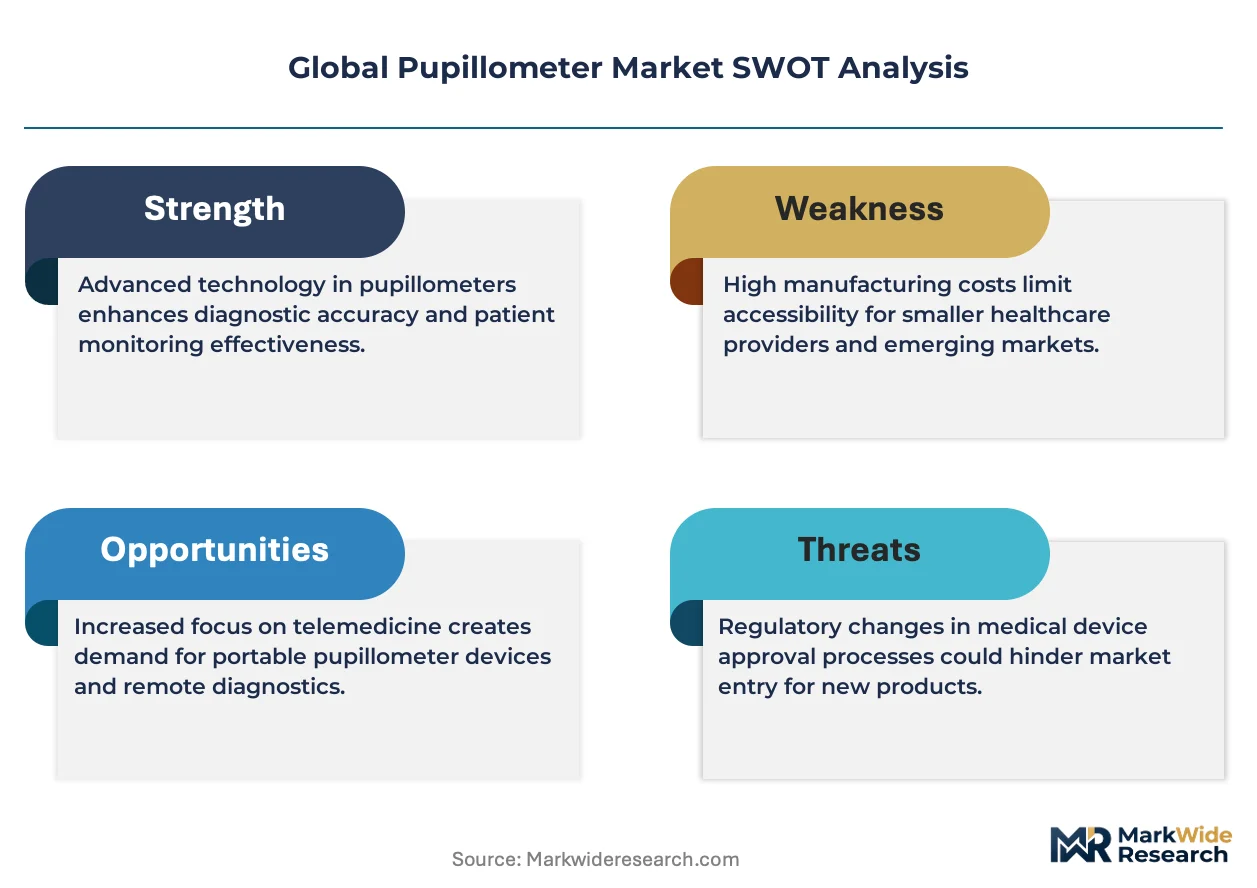
- Infrared sensor supply concentration:German and Japanese precision optics suppliers control critical detector substrate manufacturing, exposing device assemblers to allocation risk during semiconductor cycle tightness.
- ISO 10993 biocompatibility testing timelines:Periocular contact materials require extended cytotoxicity and sensitization studies, stretching product development cycles for novel housing polymers.
- Manual penlight substitution in resource-constrained settings:Low-cost acute care facilities in secondary markets continue defaulting to subjective assessment methods, capping addressable volume in price-sensitive procurement segments.
Strategic Opportunities
- Remote monitoring protocol expansion:Sports medicine clinics and concussion management programs are piloting cloud-connected pupillometry for longitudinal athlete tracking outside hospital walls.
- India's CDSCO medical device registration streamlining:The 2017 Medical Device Rules amendment and subsequent online portal rationalization are compressing import license timelines for infrared diagnostic equipment.
- Algorithm-hardware convergence:Machine learning-based motion artifact correction is hybridizing with compact CMOS sensors, enabling laboratory-grade measurement fidelity in handheld form factors previously restricted to video imaging systems.
Industry Challenges
- Neuro-ophthalmology specialist scarcity:Interpretation of complex pupillary response patterns requires subspecialty training that academic medical centers struggle to replenish.
- Legacy device interoperability:Proprietary data formats from installed base units resist HL7 FHIR standardization, forcing hospitals into costly middleware deployments or rip-and-replace decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pupillometer Market |
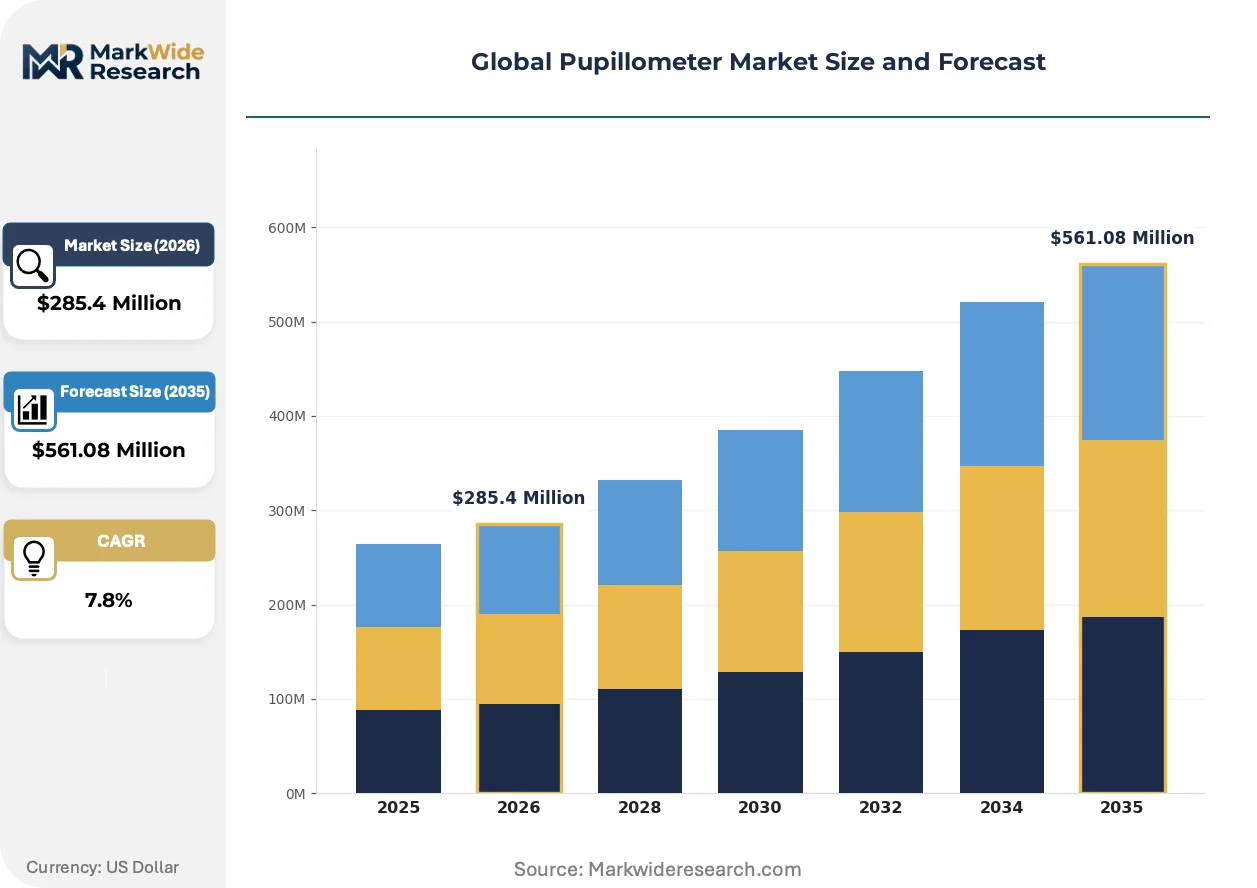
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Desktop, Virtual Reality Based, Mobile Application, Wireless Measurement Technology: Infrared, Video Imaging, Electro-Optical, Photometric, Ultrasonic End User: Neurology Centers, Emergency Departments, Research Laboratories, Sports Medicine Clinics Application: Neurological Assessment, Pharmacological Testing, Cognitive Research, Traumatic Brain Injury Evaluation |
| Companies Covered | NeurOptics, Inc., Essilor Instruments USA, HAAG-STREIT GROUP, Johnson & Johnson Vision, Luneau Technology Group, NIDEK CO., LTD., Reichert Technologies, Adaptica, SCHWIND eye-tech-solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pupillometer Market Shifts & Advancements
Digital infrared imaging and embedded algorithm processing are collapsing the traditional boundary between screening-grade portability and diagnostic-grade precision, forcing vendors to recalibrate hardware-software value allocation.
Video-based pupillometry is hybridizing with smartphone-grade camera modules and edge-computing inference chips. Emergency medicine departments in the United States are deploying these units for rapid serial neurological exams, compressing the historical performance gap against laboratory-bound stationary systems. The technology is hybridizing measurement precision with point-of-care logistics, enabling triage protocols that previously required transport to imaging suites.
REACH Annex XVII restrictions on persistent organic pollutants are constraining flame-retardant compound selection for device housings sold in European markets. Manufacturers are reformulating polymer blends to maintain IEC 60601-1 electrical safety ratings while eliminating restricted brominated additives. Video imaging systems with extended cable assemblies face the most acute material recertification burden due to jacketing surface area exposure.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, pressuring vendors to disclose hourly technical support rates and software maintenance fees separately. This transparency mandate is most visible in United States academic medical centers with centralized value analysis committees. Device suppliers are responding with tiered service tiering that decouples hardware warranty from algorithm update subscriptions.
Global Pupillometer Market Segmentation
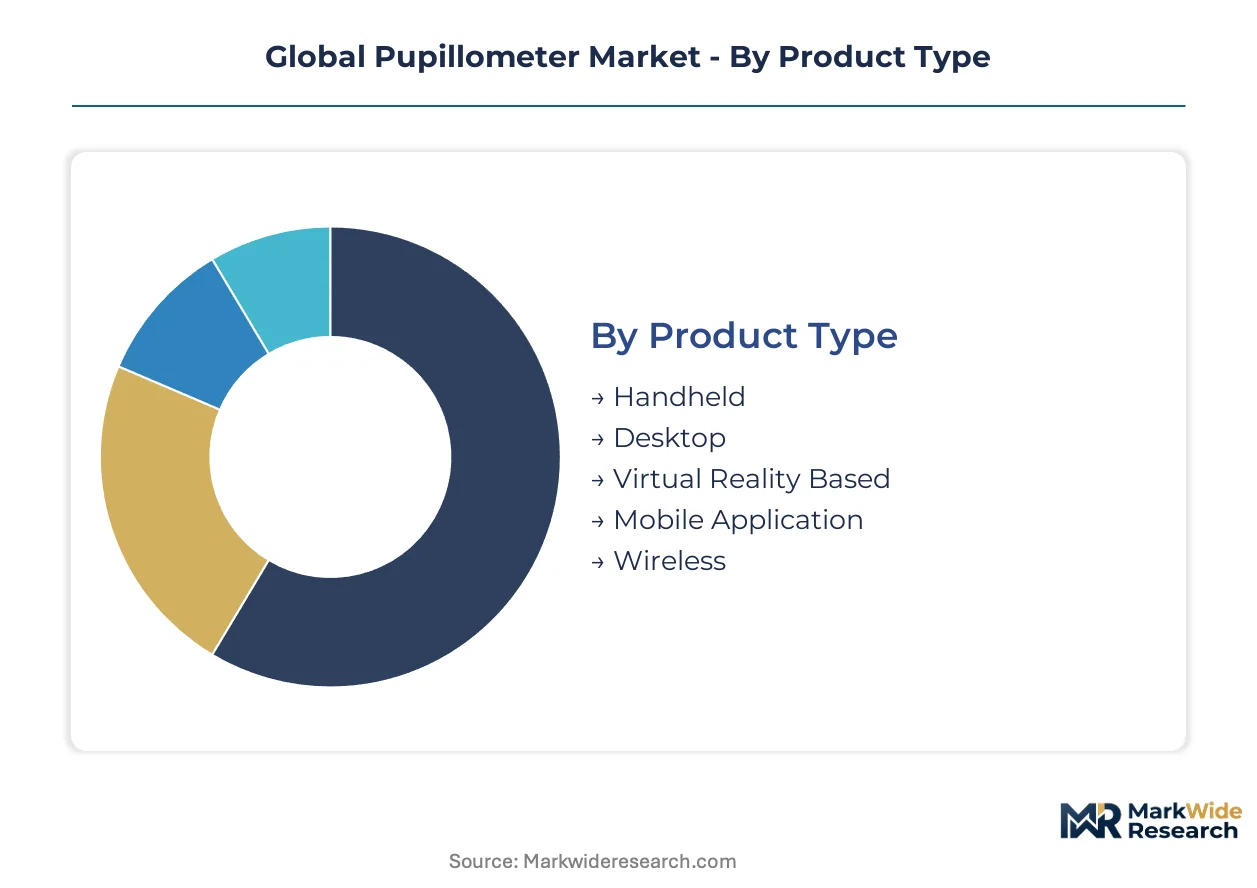
Pupillometer segmentation reflects the tension between point-of-care deployment flexibility and diagnostic precision requirements. Product form factors, measurement modalities, and end-user workflows each create distinct procurement criteria that vendors must navigate.
Product Type:
Mature hardware configurations dominate installed base volumes while emerging formats reshape software monetization models.
- Handheld:Compact battery-powered units with integrated infrared emitters and CMOS detectors enable bedside neurological exams without patient transport. Emergency departments in the United States specify these for rapid serial assessments during trauma triage.
- Desktop:Stationary systems with stabilized headrests and controlled ambient lighting deliver sub-millimeter measurement precision for longitudinal research protocols. Research laboratories at academic medical centers in Germany and Japan prioritize these for pharmacological studies requiring reproducible baselines.
- Virtual Reality Based:Head-mounted displays with embedded pupillometry sensors synchronize visual stimulus presentation with measurement capture.
- Mobile Application:Smartphone camera-based screening tools leverage ambient light cancellation algorithms for preliminary assessment outside clinical settings.
- Wireless:Bluetooth-enabled devices stream encrypted data directly to electronic health record systems, satisfying Medicare-certified facility integration mandates.
Handheld configurations retain volume leadership; wireless variants hold the steepest expansion curve.
Measurement Technology:
Cost tier stratification separates premium precision systems from accessible screening platforms.
- Infrared:Near-infrared illumination at 850-950 nanometers eliminates visible light reflex interference, enabling measurement during dark-adapted conditions. FDA-cleared infrared systems anchor reimbursement eligibility for traumatic brain injury protocols in United States trauma centers.
- Video Imaging:High-frame-rate camera capture with post-hoc motion artifact correction approximates laboratory-grade precision at reduced hardware cost. Sports medicine clinics in Australia and Canada deploy these for sideline concussion assessment where equipment portability outweighs absolute accuracy.
- Electro-Optical:Photodiode arrays with analog-to-digital conversion deliver microsecond temporal resolution for constriction velocity quantification.
- Photometric:Single-point light intensity measurement correlates pupil diameter with reflected luminance.
- Ultrasonic:Transducer-based distance sensing eliminates optical calibration requirements for patients with corneal opacities.
Infrared technology commands premium pricing; video imaging is gaining share fastest in cost-constrained procurement segments.
End User:
Application urgency determines hardware specification tolerance across clinical and research settings.
- Neurology Centers:Subspecialty departments require quantitative pupillometry for differential diagnosis of optic nerve pathology and autonomic dysfunction. Centers in France and Switzerland integrate these measurements into standardized multiple sclerosis monitoring protocols.
- Emergency Departments:Level I trauma centers mandate objective pupillary assessment for traumatic brain injury stratification per American College of Surgeons accreditation standards.
- Research Laboratories:Academic institutions employ calibrated systems for psychotropic drug trials and sleep medicine studies.
- Sports Medicine Clinics:Athletic training facilities utilize portable screening for return-to-play decisions following concussion incidents.
Emergency departments drive capital equipment procurement volume; sports medicine clinics represent the most rapidly expanding addressable segment.
Application:
Regulatory clearance pathways segment reimbursement eligibility across clinical indications.
- Neurological Assessment:Routine pupillary evaluation for intracranial pressure monitoring and brainstem function testing supports hospital neurology service line revenue capture.
- Pharmacological Testing:Pupillary response metrics serve as biomarkers for opioid effect quantification and anticholinergic drug screening in clinical trials.
- Cognitive Research:Pupillometry indices of cognitive load and emotional arousal enable experimental psychology and human factors studies.
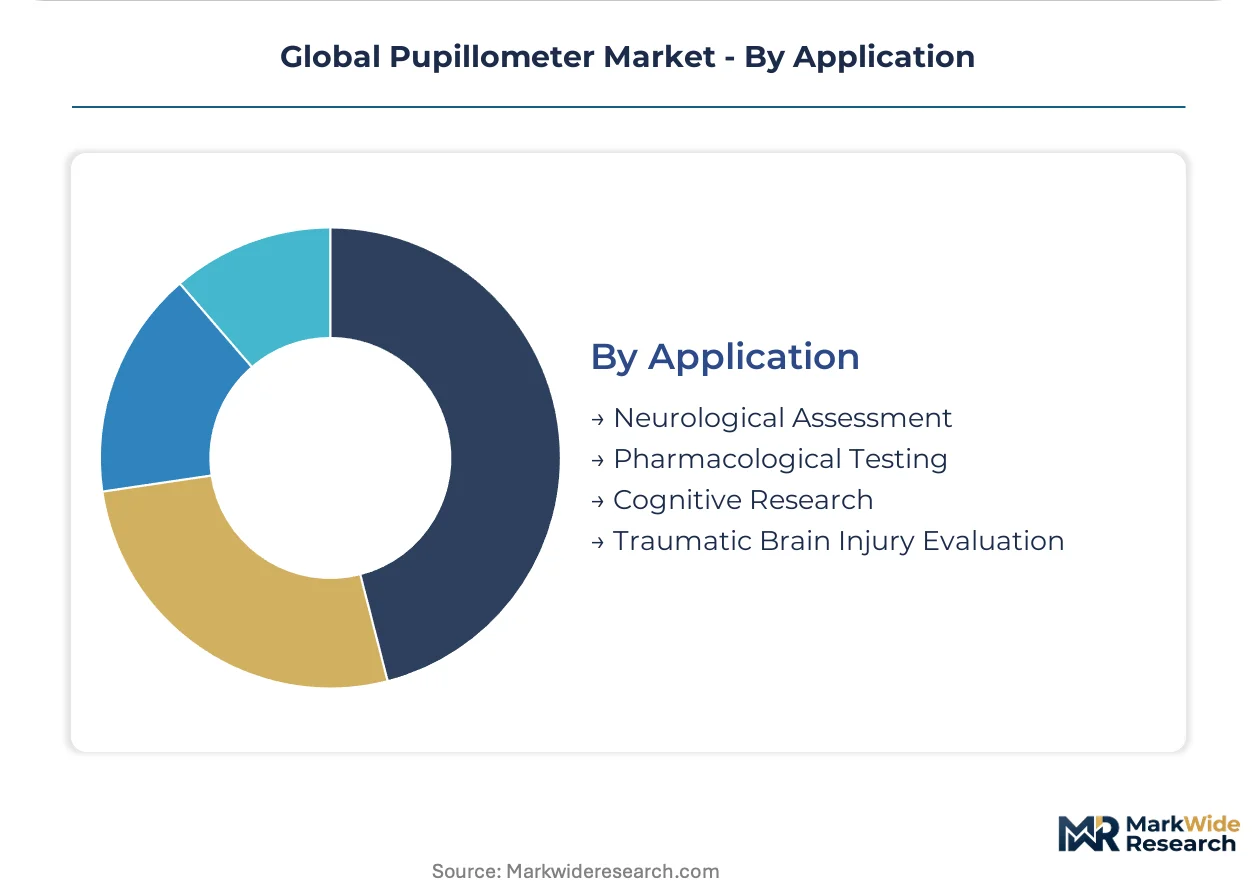
- Traumatic Brain Injury Evaluation:Quantitative pupillary reactivity scoring supports objective concussion diagnosis and prognostication for insurance documentation requirements.
Traumatic brain injury applications concentrate near-term revenue; cognitive research applications sustain longest deployment lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States dominate capital equipment orders, while neurology centers in Germany and Japan drive precision-system demand. Trauma accreditation standards and reimbursement frameworks shape regional purchasing velocity.
United States
Level I trauma centers mandate quantitative pupillometry for American College of Surgeons accreditation, compressing procurement cycles for infrared-enabled devices. FDA 510(k) clearance pathways govern commercial entry, with Medicare-certified facilities pulling Ethernet-deprived legacy systems from service. Boston and Baltimore academic medical centers anchor demand for wireless EHR-integrated configurations.
Germany
Research laboratories at Heidelberg and Tübingen universities prioritize desktop systems for pharmacological studies requiring reproducible baselines. REACH Annex XVII restrictions on persistent organic pollutants constrain flame-retardant compound selection for device housings. Bavaria's precision optics cluster supplies critical detector substrates to device assemblers across the European market.
Japan
PMDA regulatory timelines for Class II electro-optical devices shape product launch sequencing for infrared diagnostic equipment. Tokyo and Osaka neurology centers integrate pupillometry into standardized multiple sclerosis monitoring protocols. METI funding for digital health infrastructure accelerates hospital IT integration mandates.
India
CDSCO medical device registration streamlining under the 2017 Medical Device Rules amendment compresses import license timelines for infrared diagnostic equipment. Delhi-NCR and Maharashtra neurology departments pilot automated pupillary assessment for intracranial pressure monitoring. Price-sensitive procurement in secondary markets sustains demand for video imaging alternatives to premium infrared systems.
France
ANSM oversight of electro-optical medical devices imposes clinical evidence requirements that accelerate peer-reviewed publication volume. Paris and Lyon neurology centers embed quantitative pupillometry into differential diagnosis workflows for optic nerve pathology. CNIL data protection guidance shapes cloud-connected device deployment for remote monitoring protocols.
Global Pupillometer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement segments. The vendor base spans ophthalmic platform conglomerates, dedicated neurological diagnostic specialists, and precision optics fabricators with periocular device experience. Three archetypes dominate: integrated eye-care platform operators, automated pupillometry pure-plays, and optical instrumentation legacy houses. Competitive moves concentrate on algorithm-hardware convergence and unbundled service contract tiering.
Among automated pupillometry specialists, NeurOptics, Inc. and NIDEK CO., LTD. occupy positions at opposite ends of the specialization spectrum. NeurOptics exemplifies the pure-play archetype with concentrated focus on neurological emergency workflows, while NIDEK represents platform-integrated competition leveraging broader ophthalmic device portfolios. Reichert Technologies anchors the North American channel-control tier through longstanding distribution relationships across eye care practices.
| Leading Market Players |
|---|
| NeurOptics, Inc. |
| Essilor Instruments USA |
| HAAG-STREIT GROUP |
| Johnson & Johnson Vision |
| Luneau Technology Group |
| NIDEK CO., LTD. |
| Reichert Technologies |
| Adaptica |
| SCHWIND eye-tech-solutions |
| Others |
Supply & Pricing Matrix
Bavaria's precision optics cluster anchors critical detector substrate capacity, and its allocation cycles transmit directly into device assembler pricing power during semiconductor tightness. Infrared sensor foundries in this region feed assembly lines across Germany, Japan, and the United States, creating tiered cost structures that differentiate premium neurological diagnostic systems from screening-grade alternatives.
Pricing Analysis
Cost-plus contracts with germanium substrate indexation dominate procurement between Bavarian optics suppliers and device manufacturers. Pricing stratifies across FDA-cleared infrared systems, CE-marked video imaging platforms, and unregulated manual alternatives. Cost compression in video imaging tiers is intensifying because smartphone-grade CMOS modules displace dedicated optical subassemblies. Academic medical centers in Boston and Baltimore exhibit lowest price sensitivity; secondary market clinics in India and Southeast Asia drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for flame-retardant polymer compounds. Manufacturing concentrates in Germany, Japan, and the United States for precision optics; China and South Korea for CMOS sensors; and Switzerland for electro-optical calibration equipment. Device assembly draws from germanium substrates, infrared LED emitters, and biocompatible housing polymers. Single-source vulnerability persists at the substrate level. Distribution runs through ophthalmic instrument distributors, hospital GPO contracts, and direct neurology center salesforces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement committees in United States academic medical centers, fragmenting vendor pricing leverage across fragmented regional eye care practices.
For Market Incumbents: Insulate service revenue streams from hardware commoditization by unbundling algorithm update subscriptions from capital equipment warranties. Deepen backward integration into infrared detector substrate supply through captive Bavarian foundry partnerships. Defend against video imaging entrants by accelerating FDA 510(k) clearances for AI-enhanced constriction velocity metrics. For New Entrants and Emerging Players: Pursue sports medicine clinic white space in Australia and Canada where sideline concussion protocols lack reimbursement standardization. Target India's CDSCO-registered import pathway for price-disruptive video imaging platforms. Lead with cloud-connected longitudinal tracking narratives that bypass incumbent EHR integration moats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated pupillometry pure-plays over ophthalmic platform conglomerates. Five-to-ten year viability hinges on algorithm-hardware convergence patents and trauma center installed base density. Watch for inflection in Medicare reimbursement code expansion for quantitative pupillary evaluation beyond Level I trauma centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates reimbursement eligibility for traumatic brain injury protocols in United States trauma centers. |
| CE Marking Pathway | Unlocks EU Medical Device Regulation compliance for infrared systems entering German and French neurology markets. |
| Hospital System Partnership | Secures preferred vendor status with Boston and Baltimore academic medical center procurement committees. |
| Software Companion Development | Enables HL7 FHIR-compliant EHR integration for Medicare-certified facility mandates. |
| Reimbursement Strategy | Positions quantitative pupillometry within American College of Surgeons trauma accreditation requirements. |
Research Methodology
The analysis maps handheld, desktop, and wireless pupillometer sub-sectors, each validated through hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews with emergency department directors and neurology center administrators combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up shipment modeling and top-down diagnostic equipment spending analysis provided triangulation anchors.
Assumptions held fixed include FDA Class II clearance timelines and ISO 10993 biocompatibility testing durations; variables included EU MDR Article 61 clinical evidence requirements and CDSCO import license streamlining velocity. Segmentation dimensions spanned product form factor, measurement technology, end-user workflow, and regional regulatory cluster. CAGRs derived from logistic diffusion modeling of trauma center accreditation mandates and sports medicine clinic adoption curves. Forecast inputs incorporated infrared sensor supply allocation cycles and REACH Annex XVII material restriction timelines.
Sensitivities concentrate around Medicare reimbursement code expansion timing and PMDA regulatory sequencing for Japanese market entry. Forecasts reflect documented assumptions regarding trauma protocol standardization velocity and semiconductor cycle conditions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Recanalization System Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Global Micro Guide Catheters Market