
 Quadripodal Implants Market | 2026-2036
Quadripodal Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Quadripodal Implants Market Analytics
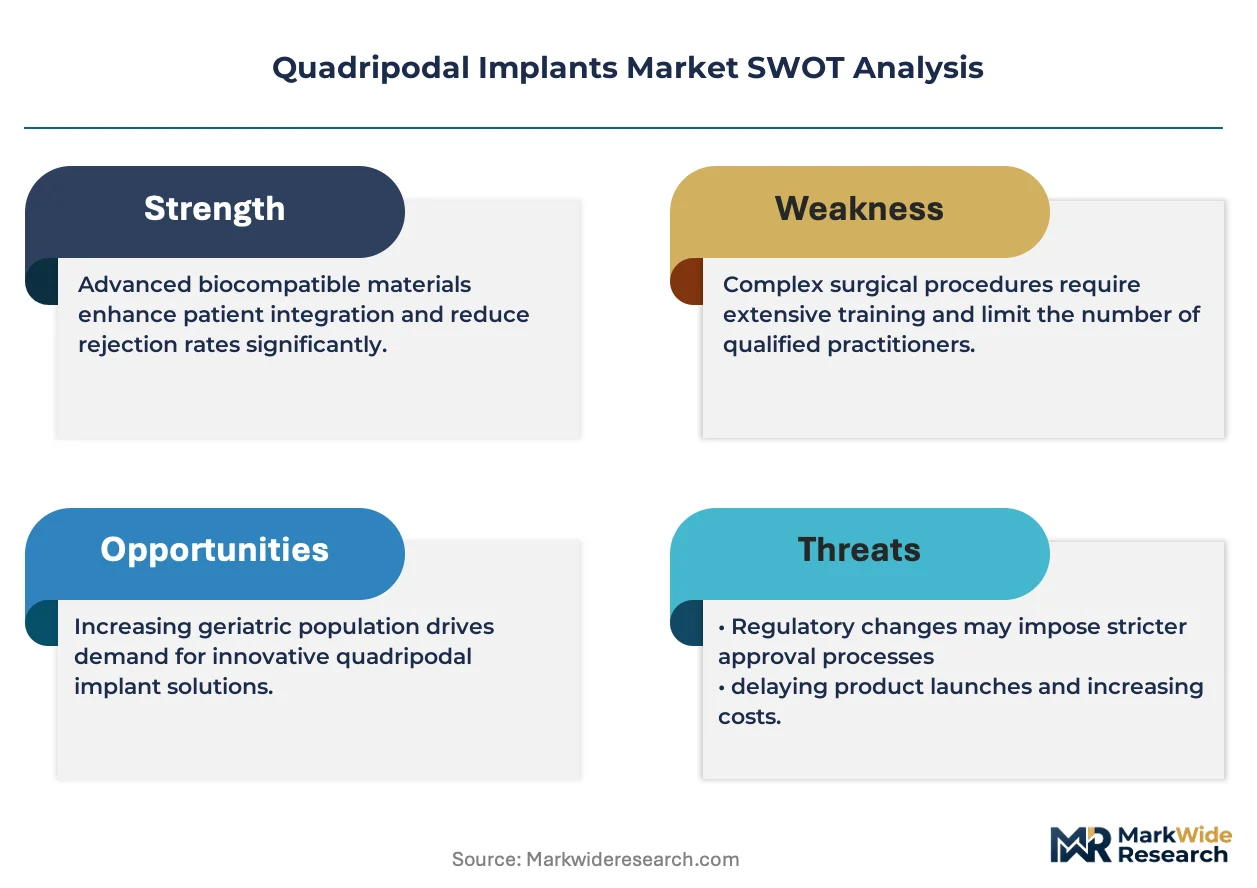
EU MDR recertification is decoupling smaller manufacturers from European market access, forcing portfolio rationalization and consolidated supplier lists. Stryker leverages its established notified body relationships and quality management infrastructure to sustain broad CE-marked portfolios across quadripodal implant lines. Zimmer Biomet anchors its position through deep orthopedic surgeon training networks and specialized instrumentation ecosystems. DePuy Synthes differentiates via integrated digital surgical planning platforms that lock in implant-system compatibility.
Quadripodal implants are four-legged structural prostheses engineered for load distribution across multiple fixation points, typically manufactured from titanium alloy or cobalt-chrome with porous surface treatments to promote osseointegration at bone-implant interfaces. These devices serve primary functions in complex revision arthroplasty and maxillofacial reconstruction where traditional bilateral fixation proves mechanically insufficient. Titanium material segments dominate current procurement volumes due to established biocompatibility profiles and fatigue resistance, while polymer-based formulations represent the fastest-expanding category as peek-optimized composites gain traction in dental and veterinary applications. Custom implant fabrication, driven by patient-specific CT-to-implant workflows, captures disproportionate margin pools despite lower unit volumes.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements jointly shape product development timelines and clinical evidence burdens for quadripodal implant manufacturers seeking dual-market presence. ISO 5832 material standards and ASTM F136 titanium alloy specifications further constrain raw material sourcing and subcontractor qualification processes. Stakeholders must monitor evolving notified body capacity constraints and FDA orthopedic panel precedents to time regulatory submissions and avoid queue-driven commercial delays.
Market Dynamics
EU MDR recertification timelines are compressing competitive timelines for quadripodal implant manufacturers, forcing accelerated clinical evidence generation and notified body queue management strategies.
Growth Catalysts
- Revision arthroplasty volume expansion:Aging implant populations in tertiary hospitals across Germany and the United States are generating complex reconstruction cases requiring four-point fixation.
- Patient-specific manufacturing workflows:CT-to-implant digital pipelines are collapsing design-to-implant cycles from weeks to days, expanding addressable case complexity.
- EU MDR Article 117 conformity routes:Harmonized quality management system requirements are streamlining cross-border market access for compliant manufacturers.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have elevated spot pricing volatility for ASTM F136 alloy inputs.
- Notified body capacity scarcity:Only twelve designated bodies currently handle EU MDR orthopedic device reviews, extending submission-to-decision intervals.
- Polyetheretherketone mechanical limitations:PEEK composites lack fatigue resistance for load-bearing pelvic applications, constraining material substitution.
Strategic Opportunities
- Veterinary maxillofacial surgery:Companion animal dentistry in North American specialty clinics represents an underpenetrated volume channel.
- Japan PMDA Sakigake fast-track pathway:Expedited review timelines for breakthrough devices are attracting early regulatory filing strategies.
- Additive manufacturing-lattice topology convergence:Electron beam melting paired with gyroid structures is enabling osseointegration-optimized pore architectures.
Industry Challenges
- Biomaterials toxicology expertise scarcity:Qualified professionals for ISO 10993 biological evaluation protocols command premium compensation.
- Legacy CAD-CAM system integration:Proprietary surgical planning software from incumbent manufacturers creates data interoperability friction.
- Cleanroom capex intensity:ISO 14644 Class 7 manufacturing environments require substantial facility investment for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quadripodal Implants Market |
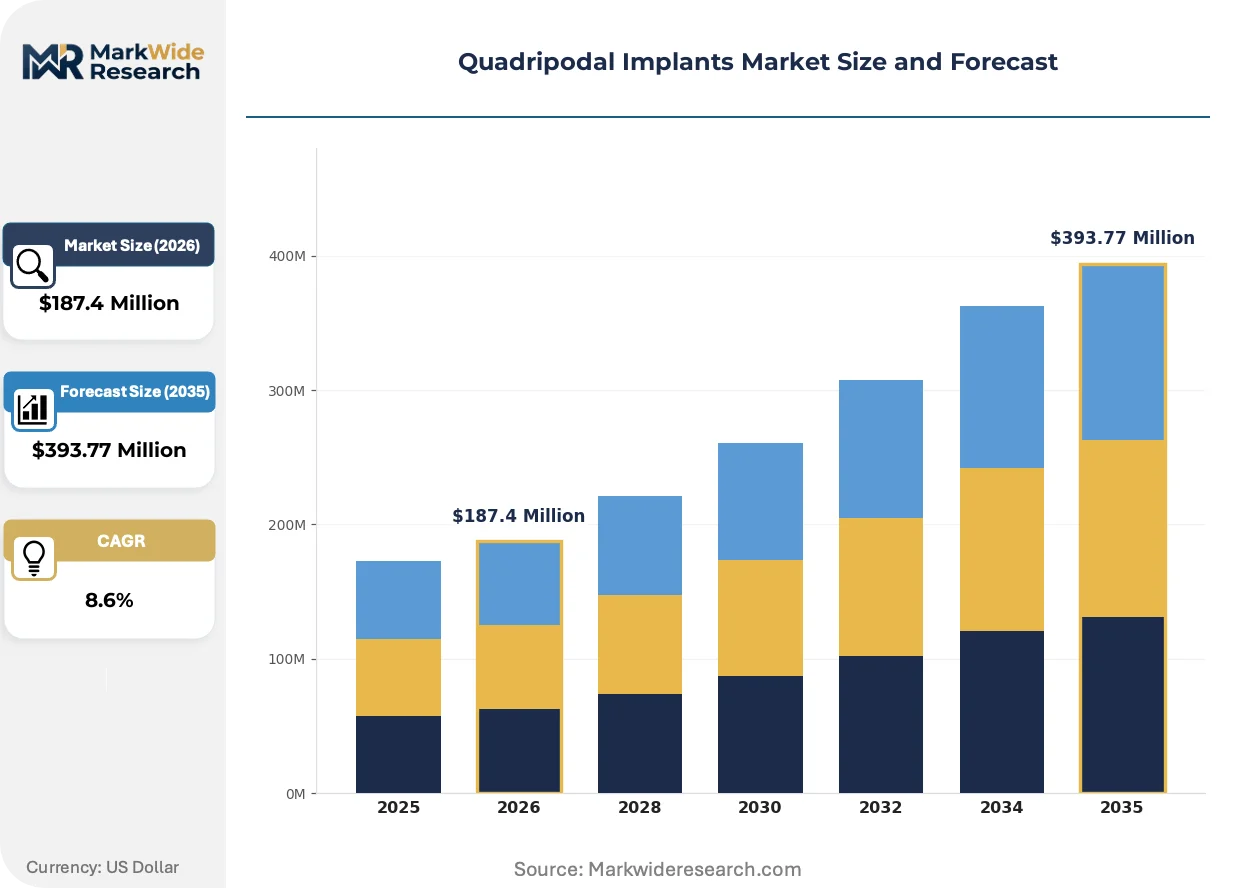
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Implants, Removable Implants, Custom Implants, Standard Implants Material: Titanium, Stainless Steel, Ceramics, Polymers Application: Orthopedic Surgery, Dental Surgery, Veterinary Medicine, Rehabilitation End User: Hospitals, Clinics, Rehabilitation Centers, Research Institutions |
| Companies Covered | Stryker, Zimmer Biomet, DePuy Synthes, Smith & Nephew, Medtronic, Integra LifeSciences, Globus Medical, NuVasive, Orthofix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quadripodal Implants Market Evolving Landscape
Digital surgical planning ecosystems are reconfiguring how quadripodal implants are specified, ordered, and validated, collapsing traditional instrumentation-heavy workflows into software-mediated precision.
Modular quadripodal baseplate systems are fragmenting monolithic implant portfolios into interchangeable fixation and bearing components. Academic medical centers in Germany and the Netherlands are piloting surgeon-assembled configurations intraoperatively. This architecture is modularizing supplier relationships, enabling hospitals to mix fixation platforms from one manufacturer with bearing surfaces from another.
EU MDR Annex XIV clinical evaluation requirements are elevating post-market clinical follow-up obligations for legacy implant lines. Manufacturers must now generate prospective data on devices with decade-long implantation histories. High-volume hip and knee revision centers in Tuttlingen and Freiburg are restructuring patient consent protocols to capture this evidence.
Surgeon training networks are displacing traditional distributor relationships as the primary channel for implant specification. Orthopedic departments in German university hospitals now contract directly with manufacturers for cadaveric lab access and proctored case support. This behavioral shift concentrates purchasing influence within residency program directors rather than procurement departments.
Quadripodal Implants Market Segmentation
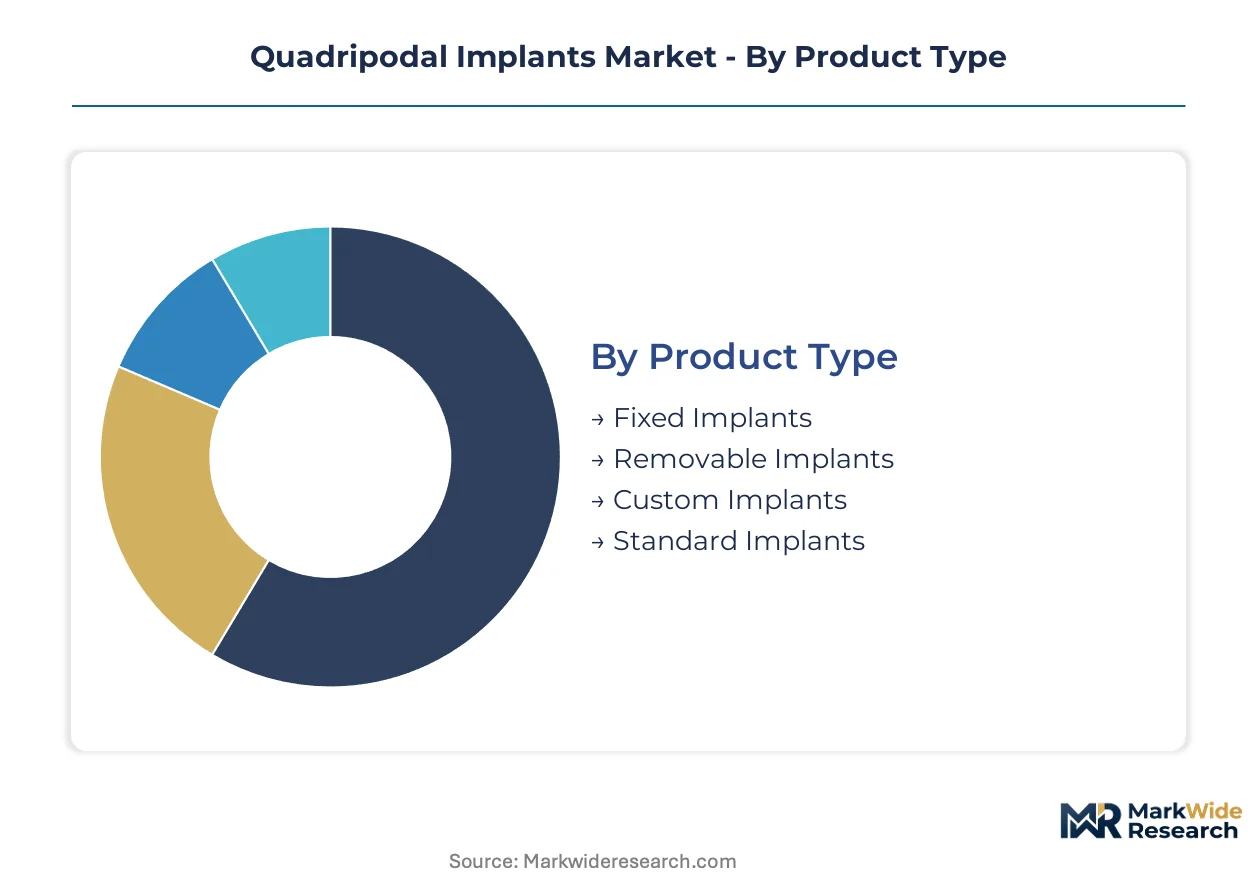
Quadripodal implant procurement patterns diverge sharply between high-volume standardized configurations and patient-specific fabrications. Manufacturers must balance inventory efficiency against the margin premiums that customization commands.
Product Type:
Customization intensity varies from off-the-shelf geometries to CT-derived patient-matched architectures, with cost and lead time scaling accordingly.
- Fixed Implants:Rigid four-point fixation structures with predetermined angular configurations. Tertiary hospitals in Germany standardize on these for routine revision arthroplasty, driving procurement volume through consolidated supplier contracts.
- Custom Implants:Patient-specific geometries manufactured from DICOM-to-CAD workflows. Maxillofacial reconstruction centers in Freiburg generate disproportionate margin capture despite lower unit throughput, as complex trauma cases require anatomically matched fixation.
- Removable Implants:Modular fixation platforms permitting intraoperative adjustment or staged removal protocols.
- Standard Implants:Catalog configurations produced to ISO 5832 specifications with minimal design variation.
Leading the category by volume: Fixed Implants. Expanding most quickly: Custom Implants.
Material:
Cost tiers separate established biocompatible metals from emerging polymer formulations, with performance trade-offs governing substitution economics.
- Titanium:ASTM F136 alloy grades dominate current procurement, offering fatigue resistance and established osseointegration profiles. German orthopedic clusters around Tuttlingen anchor global demand for titanium sponge feedstock, though Russian supply disruptions have elevated spot pricing volatility.
- Polymers:PEEK-optimized composites gain traction in dental and veterinary niches where load requirements permit. North American specialty clinics drive fastest category expansion, though pelvic applications remain constrained by mechanical limitations.
- Stainless Steel:Cost-sensitive applications in emerging markets where cobalt-chrome alternatives prove prohibitive.
- Ceramics:Alumina and zirconia formulations for bearing surfaces requiring extreme wear resistance.
Highest procurement volume: Titanium. Steepest expansion trajectory: Polymers.
Application:
Customer maturity separates complex revision centers from high-volume primary intervention sites, with case complexity dictating product specification.
- Orthopedic Surgery:Complex revision arthroplasty and pelvic reconstruction requiring four-point mechanical stability. Aging implant populations in US tertiary hospitals generate case volume, while EU MDR clinical follow-up obligations reshape evidence capture protocols.
- Dental Surgery:Maxillofacial fixation and cranial reconstruction applications. Patient-specific workflows collapse design-to-implant cycles, enabling same-week turnaround for trauma cases.
- Veterinary Medicine:Companion animal dentistry in North American specialty clinics represents underpenetrated volume opportunity.
- Rehabilitation:Post-surgical fixation support and load-bearing orthotic integration.
Dominant revenue concentration: Orthopedic Surgery. Gaining share fastest: Veterinary Medicine.
End User:
Procurement authority separates centralized hospital purchasing from distributed clinic decision-making, with training network access influencing specification.
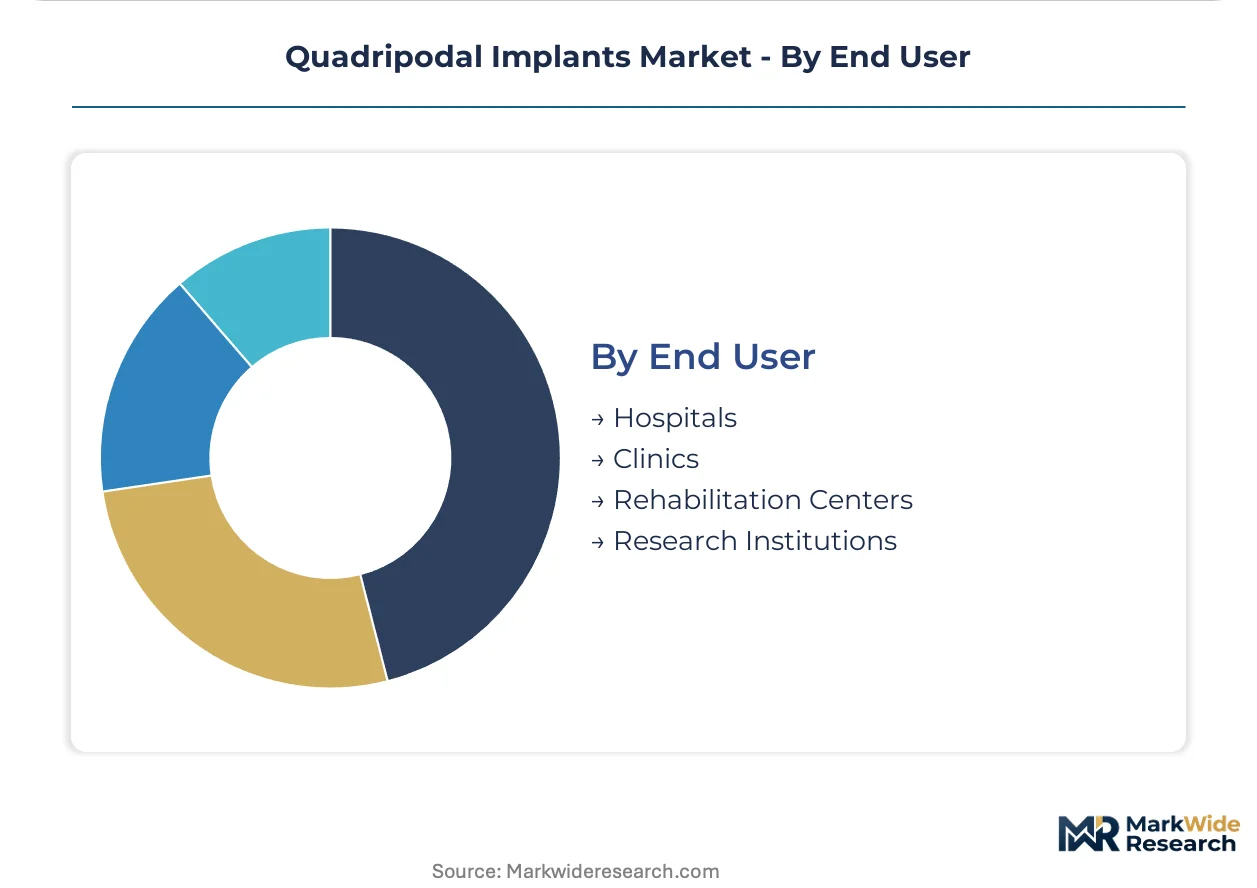
- Hospitals:Tertiary and university medical centers with integrated orthopedic departments. German academic hospitals now contract directly with manufacturers for cadaveric lab access, concentrating purchasing influence within residency program directors.
- Clinics:Ambulatory surgical centers and private practice settings with streamlined procurement authority.
- Rehabilitation Centers:Post-acute facilities managing implant-adjacent therapeutic protocols.
- Research Institutions:Academic medical centers generating post-market clinical follow-up data under EU MDR Annex XIV obligations.
Primary procurement volume: Hospitals. Fastest-growing customer segment: Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's medical technology free zones around Tuttlingen and Freiburg concentrate EU quadripodal implant production capacity. These clusters leverage proximity to university hospitals and specialized machining subcontractors.
Germany
Tertiary hospitals in Baden-Württemberg generate complex revision arthroplasty demand requiring four-point fixation systems. EU MDR recertification timelines compress commercial windows for manufacturers serving this market. The Tuttlingen-Freiburg corridor anchors precision titanium machining and notified body consulting services.
United States
Aging implant populations in major academic medical centers drive revision surgery volumes across the Midwest and Northeast. FDA 510(k) clearance pathways shape product development timelines for dual-market manufacturers. The Greater Boston and Minneapolis-St. Paul clusters concentrate orthopedic surgeon training networks and digital surgical planning development.
Japan
PMDA Sakigake fast-track designation attracts early regulatory filings for breakthrough quadripodal implant designs. METI industrial policy supports additive manufacturing adoption in medical device production. The Kansai region around Osaka maintains specialized titanium forging capacity for aerospace-medical crossover applications.
China
Domestic orthopedic demand expansion in tier-one cities pressures NMPA registration timelines for imported implant systems. National volume-based procurement reforms compress pricing for standardized configurations. The Yangtze River Delta clusters around Suzhou and Hangzhou concentrate contract manufacturing for multinational device firms.
Switzerland
Swissmedic's streamlined quality system recognition supports CE-marked portfolio maintenance under EU MDR parallel pathways. Precision machining heritage in the Jura Arc feeds medical component supply chains. The Basel-Zurich corridor hosts specialized biomaterials toxicology consulting for ISO 10993 compliance.
Quadripodal Implants Market Competitive Landscape
German producers anchor the precision-manufacturing tier; US specialists hold the digital-surgical-planning integration vector. The vendor base concentrates around three structural positions: diversified orthopedic conglomerates with broad CE-marked portfolios, mid-cap implant specialists with deep surgeon training relationships, and emerging additive manufacturing-native entrants. Consolidation pressure intensifies as EU MDR compliance costs escalate. Strategic moves center on notified body relationship deepening and patient-specific manufacturing workflow acquisition.
Within the diversified orthopedic tier, Stryker, Zimmer Biomet, and DePuy Synthes exemplify scale-driven positioning. Stryker occupies a position anchored in established notified body infrastructure. Zimmer Biomet represents the surgeon-training-network archetype. DePuy Synthes sits within the digital-ecosystem integration vector. These three firms collectively illustrate how compliance scale and clinical relationship depth separate sustainable European market access from portfolio rationalization pressures facing smaller competitors.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Smith & Nephew |
| Medtronic |
| Integra LifeSciences |
| Globus Medical |
| NuVasive |
| Orthofix |
| Others |
Value Network & Pricing Analysis
EU MDR sustainability and post-market surveillance mandates gate qualified supply access and premium-tier pricing for quadripodal implant manufacturers. Compliance infrastructure investments separate certified suppliers capable of commanding margin premiums from spot-market competitors facing procurement exclusion.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid-turnaround manufacturers with premium capture while penalizing inventory-heavy spot sellers. Three-tier pricing structure across premium, standard, and economy levels differentiates by EU MDR certification completeness and CT-to-implant customization depth. Cost compression in standard titanium configurations is intensifying because Russian feedstock disruptions have elevated ASTM F136 alloy spot pricing. Academic medical centers in Germany exhibit lowest price sensitivity due to bundled training contracts, while emerging market distributors face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Ukrainian and Russian titanium sponge suppliers that feed German precision machining clusters around Tuttlingen. Raw material dependencies center on ASTM F136 titanium alloy, PEEK composite feedstock, and cobalt-chrome bearing surfaces. Tariff exposure runs through aerospace-medical crossover forging capacity concentrated in Japan's Kansai region. Distribution runs through direct hospital contracting in Germany and GPO-aggregated procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification costs are forcing portfolio rationalization among sub-scale manufacturers, creating acquisition opportunities for well-capitalized consolidators.
For Market Incumbents: Deploy notified body relationship deepening as the primary defensive lever. Expand CE-marked portfolio breadth through accelerated Article 117 conformity submissions before queue congestion worsens. Acquire patient-specific manufacturing workflows to lock in maxillofacial reconstruction margins threatened by additive manufacturing-native entrants. For New Entrants and Emerging Players: Additive manufacturing-lattice topology convergence offers the most penetrable wedge for orthopedic applications. Target veterinary maxillofacial surgery in North American specialty clinics where regulatory barriers remain lower than human medical device pathways. Pursue direct-to-clinic digital sales models bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Notified body designation announcements are the leading indicator that mid-cap specialists have secured sustainable European market access. Frame five-to-ten year viability around EU MDR compliance infrastructure rather than product innovation pipelines. Monitor biomaterials toxicology hiring velocity at target firms as a signal of clinical evidence generation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Stryker's established relationships sustain broad CE-marked portfolios across implant lines. |
| Patient-Specific Manufacturing Acquisition | CT-to-CAD workflow integration captures margin premiums in Freiburg trauma centers. |
| Surgeon Training Network Expansion | Zimmer Biomet's cadaveric lab contracts concentrate purchasing influence within residency directors. |
| Additive Manufacturing Lattice Development | Electron beam melting with gyroid structures optimizes osseointegration pore architectures. |
| Veterinary Channel Direct Entry | Companion animal dentistry in North American clinics represents underpenetrated volume opportunity. |
Research Methodology
Independent corroboration across orthopedic surgeon interviews, notified body consultants, and hospital procurement managers underwrites the qualitative findings. Primary fieldwork captured perspectives from biomedical engineers, GPO contracts managers, and titanium alloy suppliers. Secondary validation drew from EU MDR designation databases, FDA 510(k) clearance records, hospital procurement disclosures, and ASTM material specification filings. Bottom-up implant volume modeling and top-down market sizing triangulate across the analysis window.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across product type, material grade, application complexity, and end-user procurement authority dimensions. CAGRs derive from segmented growth rate blending rather than single-equation extrapolation. Forecast inputs incorporate notified body queue length projections, titanium sponge spot price volatility bands, and revision arthroplasty incidence trajectory assumptions.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions to titanium feedstock corridors and abrupt FDA orthopedic panel precedent shifts. Forecasts reflect documented assumptions about EU MDR implementation pacing and PMDA Sakigake pathway utilization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
MRI Coils Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Deaver Retractor Market