
 Medical Liners Market | 2026-2036
Medical Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Liners Market Foresight
Buyer concentration among hospital networks is restructuring procurement dynamics across the medical liners supply chain. Olympus Corporation leverages its endoscopy ecosystem to anchor liner demand within integrated surgical suites. Saint-Gobain Performance Plastics sustains technology leadership in silicone barrier formulations for advanced wound applications. Tekni-Plex competes through vertical control over extruded polyethylene films serving disposable medical packaging.
Medical liners are thin, flexible membranes engineered from polyethylene, non-woven fabrics, polyurethane, or silicone, manufactured through calendering, extrusion, or melt-blown processes to deliver fluid absorption, microbial barrier, or skin protection in clinical and consumer health settings. Absorbent liners dominate volume flows in incontinence products where fluid retention capacity determines clinical acceptance, while barrier liners command premium positioning in surgical dressings requiring sterile field maintenance. Specialty liners represent the fastest-expanding material category as custom formulations address negative-pressure wound therapy and antimicrobial delivery systems.
FDA biocompatibility standards, EU MDR conformity requirements, and ISO 10993 testing protocols collectively elevate entry barriers for new material suppliers while forcing incumbent manufacturers toward validated cleanroom production. Japan's PMDA maintains distinct pharmaceutical-medical device combination product classifications that shape liner registration pathways for drug-eluting wound dressings. Stakeholders must monitor evolving regulatory convergence between device and pharmaceutical frameworks to anticipate compliance cost trajectories and qualification timeline shifts.
Market Dynamics
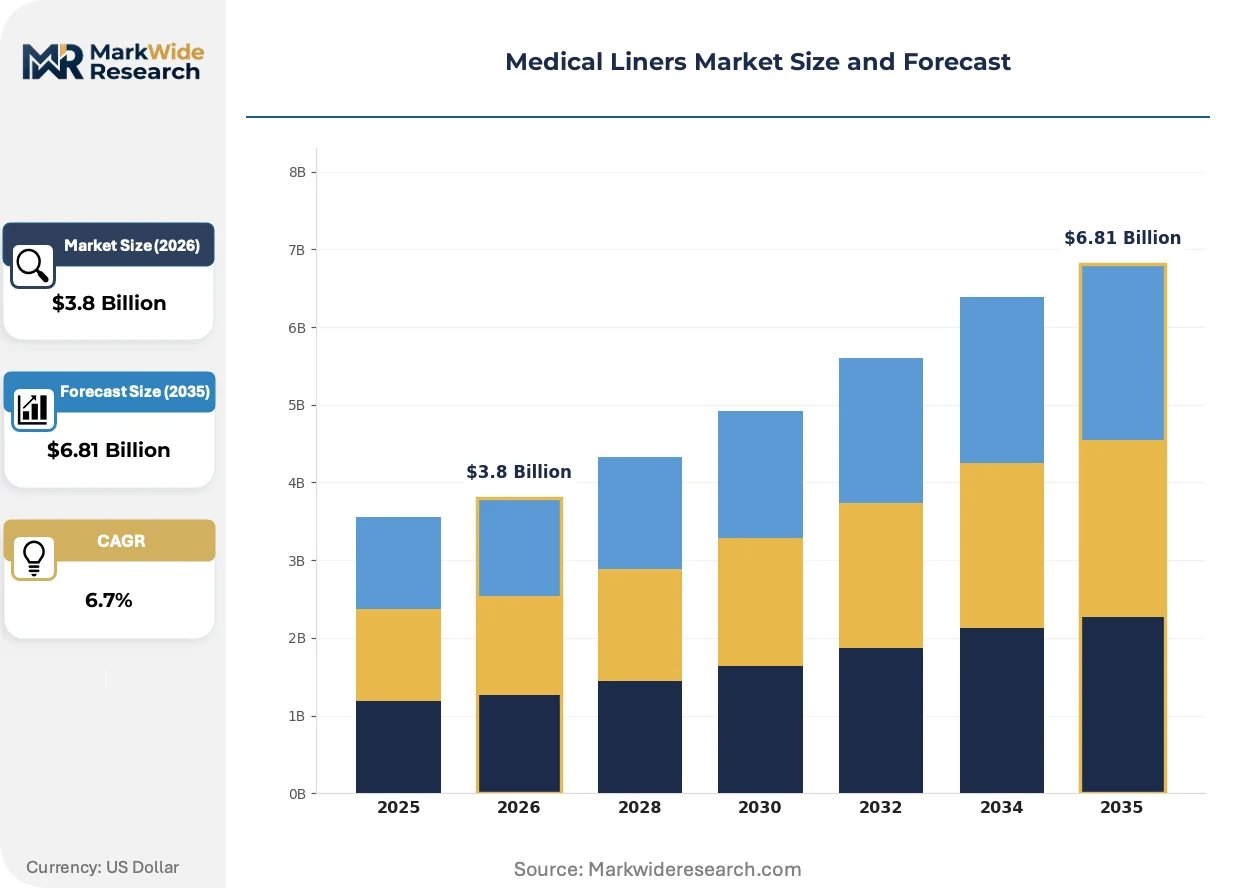
Hospital procurement consolidation and FDA biocompatibility standard updates are compressing supplier margins while accelerating material transitions toward validated silicone and polyurethane formulations across wound care and incontinence applications.
Growth Catalysts
- EU MDR conformity requirements:Stricter device classification rules are forcing manufacturers toward ISO 10993-validated cleanroom production, advantaging incumbent suppliers with established quality systems.
- Negative-pressure wound therapy:Specialty liner demand accelerates as NPWT systems expand into outpatient settings, requiring custom antimicrobial barrier formulations with precise vapor transmission rates.
- Japan's aging demographic concentration:Elevated surgical procedure volumes and incontinence product consumption in Tokyo-Osaka corridors sustain premium absorbent liner procurement from domestic distributors.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer feedstock depends on German and Japanese chemical producers, exposing converters to input cost volatility and allocation constraints.
- ISO 10993-5 cytotoxicity testing timelines:Extended biocompatibility validation protocols stretch new material qualification to 18-24 months, freezing formulation innovation cycles for mid-tier suppliers.
- Reusable textile barrier substitutes:Launderable surgical drapes and gowns in German outpatient clinics displace single-use polyethylene liners in select low-risk procedures.
Strategic Opportunities
- Drug-eluting wound dressing convergence:Pharmaceutical-device combination products create white space for liners with controlled-release antimicrobial coatings, requiring PMDA and FDA dual-track registration strategies.
- Direct-to-patient subscription channels:E-commerce platforms bypass traditional hospital distribution for incontinence liners, capturing margin from retail pharmacy intermediaries in United States metropolitan markets.
- India PLI scheme for medical textiles:Domestic manufacturing incentives attract calendering and melt-blown capacity investments serving South Asian export demand.
Industry Challenges
- Cleanroom polymer extrusion technician scarcity:Qualified operators for medical-grade film production command 40% wage premiums in United States Midwest manufacturing clusters, constraining capacity expansion.
- Legacy ERP-to-UDI integration complexity:Hospital networks demand unit-level traceability compliance, forcing liner converters to reconfigure batch record systems for FDA Unique Device Identification mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Liners Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Liners, Barrier Liners, Protective Liners, Specialty Liners Material: Polyethylene, Non-Woven Fabrics, Polyurethane, Silicone Application: Wound Care, Incontinence Products, Surgical Dressings, Protective Equipment End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Yang Zhou Huike Electronic, Allied Healthcare Products, Olympus Corporation, Gemmy Industrial Corp., Ohio Medical, ATMOS Medizin Tchnik, Tekni-Plex, Saint-Gobain Performance Plastics, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Liners Market Shifts & Advancements
Active material science convergence with digital health infrastructure is redefining liner functionality beyond passive barriers toward therapeutic delivery and real-time monitoring integration.
Antimicrobial silver-ion and chlorhexidine-impregnated polyurethane films are integrating into advanced wound dressings for diabetic foot ulcer management. Academic medical centers in Boston and Rotterdam are piloting these formulations within value-based care bundles. The technology is integrating clinical outcomes data capture directly into supplier-hospital contracting structures, compressing traditional price-volume negotiations toward performance-guarantee frameworks.
Japan's PMDA revised pharmaceutical-medical device combination product guidance in 2023, creating distinct registration pathways for drug-eluting liners. The regulation forces wound care manufacturers toward dual-quality-system compliance bridging ISO 13485 and GMP pharmaceutical standards. German converters with existing pharmaceutical coating capabilities are capturing first-mover advantage in European antimicrobial dressing segments.
Hospital network procurement consolidation is consolidating supplier panels toward single-source contracts with integrated service commitments. Group purchasing organizations in United States and Netherlands are unbundling liner procurement from broader surgical kit agreements, enabling direct manufacturer negotiation. This disintermediation concentrates volume with vertically integrated film extruders capable of custom width and thickness specifications delivered on consignment.
Medical Liners Market Segmentation
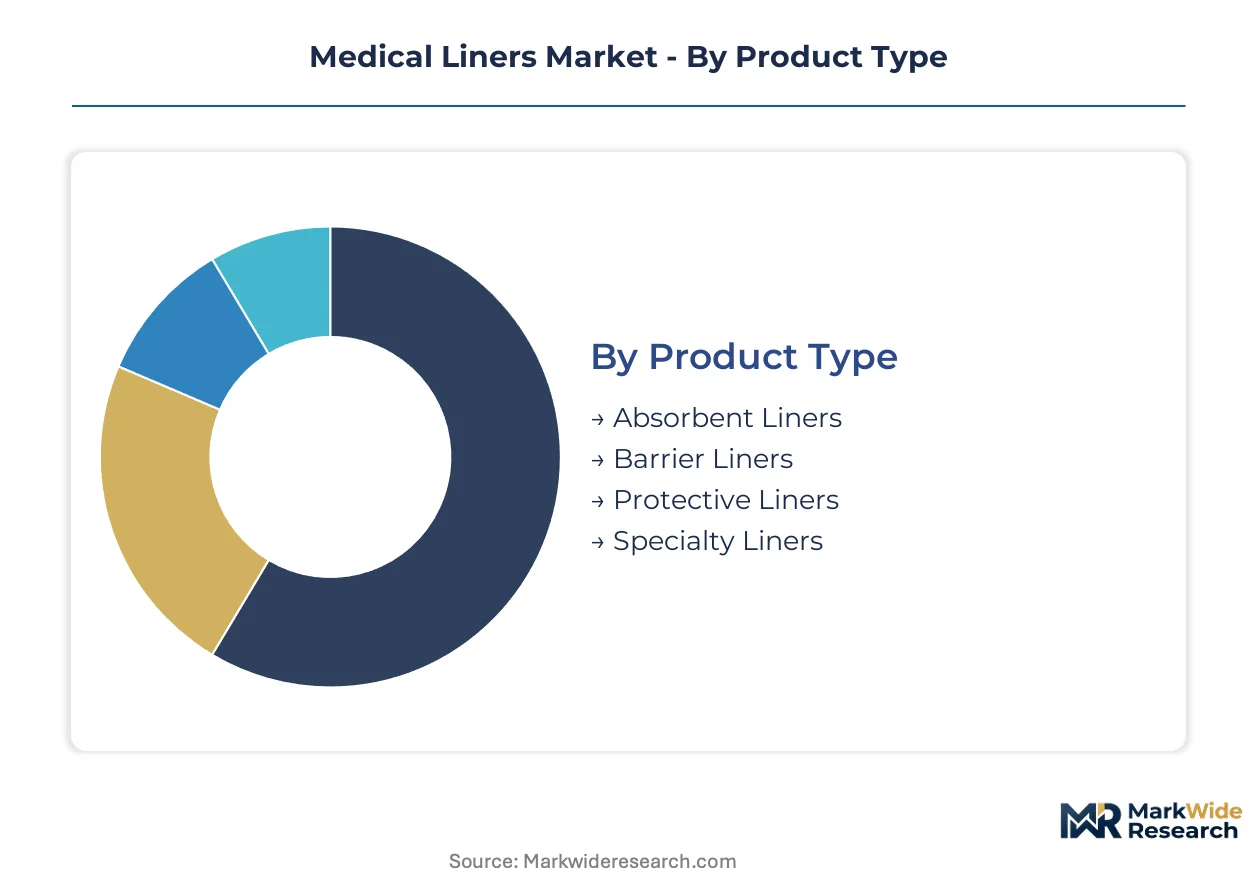
Medical liners serve divergent clinical workflows that impose incompatible performance specifications. Procurement patterns split sharply between high-volume disposable consumption in incontinence management and precision-engineered barriers for sterile surgical fields.
Product Type:
Buyer differentiation hinges on fluid handling capacity versus microbial exclusion requirements.
- Absorbent Liners:Engineered from superabsorbent polymer cores wrapped in non-woven acquisition layers, these liners manage urine and exudate volumes exceeding 800ml in acute care settings. Demand concentrates in United States long-term care facilities where Medicaid reimbursement rates drive cost-per-change optimization.
- Barrier Liners:Multi-layer polyethylene and polyurethane films maintain sterile field integrity through controlled vapor transmission rates of 800-1500g/m²/24hr. German outpatient surgical centers prioritize these liners within value-based procedure bundles that penalize surgical site infections.
- Protective Liners:Single-use polyethylene sheeting for equipment and surface coverage in procedural rooms.
- Specialty Liners:Custom-formulated membranes for negative-pressure wound therapy systems requiring precise antimicrobial elution profiles.
Absorbent liners lead volumes today; specialty liners are gaining share fastest.
Material:
Cost tier and clinical risk tolerance determine substrate selection across end-use applications.
- Polyethylene:Blown and cast film grades dominate commodity incontinence products where calendering lines achieve 200+ meters per minute throughput. Japanese converters leverage domestic petrochemical feedstock integration to maintain margin in standard-grade procurement.
- Non-Woven Fabrics:Spunbond-meltblown-spunbond laminates provide skin-facing comfort layers with 15-25gsm basis weights. United States home care distributors specify these materials for direct-to-patient subscription channels where softness ratings drive retention.
- Polyurethane:Thermoplastic elastomer films enable breathable barriers with 10,000+ g/m²/24hr moisture vapor transmission for extended wear applications.
- Silicone:Medical-grade platinum-cured elastomers command 4-6x polyethylene pricing for advanced wound dressings requiring biocompatibility validation under ISO 10993-5 cytotoxicity protocols.
Polyethylene dominates tonnage; silicone exhibits the steepest expansion trajectory.
Application:
Regulatory classification intensity varies dramatically across clinical use cases.
- Wound Care:Antimicrobial-impregnated polyurethane and silicone liners manage exudate in diabetic foot ulcers and pressure injuries. FDA 510(k) clearance requirements for drug-device combination products extend development timelines to 18-24 months.
- Incontinence Products:Adult briefs and underpads consume 60%+ of global absorbent liner volume, with procurement centralized through hospital group purchasing organizations and retail pharmacy chains.
- Surgical Dressings:Sterile barrier liners maintain incision site protection through specified bacterial filtration efficiency thresholds.
- Protective Equipment:Disposable drapes and gown reinforcement layers for isolation protocol compliance.
Incontinence products anchor volume; wound care climbs the fastest.
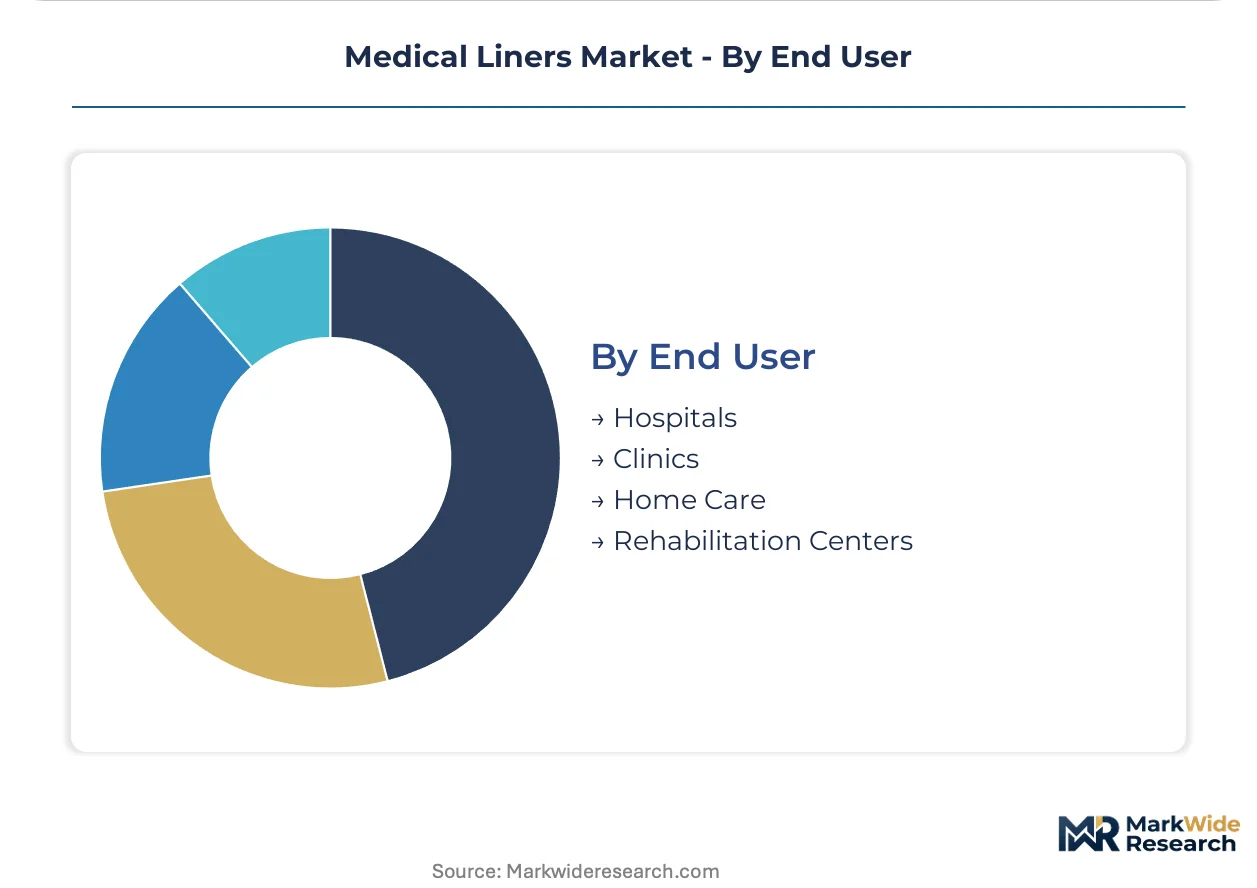
End User:
Procurement sophistication and compliance burden scale with institutional scale and regulatory exposure.
- Hospitals:Integrated delivery networks in United States and Netherlands consolidate liner procurement through single-source contracts with consignment inventory and unit-level UDI traceability mandates. FDA Unique Device Identification requirements force ERP system upgrades costing $500K-$2M per converter.
- Clinics:German outpatient surgical centers and Japanese dialysis clinics purchase through regional distributors with limited custom specification capability.
- Home Care:Direct-to-patient e-commerce channels bypass traditional distribution, capturing 15-20 point margin improvements for incontinence liner manufacturers.
- Rehabilitation Centers:Skilled nursing facilities with mixed payer populations prioritize cost containment over performance differentiation.
Hospitals command procurement volume; home care channels expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan present contrasting procurement intensities, with German outpatient surgical centers driving barrier liner specifications while Japanese distributors absorb premium absorbent volumes for aging urban populations. The United States anchors hospital network consolidation, and India's manufacturing incentives reshape supply geography.
United States
Integrated delivery networks in the Midwest and Southeast concentrate procurement through single-source contracts with consignment inventory requirements. FDA Unique Device Identification mandates force ERP system upgrades costing $500K-$2M per converter. Boston academic medical centers pilot antimicrobial-impregnated polyurethane formulations within value-based care bundles.
Germany
Outpatient surgical centers in Bavaria and North Rhine-Westphalia prioritize barrier liners within infection-prevention procedure bundles that penalize surgical site complications. EU MDR conformity requirements advantage incumbent suppliers with ISO 10993-validated cleanroom production. German chemical producers concentrate medical-grade silicone feedstock supply, exposing converters to allocation constraints.
Japan
Tokyo-Osaka corridors sustain premium absorbent liner procurement as surgical procedure volumes and incontinence product consumption climb among concentrated aging demographics. PMDA maintains distinct pharmaceutical-medical device combination product classifications that shape liner registration pathways for drug-eluting wound dressings. Domestic converters leverage petrochemical feedstock integration to maintain margin in standard-grade procurement.
India
The PLI scheme for medical textiles attracts calendering and melt-blown capacity investments serving South Asian export demand. CDSCO device classification rules are tightening for imported wound care materials, advantaging domestic manufacturers with established quality systems. Maharashtra and Gujarat industrial clusters host emerging film extrusion capacity targeting Middle East and African markets.
United Kingdom
NHS procurement consolidation drives liner specification toward standardized absorbency ratings and bulk contract structures. MHRA post-Brexit regulatory autonomy creates parallel registration pathways that extend qualification timelines for EU-originating suppliers. London and Southeast England distribution hubs manage inventory for hospital networks across England and Wales.
Medical Liners Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers in the medical liners supply chain. Market structure shows moderate consolidation among film extruders serving hospital networks, with fragmentation among regional distributors handling incontinence product flows. Three archetypes dominate: integrated material science conglomerates with pharmaceutical coating capabilities, specialized medical film extruders with cleanroom certification, and diversified packaging converters leveraging scale in commodity polyethylene. Competitive dynamics center on backward integration into polymer feedstock and strategic partnerships with negative-pressure wound therapy system manufacturers.
Within the integrated material science tier, Saint-Gobain Performance Plastics and Tekni-Plex exemplify divergent strategic positions. Saint-Gobain anchors premium barrier formulations through captive silicone elastomer capabilities. Tekni-Plex occupies a position at the scale-driven end of extruded polyethylene film supply for disposable medical packaging. Olympus Corporation represents the device-integrated archetype, leveraging endoscopy ecosystem relationships to anchor liner demand within surgical suite procurement bundles.
| Leading Market Players |
|---|
| Yang Zhou Huike Electronic |
| Allied Healthcare Products |
| Olympus Corporation |
| Gemmy Industrial Corp. |
| Ohio Medical |
| ATMOS Medizin Tchnik |
| Tekni-Plex |
| Saint-Gobain Performance Plastics |
| Mondi |
| Others |
Supply & Pricing Matrix
ISO 10993 certification tiers bifurcate the medical liners market into validated cleanroom producers commanding premium positioning versus commodity converters facing margin compression, with this divergence manifesting in both pricing power concentration among German and Japanese silicone specialists and supply chain restructuring toward captive feedstock control.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade polyethylene liners while premium silicone formulations maintain elevation through medical-grade platinum-cure validation requirements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with cost compression in commodity tiers intensifying because of Medicaid reimbursement pressure in United States long-term care. Hospital group purchasing organizations exhibit lowest price sensitivity for barrier liners within surgical site infection penalty bundles, while home care distributors show highest sensitivity on absorbent products.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States integrated delivery networks, while regional distributors manage fragmented clinic procurement across German outpatient centers. Raw material sourcing draws from German and Japanese chemical producers for medical-grade silicone, United States petrochemical complexes for polyethylene, and domestic Indian feedstock for emerging calendering capacity. Single-source vulnerability concentrates in platinum-cure silicone elastomer supply, exposing converters to allocation constraints. Distribution runs through hospital group purchasing organizations in North America, specialized medical distributors in Europe, and direct-to-patient e-commerce platforms for incontinence products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical liners manufacturing presents a geographic-arbitrage play between India's PLI-subsidized production costs and Japan's premium pricing for PMDA-registered combination products, with regulatory compliance differentials creating margin capture opportunities for dual-registered suppliers.
For Market Incumbents: Extend cleanroom certification coverage into pharmaceutical-grade coating capabilities to capture drug-eluting wound dressing convergence, while anchoring silicone feedstock through backward integration into German or Japanese chemical partnerships. Reusable textile barrier substitutes in German outpatient settings threaten single-use polyethylene volumes, making ISO 10993-5 cytotoxicity testing capacity the priority defensive investment.
For New Entrants and Emerging Players: Antimicrobial silver-ion polyurethane formulations offer technology-first wedge positioning against established barrier liner suppliers, with negative-pressure wound therapy outpatient expansion representing the most penetrable application segment. Target direct-to-patient subscription channels in United States metropolitan markets to bypass retail pharmacy intermediaries and capture 15-20 point margin improvements.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack ERP-to-UDI integration capabilities required by FDA hospital network mandates, creating acquisition targets among film extruders with cleanroom certification but legacy batch record systems. Long-term viability over the projection horizon favors vertically integrated players with captive silicone supply and dual-track FDA-PMDA registration infrastructure. Watch for PMDA guidance revisions on pharmaceutical-device combination products as inflection indicator for wound care segment repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-5 Cytotoxicity Validation Investment | Accelerates qualification timelines for silicone barrier formulations against 18-24 month testing protocols. |
| Dual-Track FDA-PMDA Registration | Captures first-mover advantage in drug-eluting wound dressings through converged quality systems. |
| Backward Integration into Medical-Grade Silicone | Insulates margin from German and Japanese chemical producer allocation constraints. |
| Direct-to-Patient E-Commerce Launch | Bypasses retail pharmacy intermediaries in United States incontinence product distribution. |
| Hospital System Partnership with Consignment Inventory | Locks in volume through integrated delivery network single-source contracts with UDI traceability compliance. |
Research Methodology
Bottom-up wound care and incontinence modeling reconciled against top-down medical film extrusion capacity tracking forms the analytical core, combining primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and cleanroom production technicians with secondary validation against FDA 510(k) filings, PMDA submission databases, hospital procurement records, and EU MDR conformity assessment documentation. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity across absorbent, barrier, and specialty liner categories.
Historical trendline analysis of medical-grade film pricing and surgical procedure volumes anchors the projection framework, with CAGR derivation reflecting material transition dynamics toward silicone and polyurethane formulations across the analysis window. Segmentation dimensions modeled include product type, material substrate, application workflow, and end-user procurement sophistication, with forecast inputs incorporating EU MDR implementation pace and Japan's aging demographic surgical volume trajectories.
The model holds under stable regulatory convergence timelines between device and pharmaceutical frameworks; deviation in PMDA or FDA guidance acceleration would shift qualification cost assumptions. Forecasts reflect documented base conditions including continued hospital procurement consolidation and cleanroom technician scarcity in United States Midwest clusters. Periodic stress-testing of base assumptions is recommended against antimicrobial resistance patterns and reusable textile barrier adoption rates in European outpatient settings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Compression Socks Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Endoscope Cleaning Products Market