
 Heart Closure Devices Market | 2026-2036
Heart Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Closure Devices Market Intelligence
Modular procedure kits bundling delivery sheaths with occluder devices is expanding buyer choice in the heart closure devices space. Abbott Laboratories leverages its structural heart portfolio to sustain integrated catheter-occluder offerings across major cardiac centers. Medtronic plc anchors its position through deep manufacturing scale in nitinol mesh production. Occlutech International AB specializes in customizable left atrial appendage solutions that differentiate its catalog from larger competitors.
Heart closure devices are implantable mechanical or biological constructs, typically fabricated from nitinol wire mesh with polyester fabric inserts, designed to achieve permanent tissue integration and hemodynamic isolation of cardiac septal defects or vascular shunts. Their primary purpose is to eliminate abnormal blood flow between heart chambers or great vessels without open surgical intervention. Septal occluders occupy the dominant revenue position due to established reimbursement pathways for atrial septal defect repair, while transcatheter delivery mode segments capture the fastest expansion as catheterization labs upgrade capabilities. Closure plugs retain concentrated margin pools in pediatric applications where anatomical variability demands specialized sizing.
The FDA maintains stringent premarket approval requirements for transcatheter occluders through its Office of Cardiovascular Devices, while the European Medicines Agency enforces MDR compliance timelines that compress certification cycles for nitinol-based implants. These frameworks elevate clinical evidence thresholds and concentrate market access among manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor how evolving FDA breakthrough device designation criteria reshape competitive timelines for novel closure mechanisms.
Market Dynamics
Structural heart programs at cardiac centers are absorbing catheterization lab upgrades that compress procedure times and expand patient throughput for minimally invasive closure interventions.
Growth Catalysts
- Transcatheter delivery mode:Catheterization labs across Germany, the United States, and Japan are retrofitting infrastructure to accommodate same-day discharge protocols for septal defect repair.
- MDR compliance timelines:The European Medicines Agency's compressed certification cycles for nitinol-based implants are accelerating evidence-generation investments by established manufacturers.
- Specialized heart valve centers:Concentrated clinical expertise in urban German medical clusters drives protocol standardization and referral network density for next-generation occluder adoption.
Market Restraints
- Nitinol wire supply concentration:Superelastic alloy production for mesh fabrication concentrates among a limited supplier base in Western Europe and East Asia, exposing device makers to input volatility.
- FDA premarket approval thresholds:The Office of Cardiovascular Devices maintains stringent clinical evidence requirements that extend development timelines for novel closure mechanisms.
- Surgical closure persistence:Open surgical repair retains preference for complex anatomical variants in pediatric populations where transcatheter sizing constraints limit applicability.
Strategic Opportunities
- Left atrial appendage closure expansion:Stroke prevention protocols in atrial fibrillation populations create procedural white space beyond traditional septal defect indications.
- Modular procedure kit bundling:Integrated delivery sheath-occluder combinations enable premium positioning through reduced inventory complexity for catheterization lab purchasers.
- Breakthrough device designation pathway:Evolving FDA criteria for novel closure mechanisms offer compressed review timelines for first-in-class technologies demonstrating superior hemodynamic performance.
Industry Challenges
- Interventional cardiologist training pipelines:Specialized structural heart fellowships produce insufficient operators to match catheterization lab expansion rates at tertiary centers.
- Reimbursement code fragmentation:Divergent national health technology assessment methodologies across European markets complicate parallel market entry strategies for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Closure Devices Market |
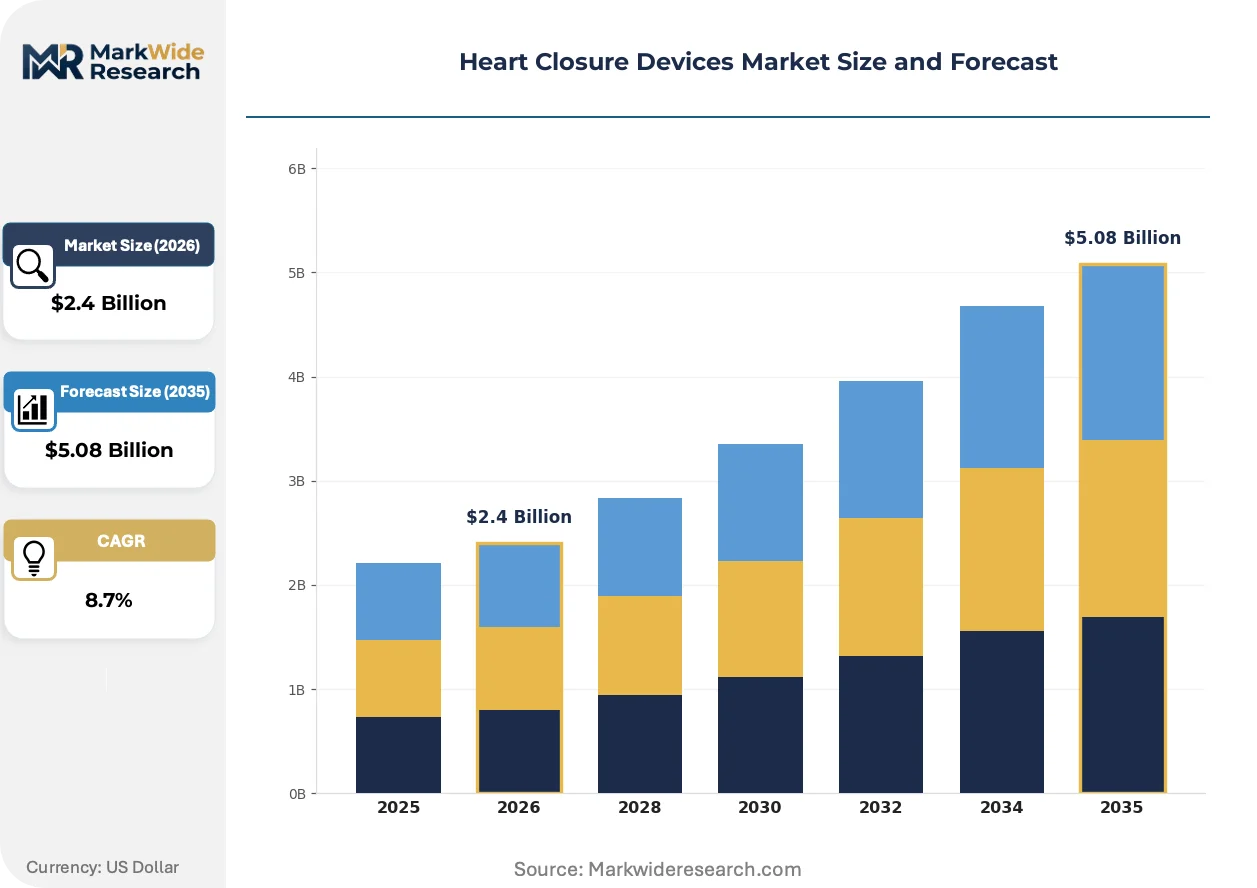
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Septal Occluders, Closure Plugs, Catheters, Stents Application: Atrial Septal Defect, Patent Foramen Ovale, Ventricular Septal Defect, Others End User: Hospitals, Cardiac Centers, Clinics, Surgical Centers Delivery Mode: Transcatheter, Surgical, Hybrid, Percutaneous |
| Companies Covered | Edwards Lifesciences Corporation, Occlutech International AB, Abbott Laboratories, Lepu Medical Technology, AtriCure Inc., Boston Scientific Corporation, W. L. Gore & Associates Inc., LivaNova PLC, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Closure Devices Market Strategic Shifts & Innovations
Device architecture is absorbing computational modeling advances that compress design iteration cycles and enable patient-specific occluder geometries. Three developments are restructuring competitive positioning.
Bioresorbable polymer scaffolds are absorbing nickel release concerns that previously constrained pediatric applications and nickel-sensitive patient populations. Pediatric cardiac centers in the United States are piloting magnesium-based closure frameworks that eliminate permanent implant burden. The technology is absorbing regulatory scrutiny around degradation kinetics and endothelialization timing that manufacturers must resolve before broader commercialization.
The FDA's evolving guidance on transcatheter device trials is reshaping pivotal study design requirements for structural heart interventions. Manufacturers now face expanded imaging endpoints and longer follow-up protocols that elevate clinical program costs. Septal occluder segments absorb the most significant compliance burden as established predicate devices raise evidentiary bars for non-inferiority claims.
Catheterization lab purchasing consortia are consolidating procurement authority across multi-hospital systems in the United States and Germany. Integrated delivery networks now negotiate bundled device-sheath agreements that disaggregate traditional distributor relationships. This concentration is most visible in urban cardiac center clusters where procedure volumes justify direct manufacturer contracting.
Heart Closure Devices Market Segmentation
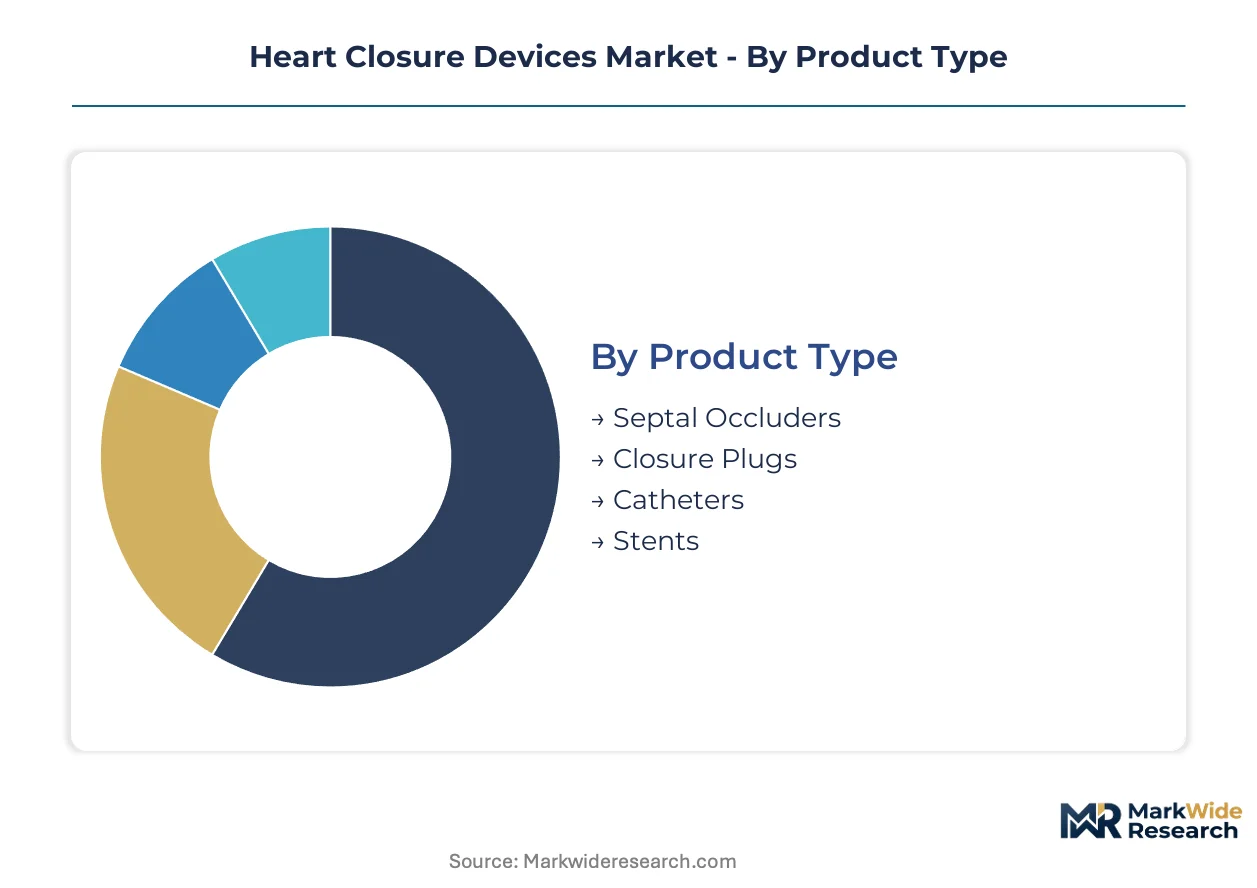
Product architecture in heart closure devices fragments across implantable constructs, delivery systems, and procedural accessories. Each segment carries distinct regulatory pathways, manufacturing scale requirements, and clinical training demands that reshape competitive entry barriers.
Product Type:
Manufacturing scale concentrates in nitinol mesh fabrication and polyester textile integration, with supply constraints rippling through downstream device assembly.
- Septal Occluders:Double-disc nitinol wire frames with central polyester fabric waists achieve hemodynamic isolation of atrial and ventricular septal defects. Cardiac centers in Germany and the United States absorb the majority of procedural volume as reimbursement pathways mature for adult congenital heart disease interventions.
- Closure Plugs:Cylindrical or mushroom-shaped constructs fabricated from biocompatible polymers or metal alloys address patent ductus arteriosus and vascular shunts. Pediatric applications in specialized surgical centers drive demand variability due to anatomical sizing constraints that complicate standardized manufacturing.
- Catheters:Delivery sheaths and guiding catheters engineered for transseptal navigation and device deployment.
- Stents:Scaffold structures occasionally deployed in conjunction with closure procedures for coarctation or vascular support.
Septal occluders absorb the bulk of installed capacity; closure plugs are expanding most quickly in pediatric specialty networks.
Application:
Clinical indication segmentation tracks congenital prevalence patterns, procedural complexity gradients, and evolving eligibility criteria across age cohorts.
- Atrial Septal Defect:Secundum-type defects constitute the dominant transcatheter closure indication, with device sizing algorithms now incorporating three-dimensional echocardiographic modeling. German heart valve centers and United States cardiac centers standardize protocols that compress pre-procedural screening timelines.
- Patent Foramen Ovale:Cryptogenic stroke prevention drives expanded eligibility beyond traditional congenital repair, though reimbursement variability across national health systems constrains uniform adoption. Japanese stroke centers pilot expanded closure criteria for recurrent cerebrovascular events.
- Ventricular Septal Defect:Muscular and perimembranous defects requiring precise device positioning to avoid conduction system compromise.
- Others:Left atrial appendage closure and paravalvular leak occlusion emerging as procedural extensions.
Atrial septal defect procedures anchor current utilization; patent foramen ovale closure is gaining share fastest as stroke prevention protocols evolve.
End User:
Site-of-care economics fragment procurement authority across integrated delivery networks, standalone specialty facilities, and ambulatory surgical platforms.
- Hospitals:Tertiary academic medical centers maintain hybrid operating suites combining surgical backup with catheterization lab capabilities. Urban United States hospital systems consolidate purchasing through multi-facility consortia that negotiate direct manufacturer contracts.
- Cardiac Centers:Dedicated structural heart programs concentrate interventional cardiologist expertise and procedure volume sufficient to justify dedicated device inventory. German metropolitan clusters demonstrate highest per-capita catheterization lab density for minimally invasive closure.
- Clinics:Outpatient diagnostic and follow-up facilities without procedural capabilities.
- Surgical Centers:Ambulatory platforms capturing select low-complexity pediatric closures.
Cardiac centers command premium positioning through volume concentration; hospitals retain the deepest installed base across combined service lines.
Delivery Mode:
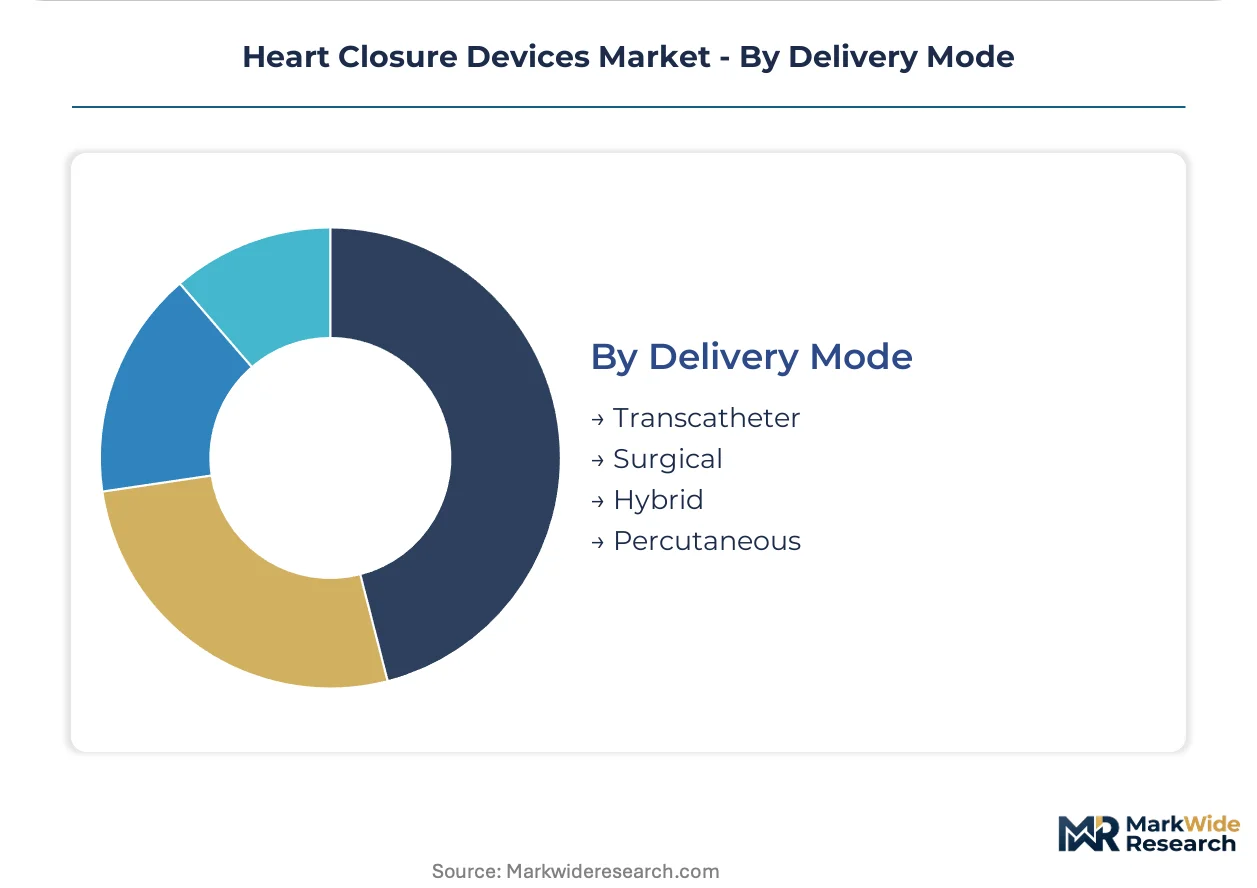
Procedural approach segmentation reflects infrastructure investment cycles, operator training pipelines, and same-day discharge protocol feasibility.
- Transcatheter:Percutaneous femoral or jugular access with fluoroscopic and echocardiographic guidance eliminates sternotomy and cardiopulmonary bypass. Catheterization labs across Japan, Germany, and the United States retrofit angiography suites to accommodate structural heart device delivery.
- Surgical:Open repair through median sternotomy or thoracotomy retains preference for complex anatomical variants and concomitant procedures.
- Hybrid:Combined surgical and interventional approaches in hybrid operating rooms.
- Percutaneous:Minimally invasive access techniques distinct from full transcatheter deployment systems.
Transcatheter delivery claims the steepest expansion trajectory as lab infrastructure proliferates; surgical closure defends position in anatomically complex pediatric cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale for nitinol mesh fabrication concentrates in Germany and the United States, while procedural demand expands fastest across specialized cardiac centers in Japan and urban clusters in Western Europe. Consumption patterns diverge sharply between mature reimbursement environments and emerging markets where private health infrastructure drives device adoption.
United States
Structural heart programs at tertiary cardiac centers absorb the majority of transcatheter closure procedures, with catheterization lab upgrades compressing same-day discharge timelines. The FDA's Office of Cardiovascular Devices maintains stringent premarket approval thresholds that elevate clinical evidence requirements for novel occluder mechanisms. The Boston-Cleveland corridor concentrates hybrid operating suite investments where academic medical centers standardize minimally invasive protocols.
Germany
Specialized heart valve centers in metropolitan clusters drive protocol standardization and referral network density for next-generation occluder adoption. The EMA's MDR compliance timelines compress certification cycles for nitinol-based implants, accelerating evidence-generation investments by established manufacturers. The Rhine-Ruhr and Bavarian medical clusters demonstrate highest per-capita catheterization lab density for septal defect repair.
Japan
Stroke prevention protocols for patent foramen ovale closure expand eligibility criteria beyond traditional congenital repair, with PMDA regulatory pathways adapting to incorporate expanded imaging endpoints. Japanese stroke centers pilot closure criteria for recurrent cerebrovascular events that reshape procedural indications. The Tokyo-Osaka corridor concentrates interventional cardiologist training pipelines and catheterization lab retrofit investments.
China
Domestic nitinol wire supply expansion reduces import dependency for mesh fabrication, with NMPA regulatory harmonization accelerating local manufacturing scale-up. Provincial cardiac centers in the Yangtze River Delta and Pearl River Delta absorb the bulk of pediatric and adult congenital closure volumes. Shanghai and Beijing medical clusters drive protocol adoption for transcatheter delivery modes.
Switzerland
Swissmedic maintains rigorous post-market surveillance requirements for permanent implants that elevate long-term follow-up obligations for device manufacturers. Precision manufacturing heritage in the Basel-Zurich corridor supports specialized nitinol component fabrication for export markets. Swiss cardiac centers concentrate expertise in complex anatomical variants requiring customized occluder sizing.
Heart Closure Devices Market Key Industry Players
The competitive structure tilts toward diversified structural heart portfolios rather than pure-play specialists. Three to five multinational conglomerates anchor revenue concentration through integrated catheter-occluder offerings, while mid-scale specialists defend margin positions in customizable left atrial appendage solutions. Strategic moves center on modular procedure kit bundling and direct contracting with catheterization lab purchasing consortia.
Within the diversified structural heart tier, Abbott Laboratories and Medtronic plc occupy positions defined by manufacturing scale and integrated delivery system portfolios. Occlutech International AB exemplifies the specialist archetype through focused left atrial appendage customization capabilities. Edwards Lifesciences Corporation and Boston Scientific Corporation represent the transcatheter innovation vector where regulatory affairs infrastructure concentrates market access among established players.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Occlutech International AB |
| Abbott Laboratories |
| Lepu Medical Technology |
| AtriCure Inc. |
| Boston Scientific Corporation |
| W. L. Gore & Associates Inc. |
| LivaNova PLC |
| Medtronic plc |
| Others |
Cost & Logistics Intelligence
Specialized nitinol metallurgists in the Basel-Zurich corridor command wage premiums that propagate through device cost structures, compressing margin spreads between premium catheter-occluder bundles and standard septal occluder configurations.
Pricing Analysis
Margin tightening in standard septal occluder tiers reflects catheterization lab purchasing consortia leveraging volume concentration for direct manufacturer contracts. Three-tier pricing structure across premium integrated kits, standard occluder-sheath combinations, and economy standalone devices stratifies by FDA breakthrough designation status and bundled after-sales support. Pricing pressure stems from German cardiac center procurement alliances consolidating multi-hospital negotiations. Pediatric specialty clinics exhibit highest price sensitivity due to anatomical customization demands, while tertiary academic medical centers absorb premium positioning for same-day discharge protocols.
Supply Chain Analysis
Workforce availability for precision nitinol wire drawing concentrates in Germany, Switzerland, and select Japanese industrial clusters, constraining mesh fabrication scale-up. Superelastic alloy production draws from titanium-nickel feedstock suppliers in Western Europe and East Asia, with polyester textile integration anchoring downstream device assembly in German manufacturing hubs. Single-source vulnerability pervades nitinol wire supply given limited qualified metallurgical facilities. Distribution runs through catheterization lab purchasing consortia disintermediating traditional distributor networks in United States urban cardiac clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive nitinol wire production and direct hospital system contracting determine margin defense against procurement concentration.
For Market Incumbents: Anticipate catheterization lab purchasing consortia consolidation by securing long-term supply agreements with German and Swiss nitinol wire fabricators. Deepen backward integration into superelastic alloy production to offset input volatility from East Asian suppliers. Prioritize FDA breakthrough device designation investments to compress review timelines against emerging bioresorbable polymer substitutes.
For New Entrants and Emerging Players: Enter via left atrial appendage closure customization where patient-specific occluder geometries escape commodity pricing pressure. Target Japanese stroke centers piloting expanded patent foramen ovale closure criteria for recurrent cerebrovascular events. Deploy computational modeling partnerships with academic medical centers to differentiate on patient-specific design capabilities.
For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with customizable left atrial appendage portfolios and established European MDR compliance infrastructure. Monitor FDA guidance evolution on transcatheter device trial imaging endpoints as inflection indicator for clinical program cost escalation. Favor targets with captive nitinol mesh fabrication or hybrid operating suite partnerships in United States academic medical centers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compressed timelines force evidence-generation investments by established nitinol implant manufacturers. |
| Hospital System Partnership | Direct catheterization lab contracting with United States multi-facility consortia disintermediates traditional distribution. |
| Backward Integration | In-house nitinol wire production insulates margin pressure from Western European and East Asian supply concentration. |
| Software Companion Development | Three-dimensional echocardiographic modeling integration compresses pre-procedural screening timelines for septal defect repair. |
| Reimbursement Strategy | CMS Medicare coverage determinations for patent foramen ovale stroke prevention reshape eligible patient populations. |
Research Approach
Multi-period observation of catheterization lab upgrade cycles, FDA premarket approval timelines, and EMA MDR certification completions anchored the trend analysis, supplemented by interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers specializing in structural heart devices, GPO contracts managers, and regulatory affairs leads at nitinol implant manufacturers. Secondary validation drew from FDA 510(k) and PMA filings, EMA MDR technical documentation, hospital procurement databases, CMS Medicare coverage determinations, and German heart valve center accreditation records. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates.
The input-output matrix framed demand-side projections through segmentation across product architecture, clinical indication, site-of-care economics, and procedural approach dimensions. CAGRs derived from installed catheterization lab capacity expansion rates, operator training pipeline throughput, and reimbursement pathway maturation trajectories across the analysis window. Industry-specific forecast inputs incorporated nitinol wire supply elasticity and breakthrough device designation approval velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance shifts on transcatheter trial imaging endpoints or nitinol supply disruptions from Western European metallurgical facilities. Material deviation in EMA MDR enforcement intensity or catheterization lab purchasing consortia consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Pectus Bar Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Treatment Pumps Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Human Enhancement Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Global on-Body Injectors Market