
 Nasometry Devices Market | 2026-2036
Nasometry Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nasometry Devices Market Foresight
Aftermarket calibration and software upgrade revenue is reconfiguring margin pools away from one-time hardware sales across the nasometry landscape. PENTAX Medical leverages its endoscopy channel infrastructure to bundle nasometry with laryngoscopy workflows. Medtronic plc anchors its position through deep integration with surgical navigation platforms in tertiary hospitals. Interacoustics A/S specializes in audiologist-centric distribution, competing on protocol standardization rather than price alone.
Nasometry devices measure nasal airflow and acoustic energy during speech production using pressure transducers and sound separation plates, typically sampling at rates exceeding 10 kHz to capture velopharyngeal closure dynamics. These instruments serve speech-language pathologists and otolaryngologists in quantifying hypernasality and planning surgical or therapeutic intervention. Portable devices now lead unit shipments as clinic-based speech therapy expands beyond hospital walls, while software solutions capture expanding margin pools through subscription-based analytics and remote monitoring capabilities. Signal processing technology underpins competitive differentiation, with biometric feedback applications emerging as the fastest-growing segment as biofeedback-driven rehabilitation protocols gain clinical traction.
FDA 510(k) premarket notification requirements shape product development timelines and clinical validation burdens for manufacturers targeting the United States, while the EU Medical Device Regulation (MDR) and CE marking obligations govern European market access with intensified post-market surveillance demands. ISO 13485 quality management certification has become table stakes for contract manufacturing relationships and OEM supply agreements. Stakeholders must monitor evolving reimbursement codes for speech pathology diagnostics across Medicare and national health systems, as coding recognition directly determines addressable clinic budgets and device procurement cycles.
Market Dynamics
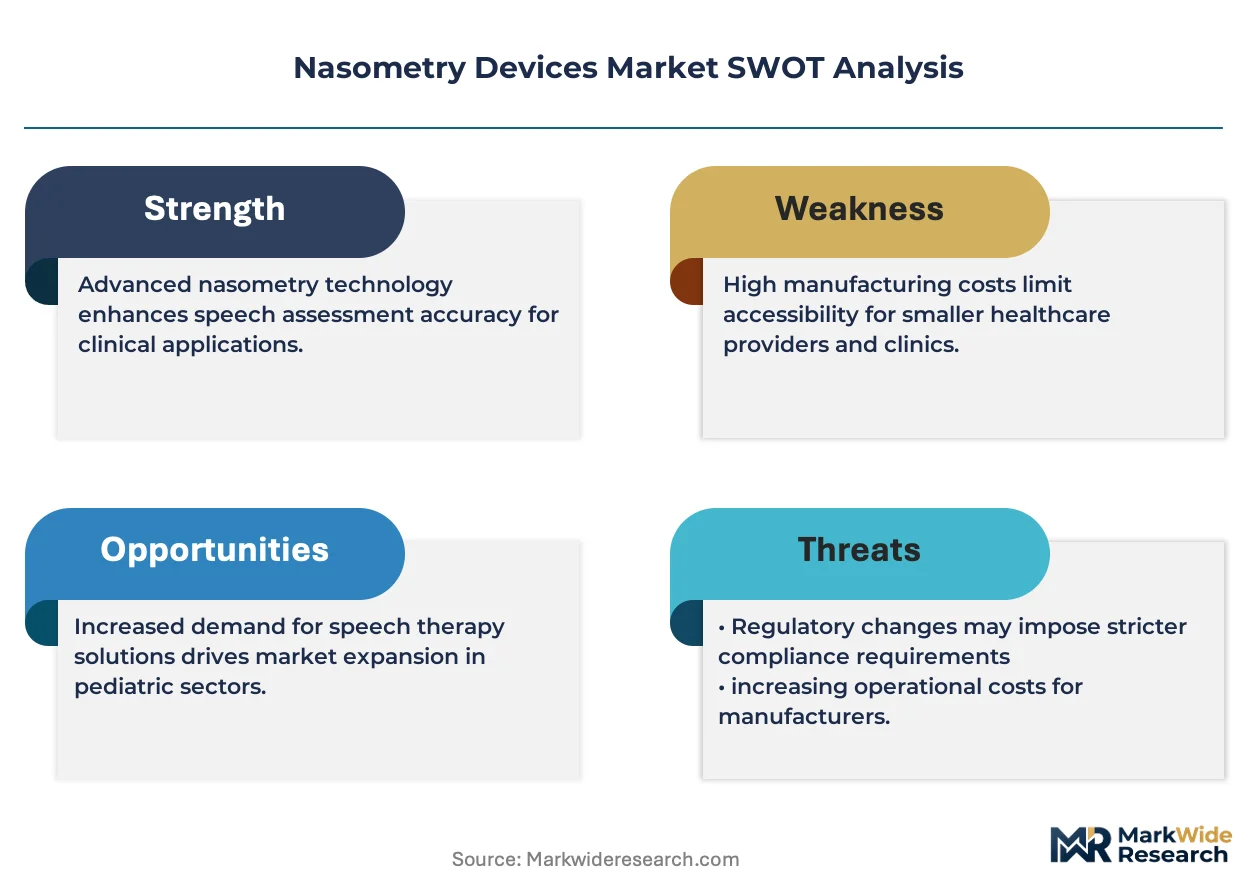
Portable nasometry systems are virtualizing diagnostic workflows, shifting value capture from capital equipment toward software-enabled service layers that clinic networks deploy across distributed speech therapy sites.
Growth Catalysts
- EU MDR streamlining:CE marking pathways for acoustic diagnostic devices under the Medical Device Regulation are compressing time-to-market for manufacturers targeting Germany's ENT specialist network.
- Telehealth speech therapy:Remote rehabilitation protocols are expanding addressable patient populations beyond traditional hospital catchment areas into home-based care settings.
- Biometric feedback integration:Real-time velopharyngeal closure visualization is embedding nasometry into biofeedback-driven therapeutic interventions for cleft palate and post-surgical speech rehabilitation.
Market Restraints
- Pressure transducer supply concentration:Precision acoustic sensors for nasometry devices rely on a limited supplier base concentrated in East Asian manufacturing clusters, creating input vulnerability.
- Reimbursement coding gaps:Medicare and national health systems lack dedicated CPT codes for nasometry diagnostics, forcing procurement through bundled speech pathology service fees that compress device budgets.
- Acoustic environmental sensitivity:Ambient noise interference in non-clinical settings limits portable device reliability, constraining deployment outside sound-controlled environments.
Strategic Opportunities
- Subscription analytics platforms:Cloud-based signal processing and longitudinal outcome tracking are creating recurring revenue streams that offset hardware margin compression.
- University medical center partnerships:Research collaborations for normative database development are establishing proprietary clinical validation barriers for emerging competitors.
- Pediatric screening mandates:Early childhood speech disorder detection programs in Scandinavian public health systems are generating institutional procurement pull for standardized nasometry protocols.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for contract manufacturing relationships extends product development cycles by 12-18 months.
- Signal processing talent scarcity:Specialized expertise in real-time acoustic analysis and velopharyngeal biomechanics is concentrated within academic speech science departments, limiting workforce scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasometry Devices Market |
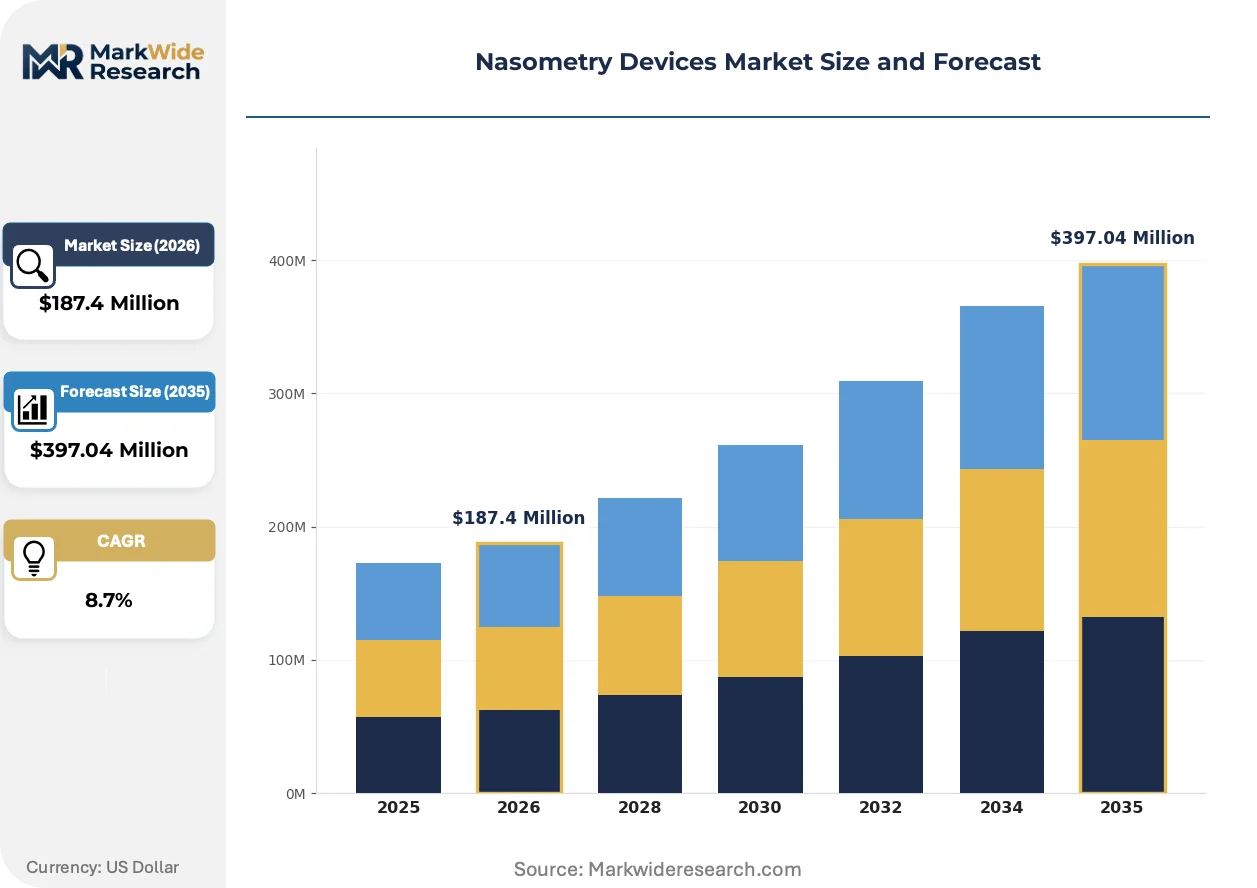
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Stationary Devices, Software Solutions, Accessories End User: Hospitals, Clinics, Research Institutions, Diagnostic Laboratories Application: Speech Therapy, Voice Quality Assessment, Research Studies, Education Technology: Acoustic Analysis, Signal Processing, Digital Monitoring, Biometric Feedback |
| Companies Covered | GM Instruments Ltd., Rose Medical Solutions Ltd., PENTAX Medical, Medtronic plc, Interacoustics A/S, Natus Medical Incorporated, Welch Allyn, Atmos MedizinTechnik GmbH & Co. KG, Auditdata A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasometry Devices Market Shifts & Advancements
Software-defined diagnostics are displacing hardware-centric business models across the nasometry landscape, with signal processing algorithms now delivering the core value proposition rather than physical measurement apparatus.
Machine learning-based hypernasality scoring is virtualizing the interpretation layer that previously required specialized speech-language pathologist expertise. Community health centers and school-based therapy programs are adopting these automated assessment tools to extend diagnostic access without proportional specialist hiring. The technology is compressing the value chain toward algorithm developers and away from traditional device manufacturers.
FDA 510(k) premarket notification pathways for acoustic diagnostic devices are evolving toward software-as-medical-device frameworks that recognize algorithm updates as distinct from hardware modifications. This regulatory recalibration is accelerating product iteration cycles for manufacturers with established quality management systems. Portable nasometry systems targeting US speech therapy clinics are restructuring submission strategies around predetermined change control plans.
Aftermarket service unbundling is fragmenting the traditional capital sale model into discrete calibration, software upgrade, and remote monitoring subscriptions. Hospital procurement departments are resisting bundled pricing while clinic networks prioritize operational expenditure flexibility. This shift is most visible in North American outpatient speech therapy chains negotiating per-patient diagnostic fees rather than device ownership transfers.
Nasometry Devices Market Segmentation
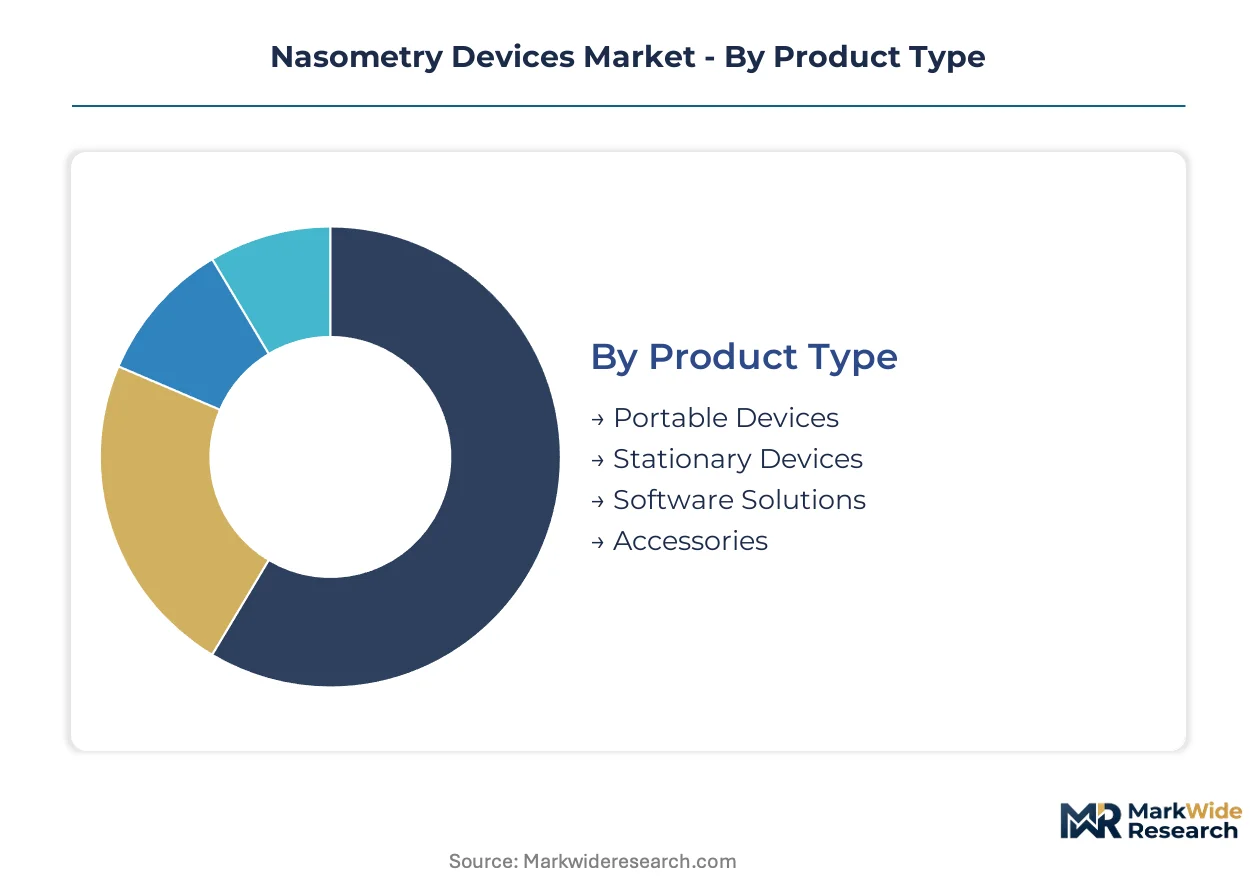
Nasometry device segmentation reveals divergent procurement cycles across product categories, with portable hardware refreshing every 3-4 years while software subscriptions renew annually. Understanding these velocity differences helps manufacturers align inventory planning against recurring revenue streams.
Product Type:
Portable devices turn inventory fastest through clinic network expansion, while stationary systems anchor long-cycle hospital capital budgets. Software solutions operate on monthly or annual renewal rhythms distinct from hardware depreciation schedules.
- Portable Devices:Battery-powered units with integrated pressure transducers and sound separation plates sample velopharyngeal dynamics at rates exceeding 10 kHz. Demand concentrates in North American outpatient speech therapy chains deploying distributed diagnostic networks, driven by FDA 510(k) pathway streamlining for acoustic diagnostic devices.
- Software Solutions:Cloud-based signal processing platforms deliver automated hypernasality scoring and longitudinal outcome tracking through subscription licensing. Procurement is accelerating among community health centers and school-based therapy programs in Germany's ENT specialist network, constrained by ISO 13485 certification requirements for algorithm-as-medical-device frameworks.
- Stationary Devices:Tethered laboratory-grade systems with enhanced acoustic isolation target university medical centers and tertiary hospital speech pathology departments.
- Accessories:Replacement transducers, calibration kits, and disposable sound separation plates sustain installed base utilization.
Portable devices anchor the volume base while software solutions gain share at the steepest rate.
End User:
Customer procurement authority varies sharply across this dimension, with hospital purchasing departments negotiating enterprise contracts while research institutions operate through principal investigator discretionary budgets.
- Hospitals:Tertiary medical centers integrate nasometry with surgical navigation platforms and cleft palate repair workflows, requiring deep EMR connectivity. Procurement concentrates in US academic medical centers and Germany's university hospital networks, shaped by bundled reimbursement for speech pathology diagnostics.
- Clinics:Outpatient speech therapy practices prioritize operational expenditure flexibility over capital ownership, favoring per-patient diagnostic fees. Scandinavian pediatric screening mandates are institutionalizing standardized nasometry protocols across municipal clinic chains.
- Research Institutions:Speech science departments and biomedical engineering labs source devices for normative database development and velopharyngeal biomechanics investigation.
- Diagnostic Laboratories:Specialized testing facilities process referred cases for hypernasality quantification and pre-surgical assessment.
Hospitals dominate absolute procurement value while clinics expand addressable unit volume most aggressively.
Application:
Clinical utility intensity varies across use cases, with therapeutic intervention demanding continuous monitoring capabilities while research applications prioritize raw data export flexibility.
- Speech Therapy:Biofeedback-driven rehabilitation protocols for cleft palate and post-surgical speech recovery require real-time velopharyngeal closure visualization. Telehealth expansion is extending these applications into home-based care settings beyond traditional hospital catchment areas.
- Voice Quality Assessment:Pre- and post-intervention documentation for phonosurgery and vocal fold procedures demands standardized acoustic metrics. Adoption is concentrating in otolaryngology practices affiliated with US head and neck surgery centers.
- Research Studies:Longitudinal outcome tracking and treatment efficacy comparison across patient cohorts requires interoperable data formats.
- Education:Training programs for speech-language pathology students utilize nasometry for hands-on velopharyngeal function demonstration.
Speech therapy anchors current utilization while voice quality assessment applications climb the fastest.
Technology:
Technical sophistication tiers separate established measurement approaches from emerging algorithmic capabilities, with development resource allocation shifting toward machine learning interpretation layers.
- Biometric Feedback:Real-time visualization of nasal airflow and acoustic energy patterns enables patient-directed therapeutic adjustment. Integration into pediatric rehabilitation protocols is accelerating fastest among Scandinavian public health systems and North American cleft palate centers.
- Signal Processing:Real-time acoustic analysis algorithms separate oral and nasal sound components through computational separation techniques. Talent scarcity in velopharyngeal biomechanics expertise is constraining workforce scaling for this capability layer.
- Acoustic Analysis:Fundamental frequency and formant measurement provides baseline hypernasality quantification.
- Digital Monitoring:Continuous data capture and cloud synchronization enable remote clinician oversight of patient progress.
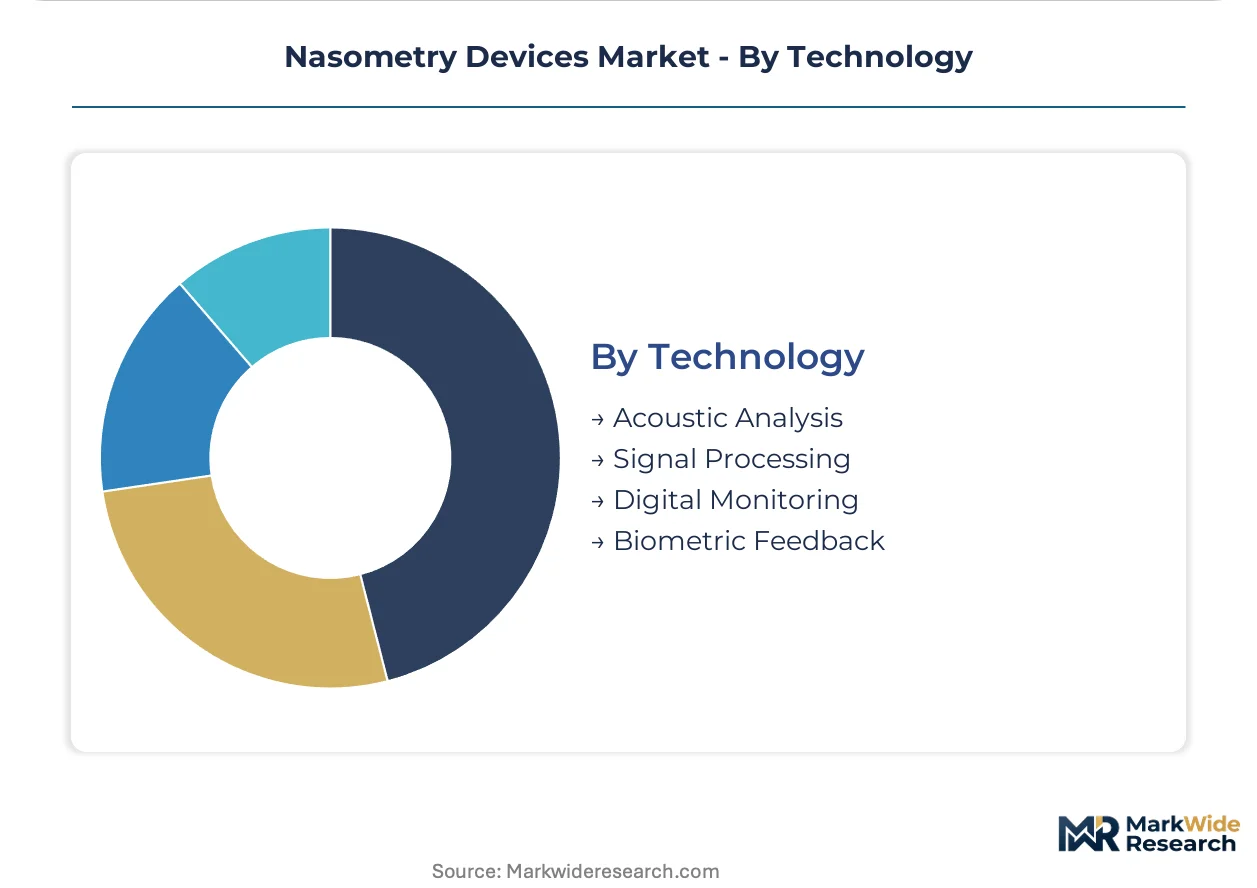
Signal processing underpins current device functionality while biometric feedback integration expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Outpatient speech therapy chains in the United States resist capital ownership, while Germany's ENT specialist network accepts premium pricing for integrated diagnostic workflows. Scandinavian public health systems drive volume through pediatric screening mandates.
United States
FDA 510(k) clearance pathways compress time-to-market for acoustic diagnostic devices. Medicare reimbursement gaps force procurement through bundled speech pathology service fees. Boston and Philadelphia academic medical centers anchor tertiary hospital adoption of stationary nasometry systems integrated with surgical navigation platforms.
Germany
University medical centers in the ENT specialist network prioritize protocol standardization over price competition. EU MDR intensifies post-market surveillance obligations for CE-marked devices. Munich and Heidelberg clusters concentrate demand for software-defined diagnostics with EMR connectivity requirements.
Sweden
Early childhood speech disorder detection programs generate institutional procurement pull for standardized nasometry protocols. The Swedish Medical Products Agency enforces rigorous clinical validation standards for diagnostic algorithms. Stockholm and Gothenburg municipal clinic chains deploy portable systems across distributed therapy sites.
Japan
PMDA regulatory frameworks govern medical device market access with structured premarket consultation processes. Aging demographics expand demand for post-stroke speech rehabilitation services. Tokyo and Osaka metropolitan areas concentrate cleft palate center capacity and biofeedback-driven therapeutic adoption.
United Kingdom
NHS procurement frameworks favor operational expenditure models over capital equipment purchases. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines. London and Manchester speech therapy networks pilot subscription-based analytics platforms for longitudinal outcome tracking.
Nasometry Devices Market Competitive Landscape
Capability concentration sits with specialized acoustic diagnostic developers; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: endoscopy channel incumbents bundling nasometry with visualization workflows, audiologist-centric specialists competing on protocol standardization, and hearing diagnostic platform players leveraging installed base relationships. Dominant competitive moves include strategic partnerships with university medical centers for normative database development and portfolio diversification into software-as-medical-device frameworks.
Within the diversified medical technology tier, Medtronic plc and PENTAX Medical exemplify scale-driven positioning through hospital system integration. Among specialized acoustic diagnostic developers, Interacoustics A/S occupies the audiologist-centric archetype with protocol-focused differentiation. Rose Medical Solutions Ltd. represents the independent specialist model concentrated on speech-language pathology workflows.
| Leading Market Players |
|---|
| GM Instruments Ltd. |
| Rose Medical Solutions Ltd. |
| PENTAX Medical |
| Medtronic plc |
| Interacoustics A/S |
| Natus Medical Incorporated |
| Welch Allyn |
| Atmos MedizinTechnik GmbH & Co. KG |
| Auditdata A/S |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian pressure transducer manufacturers exposes nasometry device producers to tariff volatility and input cost spikes, compressing margin structures across premium laboratory systems and forcing clinic-tier suppliers toward modular hardware architectures with shorter replacement cycles.
Pricing Analysis
Long-term service contracts dominate procurement relationships, with hospital systems negotiating multi-year calibration and software upgrade bundles while outpatient clinics favor per-patient diagnostic fees. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and EMR integration depth. Cost compression in the portable device tier is intensifying because subscription analytics platforms displace capital ownership models. Community health centers exhibit highest price sensitivity; university medical centers anchored to surgical navigation workflows accept premium positioning.
Supply Chain Analysis
Extended payment terms from Japanese and German hospital procurement departments strain component suppliers concentrated in Taiwan, South Korea, and coastal China manufacturing zones. Precision acoustic sensors, sound separation plates, and pressure transducers draw from limited qualified vendor pools. Single-source vulnerability in 10 kHz sampling rate transducers threatens production continuity. Distribution runs through audiology equipment distributors and endoscopy channel partners serving ENT specialist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-as-medical-device regulatory frameworks are reconfiguring nasometry from hardware-centric to platform-centric economics, with FDA 510(k) predetermined change control plans and EU MDR algorithm validation requirements creating interoperability standards that favor ecosystem orchestrators over point-product vendors.
For Market Incumbents: Pre-empt displacement by machine learning-based hypernasality scoring through acquisition of signal processing talent clusters in academic speech science departments. Deepen backward integration into pressure transducer supply through exclusive partnerships with Taiwanese MEMS foundries. Lock hospital system loyalty via EMR-integrated workflow bundles that raise switching costs for competing surgical navigation platforms. For New Entrants and Emerging Players: Scandinavian pediatric screening mandates and German community health center digitization programs represent the most penetrable entry points for cloud-native nasometry platforms without legacy hardware baggage. Target school-based therapy programs in North American district procurement frameworks with automated assessment tools that bypass specialist hiring constraints. Pursue university medical center research collaborations for proprietary normative database development as clinical validation barriers. For Investors and Strategic Acquirers: EU MDR intensification and FDA software-as-medical-device pathway maturation reshape the acquisition landscape toward algorithm-heavy, asset-light targets with established quality management systems. Five-to-ten year viability favors developers of biometric feedback integration layers over pure hardware manufacturers. Monitor Medicare CPT code recognition for standalone nasometry diagnostics as the critical reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Certification | FDA 510(k) predetermined change control plans accelerate algorithm update cycles without fresh submissions. |
| University Medical Center Partnership | Proprietary normative databases create clinical validation moats against emerging competitors. |
| Subscription Analytics Platform Launch | Cloud-based signal processing captures recurring revenue streams offsetting hardware margin erosion. |
| Pressure Transducer Supply Agreement | Exclusive Taiwanese MEMS foundry partnerships secure input continuity against East Asian concentration risk. |
| Pediatric Screening Protocol Standardization | Scandinavian public health system mandates institutionalize recurring procurement for early childhood programs. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR CE marking registries, and hospital procurement contract disclosures preceded structured interviews with speech-language pathologists, ENT specialists, biomedical engineers, and GPO contracts managers. Secondary validation drew from ISO 13485 certification records, Medicare reimbursement coding manuals, and academic speech science publication corpora. Bottom-up unit shipment estimates triangulated against top-down addressable clinic budget assessments.
Assumptions held fixed include regulatory pathway timelines for acoustic diagnostic devices and reimbursement code stability across national health systems; variables tested included telehealth adoption velocity and machine learning algorithm validation burden. Segmentation modeling spanned product type, end user procurement authority, clinical application intensity, and signal processing technology tier. CAGRs derived from logistic diffusion curves fitted to portable device penetration rates and software subscription renewal patterns. Forecast inputs incorporated pressure transducer supply lead times and university medical center research funding cycles.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or East Asian trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding FDA and EU MDR pathway efficiency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Pathological Examination Market