
 Absorbable Surgical Suture with Needle Market | 2026-2036
Absorbable Surgical Suture with Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Surgical Suture with Needle Market Insights
Chinese polymer manufacturers is pivoting toward medical-grade polyglycolic acid output to serve branded device makers. Johnson & Johnson leverages its Ethicon franchise to sustain dominance in synthetic absorbable platforms across North American and European hospital systems. Medtronic anchors its suture portfolio through deep integration with surgical stapling and energy device bundles. B. Braun competes on manufacturing scale, operating multiple European production sites that supply sterile needle-suture combinations to public procurement networks.
An absorbable surgical suture with needle consists of a bio-resorbable filament—commonly composed of polyglycolic acid, polydioxanone, or polyglecaprone—swaged to a stainless steel or alloy needle, designed to maintain tensile strength for 14 to 28 days before hydrolytic degradation eliminates the need for removal. The device serves to approximate tissue during internal wound closure across general, orthopedic, and cardiovascular procedures where permanent foreign material would compromise healing or require secondary intervention. Polyglycolic acid configurations occupy the largest volume share due to predictable absorption profiles and broad surgeon familiarity, while polydioxanone variants command premium positioning in cardiovascular and orthopedic applications requiring extended wound support. General surgery generates the heaviest hospital consumption, though ambulatory surgical centers represent the fastest-growing end-user channel as same-day procedure volumes shift away from inpatient settings.
FDA 510(k) clearance pathways and EU MDR conformity assessment govern device biocompatibility, needle sharpness retention, and package sterility integrity, directly shaping product development timelines and market access costs for manufacturers. Health Canada's medical device licensing and Japan's PMDA pharmaceutical and medical device agency impose additional jurisdiction-specific testing protocols that fragment regulatory strategy. Stakeholders must monitor evolving polymer innovation cycles and reimbursement compression in outpatient settings to align R&D investment with the clinical and economic criteria that now drive hospital procurement committees.
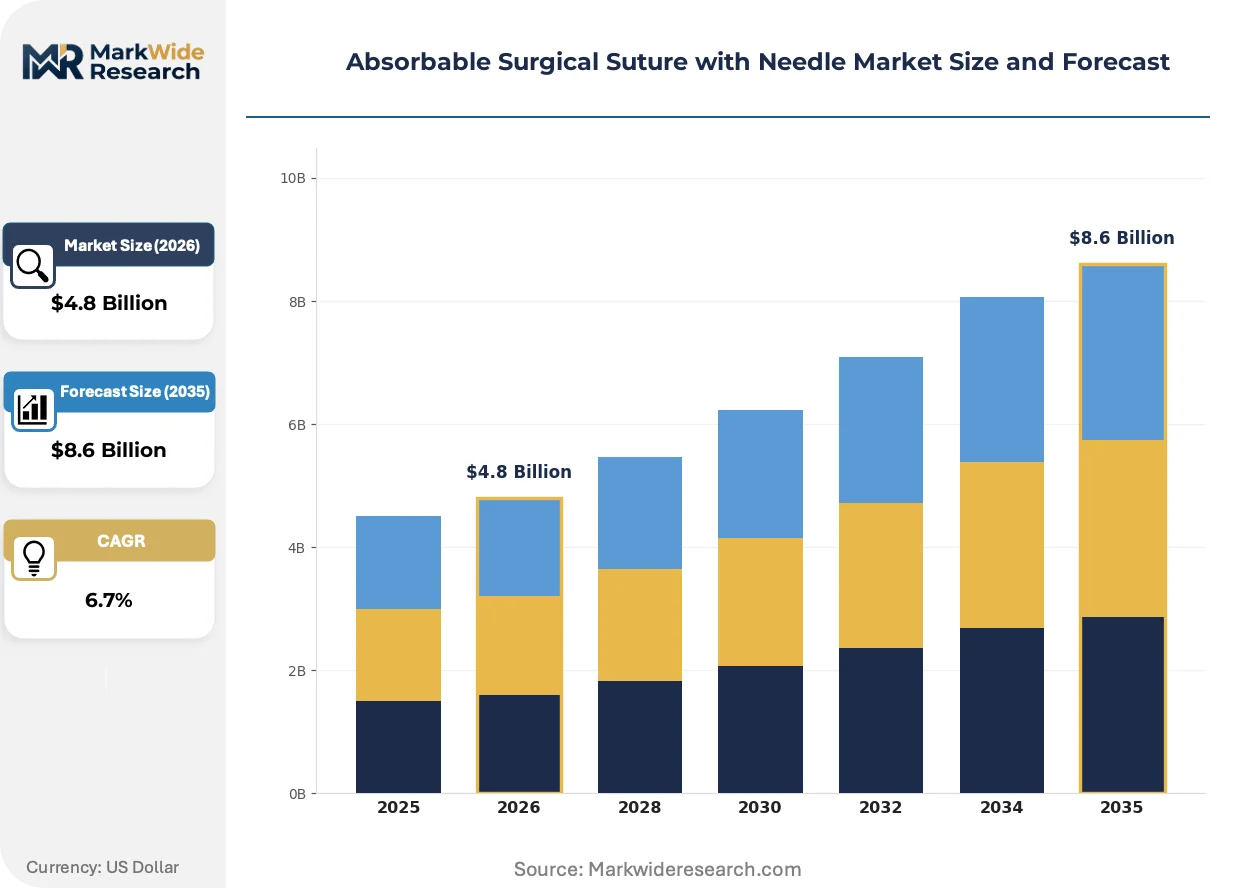
Market Dynamics
EU MDR sterility mandates and FDA Class II biocompatibility requirements are compressing product development timelines while elevating capital barriers for needle-suture combination manufacturers.
Growth Catalysts
- Outpatient surgical migration:Ambulatory surgical centers in Germany are expanding procedure volumes for same-day interventions that rely on absorbable closure materials.
- EU MDR implementation:Stricter conformity assessment for sterile needle-attached configurations is consolidating procurement toward qualified suppliers with established technical documentation.
- Polyglycolic acid standardization:Predictable hydrolytic degradation profiles are driving surgeon preference across general surgery departments in hospital systems.
Market Restraints
- Medical-grade polymer feedstock concentration:Polydioxanone precursor supply concentrates among specialty chemical producers in Germany and Switzerland.
- Extended FDA 510(k) review cycles:Needle sharpness retention testing protocols now average fourteen additional months for novel alloy configurations.
- Monofilament substitution pressure:Barbed suture designs for laparoscopic closure are capturing select cardiovascular applications previously served by braided absorbables.
Strategic Opportunities
- Japanese cardiovascular expansion:PMDA pharmaceutical and medical device agency pathways for extended tensile strength variants remain underpenetrated by Western manufacturers.
- Antimicrobial coating convergence:Integration of triclosan or chlorhexidine elution layers with synthetic polymer cores addresses surgical site infection protocols in orthopedic settings.
- Direct-to-ambulatory distribution:Bypassing hospital procurement committees through specialized distributors serving freestanding surgical centers in Texas and Florida.
Industry Challenges
- Polymer synthesis expertise scarcity:Medical-grade polyglycolic acid production requires chemists with GMP sterile manufacturing experience that competes with pharmaceutical sector hiring.
- EU MDR technical documentation burden:Clinical evaluation reports for legacy needle-suture combinations demand retrospective data aggregation that strains regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Surgical Suture with Needle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyglycolic Acid, Polylactic Acid, Catgut, Polydioxanone, Polyglecaprone Application: General Surgery, Gynecological Surgery, Orthopedic Surgery, Cardiovascular Surgery, Neurosurgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Medical Institutes Packaging Type: Sterile Blister Packs, Pouches, Tubes, Boxes |
| Companies Covered | Johnson & Johnson, Medtronic, B. Braun, Peters Surgical, Teleflex, Smith & Nephew, Advanced Medical Solutions Group, Healthium Medtech, DemeTECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Surgical Suture with Needle Market Trends and Innovations
Material science advances and regulatory harmonization pressures are reconfiguring how manufacturers differentiate absorbable suture platforms across hospital and ambulatory channels.
Polyglecaprone monofilament configurations is overtaking braided polyglycolic acid in subcuticular closure applications where reduced tissue drag accelerates operative efficiency. Plastic surgery departments in academic medical centers are adopting these variants for cosmetic procedures requiring minimal scarring. The shift is compressing demand for traditional multifilament constructions in superficial tissue layers.
EU MDR Annex I general safety and performance requirements now mandate real-time aging studies for sterile barrier systems that extend submission timelines by eight to twelve months. Manufacturers with legacy CE certificates under the Medical Devices Directive face compressed transition windows through 2027. Cardiovascular suture lines requiring extended absorption profiles encounter the most acute documentation gaps.
Hospital value analysis committees now require total procedural cost evidence rather than unit price comparisons when standardizing suture formularies. This behavioral pivot elevates vendors with clinical outcome data and bundling flexibility. The pattern is most pronounced in United States integrated delivery networks consolidating orthopedic and general surgery spend categories.
Absorbable Surgical Suture with Needle Market Segmentation
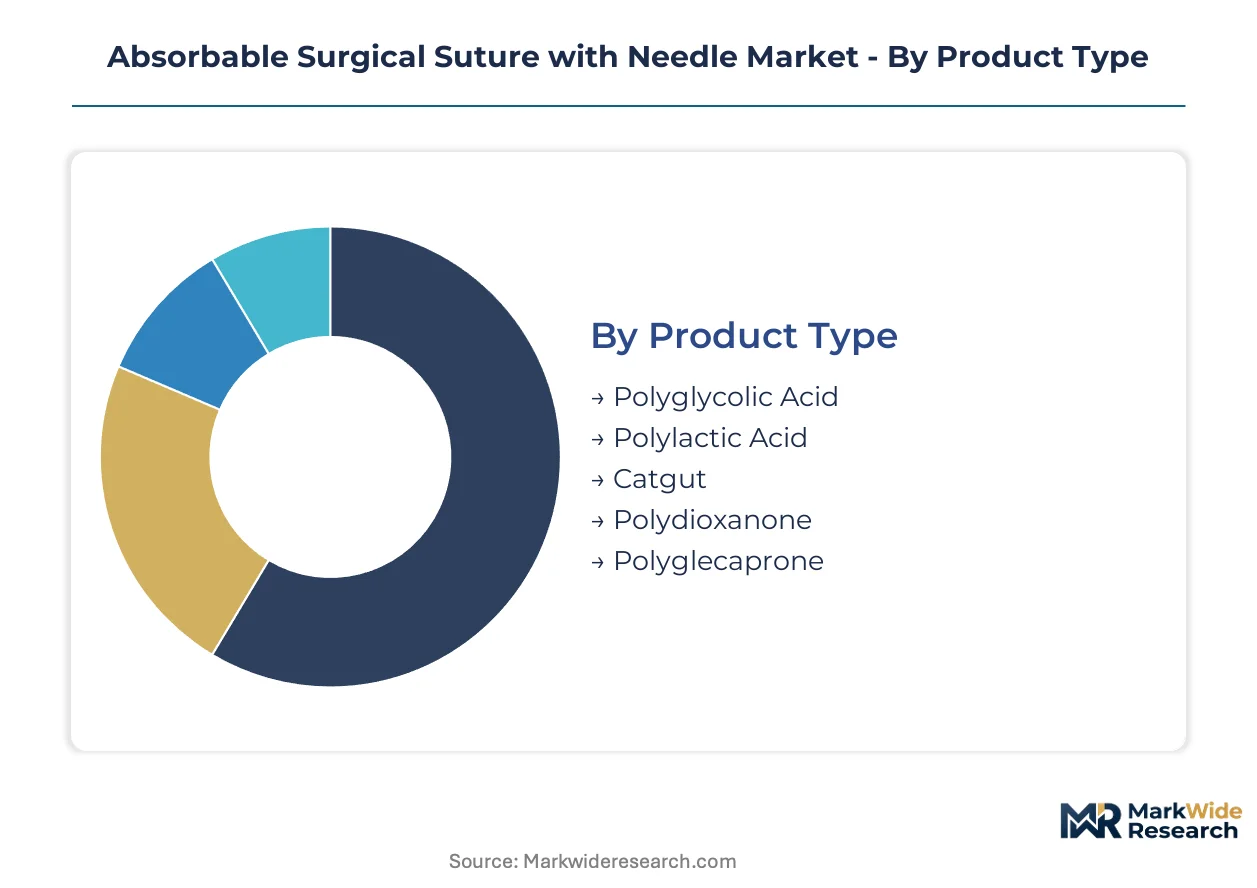
Segmentation in absorbable surgical sutures with needle reveals how polymer chemistry, procedure complexity, and care setting economics fragment procurement priorities. Manufacturers must align formulation portfolios with the divergent performance timelines and sterility requirements that separate hospital operating theaters from ambulatory suites.
Product Type:
Surgeon preference for predictable hydrolysis rates and tensile strength retention governs polymer selection across procedure categories.
- Polyglycolic Acid:Braided multifilament construction delivers tensile strength for 14 to 21 days with complete absorption by 60 to 90 days. General surgery departments in United States hospital systems standardize on this platform for routine wound closure.
- Polydioxanone:Monofilament architecture maintains wound support for 28 to 42 days, serving cardiovascular and orthopedic applications where extended healing is required. German surgical centers pay premium pricing for these variants in valve replacement and tendon repair.
- Polylactic Acid:Synthetic polymer with slower absorption kinetics suits maxillofacial and plastic surgery applications.
- Catgut:Collagen-based natural material retains niche use in emerging markets with price-sensitive procurement.
- Polyglecaprone:Rapid absorption profile with minimal tissue reaction supports subcuticular closure in cosmetic procedures.
Volume sits with Polyglycolic Acid; growth tilts toward Polydioxanone as cardiovascular procedure volumes climb.
Application:
Procedure reimbursement tiers and operative complexity dictate suture performance specifications and volume concentration.
- General Surgery:Appendectomy, hernia repair, and cholecystectomy generate the highest unit consumption across health systems. Ambulatory migration in Texas and Florida is shifting volume toward same-day discharge protocols.
- Cardiovascular Surgery:Sternotomy closure and vascular anastomosis demand extended tensile strength variants with documented biocompatibility. Japanese cardiovascular centers underutilize Western absorbable platforms relative to procedure volume.
- Orthopedic Surgery:Soft tissue reattachment and ligament repair require high-strength braided configurations.
- Gynecological Surgery:Hysterectomy and cesarean section closure drive seasonal demand patterns.
- Neurosurgery:Dural closure and cranial procedures command ultra-fine gauge specifications with minimal inflammatory response.
General Surgery captures the largest share; Cardiovascular Surgery is expanding most quickly as aging demographics drive intervention rates.
End User:
Procurement authority and inventory management sophistication separate institutional buyers across the care continuum.
- Hospitals:Integrated delivery networks consolidate suture purchasing through value analysis committees that demand outcome data and bundling flexibility. United States health systems increasingly standardize formularies across affiliated facilities.
- Ambulatory Surgical Centers:Freestanding facilities in Germany and the United States prioritize rapid-turn inventory with direct distributor relationships bypassing hospital procurement layers.
- Specialty Clinics:Dermatology and ophthalmology practices require procedure-specific configurations in smaller lot sizes.
- Medical Institutes:Academic centers drive early adoption of novel polymer platforms through investigator-initiated trials.
Hospitals retain volume dominance; Ambulatory Surgical Centers are gaining share fastest as same-day procedure authorization expands.
Packaging Type:
Sterility assurance and shelf-life requirements shape barrier system selection and regulatory documentation burden.
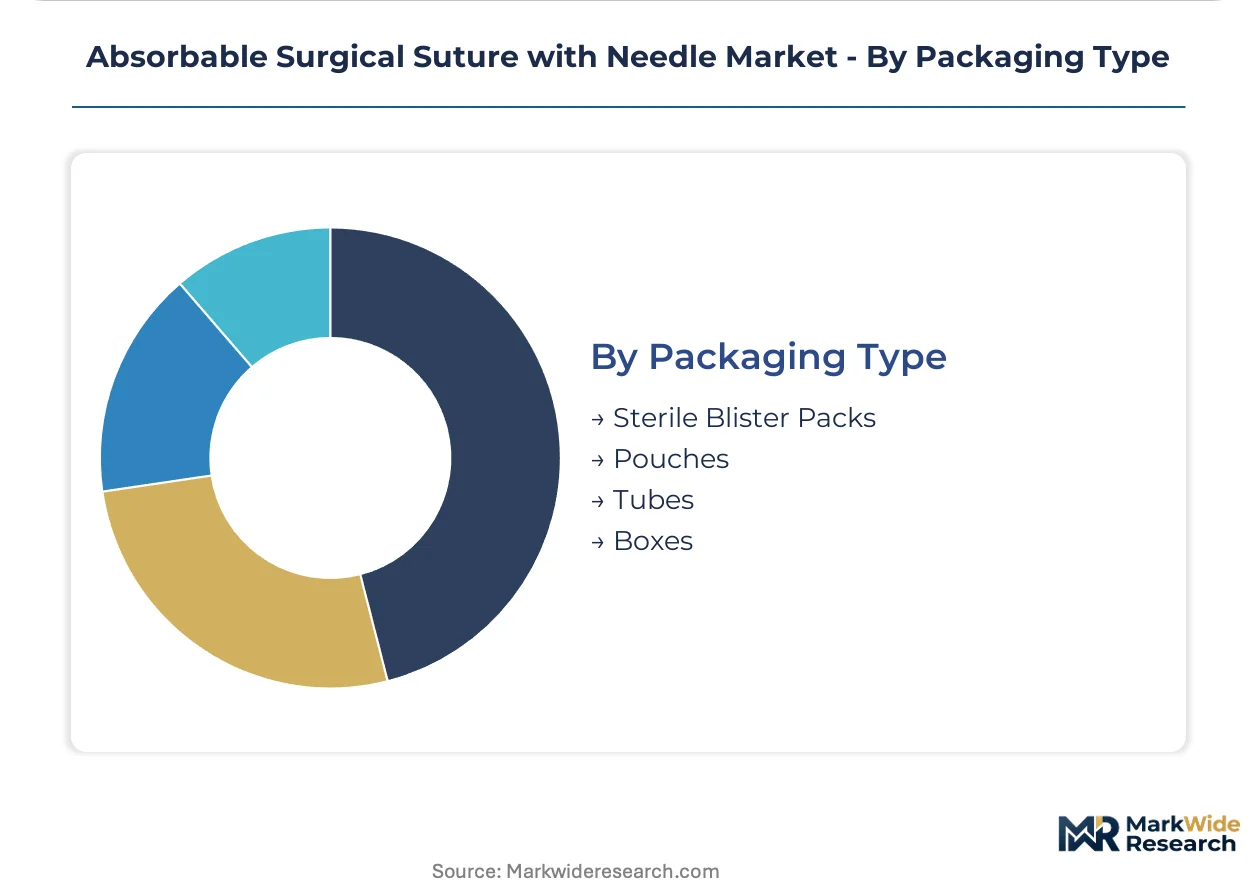
- Sterile Blister Packs:Tyvek-film combinations dominate hospital procurement for needle-suture combinations requiring immediate visual verification. EU MDR real-time aging studies now extend submission timelines for these configurations.
- Pouches:Flexible sterilization barriers serve ambulatory centers with space-constrained storage.
- Tubes:Rigid packaging protects multifilament braids from compression damage during distribution.
- Boxes:Bulk configurations support high-volume orthopedic and general surgery suites with automated dispensing systems.
Sterile Blister Packs command the highest volume; Pouches are climbing the fastest as ambulatory center construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer synthesis expertise concentrates in German and Swiss chemical corridors, while finished device manufacturing clusters span North American hospital supply chains and East Asian export hubs.
United States
FDA 510(k) clearance pathways govern needle-suture combination approvals, with review cycles extending for novel alloy configurations. Hospital value analysis committees in Texas and Florida consolidate procurement across integrated delivery networks, prioritizing outcome data over unit pricing. Ambulatory surgical center construction in these states accelerates direct-to-facility distribution bypassing traditional hospital supply chains.
Germany
Outpatient surgical volumes and ambulatory center investments continue rising in Baden-Württemberg and Bavaria. EU MDR sterility mandates and conformity assessment requirements compress transition windows for legacy device certificates through 2027. Specialty chemical producers in the Rhine-Neckar metropolitan region concentrate polydioxanone precursor supply serving branded device makers.
China
Domestic polymer manufacturers pivot toward medical-grade polyglycolic acid output to serve branded device makers. NMPA medical device registration pathways impose jurisdiction-specific biocompatibility testing that fragments market access timelines. Yangtze River Delta production clusters scale sterile needle-suture combinations for export markets and domestic hospital procurement.
Japan
PMDA pharmaceutical and medical device agency pathways for extended tensile strength variants remain underpenetrated by Western manufacturers. Cardiovascular procedure volumes in Tokyo and Osaka metropolitan areas drive demand for premium absorbable platforms. Kanto region academic medical centers pioneer early adoption of novel polymer configurations through investigator-initiated trials.
Switzerland
Swissmedic medical device regulations align with EU MDR technical documentation requirements for sterile barrier systems. Basel-area chemical producers supply high-purity polymer precursors to European and North American device manufacturers. Precision manufacturing clusters in the Swiss Mittelland region specialize in needle alloy processing for premium surgical applications.
Absorbable Surgical Suture with Needle Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue antimicrobial coating convergence and direct-to-ambulatory distribution channels. The market structure consolidates around diversified medical device conglomerates with deep hospital system relationships, while mid-scale specialists compete on manufacturing scale and regional regulatory expertise. Three archetypes dominate: polymer-integrated manufacturers with captive feedstock supply, surgical platform bundlers leveraging stapling and energy device portfolios, and sterile combination specialists serving public procurement networks. Competitive moves center on EU MDR technical documentation completion and ambulatory center distributor acquisitions.
Within the diversified conglomerate tier, Johnson & Johnson and Medtronic exemplify platform bundling strategies that integrate suture portfolios with broader surgical device ecosystems. B. Braun occupies a position among European-scale sterile combination specialists with distributed manufacturing footprints. These three anchors represent divergent responses to procurement consolidation: one leverages franchise brand equity across North American hospital systems, another anchors portfolio breadth through surgical stapling integration, and the third competes on manufacturing scale serving public procurement networks.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| B. Braun |
| Peters Surgical |
| Teleflex |
| Smith & Nephew |
| Advanced Medical Solutions Group |
| Healthium Medtech |
| DemeTECH |
| Others |
Pricing and Supply Chain Analysis
EU MDR sterility mandates and FDA Class II biocompatibility requirements gate qualified supply access for needle-suture combinations, allowing only manufacturers with validated technical documentation to command premium-tier pricing in hospital procurement networks. This regulatory filtration concentrates pricing power among established producers while compressing margins for entrants lacking legacy CE certificates or completed 510(k) dossiers.
Pricing Analysis
Warranty and service bundling separates premium polydioxanone variants from unbundled standard polyglycolic acid configurations, with cardiovascular applications demanding extended tensile strength guarantees and dedicated clinical support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from integrated delivery networks. Cost compression in standard braided absorbables is intensifying because ambulatory surgical centers negotiate direct distributor contracts bypassing hospital procurement layers. Ambulatory centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize outcome data over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks and German hospital procurement coalitions mandate multi-supplier qualification for polyglycolic acid and polydioxanone precursors, preventing single-source dependency. Medical-grade polymer synthesis concentrates in Germany, Switzerland, and China, with specialty chemical producers in the Rhine-Neckar region and Basel area supplying high-purity feedstock. Raw material dependencies center on glycolide monomer, dioxanone precursor, and medical-grade stainless steel needle alloys. Single-source vulnerability persists for extended-absorption polymer formulations with limited qualified synthesis capacity. Distribution runs through specialized surgical device distributors serving hospital systems and direct-to-facility channels for ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR technical documentation burdens and extended FDA review cycles force weaker players lacking regulatory affairs infrastructure toward exit or acquisition.
For Market Incumbents: Extend polymer platform breadth through backward integration into medical-grade polyglycolic acid production, securing captive feedstock supply against specialty chemical producer concentration in Germany and Switzerland. Add sterile manufacturing capacity in Baden-Württemberg or Bavaria to serve expanding German ambulatory surgical center demand with localized distribution. Barbed suture substitution for laparoscopic closure threatens braided absorbable volumes in cardiovascular applications; counter through clinical outcome data investments targeting hospital value analysis committees. For New Entrants and Emerging Players: Launch via direct-to-ambulatory distribution partnerships in Texas and Florida, bypassing consolidated hospital procurement committees that favor incumbent bundling arrangements. Target Japanese cardiovascular centers with extended tensile strength variants, as PMDA pathways remain underpenetrated by Western manufacturers relative to procedure volume. White-space opportunities concentrate in antimicrobial-coated configurations for orthopedic surgical site infection protocols and polylactic acid platforms for maxillofacial applications. For Investors and Strategic Acquirers: EU MDR certificate transition deadlines approaching is the leading indicator that distressed asset availability will peak among mid-scale manufacturers lacking retrospective clinical data aggregation capabilities. Five-to-ten year viability favors polymer-integrated manufacturers with captive feedstock and established sterile barrier validation. Acquisition target archetype: European-scale sterile combination specialists with distributed manufacturing footprints and incomplete MDR technical documentation requiring capital injection. Watch for PMDA approval acceleration for extended tensile strength variants as inflection signal for Japanese market penetration viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Establishes market access continuity for sterile needle-suture combinations across German and Swiss procurement networks. |
| Antimicrobial Coating Integration | Addresses surgical site infection protocols in orthopedic settings with triclosan or chlorhexidine elution layers. |
| Ambulatory Center Distributor Acquisition | Captures same-day procedure volume migration in Texas and Florida through direct-to-facility channels. |
| Medical-Grade Polymer Backward Integration | Secures captive glycolide and dioxanone supply against Rhine-Neckar and Basel producer concentration. |
| Japanese PMDA Regulatory Pathway Investment | Unlocks cardiovascular center penetration in Tokyo and Osaka metropolitan areas for extended tensile strength variants. |
Research Methodology
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads underwrites the qualitative findings on suture formulary standardization and MDR transition pressures. Primary interviews with sterile manufacturing directors and polymer synthesis chemists combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data establish demand-side triangulation. Bottom-up segmentation modeling and top-down market sizing approaches cross-validate volume and value estimates.
Rate-of-change decomposition across polymer chemistry segments, procedure categories, and end-user channels structures the analytical framework over the projection horizon. Modeled dimensions include absorbable polymer type, surgical application complexity, procurement authority tier, and regional regulatory cluster. CAGRs derive from procedure volume elasticity to demographic shifts, reimbursement policy changes, and ambulatory migration patterns. Forecast inputs incorporate EU MDR transition timeline assumptions and PMDA pathway penetration rates for extended tensile strength variants.
The model assumes a particular technology adoption path; alternative pathways for barbed suture designs in laparoscopic closure would alter the outlook for traditional braided absorbables. Deviation in FDA 510(k) review cycle duration or EU MDR certificate transition enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Global Surgical Instrument Tracking System Market